
 Gift Card and Incentive Card Market | 2026-2036
Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
Gift Card and Incentive Card Market Foresight
Subscription-based loyalty program management is consolidating around platform providers that bundle issuance, redemption analytics, and fraud monitoring into recurring contracts. Amazon.com, Inc. leverages its Prime ecosystem to anchor digital gift card distribution within a captive marketplace. Apple Inc. sustains margin-rich positioning through Wallet-integrated branded cards with proprietary tokenization. InComm Payments competes via retail network density, controlling physical card activation infrastructure across grocery and convenience channels.
Gift cards and incentive cards are prepaid stored-value instruments, typically encoded with magnetic stripes, EMV chips, or tokenized digital credentials, designed to transfer purchasing power from an issuer to a recipient for specified merchant networks or open-loop acceptance. Their primary commercial purpose centers on customer acquisition, retention mechanics, and non-cash compensation workflows. Virtual cards within the Card Type dimension show the steepest trajectory as real-time issuance replaces physical inventory carrying costs. Corporate Incentives under Application captures deepening margin pools, since enterprise buyers prioritize configurable bulk-order platforms with API-driven fulfillment over consumer retail formats.
The Federal Reserve's Regulation E shapes liability frameworks for prepaid instruments in the United States, while the EU's PSD2 and GDPR jointly constrain data handling across digital wallet card architectures. Financial Institutions under End User face heightened compliance burden as anti-money laundering rules tighten on anonymous prepaid thresholds. Stakeholders must monitor whether central bank digital currency pilots in major economies absorb or complement existing private-label card infrastructure.
Market Dynamics
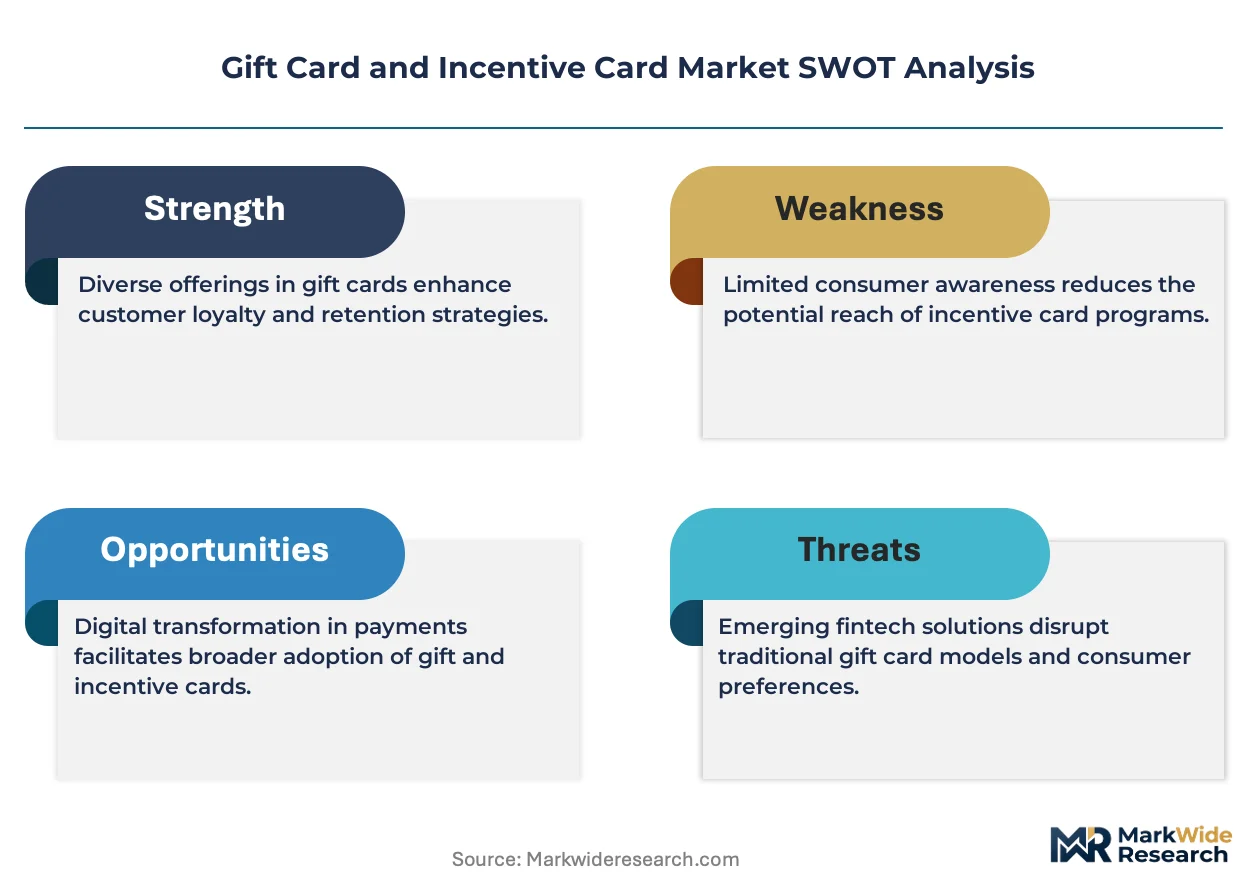
Real-time digital issuance infrastructure is compressing physical card manufacturing cycles while open-banking APIs enable direct wallet integration, fundamentally altering how purchasing power transfers from issuers to recipients across merchant networks.
Growth Catalysts
- EU PSD2 open-banking mandates:Regulatory frameworks in Europe compel financial institutions to expose payment initiation APIs, accelerating digital gift card wallet integration and reducing friction in redemption workflows.
- Corporate HR technology stacks:Enterprise human resource departments embed incentive cards directly into compensation management platforms, driving bulk-order automation and API-driven fulfillment at scale.
- Tokenization protocols:Proprietary digital credential systems replace magnetic stripe encoding, enabling instant issuance and eliminating physical inventory carrying costs across retail distribution networks.
Market Restraints
- Anonymous prepaid thresholds:Anti-money laundering regulations tighten compliance burdens on financial institutions, requiring enhanced due diligence for stored-value instruments below identification thresholds.
- Plastic substrate supply concentration:EMV chip manufacturing capacity clusters in East Asian foundries, creating input cost volatility and supply chain vulnerability for physical card production.
- Merchant network fragmentation:Closed-loop card acceptance remains limited to specific retail ecosystems, constraining recipient utility compared to open-loop alternatives.
Strategic Opportunities
- Central bank digital currency pilots:Sovereign digital currency experiments in major economies present complementary infrastructure partnerships or absorption risks for private-label card platforms.
- Subscription loyalty bundling:Platform providers integrate issuance, redemption analytics, and fraud monitoring into recurring contracts, capturing enterprise procurement budgets.
- API-driven fulfillment channels:Direct integration with enterprise resource planning systems displaces traditional retail card rack distribution for bulk corporate incentive orders.
Industry Challenges
- GDPR-compliant data architectures:Digital wallet card platforms face complex cross-border data handling constraints across European jurisdictions, requiring costly infrastructure reconfiguration.
- Legacy magnetic stripe system integration:Retail point-of-sale infrastructure upgrades lag behind EMV and tokenized credential standards, forcing dual-format support and technical debt accumulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gift Card and Incentive Card Market |
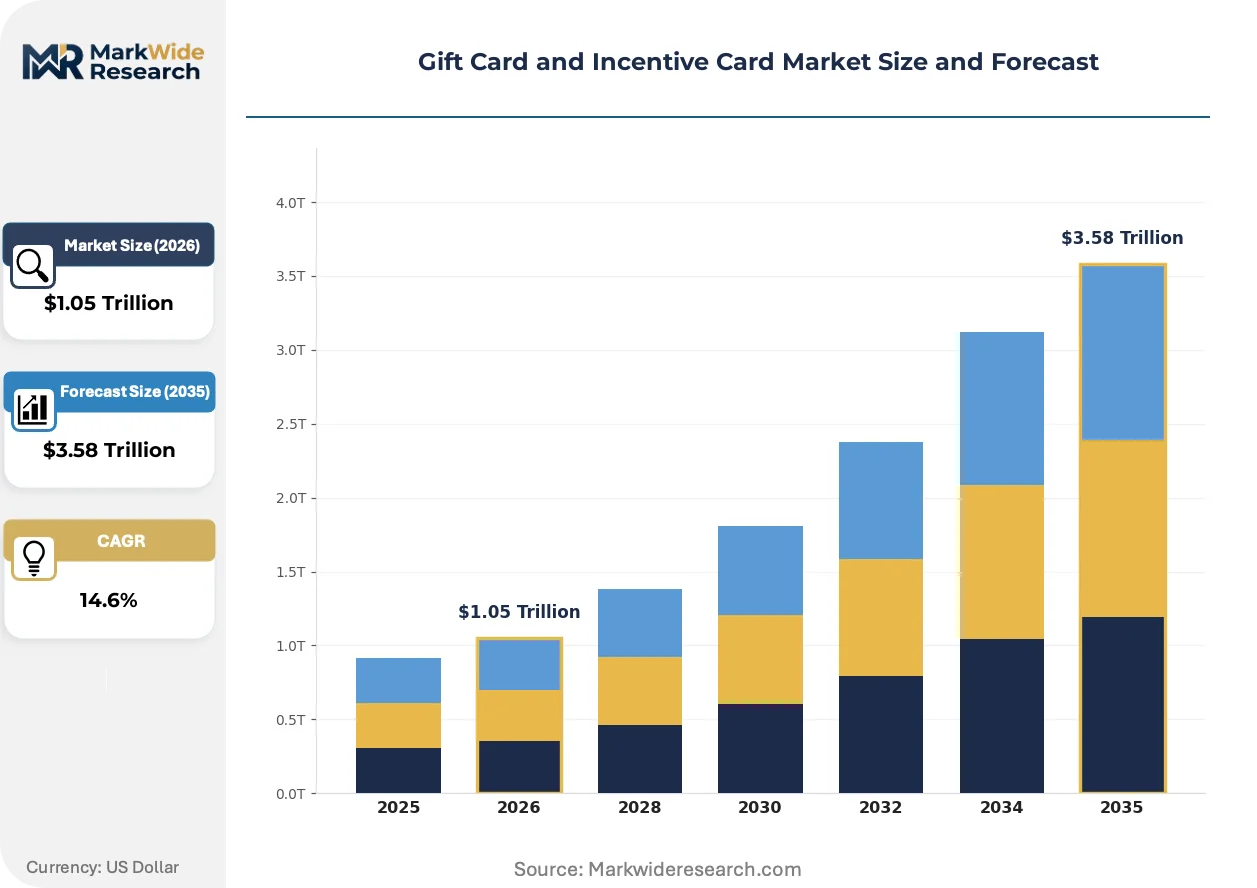
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $3.58 Trillion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Physical Cards, Virtual Cards, Hybrid Cards, Digital Wallet Cards Application: Employee Rewards, Customer Loyalty, Promotional Campaigns, Corporate Incentives, Event Giveaways End User: Retailers, Hospitality Chains, Financial Institutions, E-commerce Platforms, Travel Agencies Distribution Channel: Online Platforms, In-store Sales, Mobile Apps, Partner Networks, Direct Corporate Sales |
| Companies Covered | Blackhawk Network Holdings, Inc., InComm Payments, Amazon.com, Inc., Walmart Inc., Apple Inc., Visa Inc., Target Corporation, Starbucks Corporation, Edenred Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gift Card and Incentive Card Market Shifts & Advancements
Digital credential technologies are compressing issuance timelines from days to seconds while regulatory pressure on data handling intensifies across jurisdictions. These forces reshape competitive positioning around platform integration depth rather than physical distribution density.
Tokenized virtual card infrastructure is consolidating purchasing power transfer mechanisms around real-time API issuance. Enterprise procurement departments adopt these systems for employee incentives and customer rewards programs. This compression eliminates physical manufacturing, warehousing, and retail rack placement costs from value chain economics.
GDPR and PSD2 jointly constrain digital wallet architectures across European markets. Data localization requirements and payment initiation mandates force platform redesigns. Financial institutions respond by embedding compliance tooling directly into card management systems, treating regulatory adherence as product feature differentiation.
Enterprise buyers now prioritize configurable bulk-order platforms over consumer retail formats for incentive programs. Traditional card rack distribution faces displacement from direct ERP integration and automated fulfillment workflows. This shift concentrates most visibly in United States corporate technology stacks where HR platforms seek seamless compensation tooling.
Gift Card and Incentive Card Market Segmentation
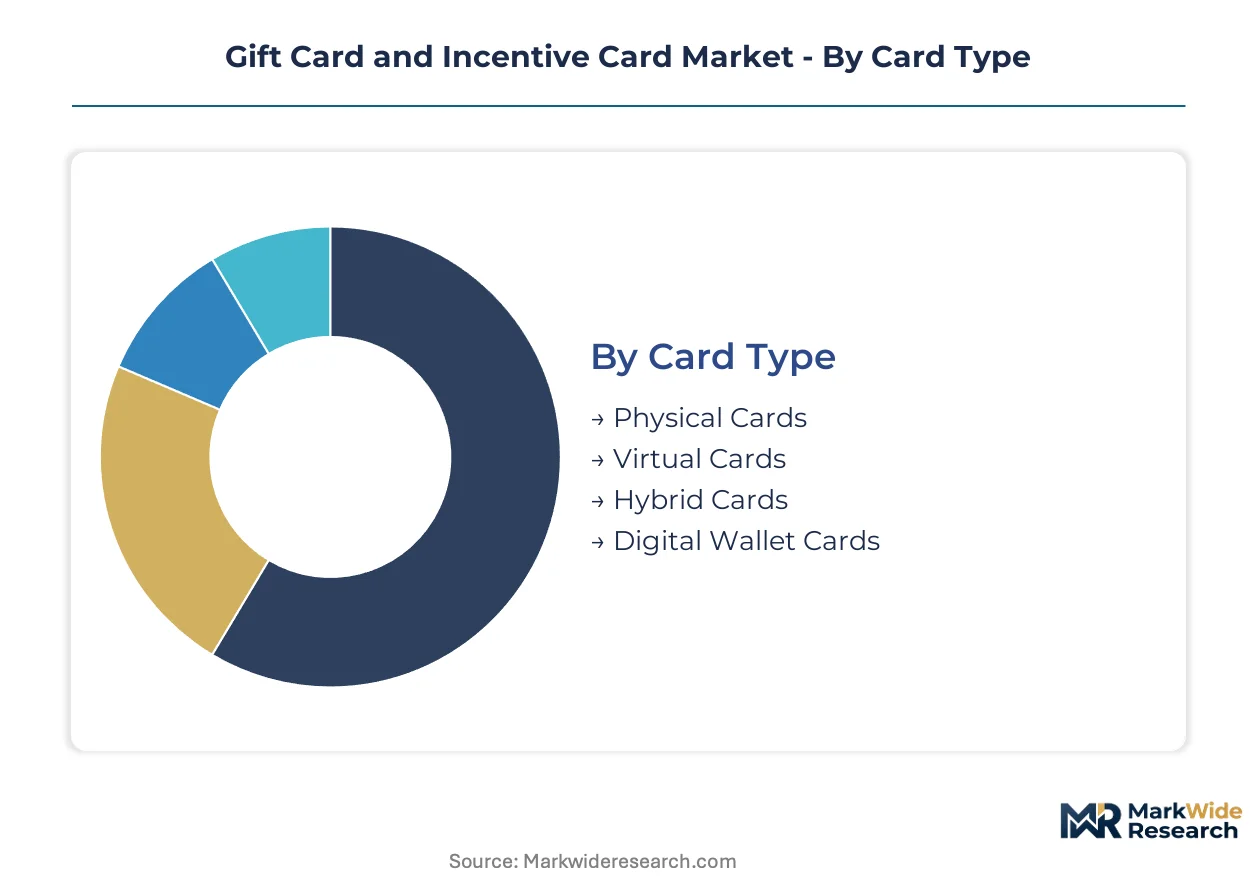
Segmentation in the Gift Card and Incentive Card Market reveals how technology choices, application contexts, and channel strategies concentrate margin pools. Distinct procurement patterns across card formats and end-user verticals create differentiated competitive arenas requiring specialized platform capabilities.
Card Type:
Card Type segmentation tracks the migration from magnetic stripe substrates toward tokenized digital credentials, with each format carrying distinct manufacturing economics and integration requirements.
- Physical Cards:EMV chip and magnetic stripe encoding dominate this substrate-dependent category. Retail rack placement across United States grocery and convenience channels sustains volume concentration despite compression from digital alternatives.
- Virtual Cards:Real-time API issuance eliminates inventory carrying costs entirely. Corporate incentive programs in enterprise HR technology stacks drive the steepest adoption trajectory as bulk-order automation replaces physical fulfillment workflows.
- Hybrid Cards:Dual-credential systems bridge physical and digital redemption paths. Merchant-branded programs seeking omnichannel flexibility concentrate demand here.
- Digital Wallet Cards:Proprietary tokenization integrates directly with Apple Wallet and competing wallet architectures. Open-banking API mandates in European markets accelerate deployment velocity.
Mature deployment sits with Physical Cards. Newer deployment is concentrated in Virtual Cards.
Application:
Application segmentation maps how stored-value instruments serve distinct commercial objectives from workforce compensation to customer acquisition mechanics.
- Corporate Incentives:Configurable bulk-order platforms with API-driven fulfillment anchor enterprise procurement budgets. United States HR departments embed these systems directly into compensation management stacks, deepening margin pools through recurring platform contracts.
- Customer Loyalty:Subscription-based program management consolidates around providers bundling issuance, redemption analytics, and fraud monitoring. Amazon's Prime ecosystem exemplifies captive marketplace anchoring of digital distribution.
- Employee Rewards:Non-cash compensation workflows integrate with existing payroll and benefits administration systems. Mid-market enterprises drive standardization here.
- Promotional Campaigns:Time-bound issuance for product launches and seasonal marketing requires rapid deployment flexibility. Marketing agencies prioritize speed over customization depth.
- Event Giveaways:Conference and experiential marketing deployments favor low-denomination, single-use formats. Activation infrastructure costs constrain scalability.
Margin concentration favors Corporate Incentives. Volume expansion is climbing the fastest in Customer Loyalty.
End User:
End User segmentation reflects how vertical-specific compliance burdens and redemption infrastructure shape platform requirements.
- Financial Institutions:Anti-money laundering regulations tighten compliance burdens on anonymous prepaid thresholds. Enhanced due diligence requirements for stored-value instruments below identification thresholds elevate operational costs.
- E-commerce Platforms:Digital-native redemption infrastructure eliminates physical point-of-sale constraints. Amazon and competing marketplaces leverage captive customer bases for seamless gift card circulation.
- Retailers:Merchant-branded card ecosystems remain deeply embedded in United States consumer behavior. Physical rack placement and private-label program management sustain relevance.
- Hospitality Chains:Property management system integration drives closed-loop program design. Franchise structures complicate centralized platform adoption.
- Travel Agencies:Cross-border redemption requirements expose GDPR data handling complexity. Currency fluctuation hedging adds financial engineering overhead.
Compliance complexity peaks with Financial Institutions. Platform agility concentrates in E-commerce Platforms.
Distribution Channel:
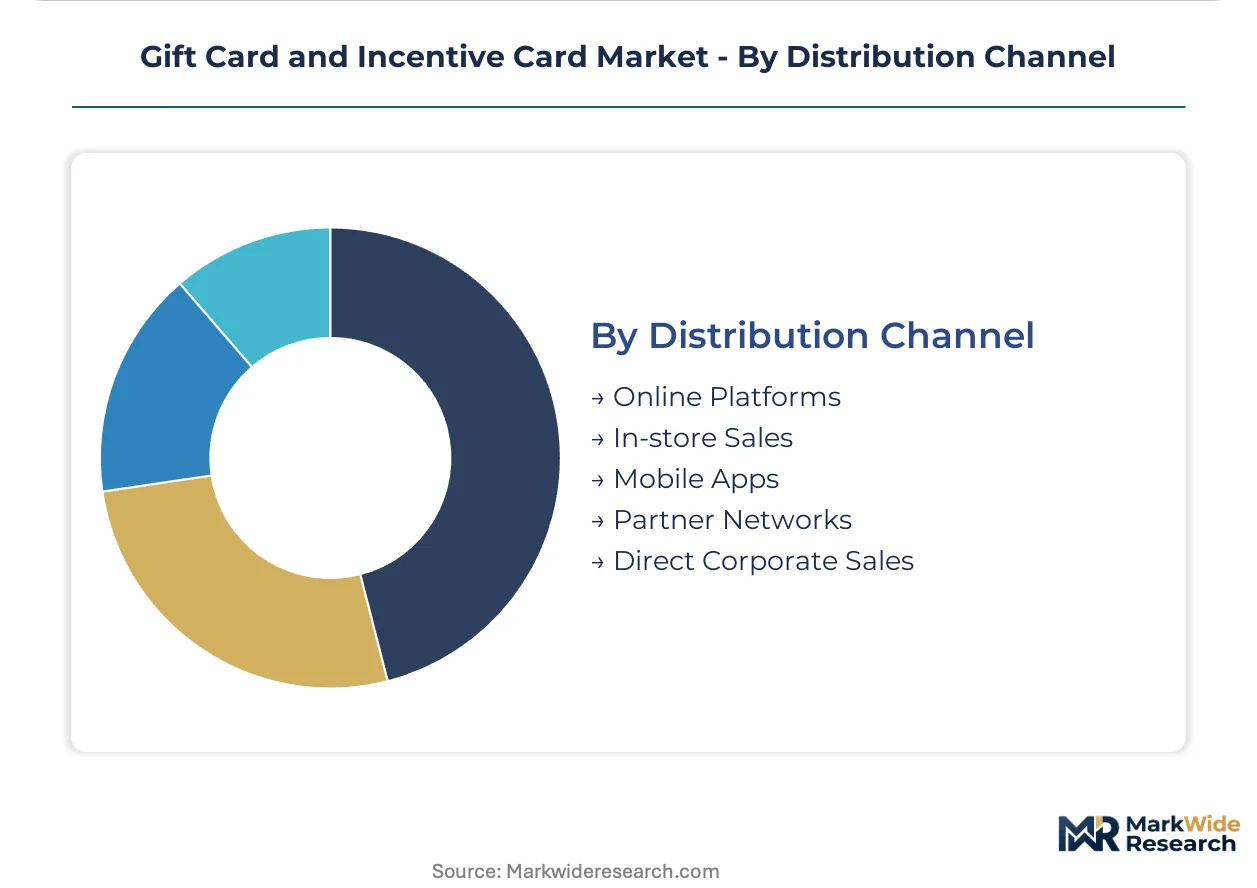
Distribution Channel segmentation captures the displacement of retail rack networks by direct enterprise integration and mobile-first issuance.
- Direct Corporate Sales:ERP-integrated fulfillment displaces traditional distribution for bulk incentive orders. Enterprise procurement departments prioritize configurable platforms with automated workflow embedding.
- Online Platforms:Real-time digital issuance compresses delivery timelines from days to seconds. Consumer self-service redemption reduces customer service overhead.
- Mobile Apps:Wallet-integrated branded cards leverage proprietary tokenization for margin-rich positioning. Apple sustains competitive advantage through hardware-software integration depth.
- In-store Sales:Physical activation infrastructure across grocery and convenience channels concentrates with InComm Payments and competing network density players.
- Partner Networks:Third-party program management introduces margin sharing arrangements. Co-branding complexity elevates contractual negotiation overhead.
Legacy infrastructure investment protects In-store Sales. Growth capital is flowing into Direct Corporate Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors digital wallet card innovation through Apple Inc.'s hardware-software integration. The Bay Area's fintech density accelerates tokenization protocol development. This concentration shapes how purchasing power transfers across merchant networks worldwide.
United States
Enterprise HR technology stacks drive corporate incentive card adoption through API-driven fulfillment platforms. The Federal Reserve's Regulation E governs prepaid instrument liability frameworks. New York's financial services corridor hosts major issuers integrating compliance tooling into card management systems.
Germany
Industrial conglomerates deploy incentive cards within workforce compensation workflows. The EU's PSD2 mandates payment initiation APIs that accelerate digital wallet integration. Frankfurt's banking cluster concentrates open-banking infrastructure development for cross-border redemption.
United Kingdom
E-commerce platforms leverage captive customer bases for seamless gift card circulation. The Financial Conduct Authority's e-money regulations constrain anonymous prepaid thresholds. London's fintech ecosystem pioneers subscription-based loyalty program bundling.
Japan
Retail conglomerates sustain merchant-branded card ecosystems through physical and digital hybrid formats. METI guidelines shape stored-value instrument disclosure requirements. Tokyo's convenience store network density supports last-mile activation infrastructure.
India
Digital payment adoption accelerates virtual card issuance for promotional campaigns. The Reserve Bank of India's prepaid payment instrument regulations mandate KYC compliance thresholds. Mumbai's financial district concentrates enterprise procurement platform development for bulk incentive orders.
Gift Card and Incentive Card Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across issuance infrastructure. The market structures around three tiers: technology-integrated platform owners, retail network density operators, and specialized incentive program managers. Strategic moves concentrate on API-driven fulfillment automation and subscription-based loyalty bundling.
Within the technology-integrated tier, Apple Inc. exemplifies hardware-software vertical control through wallet-embedded tokenization. Amazon.com, Inc. represents marketplace-anchored distribution leverage. InComm Payments occupies the physical activation infrastructure position across grocery and convenience channels.
| Leading Market Players |
|---|
| Blackhawk Network Holdings, Inc. |
| InComm Payments |
| Amazon.com, Inc. |
| Walmart Inc. |
| Apple Inc. |
| Visa Inc. |
| Target Corporation |
| Starbucks Corporation |
| Edenred Group |
| Others |
Supply & Pricing Matrix
EU PSD2 data localization mandates gate qualified supply for premium-tier digital wallet card platforms, filtering out non-compliant infrastructure providers and anchoring price premiums to regulatory certification depth rather than raw processing scale.
Pricing Analysis
Outcome-based pricing anchored to redemption throughput and fraud prevention yield dominates enterprise procurement negotiations. Three-tier pricing structure across premium API-integrated, standard self-serve, and economy bulk-issuance levels separates compliant financial institutions from mid-market retailers and promotional campaign buyers. Cost compression in economy tiers is intensifying because virtual card infrastructure eliminates physical manufacturing overhead entirely. Promotional campaign buyers exhibit highest price sensitivity; financial institutions under AML scrutiny show lowest sensitivity due to compliance-driven vendor consolidation.
Supply Chain Analysis
Single-source vulnerability sits with East Asian EMV chip foundries concentrated in Taiwan and South Korea. Plastic substrate production draws from petrochemical feedstocks anchored in China, Germany, and the United States. Tariff exposure on semiconductor inputs creates margin volatility for physical card manufacturers. Distribution runs through direct ERP integration displacing retail rack networks for corporate incentive volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where the Federal Reserve's Regulation E liability frameworks create a barrier-to-entry moat for issuers with embedded legal infrastructure.
For Market Incumbents: Anticipate margin compression from tokenization protocol commoditization by deepening API integration depth with enterprise HR platforms and defending position through captive fraud monitoring tooling. Prioritize certification investment in GDPR-compliant data architectures as European procurement budgets consolidate around compliant vendors. For New Entrants and Emerging Players: Direct-to-enterprise API sales channels bypass incumbent retail network density advantages. White-space targets include mid-market hospitality chains seeking property management system integration and Indian promotional campaign issuers navigating RBI KYC thresholds. Pursue vertical specialization in subscription loyalty bundling rather than competing on issuance scale. For Investors and Strategic Acquirers: Central bank digital currency pilot announcements in major economies are the leading indicator that complementary infrastructure partnerships or absorption risks will reshape private-label card platform valuations. Long-term viability favors asset-light tokenization specialists with recurring revenue concentration over physical distribution operators. Target acquisition archetype: API-first incentive platforms with embedded compliance tooling.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Real-time issuance eliminates physical inventory carrying costs for enterprise buyers. |
| GDPR Compliance Certification | European procurement budgets consolidate around data-localization verified vendors. |
| ERP Integration Partnerships | Direct workflow embedding displaces traditional retail card rack distribution channels. |
| Tokenization Protocol Licensing | Proprietary credential systems anchor margin-rich positioning in wallet architectures. |
| Fraud Monitoring Bundling | Recurring subscription contracts deepen enterprise customer retention and switching costs. |
Research Methodology
SEC 10-K filings, EU regulatory disclosure databases, and central bank payment system reports formed the secondary backbone. Primary interviews with gift card platform executives, enterprise HR procurement leads, compliance officers at financial institutions, and retail distribution channel managers combined with bottom-up and top-down triangulation to validate volume estimates across issuance formats.
Bottom-up modeling aggregated segment-level transaction volumes while top-down cross-checks anchored against aggregate stored-value instrument flows. Card type, application purpose, end-user vertical, and distribution channel dimensions structured the forecast framework across the analysis window. CAGRs derived from historical growth rate regression adjusted for regulatory inflection points and technology substitution curves. Forecast inputs included corporate incentive program adoption rates and open-banking API penetration metrics.
The model holds under stable regulatory enforcement intensity; deviation in AML threshold adjustments or CBDC launch timelines would shift issuance format mix assumptions materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Smart Payment Market
Payments
Global Point of Sale Terminals Market
Payments
Social Media Payment Solution Market
Payments
Canada Mobile Payments Market
Payments
Asia Pacific POS Terminal Market
Payments
Japan Virtual Cards Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
United States Real Time Payments Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Mexico Payments Market
Payments
Consumer Mobile Payment Market
Payments
Payment Service Provider Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Africa Virtual Cards Market
Payments
Canada Gift Card and Incentive Card Market