
 Cryptocurrency Payment Apps Market | 2026-2036
Cryptocurrency Payment Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptocurrency Payment Apps Market Intelligence
MiCA is pivoting European demand toward licensed custodial payment rails. Coinbase leverages its regulatory licenses across multiple jurisdictions to sustain merchant onboarding velocity. Binance competes on transaction fee architecture, while BitPay anchors North American B2B invoicing workflows through stablecoin settlement corridors.
Cryptocurrency payment apps function as software interfaces enabling digital asset transfer between payers and merchants, typically integrating blockchain node infrastructure, multi-signature wallet architecture, and real-time fiat conversion APIs to execute settlement. The primary commercial purpose centers on reducing cross-border transaction friction and chargeback exposure for merchants accepting volatile or stablecoin-denominated payments. Mobile platforms dominate transaction volume due to QR-code-native merchant interfaces and biometric authentication standards, while escrow-based transaction methods capture elevated trust premiums in freelance and high-value retail segments where settlement finality concerns persist.
The EU AI Act, MiCA framework, and FATF Travel Rule collectively reshape product architecture by mandating identity verification workflows, reserve transparency, and audit trail retention across payment corridors. The SEC's enforcement posture on unregistered staking services further constrains revenue model expansion for US-facing providers. Stakeholders must monitor divergence between permissive Asian licensing regimes and restrictive European compliance thresholds when allocating product development resources.
Market Dynamics
Merchant checkout integration is fragmenting across jurisdictional licensing requirements, forcing payment app providers to architect modular compliance stacks that can toggle between Singapore's permissive custodial framework and Europe's MiCA reserve transparency mandates.
Growth Catalysts
- MiCA Reserve Mandates:Europe's Markets in Crypto-Assets framework requires stablecoin issuers to maintain liquid reserves, creating demand for audited settlement rails that payment apps can white-label to merchants seeking regulatory cover.
- QR-Code Native Interfaces:Mobile-first merchant onboarding in Southeast Asia is compressing implementation timelines from weeks to hours, accelerating small-business penetration in Singapore and Vietnam.
- Stablecoin Settlement Corridors:Cross-border B2B invoicing workflows are migrating from correspondent banking to USDC and USDT rails, reducing settlement finality from T+2 to near-instant.
Market Restraints
- SEC Staking Enforcement:The Securities and Exchange Commission's litigation posture against unregistered yield-bearing products constrains revenue model expansion for US-facing providers, forcing geographic portfolio rebalancing.
- Node Infrastructure Concentration:Ethereum validator sets and Bitcoin mining hash rate concentrate in specific jurisdictions, creating geopolitical tail risk for settlement finality guarantees.
- Fiat On-Ramp Friction:Banking partnerships for cryptocurrency-to-fiat conversion remain concentrated among a handful of licensed money transmitters, elevating counterparty exposure.
Strategic Opportunities
- Embedded Finance Convergence:Payment apps that integrate decentralized finance primitives with traditional merchant acquiring are capturing wallet share in Latin American markets where banking penetration lags.
- FATF Travel Rule Automation:Jurisdictions implementing the Financial Action Task Force's beneficiary disclosure requirements are creating first-mover advantages for apps with native identity verification workflows.
- Freelance Escrow Segments:High-value retail and independent contractor marketplaces represent underpenetrated verticals where programmable escrow and multi-signature release conditions command trust premiums.
Industry Challenges
- Smart Contract Audit Talent Scarcity:The pipeline of developers capable of formal verification for payment rail contracts remains constrained, elevating bug bounty costs and insurance premiums.
- Cross-Chain Interoperability Complexity:Merchant demand for settlement across multiple layer-1 and layer-2 networks requires maintaining liquidity pools and light client infrastructure that fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptocurrency Payment Apps Market |
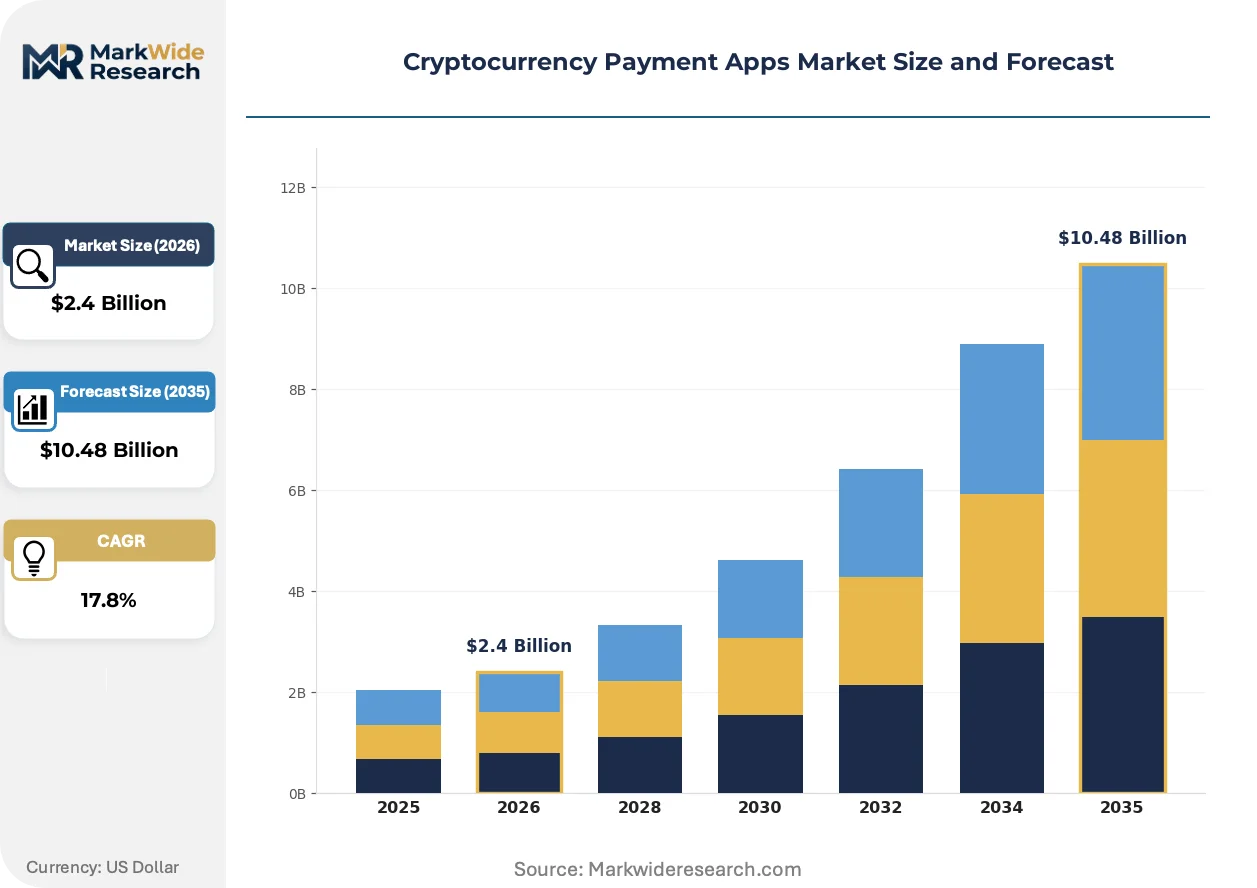
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $10.48 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: E-commerce, Retail, Remittances, Invoicing User Type: Individual Users, Merchants, Businesses, Freelancers Platform: Mobile, Web, Desktop, Hybrid Transaction Method: Direct, Escrow, Peer-to-Peer, Subscription |
| Companies Covered | BitPay, Coinbase, Binance, CoinGate, Circle Internet Financial, Coinomi, Paytomat, Apirone, CoinPayments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptocurrency Payment Apps Market Strategic Shifts & Innovations
Wallet architecture is bifurcating between self-custodial and custodial models, with merchant-facing products converging on hybrid designs that abstract private key management while preserving audit trail compliance.
Account abstraction standards on Ethereum are modularizing wallet functionality, enabling programmable transaction batching and gasless experiences for end-users. E-commerce merchants in Germany and the Netherlands are piloting these interfaces to reduce checkout abandonment. The technology is modularizing how payment apps bundle authentication, authorization, and settlement into single atomic operations.
Singapore's Payment Services Act licensing regime is mandating segregation of customer assets from operational funds, compelling infrastructure providers to rearchitect treasury operations. This industrial consequence elevates compliance costs for smaller entrants while entrenching licensed incumbents. Asian payment corridors are responding by consolidating under MAS-regulated entities to maintain correspondent banking relationships.
Merchant procurement of payment rails is compressing vendor evaluation cycles from multi-quarter RFP processes to API sandbox trials measured in days. Aggregator platforms serving mid-market retailers are displacing direct sales motions. This behavioral shift is most visible in Southeast Asian markets where plug-and-play checkout widgets dominate e-commerce platform marketplaces.
Cryptocurrency Payment Apps Market Segmentation
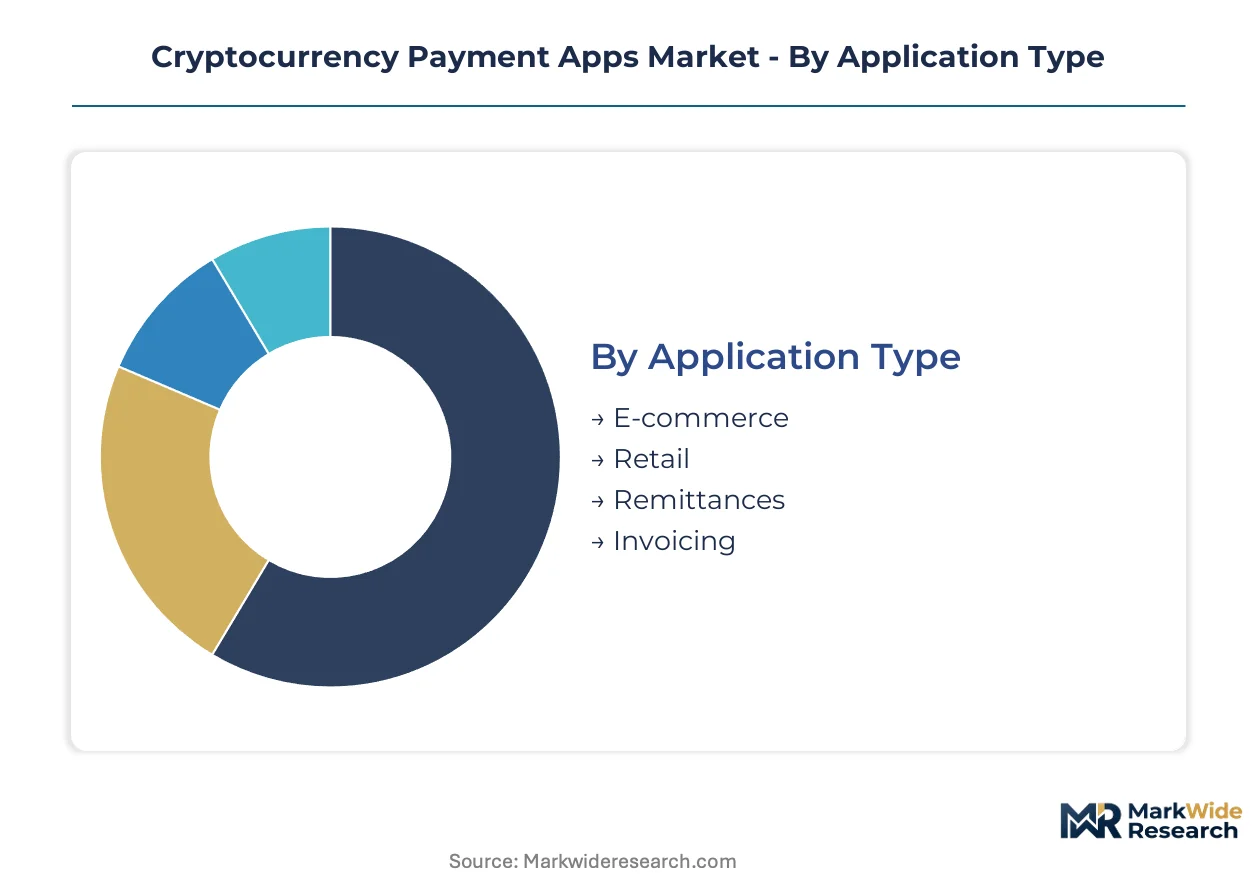
Cryptocurrency payment apps fragment across four operational dimensions that determine compliance architecture, revenue model design, and geographic deployment strategy. Each segmentation axis carries distinct regulatory exposure and margin profiles that shape vendor prioritization.
Application Type:
Merchant procurement decisions center on settlement finality requirements and chargeback risk exposure.
- E-commerce:Checkout integrations demand sub-second confirmation times and stablecoin-denominated pricing to shield merchants from volatility. Demand clusters in Germany and the Netherlands where account abstraction pilots reduce cart abandonment.
- Retail:Point-of-sale systems prioritize QR-code-native interfaces and biometric authentication for in-person velocity. Singapore's hawker centers and Vietnamese convenience stores drive mobile-first deployment.
- Remittances:Cross-border corridors leverage USDC and USDT rails to bypass correspondent banking delays.
- Invoicing:B2B workflows require programmable escrow and multi-signature release conditions for high-value settlements.
Volume sits with E-commerce; growth tilts toward Invoicing.
User Type:
Customer acquisition costs and lifetime value calculations diverge sharply across entity scale and transaction frequency.
- Individual Users:Retail adoption depends on fiat on-ramp friction and wallet abstraction complexity. Southeast Asian markets show concentration where banking penetration lags.
- Merchants:Small-business onboarding compresses from weeks to hours via plug-and-play checkout widgets in platform marketplaces.
- Businesses:Enterprise procurement runs through API sandbox trials measured in days rather than multi-quarter RFP processes.
- Freelancers:Independent contractor marketplaces command trust premiums for programmable escrow with milestone-based release conditions.
Merchant transaction density anchors current revenue; Freelancer segments climb the fastest as gig economy platforms integrate native settlement.
Platform:
Engineering resource allocation hinges on device-native authentication standards and offline functionality requirements.
- Mobile:Dominates transaction volume through QR-code interfaces and biometric security. Singapore's Payment Services Act mandates segregated asset architecture that elevates compliance costs.
- Web:Browser-based interfaces serve merchant dashboard analytics and reconciliation workflows.
- Desktop:Institutional treasury operations require hardened key management and multi-signature coordination.
- Hybrid:Cross-platform synchronization enables seamless handoff between mobile initiation and desktop confirmation.
Mobile captures absolute transaction count; Hybrid deployments gain share fastest as merchants demand unified reconciliation across devices.
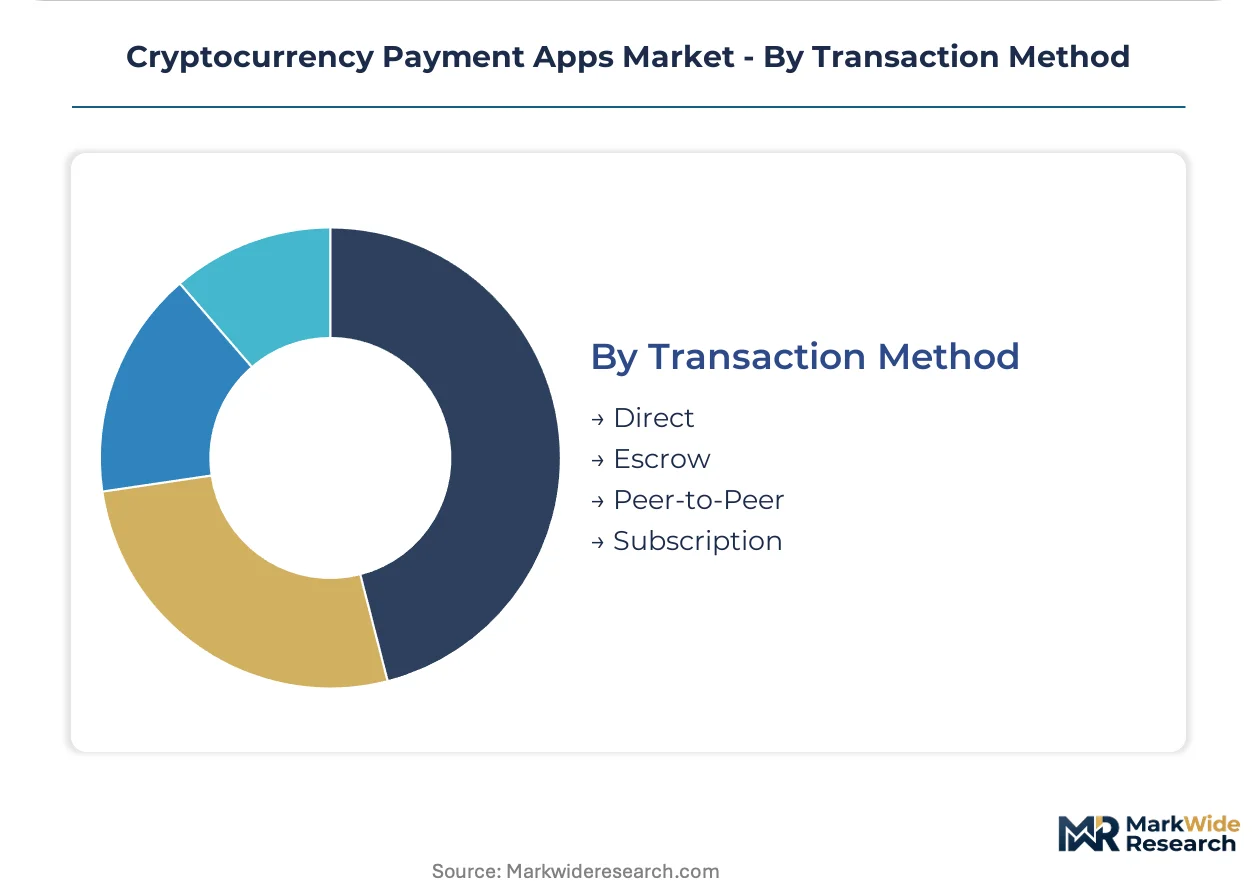
Transaction Method:
Settlement architecture selection reflects counterparty trust levels and recourse requirements.
- Direct:Immediate transfer without intermediary suits established merchant-customer relationships with low dispute incidence.
- Escrow:Programmable release conditions capture elevated premiums in freelance and high-value retail where finality concerns persist.
- Peer-to-Peer:Disintermediated exchange protocols reduce fees but increase self-custody burden for non-technical users.
- Subscription:Recurring authorization frameworks require stablecoin-denominated pricing to manage volatility exposure over multi-period contracts.
Direct settlement handles volume density; Escrow mechanisms expand most quickly as marketplace platforms integrate native trust infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay financial district anchors cryptocurrency payment infrastructure development, hosting licensed custodial providers under the Monetary Authority of Singapore's Payment Services Act regime.
United States
Merchant checkout integration and B2B invoicing workflows drive demand across California and New York financial corridors. The SEC's enforcement posture on unregistered staking services constrains revenue model expansion for domestic providers. Miami and Austin emerge as sub-regional clusters where state-level regulatory clarity attracts payment infrastructure startups.
Germany
E-commerce merchants pilot account abstraction standards to reduce checkout abandonment in Berlin and Munich metropolitan zones. The EU AI Act and MiCA framework mandate reserve transparency and audit trail retention across payment corridors. Frankfurt's financial district concentrates compliance technology vendors serving licensed custodial payment rails.
Singapore
Mobile-first merchant onboarding and QR-code-native interfaces accelerate small-business penetration in hawker centers and convenience retail. The Monetary Authority of Singapore's licensing regime mandates segregation of customer assets from operational funds. The Raffles Place financial district hosts consolidated payment infrastructure providers maintaining correspondent banking relationships.
Netherlands
Retail point-of-sale systems prioritize biometric authentication for in-person transaction velocity in Amsterdam and Rotterdam urban cores. MiCA reserve mandates create demand for audited settlement rails that payment apps white-label to merchants. The Eindhoven technology corridor hosts wallet architecture firms specializing in hybrid custodial designs.
Vietnam
Cross-border remittance corridors leverage stablecoin settlement rails to bypass correspondent banking delays between Ho Chi Minh City and diaspora networks. The State Bank of Vietnam's regulatory framework evolves toward licensed digital asset service provider recognition. The Saigon Hi-Tech Park concentrates engineering talent for QR-code payment interface development.
Cryptocurrency Payment Apps Market Key Industry Players
The competitive structure tilts toward licensed infrastructure providers with multi-jurisdictional compliance stacks. Consolidation pressures favor entities with established banking partnerships and regulatory cover across divergent frameworks. Three archetypes dominate: exchange-integrated payment rails, standalone merchant acquiring specialists, and stablecoin settlement infrastructure operators. Geographic portfolio rebalancing and modular compliance architecture represent the dominant competitive moves as providers navigate SEC enforcement in the United States against permissive Asian licensing regimes.
Within the licensed infrastructure tier, Coinbase and Circle Internet Financial exemplify multi-jurisdictional compliance architecture, while BitPay anchors North American B2B invoicing workflows through stablecoin settlement corridors. These entities occupy positions that reflect the market's bifurcation between exchange-integrated and standalone merchant-facing models.
| Leading Market Players |
|---|
| BitPay |
| Coinbase |
| Binance |
| CoinGate |
| Circle Internet Financial |
| Coinomi |
| Paytomat |
| Apirone |
| CoinPayments |
| Others |
Cost & Logistics Intelligence
Merchant procurement of cryptocurrency payment rails is compressing vendor evaluation cycles from multi-quarter RFP processes to API sandbox trials measured in days, forcing infrastructure providers to absorb upfront integration costs and recapture margin through transaction volume scaling rather than premium deployment fees.
Pricing Analysis
Settlement finality guarantees anchor value-based pricing tiers, with providers charging premium rates for near-instant confirmation workflows versus standard tiers accepting longer finality windows. Pricing stratifies across audited reserve transparency, jurisdictional licensing coverage, and embedded compliance automation levels. Cost compression in standard-tier merchant acquiring is intensifying because aggregator platforms displace direct sales motions. Small-business merchants exhibit highest price sensitivity, while enterprise treasury operations prioritize uptime guarantees over transaction fee minimization.
Supply Chain Analysis
Dual-sourcing requirements for fiat on-ramp banking partnerships are compelling payment apps to maintain correspondent relationships across multiple licensed money transmitters in Singapore, the United States, and Germany. Node infrastructure for Ethereum validation and Bitcoin settlement concentrates in the United States, Iceland, and Kazakhstan. Smart contract audit talent scarcity elevates bug bounty costs and insurance premiums. Single-source vulnerability in specialized compliance technology vendors represents the dominant structural risk. Distribution runs through API-first platform marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryptocurrency payment infrastructure is consolidating around licensed entities with multi-jurisdictional compliance stacks, as MiCA reserve mandates and SEC enforcement actions force capital-constrained entrants toward acquisition or exit.
For Market Incumbents: Cement regulatory moats by deepening licensing coverage across Singapore's Payment Services Act and Europe's MiCA frameworks before smaller competitors achieve scale. Acquire specialized compliance technology vendors in Frankfurt and Singapore to internalize audit trail automation capabilities. Prioritize banking partnership exclusivity in key correspondent corridors to constrain rival fiat on-ramp access. For New Entrants and Emerging Players: Account abstraction standards on Ethereum offer a technology-first wedge into German and Dutch e-commerce merchant segments where checkout abandonment reduction commands premium pricing. Target freelance marketplace platforms in Southeast Asia with programmable escrow-native interfaces. Pursue partnership-first go-to-market models with established e-commerce platform aggregators rather than direct merchant acquisition. For Investors and Strategic Acquirers: The window for entry favors licensed custodial infrastructure operators with established MAS or BaFin regulatory cover and proven banking correspondent relationships. Long-term viability hinges on compliance automation capabilities that scale across divergent jurisdictional frameworks. Watch for MiCA enforcement consistency across EU member states as the inflection indicator for European market consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Licensing Expansion | MiCA and MAS compliance coverage unlocks merchant onboarding in Europe and Singapore simultaneously. |
| Account Abstraction Integration | Programmable transaction batching reduces gas fees and cart abandonment for German e-commerce merchants. |
| Stablecoin Settlement Infrastructure | USDC and USDT rails bypass correspondent banking delays in cross-border B2B invoicing workflows. |
| Compliance Technology Acquisition | Internalizing audit trail automation reduces reliance on scarce smart contract verification talent. |
| Banking Partnership Diversification | Dual-sourcing fiat on-ramp relationships mitigates counterparty concentration in licensed money transmitter networks. |
Research Approach
Independent corroboration across payment infrastructure executives, regulatory compliance officers, and merchant platform integrators underwrites the qualitative findings, validated against secondary sources including MAS licensing disclosures, SEC enforcement dockets, EU MiCA regulatory texts, and stablecoin reserve attestation reports. Primary fieldwork encompassed structured interviews with CTOs at licensed custodial providers, API product managers at checkout integration platforms, and treasury directors at cross-border B2B invoicing firms. Bottom-up transaction volume modeling triangulates against top-down market sizing derived from banking partnership capacity disclosures and merchant onboarding velocity metrics.
Rate-of-change decomposition across the analysis window segments growth by application type, user entity scale, platform architecture, and transaction settlement method, with cross-elasticity adjustments for regulatory enforcement intensity and banking partnership availability. CAGRs were derived from trend extrapolation of licensed entity counts, merchant API integration volumes, and stablecoin settlement corridor throughput. Forecast inputs incorporate MiCA implementation timelines, SEC litigation posture trajectories, and Payment Services Act licensing queue depths.
Several conditions sit outside the modeled scope, including unannounced central bank digital currency launches, major smart contract exploit events, and abrupt correspondent banking relationship terminations. Deviation in SEC enforcement consistency or MiCA reserve audit standardization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Vehicle Toll Collection and Access System Market
Payments
Mobile POS Market
Payments
Digital Payment Market
Payments
Hong Kong Credit Cards Market
Payments
Brazil Real Time Payments Market
Payments
Middle East and Africa Buy Now Pay Later Services Market
Payments
United Kingdom Payment Market
Payments
Spain Payment Gateway Market
Payments
Mexico Real Time Payments Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Belgium POS Terminals Market
Payments
Vietnam Mobile Payments Market
Payments
Contactless Payment Market
Payments
Online Charging System (OCS) Market
Payments
Mexico Digital Wallet Market
Payments
Saudi Arabia Payments Market