
 China Liability Insurance Market | 2026-2036
China Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
China Liability Insurance Market Insights
Corporate buyer demand is consolidating around large technology and manufacturing conglomerates that require multi-layer liability structures. PICC Property and Casualty dominates state-backed infrastructure coverage and leverages its government relationships to anchor municipal construction mandates. Ping An Property and Casualty competes through integrated risk analytics platforms that extend beyond traditional underwriting into enterprise safety consulting. ZhongAn Online P&C Insurance differentiates via embedded digital distribution, occupying niche segments in e-commerce seller liability.
China liability insurance constitutes contractual risk transfer instruments that indemnify policyholders against third-party claims for bodily injury, property damage, or financial loss arising from negligence, defective products, or professional errors, with coverage limits typically structured in renminbi-denominated layers subject to SAMR filing requirements. General liability retains the largest premium pool among policy types, though professional liability accelerates fastest as the CSRC expands director and officer exposure for listed entities. Construction and healthcare lead industry vertical adoption, with the former sustaining mature premium flows from state project mandates while the latter generates widening margins from malpractice severity trends.
SAMR maintains product filing authority over policy terms and rate adequacy, while the CEA coordinates catastrophe reserve requirements that influence environmental liability pricing. The MIIT's data security obligations are forcing technology firms to purchase higher-limit cyber liability endorsements. Stakeholders must monitor how the dual carbon goals reshape manufacturing ESG underwriting standards and whether captive alternatives emerge among state-owned enterprises seeking cost control.
Market Dynamics
MIIT's tightening data security obligations are forcing technology firms to restructure their liability coverage, triggering a wave of multi-layer umbrella policy purchases that anchor premium growth across the sector.
Growth Catalysts
- MIIT Data Governance Mandates:Technology companies face escalating third-party cyber liability exposure as data localization rules harden, compelling higher-limit endorsements and specialized breach response coverage.
- State Infrastructure Procurement:Municipal construction mandates under SAMR filing requirements sustain mature premium flows through compulsory liability attachments on government-backed projects.
- CSRC Director and Officer Expansion:Listed entity disclosure obligations are accelerating professional liability uptake as securities regulators broaden personal accountability frameworks for corporate officers.
Market Restraints
- Renminbi-Denominated Layer Complexity:SAMR rate adequacy reviews create filing friction that extends product approval timelines and compresses pricing flexibility for foreign reinsurance participation.
- Catastrophe Reserve Requirements:CEA-coordinated environmental liability provisions force carriers to lock capital in low-yield reserves, elevating combined ratios on pollution and climate-related coverage lines.
- State-Owned Enterprise Captive Alternatives:Large SOEs are exploring self-insurance vehicles to circumvent commercial premium loads, threatening volume concentration among traditional underwriters.
Strategic Opportunities
- Guangdong-Hong Kong-Macao Greater Bay Area:Cross-border manufacturing clusters generate underpenetrated demand for product liability bridging mainland and international coverage standards.
- Dual Carbon Goal ESG Underwriting:MEE emissions disclosure rules create a regulatory tailwind for environmental impairment liability products targeting heavy industrial emitters.
- Embedded Digital Distribution:E-commerce platform integration enables point-of-sale liability attachment for SME sellers, replicating ZhongAn's model across logistics and live-streaming commerce verticals.
Industry Challenges
- Cyber Risk Actuarial Modeling:Sparse historical loss data for data breach severity complicates rate-setting for technology sector policies, forcing reliance on scenario-based pricing that carriers struggle to validate.
- Legacy System Integration:Traditional insurers face friction merging digital risk analytics platforms with existing policy administration infrastructure, delaying real-time underwriting automation.
- Medical Malpractice Severity Escalation:Healthcare liability lines confront rising claim severity trends that outpace premium adequacy, squeezing margins despite volume expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Liability Insurance Market |
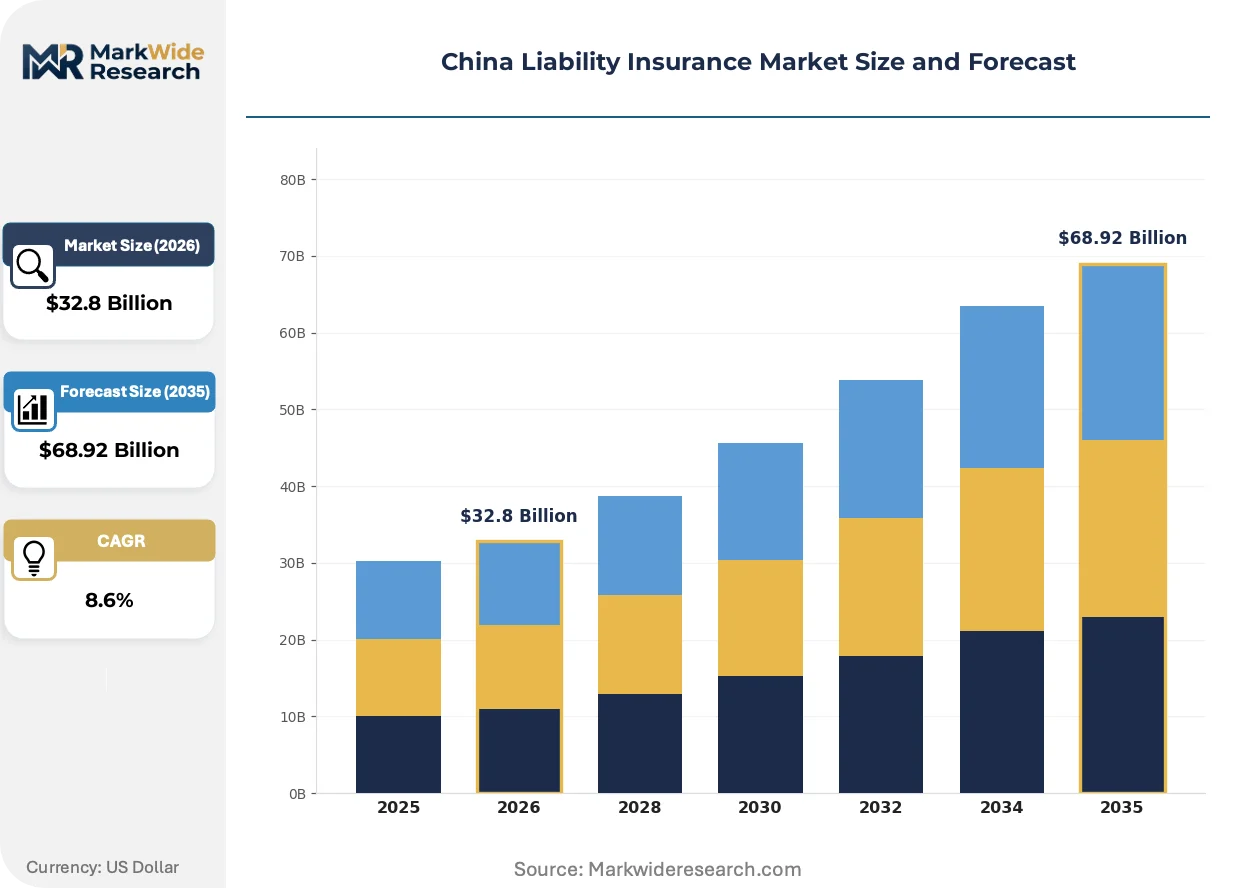
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $68.92 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
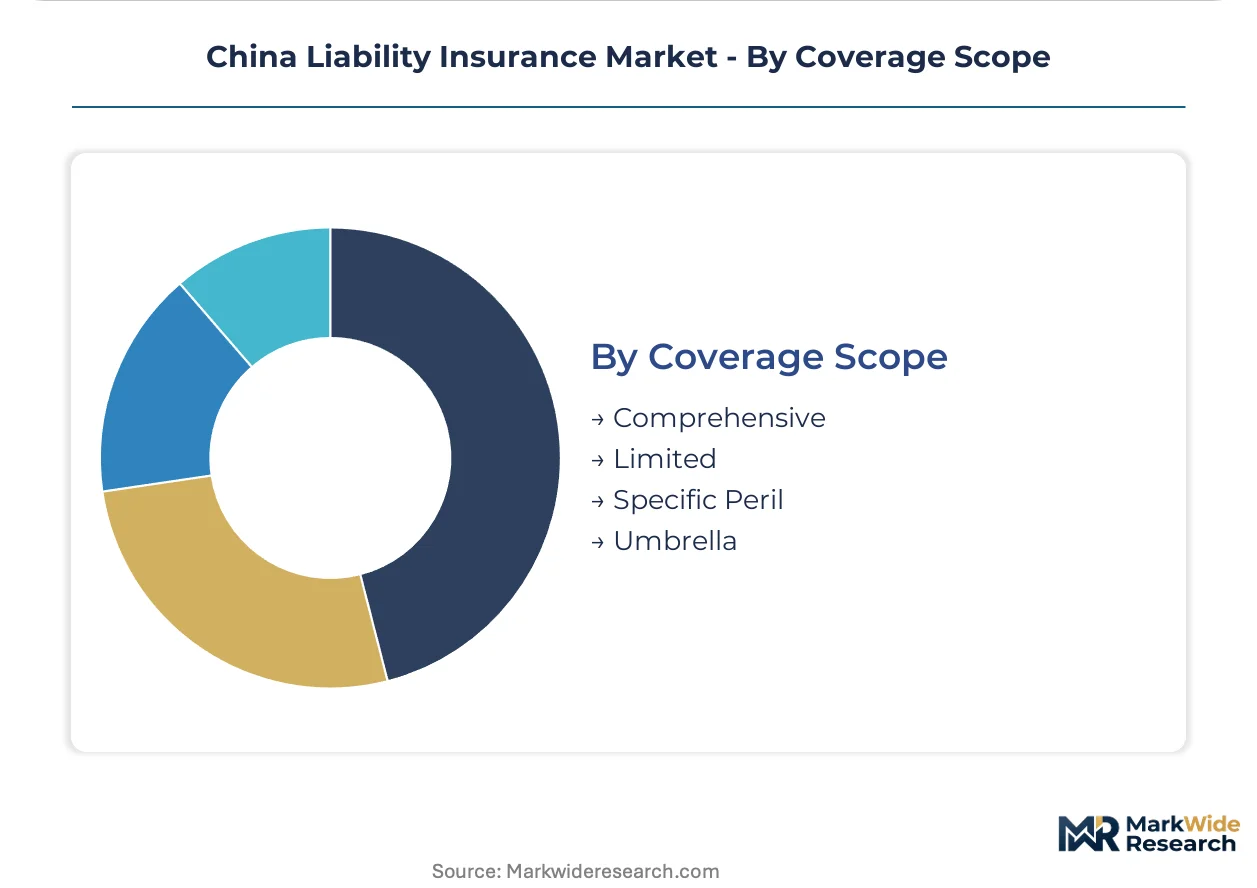
| Segmentation | Policy Type: General Liability, Professional Liability, Product Liability, Environmental Liability End User: Small Businesses, Corporations, Non-Profits, Self-Employed Industry Vertical: Construction, Healthcare, Manufacturing, Technology Coverage Scope: Comprehensive, Limited, Specific Peril, Umbrella |
| Companies Covered | PICC Property and Casualty, Ping An Property and Casualty, China Pacific Property Insurance, Huatai Property and Casualty Insurance, AXA Tianping Property and Casualty Insurance, China Taiping Insurance Holdings, ZhongAn Online P&C Insurance, Ant Insurance Services, Tencent WeSure, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Liability Insurance Market Trends and Innovations
Digital risk quantification tools are compressing underwriting cycles and enabling real-time policy adjustments, fundamentally altering how carriers price and distribute liability coverage across corporate segments.
Parametric cyber insurance triggers are expanding into technology sector policies, replacing traditional proof-of-loss documentation with automated breach detection protocols. Mid-market software firms are adopting these instruments fastest, drawn by accelerated claims settlement. This shift is expanding into director and officer coverage as boards demand instantaneous protection against securities litigation fallout.
SAMR's 2024 product filing digitization initiative is streamlining policy term approvals while tightening rate adequacy surveillance, compressing carrier pricing discretion. The regulatory overhaul most affects construction and healthcare liability lines where historical loss ratios had allowed informal rate flexibility. Domestic carriers are responding by front-loading actuarial resources into pre-submission modeling.
Corporate risk managers are consolidating vendor relationships around integrated risk analytics platforms that bundle underwriting with enterprise safety consulting. Manufacturing conglomerates in the Yangtze River Delta are driving this consolidation, preferring single-source accountability over fragmented broker arrangements. Shanghai-based multinational headquarters exhibit the most aggressive consolidation, leveraging scale to extract advisory services from premium spend.
China Liability Insurance Market Segmentation
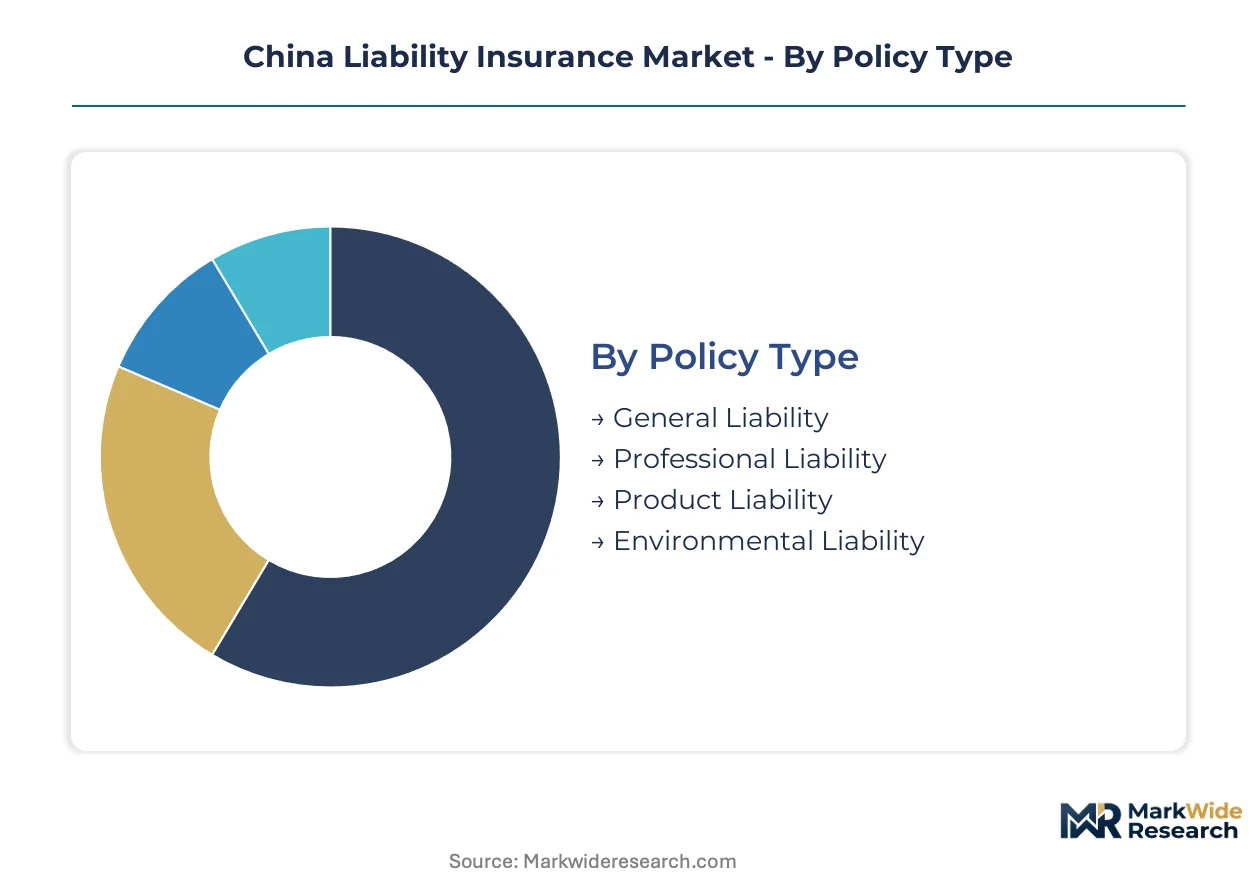
China liability insurance segmentation reflects regulatory filing requirements under SAMR and the divergent risk profiles across state-mandated construction projects versus voluntary corporate coverage. Understanding how policy structures align with MIIT data obligations and CEA catastrophe reserves enables carriers to optimize capital allocation across premium layers.
Policy Type:
SAMR maintains distinct filing protocols for each policy category, with rate adequacy reviews varying by line complexity and historical loss ratio transparency.
- General Liability:Broad-spectrum coverage indemnifying against third-party bodily injury and property damage claims arising from premises operations or completed operations. Demand concentrates among municipal construction contractors executing state-backed infrastructure mandates under compulsory attachment requirements. SAMR filing friction is lowest for this mature line, sustaining volume leadership despite compressed margins.
- Professional Liability:Indemnification instruments covering negligence claims against licensed practitioners including directors, officers, and technical consultants. Shanghai-based multinational headquarters drive umbrella-layer purchases as CSRC expands personal accountability frameworks for listed entity officers. Sparse actuarial data complicates rate-setting, forcing reliance on scenario-based pricing that carriers struggle to validate.
- Product Liability:Coverage for defective product claims spanning manufacturing, distribution, and retail chain exposure. Guangdong-Hong Kong-Macao Greater Bay Area cross-border clusters generate bridging demand between mainland GB standards and international coverage requirements.
- Environmental Liability:Pollution and climate-related impairment coverage subject to CEA-coordinated catastrophe reserve requirements. MEE emissions disclosure rules under dual carbon goals create regulatory tailwinds for heavy industrial emitters in the Yangtze River Delta.
Leading the category by volume: General Liability. Growing fastest: Professional Liability.
End User:
Premium adequacy and distribution economics diverge sharply across customer scale, with embedded digital platforms capturing SME volume while multinational headquarters demand integrated risk analytics.
- Corporations:Large technology and manufacturing conglomerates requiring multi-layer liability structures with integrated enterprise safety consulting. Shanghai financial district headquarters anchor umbrella policy uptake through consolidated vendor relationships.
- Small Businesses:E-commerce sellers and logistics operators accessing liability attachment through platform-embedded distribution. ZhongAn's digital model replicates across live-streaming commerce verticals with point-of-sale activation.
- Self-Employed:Individual practitioners and sole proprietors purchasing minimum-limit coverage to satisfy contractual counterparty requirements. Price sensitivity drives preference for limited scope over comprehensive protection.
- Non-Profits:Social service organizations and educational institutions with constrained premium budgets seeking volunteer liability and director protection. SAMR filing exemptions for certain charitable structures reduce administrative burden.
Corporations dominate premium concentration. Small Businesses are expanding most quickly through platform distribution.
Industry Vertical:
Regulatory mandate intensity and claim severity trajectories create divergent margin profiles across verticals, with state procurement sustaining construction flows while healthcare confronts severity escalation.
- Construction:Mature premium flows from compulsory liability attachments on government-backed municipal projects. SAMR filing requirements anchor coverage mandates, with PICC leveraging state relationships to dominate infrastructure accounts.
- Technology:MIIT data security obligations are forcing restructuring of cyber liability coverage with higher-limit endorsements and specialized breach response. Parametric triggers with automated breach detection protocols accelerate adoption among mid-market software firms.
- Healthcare:Medical malpractice lines confront rising claim severity trends that outpace premium adequacy, squeezing margins despite volume expansion from hospital network consolidation.
- Manufacturing:Dual carbon goal ESG underwriting standards reshape environmental impairment demand for heavy industrial emitters. Yangtze River Delta conglomerates prefer single-source accountability bundling underwriting with enterprise safety consulting.
Construction leads by policy count. Technology shows the steepest expansion trajectory from regulatory compulsion.
Coverage Scope:
Layer complexity and capital requirements scale non-linearly with scope breadth, with umbrella structures demanding sophisticated reinsurance participation that SAMR rate reviews complicate.
- Umbrella:Excess liability layers providing catastrophic limit protection above primary policy thresholds. Multinational headquarters in Shanghai drive uptake as CSRC accountability expansion increases personal exposure for corporate officers.
- Comprehensive:All-risk protection spanning multiple peril categories with minimal exclusion carve-outs. State-owned enterprises explore captive alternatives to circumvent commercial premium loads on broad coverage.
- Specific Peril:Named-risk coverage isolating single exposure categories such as cyber breach or environmental impairment. Technology firms favor this structure to align precisely with MIIT data governance mandates.
- Limited:Restricted scope policies with explicit exclusion language reducing premium outlay for cost-constrained purchasers. Self-employed professionals and small businesses select this tier to satisfy minimum contractual requirements.
Umbrella layers command the highest premium per policy. Specific Peril coverage is gaining share fastest from targeted regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's eastern coastal provinces where multinational headquarters and state infrastructure procurement intersect. Regional variation reflects divergent regulatory enforcement intensity and industrial cluster composition across sub-national markets.
Yangtze River Delta
Shanghai anchors umbrella policy uptake as CSRC accountability expansion drives multinational headquarters to consolidate vendor relationships. MIIT data governance mandates compel technology firms in Suzhou and Hangzhou to purchase higher-limit cyber endorsements. Manufacturing conglomerates in Jiangsu province prefer single-source accountability bundling underwriting with enterprise safety consulting.
Pearl River Delta
Cross-border manufacturing clusters in Guangdong generate bridging demand between mainland GB standards and international coverage requirements. Shenzhen technology firms adopt parametric cyber triggers with automated breach detection protocols fastest. Zhuhai and Dongguan industrial zones sustain mature premium flows from municipal construction mandates under SAMR filing requirements.
Beijing-Tianjin-Hebei
State-owned enterprise headquarters in Beijing explore captive alternatives to circumvent commercial premium loads on comprehensive coverage. MEE emissions disclosure rules under dual carbon goals create regulatory tailwinds for environmental impairment liability targeting heavy industrial emitters in Hebei. Tianjin port logistics operators access liability attachment through platform-embedded distribution.
Sichuan-Chongqing
Western China infrastructure investment sustains compulsory liability attachments on government-backed transportation projects. Chongqing automotive and electronics manufacturers drive product liability demand as supply chain complexity increases defect exposure. Chengdu technology parks show accelerating professional liability uptake from CSRC disclosure obligation expansion.
Shandong Peninsula
Petrochemical and heavy manufacturing concentration elevates environmental liability demand under MEE regulatory scrutiny. Qingdao port operations generate marine and cargo liability requirements distinct from inland coverage structures. Jinan municipal construction mandates anchor PICC's state-backed infrastructure coverage dominance through government relationship leverage.
China Liability Insurance Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital distribution and embedded coverage integration. The market structures around state-backed incumbents with government relationship advantages, integrated risk analytics platforms, and niche digital specialists. Three archetypes dominate: infrastructure mandate anchors, enterprise consulting bundlers, and platform-embedded distributors. Competitive moves concentrate on strategic partnerships with industrial clusters and portfolio diversification into parametric and cyber-specific structures.
Among state-backed anchors, PICC Property and Casualty exemplifies the infrastructure mandate tier through its leverage of government relationships. Ping An Property and Casualty occupies the integrated analytics position, bundling underwriting with enterprise safety consulting. ZhongAn Online P&C Insurance represents the digital distribution archetype, embedding liability products at point-of-sale across e-commerce and logistics platforms.
| Leading Market Players |
|---|
| PICC Property and Casualty |
| Ping An Property and Casualty |
| China Pacific Property Insurance |
| Huatai Property and Casualty Insurance |
| AXA Tianping Property and Casualty Insurance |
| China Taiping Insurance Holdings |
| ZhongAn Online P&C Insurance |
| Ant Insurance Services |
| Tencent WeSure |
| Others |
Pricing and Supply Chain Analysis
Reinsurance capital costs flow from international markets through SAMR rate adequacy reviews into renminbi-denominated premium layers, compressing carrier pricing discretion while elevating capital requirements for umbrella structures. This cost transmission shapes a three-tier pricing structure across premium, standard, and economy levels that segments corporate buyers by limit complexity and regulatory filing intensity.
Pricing Analysis
Volume concentrates in standard-tier general liability with compressed margins from state-mandated construction attachments, while premium-tier umbrella layers capture disproportionate margin from CSRC-driven director and officer exposure expansion. Price differentiation hinges on SAMR filing tier and reinsurance participation depth, with multinational headquarters in Shanghai exhibiting lowest price sensitivity due to consolidated vendor relationships. Pricing pressure stems from SOE captive alternatives threatening volume concentration, forcing traditional underwriters to absorb advisory service costs into premium loads.
Supply Chain Analysis
Reinsurance capacity rests on Lloyd's of London, Bermuda, and Singapore specialty markets for catastrophe-layer environmental and cyber coverage. Capital dependencies include catastrophe reserves locked under CEA coordination, SAMR-filing actuarial resources, and breach response service networks. Single-source vulnerability concentrates in international reinsurer appetite for China risk, complicated by renminbi-denominated layer complexity. Distribution runs through state-backed carrier direct channels, brokered corporate placements, and platform-embedded digital activation for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as carriers pursue backward integration into enterprise risk consulting to defend margin position against digital distributors and captive alternatives.
For Market Incumbents: Deploy captive consulting units bundling underwriting with enterprise safety advisory to counter Ping An's integrated analytics platform. Lock municipal construction relationships through PICC-style government mandate anchoring before SOE self-insurance vehicles mature. This defensive posture addresses the dual threat of ZhongAn's platform distribution and state-owned enterprise captive migration.
For New Entrants and Emerging Players: Platform-embedded distributors represent the most penetrable channel for white-space capture. Target live-streaming commerce and cross-border logistics verticals where ZhongAn's model has not yet saturated point-of-sale attachment. Pursue parametric cyber trigger specialization for mid-market technology firms seeking accelerated claims settlement.
For Investors and Strategic Acquirers: MIIT data governance mandate expansion is the leading indicator that cyber liability endorsements will command sustained premium growth. Position for acquisition of breach response service networks and automated detection protocol developers rather than traditional underwriting capacity. A small set of named triggers warrants ongoing watch: SAMR digitization timeline, CEA reserve requirement adjustments, and dual carbon goal enforcement intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Risk Analytics Platform Development | Bundles Ping An-style underwriting with enterprise safety consulting for Yangtze River Delta manufacturing conglomerates. |
| Parametric Cyber Trigger Deployment | Replaces proof-of-loss documentation with automated breach detection for MIIT-compliant technology firms. |
| Platform-Embedded Distribution Expansion | Replicates ZhongAn's point-of-sale model across live-streaming commerce and logistics verticals. |
| Captive Consulting Unit Establishment | Defends incumbent margins against SOE self-insurance alternatives through advisory service integration. |
| Cross-Border Coverage Bridging | Addresses Greater Bay Area demand for GB-to-international standard alignment in product liability. |
Research Methodology
Document review covered SAMR product filing databases, CEA catastrophe reserve disclosures, and MIIT regulatory bulletins, complemented by interviews with chief risk officers at Shanghai multinational headquarters, underwriters at PICC and Ping An, and brokers placing umbrella layers for technology sector clients. Secondary validation drew from CSRC disclosure requirement updates, MEE emissions rulemakings, and reinsurance market capacity reports. Bottom-up policy structure analysis triangulated against top-down premium flow estimates across the analysis window.
Segment-level outputs across policy type, end user scale, industry vertical, and coverage scope dimensions were modeled using historical loss ratio trajectories and regulatory mandate intensity scoring. CAGRs were derived from scenario-weighted projections incorporating MIIT enforcement phase-ins and dual carbon goal implementation pacing. Forecast inputs included construction procurement pipeline data, technology sector D&O exposure expansion rates, and healthcare malpractice severity trend assumptions.
Caveats apply where SAMR rate adequacy review delays, CEA reserve requirement recalibrations, or SOE captive vehicle approvals could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Travel Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Crop Insurance Market
Insurance
India Dental Insurance Market
Insurance
Global Long Term Care Insurance Market
Insurance
Aviation Insurance Market
Insurance
Title Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Endowment Insurances Market
Insurance
France Car Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
EV Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
India Life and Non-Life Insurance Market