
 POS Terminals Market | 2026-2036
POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
POS Terminals Market Analysis
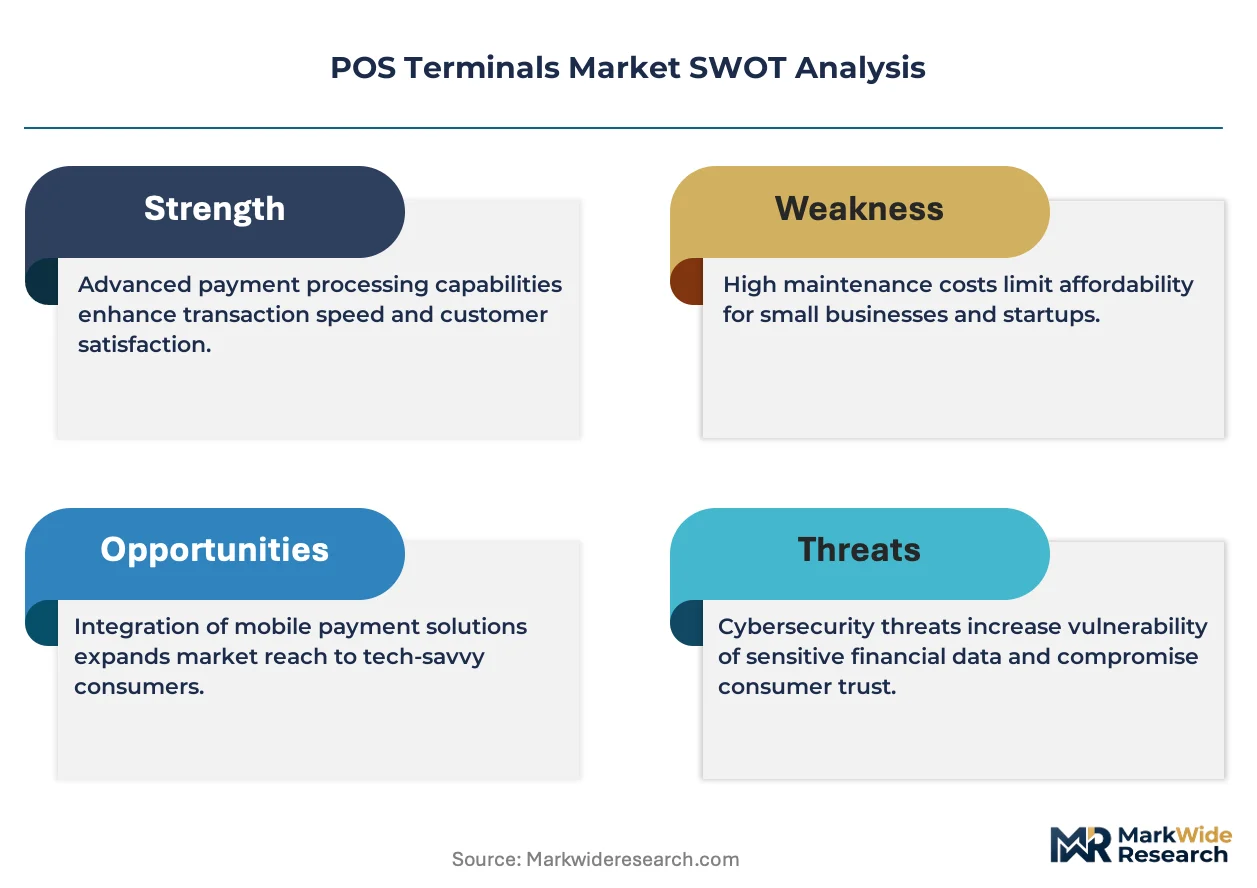
Embedded firmware engineering talent is collapsing across the POS hardware supply chain, constraining OEM capacity to certify new devices against evolving payment standards. NCR Corporation leverages its captive software stack to sustain end-to-end platform control across grocery and fuel retail verticals. PAX Global Technology Ltd. anchors Asia-Pacific manufacturing scale through Shenzhen-based production facilities. Ingenico Group competes on EMV kernel specialization and European bank channel relationships.
POS terminals constitute electronic payment interface devices combining secure processors, PIN entry modules, and encrypted communication radios to authenticate and settle card-present transactions. These systems integrate PCI PTS-certified hardware with merchant management software to enable sales recording, inventory tracking, and reconciliation across physical commerce environments. Mobile terminals lead unit shipments as micro-merchants and delivery fleets abandon fixed counter installations; cloud-based deployments capture expanding margin pools by converting capital expenditure into recurring software revenue. Contactless technology displaces magnetic-stripe dominance as NFC-enabled smartphones and wearable credentials proliferate among consumers.
FDA oversight of healthcare payment terminals intersects with HIPAA transaction security requirements, while FCC Part 15 governs radio frequency emissions for wireless POS devices operating in the United States. PCI Security Standards Council certification timelines directly shape product launch cadences and geographic market access windows for terminal vendors. Stakeholders must monitor central bank digital currency pilot programs and biometric authentication mandates to anticipate hardware refresh cycles before compliance deadlines crystallize.
Market Dynamics
Contactless payment mandates from the Reserve Bank of India and PCI DSS compliance deadlines are forcing terminal hardware refresh cycles across Southeast Asian retail chains, compressing replacement timelines from five-year cycles to three-year rotations.
Growth Catalysts
- UPI Integration Mandates:India's unified payments interface requirements push urban merchants toward NFC-enabled terminals capable of real-time settlement.
- GST-Compliant Invoicing:India's goods and services tax framework drives procurement of integrated hardware-software systems with automated tax reporting.
- Cloud Migration:Micro-merchants and delivery fleets convert capital expenditure into recurring software revenue through subscription-based terminal management platforms.
Market Restraints
- Firmware Talent Scarcity:Embedded engineering expertise is collapsing across the POS hardware supply chain, constraining OEM certification capacity.
- Shenzhen Production Concentration:Asia-Pacific manufacturing gravity creates single-point vulnerability for terminal component sourcing.
- Magnetic-Stripe Infrastructure:Legacy swipe-based merchant installations delay NFC adoption in rural and semi-urban corridors.
Strategic Opportunities
- Central Bank Digital Currency Pilots:RBI's e-rupee experimentation creates hardware upgrade demand for CBDC-compatible secure elements.
- Biometric Authentication Mandates:Fingerprint and facial recognition integration opens premium terminal tiers for high-value transaction environments.
- Healthcare Payment Terminals:HIPAA-compliant devices for hospital and clinic networks represent an underpenetrated vertical with specialized security requirements.
Industry Challenges
- PCI PTS Certification Timelines:Security standards council approval windows directly shape product launch cadences and geographic market access.
- EMV Kernel Specialization:Chip card protocol expertise scarcity limits vendor ability to support multi-standard transaction processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | POS Terminals Market |
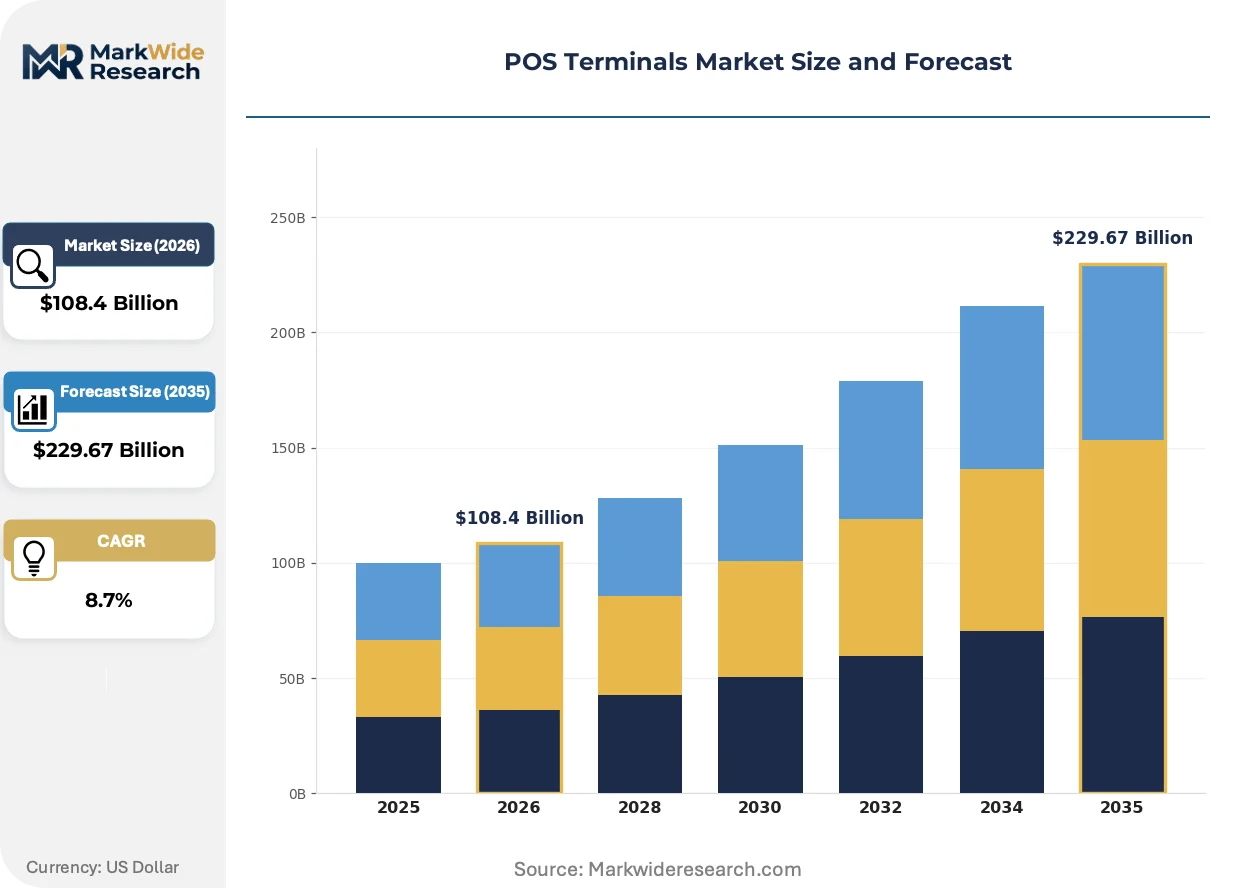
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $229.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Mobile, Self-Service, Cloud-Based Technology: Contactless, Barcode Scanners, EMV, NFC End User: Retail, Hospitality, Healthcare, Entertainment Service Type: Payment Processing, Customer Support, Software Integration, Maintenance |
| Companies Covered | NCR Corporation, Panasonic Corporation, Verifone Systems Inc., SZZT Electronics Co. Ltd., Newland Payment Technology, PAX Global Technology Ltd., Toshiba Global Commerce Solutions, Castles Technology, Ingenico Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
POS Terminals Market Emerging Trajectories
Payment terminal architecture is fragmenting across three vectors: hardware miniaturization for mobility, software unbundling for recurring revenue capture, and security layer proliferation to counter credential fraud.
SoftPOS applications running on commercial off-the-shelf smartphones and tablets is supplanting dedicated hardware for micro-merchants and pop-up retail formats. Street vendors and food truck operators in Mumbai and Jakarta now process EMV transactions through app-based acceptance without capital investment in physical terminals. This shift compresses addressable hardware volume in the sub-$200 price band while expanding total transaction processing addressable market.
India's RBI contactless payment mandates intersect with PCI DSS 4.0 compliance deadlines to accelerate terminal replacement cycles. Merchants face simultaneous pressure to support tap-to-pay limits above existing thresholds while patching legacy systems against evolving attack vectors. Urban merchant corridors in Bangalore and Hyderabad are responding with consolidated procurement of dual-certified devices rather than sequential upgrades.
Merchant acquisition patterns are rotating from bank-led distribution toward independent sales organizations and fintech direct channels. ISOs in India's tier-2 cities now bundle terminal provisioning with working capital loans, displacing traditional branch-based onboarding. This channel shift is most visible in Gujarat and Tamil Nadu, where regional payment aggregators have captured merchant onboarding velocity from incumbent banking networks.
POS Terminals Market Segmentation
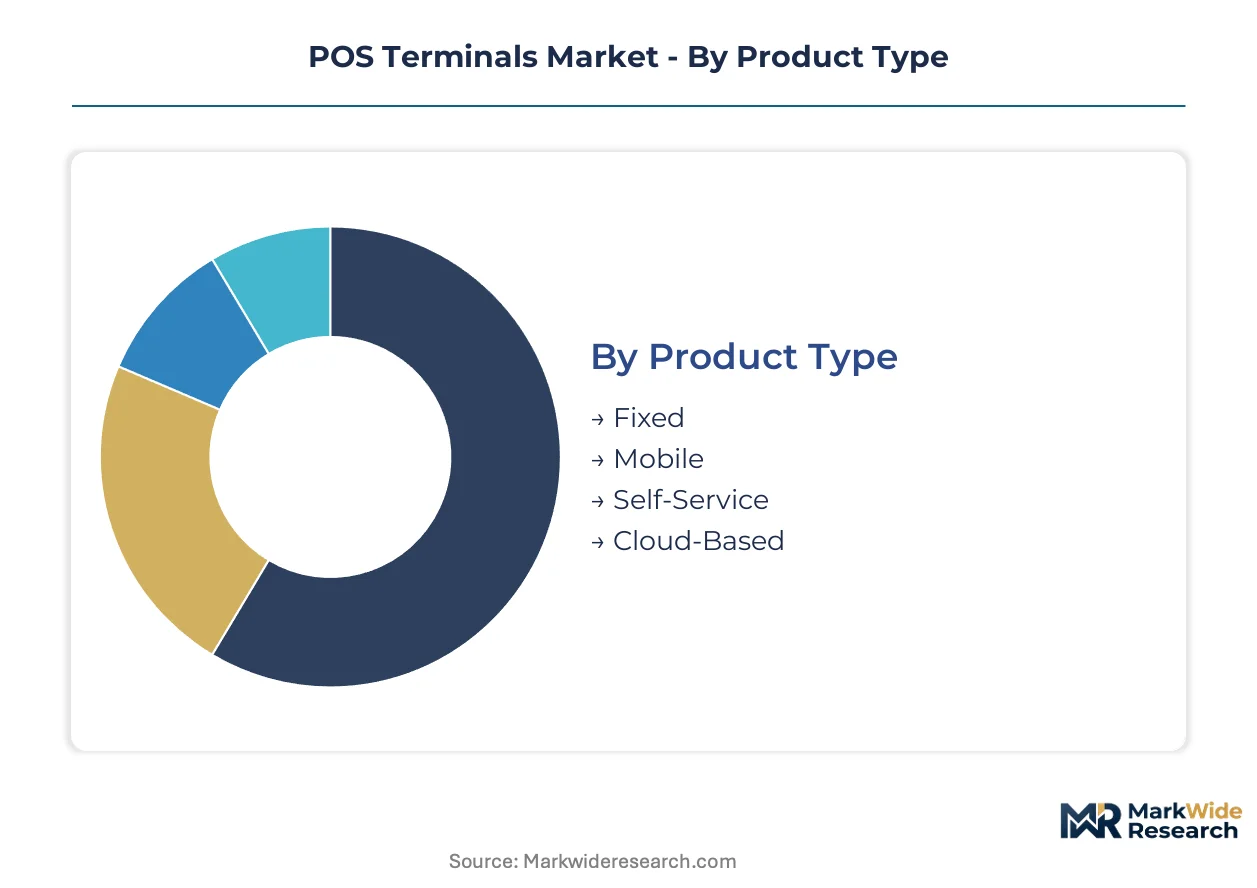
POS terminal segmentation reveals how hardware specifications, connectivity protocols, and service bundles align with distinct regulatory compliance burdens and merchant operational models. Procurement patterns diverge sharply across these dimensions as India's RBI mandates and PCI DSS timelines force targeted upgrade investments.
Product Type:
Regulatory differentiation separates fixed installations from portable alternatives through PCI PTS certification tiers and EMI shielding requirements.
- Fixed:Counter-mounted terminals with integrated PIN pads and ethernet connectivity dominate supermarket and fuel station deployments across Indian urban corridors. RBI contactless mandates are compressing replacement cycles from five to three years as merchants consolidate compliance investments.
- Mobile:Battery-powered units with cellular radios serve delivery fleets and pop-up retail formats in Mumbai and Jakarta. GST-compliant invoicing requirements push these devices toward integrated receipt printers and automated tax reporting capabilities.
- Self-Service:Kiosk-integrated terminals with customer-facing displays reduce labor costs in quick-service restaurants and cinema chains.
- Cloud-Based:Thin-client hardware dependent on persistent connectivity shifts capital expenditure to recurring software subscriptions for micro-merchants.
Established volume favors Fixed; emerging adoption favors Mobile.
Technology:
Cost tier differentiation separates legacy magnetic-stripe infrastructure from premium secure-element deployments required by evolving payment standards.
- Contactless:NFC-enabled radios supporting tap-to-pay protocols above existing thresholds are becoming mandatory across Southeast Asian retail chains. RBI's elevated contactless limits are forcing hardware refreshes before PCI DSS 4.0 deadlines crystallize.
- EMV:Chip card processing kernels with certified cryptographic modules anchor transaction security in bank-led merchant acquisition channels. Kernel specialization scarcity constrains vendor certification capacity.
- NFC:Near-field communication stacks enabling smartphone and wearable credential acceptance expand addressable transaction volume.
- Barcode Scanners:Optical readers integrated into payment terminals support inventory-linked checkout workflows in grocery verticals.
Merchant procurement concentrates on Contactless for compliance; EMV retains infrastructure dominance.
End User:
Application-specific security requirements fragment terminal specifications across vertical compliance frameworks.
- Retail:High-volume checkout environments in Indian urban corridors demand dual-certified devices supporting both UPI real-time settlement and GST-automated invoicing. Bangalore and Hyderabad merchant clusters are consolidating procurement to avoid sequential upgrades.
- Healthcare:HIPAA-compliant terminals with encrypted data paths serve hospital and clinic networks under FDA oversight. Specialized security requirements create premium pricing tiers for patient payment processing.
- Hospitality:Table-side and room-charge capabilities dominate restaurant and hotel deployments.
- Entertainment:Ticketing and concession applications prioritize transaction speed over receipt detail.
Retail captures procurement volume; Healthcare offers margin expansion through compliance specialization.
Service Type:
Customer type differentiation separates transactional commodity services from integrated platform relationships with recurring revenue capture.
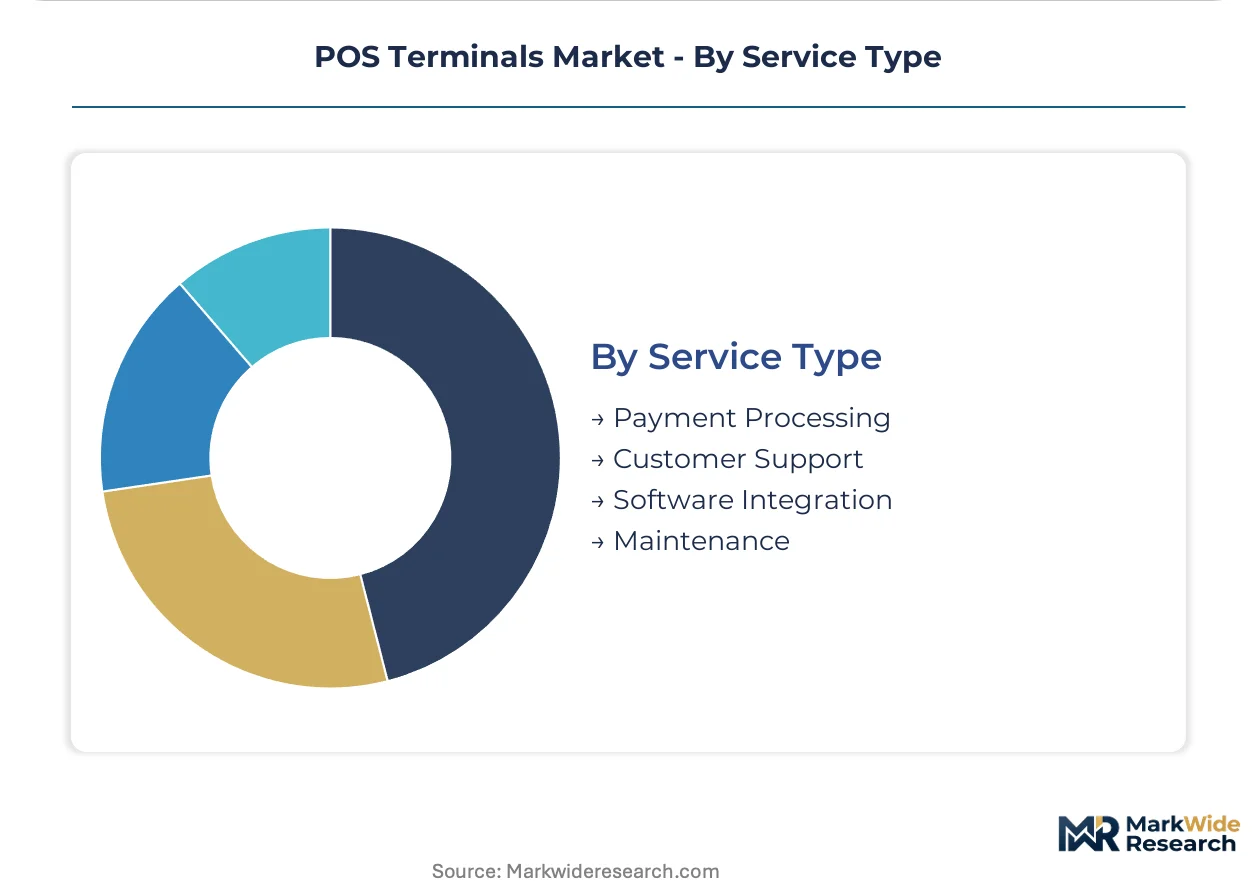
- Payment Processing:Transaction routing and settlement services constitute the core revenue pool, with ISOs in Gujarat and Tamil Nadu bundling terminal provisioning with working capital loans to displace bank-led distribution.
- Software Integration:API-linked inventory, accounting, and tax reporting systems convert hardware sales into subscription revenue streams.
- Customer Support:Helpdesk and field service networks maintain terminal uptime for merchant operations.
- Maintenance:Hardware repair and firmware update services extend equipment lifecycle against compressed replacement cycles.
Payment Processing anchors revenue; Software Integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI contactless mandates and PCI DSS compliance deadlines are compressing terminal replacement cycles across Indian urban corridors, while Southeast Asian retail chains accelerate hardware refreshes to meet evolving payment standards.
India
UPI real-time settlement and GST-automated invoicing drive merchant procurement in Bangalore and Hyderabad corridors. RBI's elevated contactless limits force dual-certified device consolidation before PCI DSS 4.0 deadlines crystallize. ISOs in Gujarat and Tamil Nadu bundle terminal provisioning with working capital loans, displacing bank-led distribution channels.
China
Shenzhen-based production facilities anchor Asia-Pacific manufacturing scale for terminal component sourcing. MIIT governs radio frequency emissions for wireless POS devices while GB standards shape domestic hardware certification. The Pearl River Delta cluster concentrates firmware engineering talent and secure element supply chains.
United States
FCC Part 15 regulates radio frequency emissions for wireless POS devices operating across merchant networks. FDA oversight intersects with HIPAA transaction security requirements for healthcare payment terminals in hospital and clinic environments. The Southeast corridor sees ISO channel expansion bundling hardware with merchant cash advance products.
Germany
EMV kernel specialization and European bank channel relationships anchor competitive positioning in continental merchant acquisition. RoHS and CE marking requirements shape hardware import compliance for Asian OEMs. The Bavaria cluster hosts payment processor headquarters influencing terminal specification standards.
Brazil
ANVISA regulatory frameworks intersect with central bank payment system mandates for healthcare and retail terminal deployments. The São Paulo metro corridor concentrates merchant acquisition activity for independent sales organizations. Legacy magnetic-stripe infrastructure in semi-urban regions delays NFC adoption despite contactless mandates.
POS Terminals Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive software stacks differentiating end-to-end platform control from component-dependent competitors. The market structure consolidates around hardware-software integration capability, with EMV kernel expertise and certification velocity serving as primary barriers. Three archetypes prevail: vertically integrated platform owners, Shenzhen-scaled manufacturers, and EMV specialization shops. Competitive moves concentrate on backward integration into secure element supply and API-linked software subscription capture.
Within the integrated platform tier, NCR Corporation and Toshiba Global Commerce Solutions exemplify captive software strategies sustaining control across grocery and fuel retail verticals. PAX Global Technology Ltd. anchors Shenzhen-based manufacturing scale for Asia-Pacific terminal supply. Ingenico Group occupies a position within the EMV specialization archetype, with European bank channel relationships supporting multi-standard transaction processing certification.
| Leading Market Players |
|---|
| NCR Corporation |
| Panasonic Corporation |
| Verifone Systems Inc. |
| SZZT Electronics Co. Ltd. |
| Newland Payment Technology |
| PAX Global Technology Ltd. |
| Toshiba Global Commerce Solutions |
| Castles Technology |
| Ingenico Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day secure element lead times in Shenzhen directly tether component availability to terminal OEM pricing power, compressing margin buffers for vendors without captive semiconductor sourcing or forward inventory positions.
Pricing Analysis
Geographic price spreads of 40-60% separate Indian urban corridors from Southeast Asian secondary markets, reflecting divergent certification burdens and logistics costs. Three-tier pricing structure across premium, standard, and economy levels aligns with PCI PTS certification grades and after-sales service bundling. Cost compression in economy tiers intensifies because SoftPOS applications displace sub-$200 hardware volumes. Micro-merchants in Jakarta street markets exhibit highest price sensitivity; hospital procurement committees in Bangalore show lowest sensitivity due to HIPAA compliance requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate terminal assembly despite secure element shortages, with strategic stockpiling limited to PCI-certified cryptographic modules. Manufacturing concentrates in China, Taiwan, and Vietnam for PCB fabrication, display assembly, and battery integration. Production draws from NAND flash memory, EMV kernel licenses, and NFC radio modules. Single-source vulnerability in Shenzhen-based secure element foundries exposes vendors to regulatory disruption. Distribution runs through independent sales organizations and fintech direct channels displacing bank-led merchant acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software Integration services represent the fastest-expanding revenue layer, converting hardware sales into recurring API-linked subscriptions for inventory, accounting, and tax reporting systems.
For Market Incumbents: Shield installed base relationships by deepening backward integration into secure element supply chains and accelerating PCI PTS 6.x certification velocity ahead of compliance deadlines. Firmware engineering talent scarcity constrains OEM capacity; captive kernel development teams in Bangalore and Shenzhen defend against emerging EMV specialization shops. Channel control through ISO partnership exclusivity in Gujarat and Tamil Nadu reinforces merchant lock-in against fintech direct channels. For New Entrants and Emerging Players: Differentiate on biometric authentication integration for healthcare and high-value retail verticals where compliance specialization commands premium pricing. White-space targets include HIPAA-compliant terminals for Indian hospital networks and CBDC-compatible devices for RBI e-rupee pilots. Go-to-market through regional payment aggregators bundling hardware with working capital loans captures merchant onboarding velocity from incumbent banking networks. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because recurring software revenue streams compound customer lifetime value beyond terminal hardware depreciation cycles. Acquisition targets include EMV kernel specialists with European bank channel relationships and cloud-native terminal management platforms. Signal to watch: central bank digital currency pilot program expansion triggering hardware refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secure Elements | Captive semiconductor sourcing defends margin position against Shenzhen supply shocks. |
| PCI PTS 6.x Certification Acceleration | Early compliance capture opens geographic market access windows before deadline crystallization. |
| Biometric Terminal Development | Fingerprint and facial recognition integration penetrates healthcare and premium retail verticals. |
| API-Linked Software Subscription Launch | Recurring revenue conversion shifts micro-merchant economics from capital expenditure to SaaS models. |
| ISO Channel Partnership Expansion | Independent sales organization bundling with working capital loans displaces bank-led distribution in tier-2 cities. |
Methodological Framework
The analysis maps fixed, mobile, and cloud-based terminal architectures, each validated through terminal OEM product managers, merchant acquisition executives at payment processors, firmware engineering directors, and healthcare compliance officers. Primary interviews combined with secondary validation against RBI circulars, PCI Security Standards Council certification databases, UPI transaction volume disclosures, and SEC 10-K filings from listed terminal vendors. Bottom-up unit shipment modeling and top-down payment industry revenue triangulation cross-check volume and value outputs.
Consistency checks against external benchmarks validated projection outputs against disclosed terminal deployment figures from payment networks and merchant bank regulatory filings. Segmentation dimensions modeled include product type, connectivity protocol, certification tier, vertical application, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to contactless payment adoption patterns and compliance deadline impacts. Industry-specific inputs encompass EMV kernel certification timelines and GST invoicing mandate enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained RBI mandate enforcement and PCI DSS timeline adherence would require recalibration. Forecasts reflect assumptions regarding firmware engineering talent availability and secure element supply continuity. Revision becomes warranted when central bank digital currency pilot program expansion crosses commercial deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Outdoor Payment Terminal Market
Payments
Mobile Payment Data Protection Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Canada Buy Now Pay Later Market
Payments
Denmark POS Terminals Market
Payments
South Korea Payments Market
Payments
Sweden Mobile Payments Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Nigeria Mobile Money Market
Payments
Asia Pacific POS Terminal Market
Payments
China Real Time Payments Market
Payments
South Africa Real Time Payments Market
Payments
NFC Payments Market
Payments
Cloud Billing Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Clearing Houses and Settlements Market