
 Japan Payments Market | 2026-2036
Japan Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Payments Market Outlook
Japan's aging IT workforce is collapsing as a bottleneck for legacy system modernization across financial institutions. Rakuten Group Inc. leverages its super-app ecosystem to anchor consumer loyalty across payments, commerce, and loyalty programs. PayPay Corporation dominates merchant acquisition through aggressive QR-code terminal deployment and zero-fee campaigns for small retailers. Mitsubishi UFJ Financial Group sustains institutional trust through its branch network while navigating digital transformation pressures.
Japan Payments encompasses electronic fund transfer systems, settlement infrastructure, and consumer-facing transaction interfaces that facilitate commercial exchange through standardized protocols such as J-Debit, QUICPay, and FeliCa-based contactless technology. The primary purpose is to replace cash-dominated commerce with traceable, interoperable digital settlement mechanisms that reduce friction for merchants and consumers. Mobile payment methods lead transaction volume growth as smartphone penetration and QR-code literacy deepen among Gen Z and millennial demographics. E-commerce transaction types capture expanding margin pools as cross-border online retail and subscription billing models proliferate. Traditional banks retain dominance in bill payment and high-value transfers, though fintech service providers are displacing them in peer-to-peer and micro-merchant segments.
METI promotes cashless conversion targets through subsidy programs and consumption tax rebate incentives for compliant merchants. The Financial Services Agency enforces Payment Services Act amendments that tighten capital requirements for prepaid payment instrument issuers and mandate customer asset segregation for crypto exchanges. JIS standards govern terminal interoperability and data security protocols for contactless transactions. Stakeholders must monitor how the Bank of Japan's central bank digital currency pilot reshapes settlement layer competition and whether regional bank consolidation accelerates or fragments merchant service pricing.
Market Dynamics
Japan's Payment Services Act amendments and METI cashless subsidies are compressing merchant compliance timelines while accelerating terminal infrastructure replacement across the archipelago.
Growth Catalysts
- METI Consumption Tax Rebate:The Ministry of Economy, Trade and Industry rewards cashless-compliant merchants with point-of-sale tax incentives, driving small retailer terminal adoption in Osaka and Fukuoka prefectures.
- FeliCa Contactless Infrastructure:Sony's embedded NFC technology enables sub-second transaction speeds that satisfy Japanese consumer expectations for railway-style tap-and-go convenience at convenience stores.
- Regional Bank Consolidation:Merger activity among Shikoku and Tohoku financial institutions is pooling capital for unified payment platform investments that previously stalled at individual bank scale.
Market Restraints
- Legacy ATM Network Costs:Rural prefectures bear disproportionate infrastructure maintenance burdens as transaction volumes migrate to digital channels, straining Hokkaido and Okinawa cooperative banks.
- Cryptocurrency Custody Capital Requirements:The Financial Services Act mandates segregated cold-wallet reserves that compress fintech balance sheet flexibility for startup exchanges seeking Payment Services Act licenses.
- Interoperability Certification Delays:JIS terminal compliance testing backlogs at accredited laboratories extend merchant onboarding timelines for QR-code hardware deployments.
Strategic Opportunities
- Kyushu and Hokkaido Underpenetration:Cash transaction rates exceeding fifty percent in rural prefectures present white-space terminal deployment opportunities for acquirers willing to absorb merchant education costs.
- Cross-Border E-Commerce Settlement:J-Debit protocol extensions into Southeast Asian corridors enable Japanese merchants to capture inbound tourist spending through familiar domestic payment rails.
- Central Bank Digital Currency Pilot:The Bank of Japan's wholesale CBDC experiments invite private settlement infrastructure providers to bid for layer-two integration contracts.
Industry Challenges
- Cobol and Mainframe Engineering Scarcity:Regional banks face recruitment gaps for systems programmers capable of modernizing core banking platforms without service disruption.
- Multi-Rail Integration Complexity:Merchants accepting both FeliCa contactless and PayPay QR-code streams require reconciliation middleware that fragments accounting workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Payments Market |
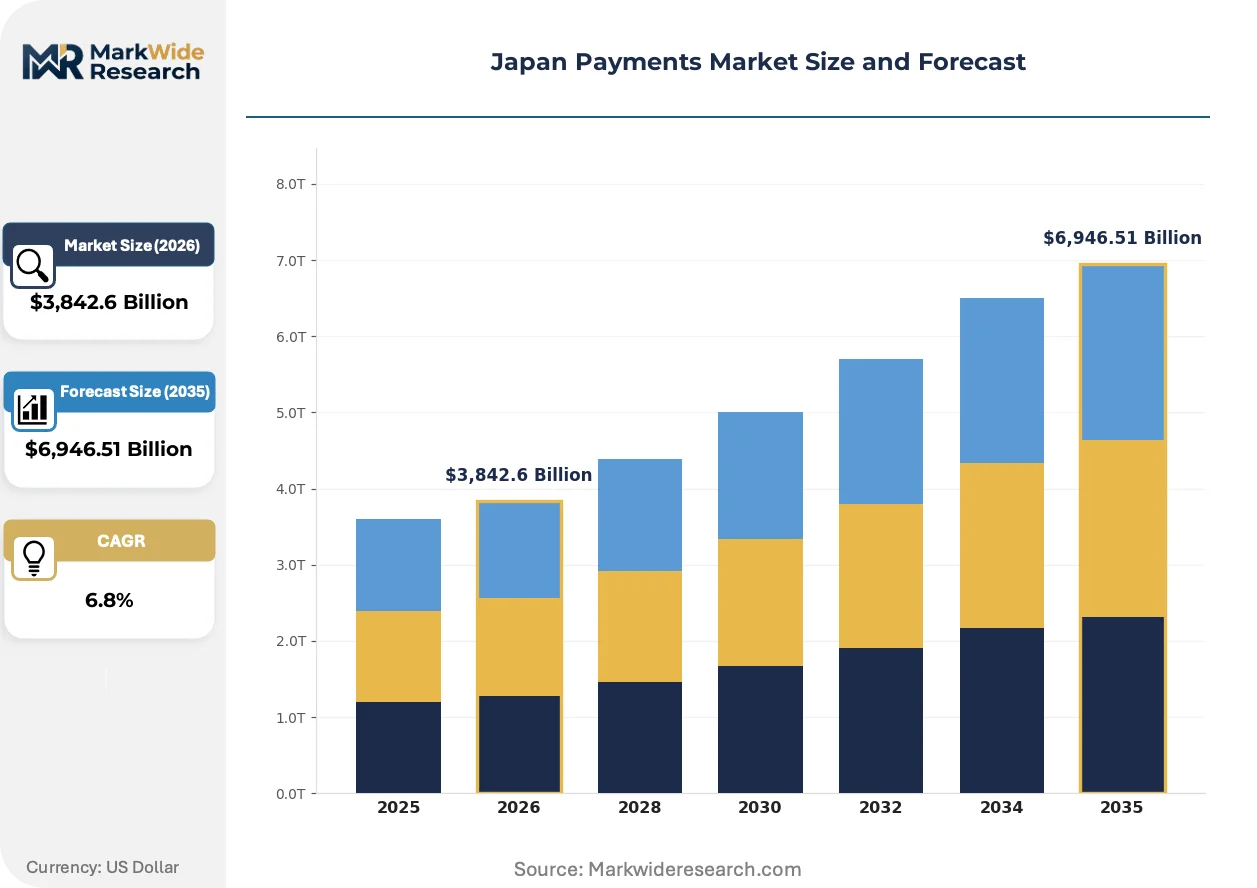
| Market Size in 2026 | $3,842.6 Billion |
| Market Size in 2035 | $6,946.51 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Payment, Bank Transfer Transaction Type: E-commerce, In-store, Peer-to-peer, Bill Payment User Demographic: Millennials, Gen Z, Seniors, Business Customers Service Provider: Traditional Banks, Fintechs, Payment Processors, E-wallet Providers |
| Companies Covered | Mizuho Group, Rakuten Group Inc., PayPay Corporation, Mer Pay Co. Ltd, Japan Post Bank Co. Ltd., KDDI Corporation, Sumitomo Mitsui Financial Group, NTT Docomo, Mitsubishi UFJ Financial Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Payments Market Strategic Shifts
Payment interface proliferation is dissolving single-rail merchant dependencies while regulatory pressure on crypto custody reshapes fintech capital structures. Behavioral shifts among aging demographics are forcing interface simplification at odds with feature expansion elsewhere.
Biometric authentication at point-of-sale is fragmenting merchant hardware procurement patterns. Convenience store chains in the Greater Tokyo corridor are piloting palm-vein readers that bypass smartphone dependency entirely. This displacement of device-centric verification is compressing acquirer terminal upgrade cycles from five-year to three-year replacement horizons.
METI's revised Payment Services Act enforcement guidelines tighten prepaid instrument issuer capital buffers and mandate real-time transaction monitoring. Fintech wallet providers face compliance cost inflation that favors incumbent bank subsidiaries with existing risk infrastructure. Crypto-asset custodians are responding by relocating operational headquarters to Fukuoka's special economic zone for regulatory sandbox access.
Elderly consumer cohorts in rural prefectures are gravitating toward voice-activated payment confirmations at post office ATMs and agricultural cooperative terminals. This behavioral pivot is pressuring interface designers to sacrifice feature depth for accessibility compliance. Deployment concentration in Aichi and Shizuoka prefectures reflects demographic density rather than urban tech adoption curves.
Japan Payments Market Segmentation
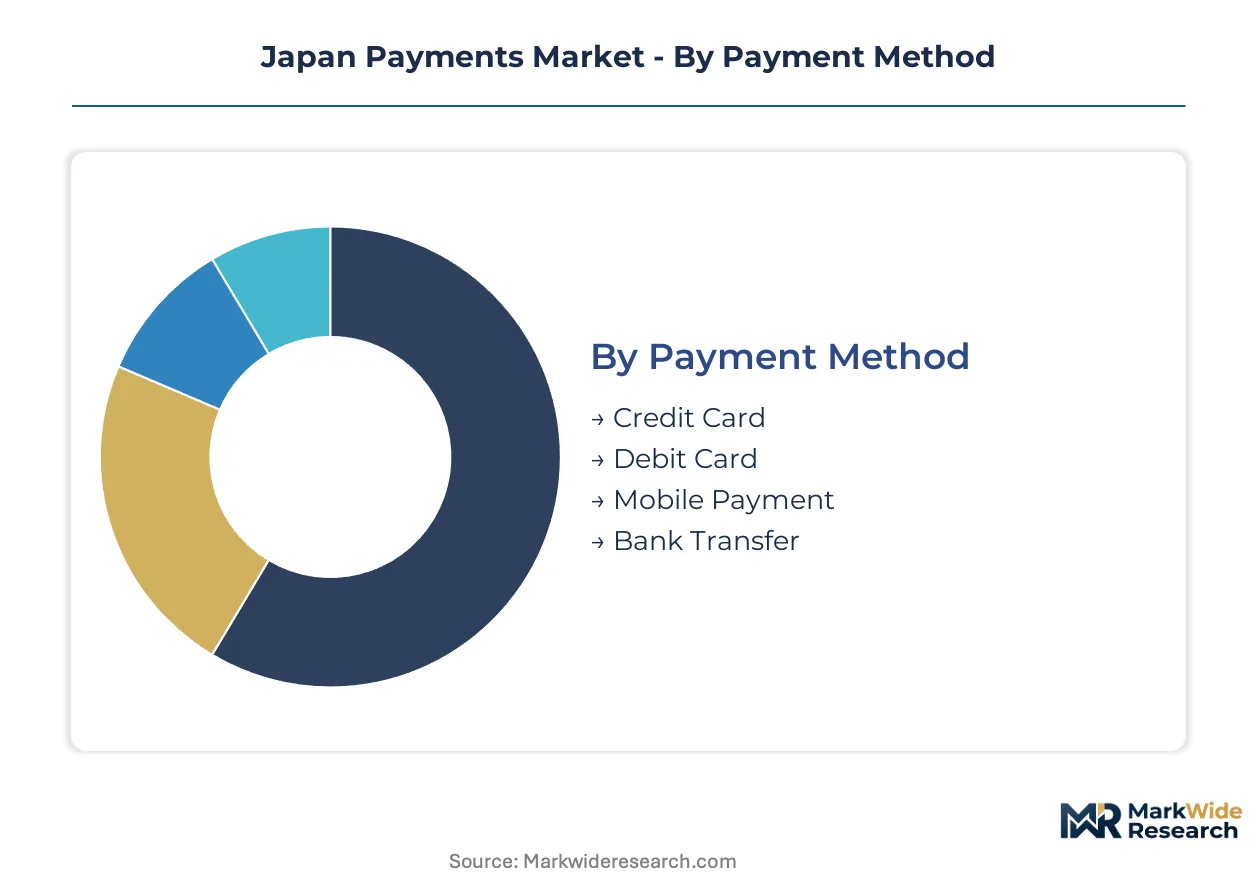
Payment method fragmentation in Japan creates distinct competitive arenas where contactless infrastructure investments clash with legacy settlement rails. Transaction type diversification forces acquirers to maintain parallel technical stacks for e-commerce and physical point-of-sale environments.
Payment Method:
Mobile payment platforms face acute substitution pressure from FeliCa-enabled contactless cards as Sony's NFC technology saturates transit and retail terminals.
- Credit Card:J-Debit and international scheme networks dominate high-value transactions through revolving credit facilities tied to loyalty point ecosystems. Corporate travel and hospitality merchants in Osaka and Fukuoka corridors concentrate demand as business expense management digitizes.
- Mobile Payment:QR-code wallets and super-app integrations capture micro-merchant volume through zero-fee acquisition campaigns and railway-style tap-and-go convenience. Gen Z consumers in Greater Tokyo drive transaction frequency through app-native reward programs.
- Debit Card:Bank-issued direct-debit instruments retain dominance in utility bill settlement and recurring subscription payments.
- Bank Transfer:Real-time gross settlement systems handle B2B invoices and property transactions requiring audit trails.
Credit cards retain volume leadership; mobile payment holds the steepest expansion curve.
Transaction Type:
Cost tier differentiation separates high-margin e-commerce processing from commoditized in-store acquiring where interchange compression squeezes processor economics.
- E-commerce:Cross-border online retail and subscription billing platforms demand multi-currency settlement APIs and fraud detection middleware. Fashion and electronics merchants in Aichi prefecture concentrate demand as inbound tourist spending shifts to pre-arrival digital channels.
- In-store:Convenience store chains and railway kiosks require sub-second authorization speeds through FeliCa contactless or QR-code acceptance. Merchant density in Tokyo-to-Osaka corridor drives terminal deployment economics.
- Peer-to-peer:Social payment splitting and informal remittances migrate from cash to app-based settlement.
- Bill Payment:Automated clearing house networks handle recurring utility and telecommunications invoices.
In-store transactions retain volume leadership; e-commerce holds the steepest expansion curve.
User Demographic:
Application-based divergence forces interface designers to balance feature depth for digital natives against accessibility compliance for aging cohorts.
- Gen Z:Smartphone-native consumers expect super-app integration where commerce, payments, and loyalty programs collapse into single interfaces. University districts and urban rental markets concentrate demand for split-payment and buy-now-pay-later features.
- Millennials:Workforce entrants prioritize corporate card integration and expense automation through mobile-first banking apps. Tokyo metropolitan employment corridors drive premium service adoption.
- Seniors:Voice-activated confirmations and large-format touchscreen interfaces dominate post office ATM and agricultural cooperative terminal design.
- Business Customers:Treasury departments demand API-accessible bulk payment initiation and multi-entity reconciliation.
Millennials retain volume leadership; Gen Z holds the steepest expansion curve.
Service Provider:
Customer type stratification concentrates margin capture among fintechs in micro-merchant segments while traditional banks defend high-value corporate relationships.
- Fintechs:QR-code acquirers and wallet providers leverage zero-fee campaigns and rapid merchant onboarding to displace legacy processors in small retailer segments. Regulatory sandbox access in Fukuoka special economic zone accelerates product iteration.
- Traditional Banks:Mitsubishi UFJ and consolidated regional institutions sustain institutional trust through branch networks while modernizing core banking platforms. Corporate treasury services and trade finance integration defend high-value relationships.
- Payment Processors:Technical infrastructure providers manage authorization switching and settlement clearing across multiple scheme networks.
- E-wallet Providers:Prepaid instrument issuers navigate tightened Payment Services Act capital requirements and real-time transaction monitoring mandates.
Traditional banks retain volume leadership; fintechs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI anchors cashless conversion policy across Japan's archipelago, directing subsidy flows toward prefectural corridors where merchant density and consumer digital literacy diverge sharply. Regional payment infrastructure modernization concentrates in metropolitan hubs while rural prefectures lag in terminal deployment.
Kanto/Tokyo
Greater Tokyo's merchant density and Gen Z smartphone penetration drive the steepest mobile payment transaction frequency in the archipelago. The Financial Services Agency enforces Payment Services Act licensing requirements that concentrate fintech headquarters in the capital corridor. Shibuya and Shinjuku ward clusters host super-app providers integrating commerce, payments, and loyalty programs into single interfaces.
Kansai/Osaka
Corporate travel and hospitality merchants in Osaka prefecture concentrate credit card transaction volume through business expense management digitization. METI consumption tax rebate incentives accelerate small retailer terminal adoption across the Keihanshin corridor. Umeda and Namba commercial districts witness aggressive QR-code terminal deployment campaigns targeting micro-merchants.
Chubu/Nagoya
Manufacturing supply chain digitization in Aichi prefecture drives B2B real-time gross settlement demand for invoice reconciliation. JIS standards govern terminal interoperability certification for contactless infrastructure deployed across automotive sector supplier networks. Nagoya metropolitan employment corridors sustain premium banking service adoption among workforce entrants prioritizing corporate card integration.
Kyushu
Cash transaction rates exceeding fifty percent in Fukuoka prefecture and surrounding prefectures present white-space terminal deployment opportunities for acquirers absorbing merchant education costs. The special economic zone in Fukuoka city accelerates fintech regulatory sandbox access for crypto-asset custodians seeking Payment Services Act licenses. Regional bank consolidation pools capital for unified payment platform investments.
Hokkaido
Rural prefectures bear disproportionate legacy ATM network maintenance burdens as transaction volumes migrate to digital channels, straining cooperative banks across the northern island. Voice-activated payment confirmations at agricultural cooperative terminals address elderly consumer accessibility requirements. Sapporo metropolitan clusters concentrate limited digital infrastructure investment amid demographic headwinds.
Japan Payments Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Japan's payment ecosystem. Three megabank groups anchor institutional trust through branch networks while defending high-value corporate treasury relationships. Fintech wallet providers and QR-code acquirers populate the specialist tier, leveraging zero-fee campaigns to displace legacy processors in micro-merchant segments. Dominant competitive moves include regional bank consolidation pooling capital for unified platforms, and super-app providers collapsing commerce, payments, and loyalty into single interfaces.
Among integrated financial conglomerates, Mitsubishi UFJ Financial Group, Mizuho Group, and Sumitomo Mitsui Financial Group represent the institutional trust tier sustaining corporate relationships through branch networks. Within the fintech specialist tier, Rakuten Group Inc. and PayPay Corporation exemplify divergent super-app and QR-code acquisition strategies. Rakuten's ecosystem integration anchors consumer loyalty across payments, commerce, and loyalty programs, while PayPay's merchant acquisition dominance concentrates on aggressive terminal deployment and zero-fee campaigns for small retailers.
| Leading Market Players |
|---|
| Mizuho Group |
| Rakuten Group Inc. |
| PayPay Corporation |
| Mer Pay Co. Ltd |
| Japan Post Bank Co. Ltd. |
| KDDI Corporation |
| Sumitomo Mitsui Financial Group |
| NTT Docomo |
| Mitsubishi UFJ Financial Group |
| Others |
Value Chain & Pricing Dynamics
JIS terminal interoperability certification gates merchant hardware procurement and simultaneously stratifies acquirer pricing power across compliance tiers. METI consumption tax rebate eligibility further segments merchant acquisition costs between certified and non-certified terminal deployments.
Pricing Analysis
Long-term interchange contracts dominate merchant acquiring relationships while spot-rate QR-code settlement compresses margins for micro-merchant segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and transaction volume scale. Pricing pressure stems from zero-fee campaigns by fintech wallet providers targeting small retailers in Osaka and Fukuoka corridors. Small and medium enterprises exhibit highest price sensitivity; corporate treasury departments prioritize API reliability over per-transaction cost.
Supply Chain Analysis
Japan and Taiwan anchor NFC chip fabrication and terminal hardware assembly for FeliCa-enabled contactless infrastructure. Sony's embedded NFC modules and Taiwanese semiconductor foundries feed into domestic terminal manufacturing. Single-source vulnerability concentrates in Sony's proprietary FeliCa licensing. Distribution runs through acquirer-direct deployment and regional bank consortium channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment infrastructure in Japan represents a service-attach opportunity as merchant analytics and loyalty program integration expand faster than terminal hardware sales. Recurring software revenue layers from transaction data monetization outpace one-time terminal deployment economics.
For Market Incumbents: Compound branch network trust into API-accessible treasury services that defend corporate relationships against fintech wallet encroachment. Accelerate core banking platform modernization through regional bank consolidation pooling scarce COBOL engineering talent. Vertical integration into merchant analytics software deepens switching costs for small and medium enterprise clients.
For New Entrants and Emerging Players: Anchor in Kyushu and Hokkaido prefectures where cash transaction rates exceed fifty percent and incumbent acquirer presence remains thin. Target agricultural cooperative terminals and post office ATM networks with voice-activated payment interfaces designed for elderly accessibility. Pursue regulatory sandbox access through Fukuoka special economic zone to compress compliance timelines for crypto-asset custody licensing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across real-time transaction monitoring infrastructure mandated by Payment Services Act amendments. Long-term viability favors fintechs with existing risk management frameworks over capital-constrained startups facing segregated cold-wallet reserve requirements. Monitor Bank of Japan CBDC pilot progression as signal for settlement layer consolidation versus fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Super-App Ecosystem Integration | Rakuten's commerce-payments-loyalty collapse captures consumer lifetime value across verticals. |
| QR-Code Terminal Deployment | PayPay's zero-fee merchant acquisition campaigns displace legacy processors in micro-merchant segments. |
| Regional Bank Consolidation | Pooled capital from Shikoku and Tohoku mergers funds unified payment platform investments. |
| CBDC Layer-Two Integration | Bank of Japan wholesale experiments invite private settlement infrastructure provider competition. |
| Biometric Authentication Pilot | Convenience store palm-vein readers bypass smartphone dependency and compress terminal replacement cycles. |
Study Parameters
Initial hypotheses were tested against primary input from payment platform executives, merchant acquisition directors, regulatory affairs specialists at the Financial Services Agency, and regional bank technology officers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of METI subsidy disbursement records, JIS certification databases, and Bank of Japan payment system reports. Bottom-up merchant terminal deployment estimates triangulated against top-down transaction volume data from the Japanese Bankers Association.
Variance decomposition across payment method, transaction type, and user demographic segments structured the analytical framework throughout the forecast period. CAGRs derived from segment-level growth trajectory modeling incorporating METI cashless conversion targets and demographic adoption curve projections. Industry-specific inputs included FeliCa terminal saturation rates and QR-code literacy indices by prefecture.
Material uncertainties — Bank of Japan CBDC policy shifts, Payment Services Act enforcement intensity, regional bank consolidation pace — sit outside the modeled envelope. Forecasts reflect assumptions about subsidy program continuity and consumer behavioral persistence. Recalibration cycles align with material shifts in regulatory guidance and terminal infrastructure deployment data.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Latin America Payment Gateway Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
B2C Payment Market
Payments
China Mobile Payments Market
Payments
Payment Analytics Software Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Wearable Payments Market
Payments
Poland Payments Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
Global Real-Time Payments Market
Payments
United Kingdom Payment Market
Payments
Global Virtual Cards Market
Payments
New Zealand Payments Market
Payments
South Korea Real Time Payments Market