
 Global Wearable Payment Device Market | 2026-2036
Global Wearable Payment Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Payment Device Market Intelligence
The market's reliance on early-adopter technology enthusiasts is hardening into a broader base that includes lifestyle consumers and corporate professionals. Apple Inc. leverages its closed ecosystem to drive adoption of its payment-enabled smartwatches. Garmin Ltd. differentiates with devices tailored for fitness fanatics who require durable payment solutions during activities. Meanwhile, Visa Inc. provides the critical payment network infrastructure that underpins many of these device transactions.
Wearable payment devices are personal accessories embedding technology to execute contactless financial transactions. These items integrate components like Near Field Communication (NFC) chips and a secure element (SE) to protect user data. Smartwatches currently dominate the device type category, valued for their multifunctionality beyond payments. While NFC remains the principal payment technology, biometric authentication is an emerging segment, offering superior security for high-value transactions.
Regulatory frameworks significantly influence device design and market access. In Europe, GDPR compliance dictates stringent data protection standards for user financial information. The U.S. Federal Trade Commission (FTC) oversees data security practices, while in China, devices must adhere to specific GB standards for interoperability. Stakeholders must now navigate the trade-offs between offering frictionless user experiences and implementing more complex, multi-factor security protocols.
Market Dynamics
The central tension shaping the wearable payment device market is the pull between consumer demand for frictionless, one-tap transactions and the escalating complexity of global data security mandates. This dynamic forces manufacturers to balance seamless user experience against robust, multi-factor authentication protocols dictated by regulations like GDPR.
Growth Catalysts
- NFC Standardization:The broad standardization of Near Field Communication (NFC) technology across payment terminals and devices creates a universal infrastructure, enabling interoperability and accelerating consumer and merchant acceptance.
- Urban Transit Modernization:Major metropolitan areas in the United States and Europe are upgrading public transit systems to accept open-loop contactless payments, creating a daily use case for payment-enabled wearables.
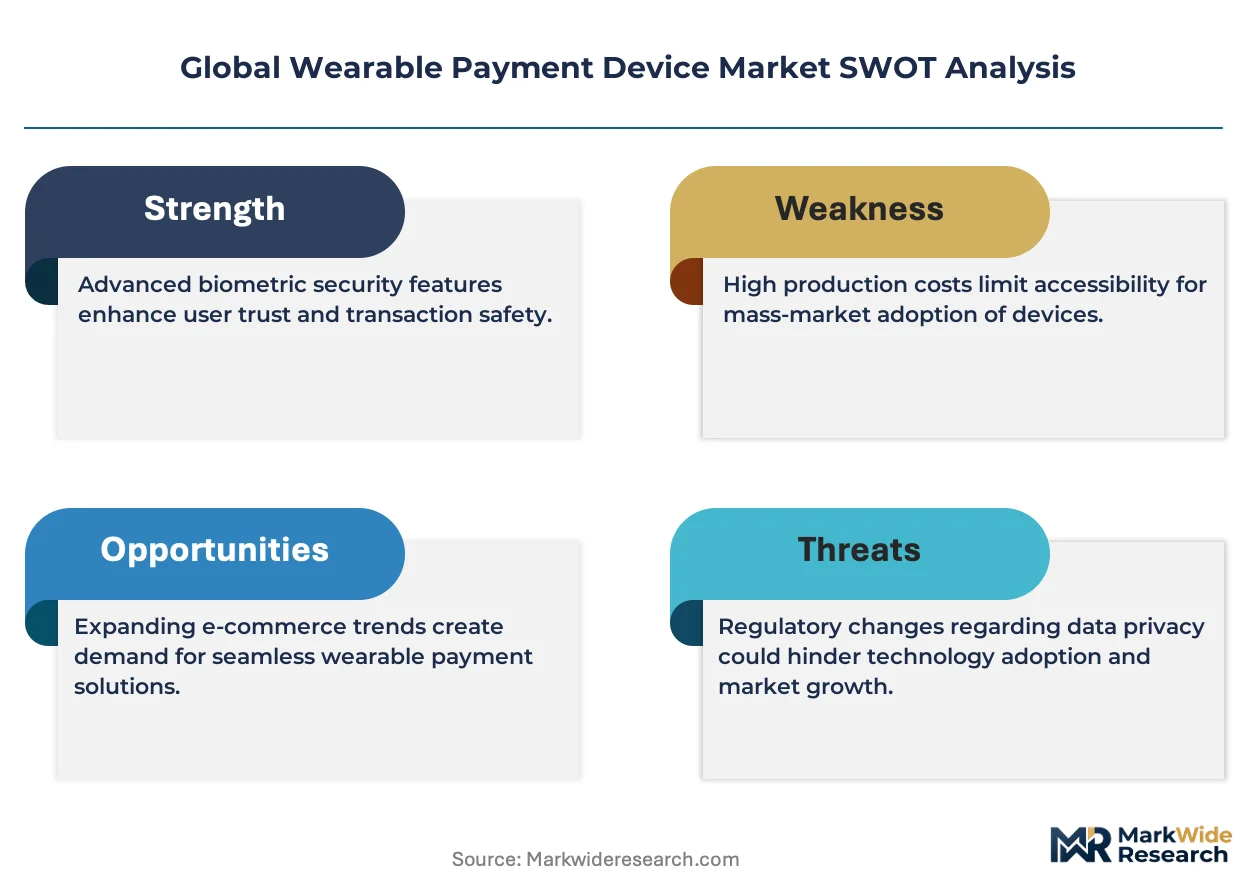
- Biometric Security Adoption:The integration of biometric sensors for authentication is enhancing user trust and encouraging the use of wearables for higher-value transactions, moving beyond small-value convenience purchases.
Market Restraints
- Device Battery Life:The constrained battery longevity of multifunctional smartwatches and other powered wearables presents a significant functional barrier, as a dead battery renders the payment feature useless.
- High Device Cost:The premium price point of feature-rich smartwatches, which dominate the market, limits accessibility for a broader consumer base, particularly in emerging economies.
- Smartphone Payment Substitution:The ubiquity of NFC-enabled smartphones provides a readily available and functionally similar alternative for contactless payments, competing directly with dedicated wearable devices.
Strategic Opportunities
- Closed-Loop Systems:Untapped opportunities exist in developing tailored wearable payment solutions for closed-loop environments like corporate campuses, theme parks, and large-scale live events, offering customized access and payment functionalities.
- Passive Wearables:Expanding into non-powered, passive wearables such as rings and jewelry embeds payment technology into fashion accessories, targeting new consumer segments that prioritize aesthetics and simplicity over multifunctionality.
- Emerging Market Leapfrogging:In regions like Southeast Asia and Latin America, wearables can address populations with high mobile connectivity but lower formal banking penetration, bypassing traditional card infrastructure.
Industry Challenges
- Interbank System Integration:Achieving seamless integration with a fragmented global landscape of thousands of individual banks, each with unique IT infrastructure and security protocols, remains a significant operational hurdle for device makers.
- Regulatory Compliance Complexity:Navigating the divergent and evolving data privacy and financial regulations, including Europe's GDPR, China's GB standards, and state-level US laws, increases development costs and time to market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Payment Device Market |
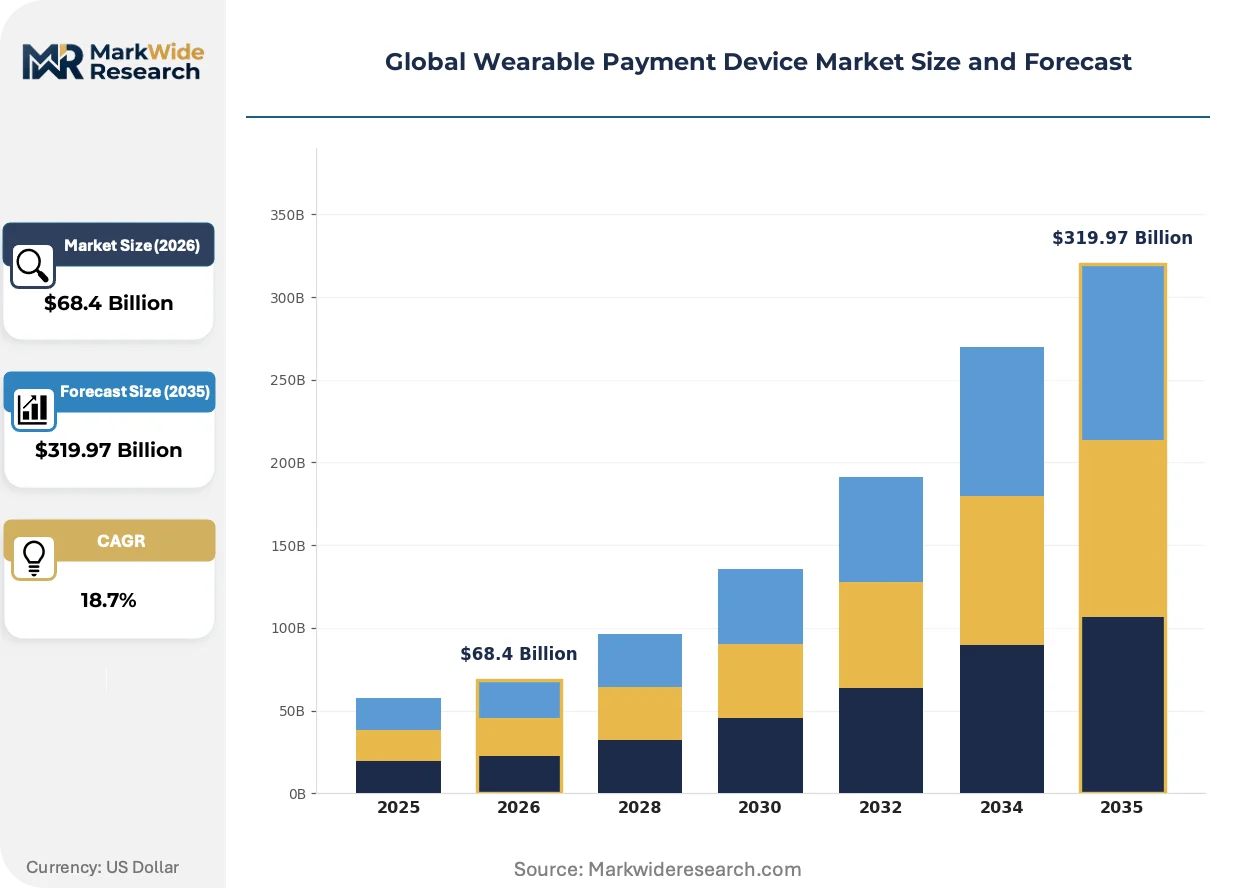
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $319.97 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatches, Fitness Bands, Payment Rings, Smart Jewelry, Wearable Patches Payment Technology: Near Field Communication, Bluetooth Low Energy, Magnetic Secure Transmission, QR Code, Biometric Authentication End User: Technology Enthusiasts, Fitness Fanatics, Corporate Professionals, Students, Lifestyle Consumers Distribution Channel: Online Retailers, Specialty Stores, Mobile Network Operators, Electronic Chains, Direct Sales |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Google LLC, Fitbit Inc., Garmin Ltd., Xiaomi Corporation, Mastercard Inc., Visa Inc., PayPal Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Payment Device Market Strategic Shifts & Innovations
Device functionality is evolving beyond simple payment execution, reshaping the market around integrated health, wellness, and identity management. This shift is driven by advancements in sensor technology and a growing consumer expectation for holistic personal devices, pushing innovation in form factor and security.
Biometric authentication provides a more secure method for transaction verification compared to traditional PINs. Lifestyle consumers and corporate professionals are the primary adopters of devices featuring this technology. This capability is integrating security directly into the hardware, making the user's unique biological traits the key to unlocking payment functions.
Europe's General Data Protection Regulation (GDPR) sets a high bar for data privacy, directly influencing device architecture. Its requirements mandate that manufacturers embed data protection measures from the initial design phase. The passive and non-powered device segment, including smart rings and bracelets, is most affected, facing challenges in demonstrating compliance within a minimalist hardware framework.
A notable consumer behavioral shift sees contactless payment capability as a standard, expected feature rather than a premium add-on. This change disrupts the value proposition of single-function payment fobs, favoring multifunctional devices like smartwatches that consolidate numerous capabilities. This demand pattern is most pronounced in developed consumer electronics markets across North America and Western Europe.
Global Wearable Payment Device Market Segmentation
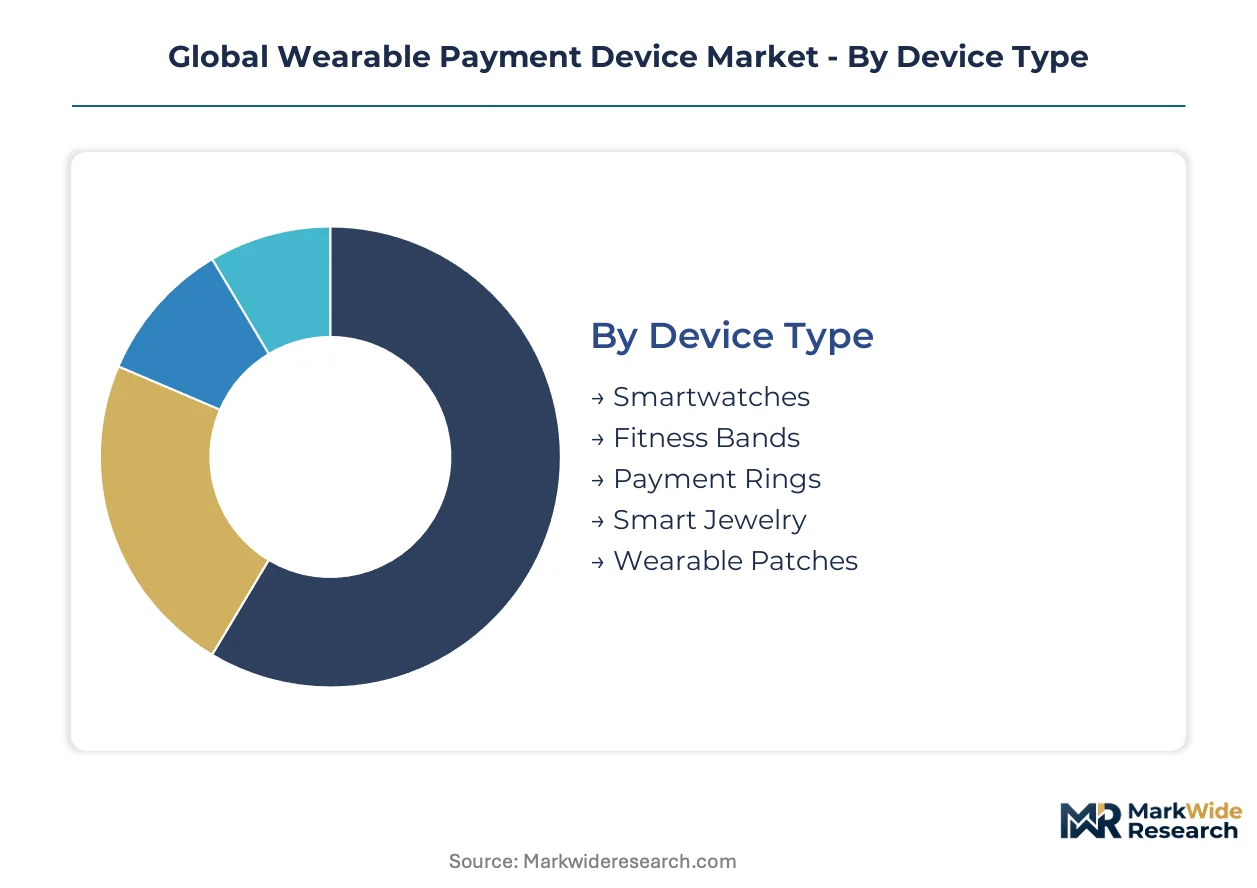
The Global Wearable Payment Device Market exhibits distinct segmentation across device types, payment technologies, end-user demographics, and distribution channels. Understanding these categories is critical for manufacturers to tailor product development and for payment providers to optimize infrastructure investments.
Device Type:
User preference for form factor drives purchasing decisions in the wearable payment device market.
- Smartwatches:These multifunctional devices integrate payment capabilities with communication, health tracking, and app ecosystems. Demand concentrates in developed urban centers like London and New York, driven by consumers seeking consolidated digital experiences.
- Payment Rings:Non-powered, passive wearables embed an NFC chip into a durable ring, offering discreet and aesthetic payment functionality. Adoption is growing among lifestyle consumers in markets such as Germany and Japan, prioritizing fashion and convenience.
- Fitness Bands:These devices primarily focus on health monitoring but increasingly include basic payment features for active users.
- Smart Jewelry:This segment encompasses necklaces, bracelets, and other accessories with embedded payment technology, appealing to fashion-conscious individuals.
- Wearable Patches:Disposable or reusable adhesive patches offer temporary payment solutions for specific events or short-term use cases.
Volume sits with Smartwatches; growth tilts toward Payment Rings.
Payment Technology:
The functional application of payment technology dictates its market penetration and security profile.
- Near Field Communication:This short-range wireless technology enables secure, contactless transactions by facilitating data exchange between devices and payment terminals. Its widespread terminal acceptance in Europe and the United States underpins its dominance.
- Biometric Authentication:This technology uses unique biological traits, such as fingerprints or heart rate, to verify user identity for transactions. Biometric integration provides enhanced security for high-value purchases, particularly in corporate and luxury retail environments.
- Bluetooth Low Energy:BLE allows for proximity-based payments and data transfer, often used for pairing devices or in specific closed-loop systems.
- Magnetic Secure Transmission:MST technology emulates a credit card's magnetic stripe, enabling payments at older, non-NFC terminals.
- QR Code:Quick Response codes facilitate payments through smartphone scanning, prevalent in markets like China for mobile wallet integrations.
Dominant technology is Near Field Communication; emergent capability is Biometric Authentication.
End User:
Target customer demographics shape product feature sets and marketing strategies.
- Lifestyle Consumers:This broad segment values convenience, aesthetics, and seamless integration into daily routines for everyday transactions. Their adoption drives market expansion in major metropolitan areas across the United States and Australia.
- Corporate Professionals:These users require secure, efficient payment solutions for business expenses and travel, often integrating with corporate expense management systems. Demand from this segment is strong in financial hubs like New York and Singapore.
- Technology Enthusiasts:Early adopters and individuals keenly interested in novel tech products often drive initial market penetration.
- Fitness Fanatics:Athletes and health-conscious individuals seek durable, water-resistant payment devices for use during physical activities.
- Students:This segment values affordable, convenient payment options for campus life and daily spending.
User engagement centers on Lifestyle Consumers; new market penetration comes from Corporate Professionals.
Distribution Channel:
Supply concentration for wearable payment devices varies significantly across different retail environments.
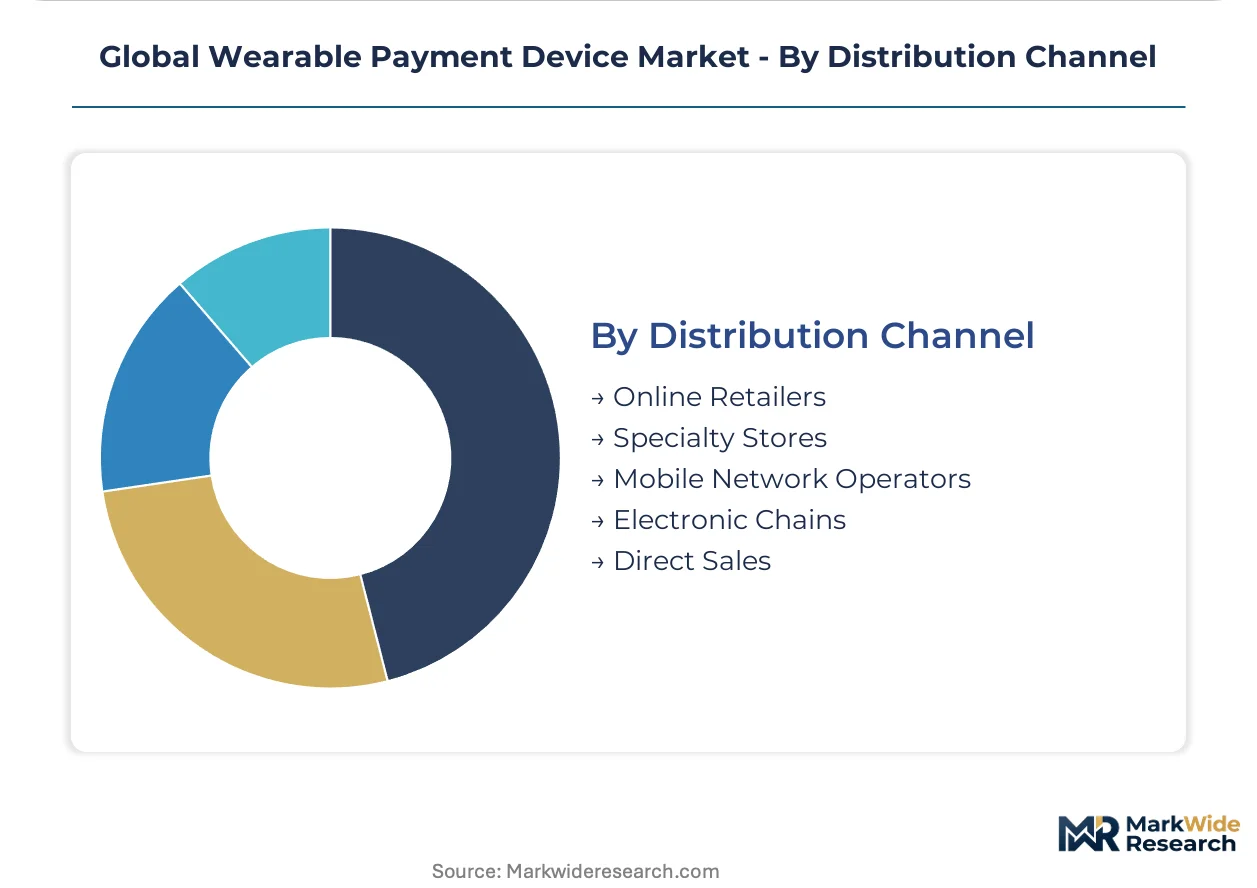
- Online Retailers:E-commerce platforms provide extensive product selection, competitive pricing, and broad geographic reach for consumers. Major online marketplaces in the United States and Germany facilitate significant sales volumes.
- Electronic Chains:Large brick-and-mortar electronics stores offer hands-on product experience and expert advice to consumers. These chains, such as those found across Europe and North America, remain crucial for product discovery.
- Specialty Stores:These outlets focus on niche products or premium brands, offering tailored customer service for high-end wearables.
- Mobile Network Operators:Telecom providers often bundle wearable devices with service plans, leveraging their existing customer base.
- Direct Sales:Manufacturers sell directly to consumers through their own websites or branded stores, maintaining brand control and customer relationships.
Consumer access primarily occurs through Online Retailers; brand control is strongest via Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of financial technology innovation within Singapore's Smart Nation initiative drives significant development in wearable payment devices. This focus on digital transformation creates a fertile ground for both demand and technological advancement. Major metropolitan areas globally serve as early adoption centers for these advanced payment solutions.
United States
Lifestyle consumers and corporate professionals in the United States drive demand for convenient, secure payment wearables. The U.S. Federal Trade Commission oversees data security practices, influencing device design and data handling. New York City's financial hub status fosters high adoption among corporate professionals seeking integrated expense solutions.
China
Rapid urbanization and robust mobile connectivity across China fuel demand for integrated wearable payment solutions. Devices must adhere to specific GB standards for interoperability and secure data exchange. Shenzhen's extensive electronics manufacturing ecosystem supports the rapid prototyping and mass production of these devices.
Germany
German lifestyle consumers increasingly adopt payment rings and smartwatches for aesthetic appeal and transaction convenience. Europe's GDPR mandates stringent data protection standards for all user financial information. Berlin's growing fintech scene contributes to innovation in secure wearable payment applications and user interfaces.
Japan
Japanese consumers seek seamless integration of payment wearables into daily routines, especially for transit and retail. Adherence to JIS standards ensures device quality and interoperability within the existing payment infrastructure. Tokyo's advanced urban transit systems are modernizing to accept open-loop contactless payments via wearable devices.
Singapore
Corporate professionals in Singapore drive demand for secure, efficient payment solutions integrated with expense management. The Monetary Authority of Singapore (MAS) sets stringent financial regulations for digital payment services. Singapore's Central Business District shows high adoption rates for wearables in corporate and luxury retail environments.
Global Wearable Payment Device Market Key Industry Players
Top-tier vendors anchor the premium smartwatch segment, while specialized manufacturers and payment network providers populate the mid-tier and infrastructure layers. Device manufacturers, payment network providers, and niche accessory developers represent key strategic archetypes. Strategic partnerships between device makers and financial institutions frequently occur. Portfolio diversification into health and wellness features also drives competitive moves.
On the premium-tier vector, Apple Inc. exemplifies a vertically integrated technology giant, leveraging its ecosystem for device adoption. Garmin Ltd. occupies a distinct position, specializing in durable payment solutions for fitness-focused consumers. Visa Inc., a global payment network provider, anchors the critical infrastructure layer, facilitating transactions across various wearable devices. These entities collectively shape the market's direction through their distinct approaches to product development and payment enablement.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Google LLC |
| Fitbit Inc. |
| Garmin Ltd. |
| Xiaomi Corporation |
| Mastercard Inc. |
| Visa Inc. |
| PayPal Holdings Inc. |
| Others |
Cost & Logistics Intelligence
The integration of advanced NFC chips and secure elements (SE) into wearable devices simultaneously reshapes manufacturing cost economics and concentrates specialized component production. This technological evolution influences the final product pricing and the geographical distribution of critical suppliers.
Pricing Analysis
Premium pricing for devices with short lead times reflects the demand for immediate access to advanced features and current designs. Pricing stratifies across premium, standard, and economy tiers, driven by brand premium from companies like Apple Inc. and the inclusion of advanced biometric security features. Pricing softness reflects intense competition from NFC-enabled smartphones, which offer a functionally similar alternative. Students typically exhibit the most price sensitivity, while corporate professionals are least sensitive due to business expense account integration and enhanced security requirements.
Supply Chain Analysis
Direct-to-consumer channels and online retailers handle significant sales volumes, while electronic chains remain crucial for product discovery. Geographic supply concentration for electronic components resides primarily in China for manufacturing and South Korea for advanced displays and chips. Raw material dependencies include specialized NFC chips, secure elements, and sophisticated biometric sensor arrays. Single-source vulnerability for advanced biometric sensors creates a significant structural risk within the supply chain. Online retailers facilitate most consumer access, whereas direct sales maintain critical brand control for manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable payment device market presents a supply-constrained landscape. Limited production capacity for specialized secure elements and advanced biometric sensors props up pricing in the premium segment.
For Market Incumbents: Cement ecosystem lock-in through deeper integration of payment features with existing health and wellness platforms. This strategy directly counters the threat of smartphone payment substitution by offering a consolidated user experience. Invest in R&D for next-generation biometric authentication, securing high-value transactions and addressing evolving regulatory shifts like Europe's GDPR. Expanding manufacturing capacity for secure elements in diverse geographies mitigates single-point failure risks.
For New Entrants and Emerging Players: Price-point gaps between premium smartwatches and basic fitness bands offer entry opportunities. Target the lifestyle consumer segment in emerging economies, particularly in Southeast Asia, with affordable passive wearables like payment rings. Leverage direct-to-consumer channels and focus on niche aesthetics and simplicity as a go-to-market angle. This approach bypasses established retail distribution networks and appeals to fashion-conscious buyers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized component manufacturers or software platform providers with strong intellectual property. Long-term viability depends on firms with robust capabilities in secure transaction processing and advanced biometric authentication. The integration of payment capabilities into broader identity management solutions is a critical signal to watch for significant market inflection. Prioritize investments in companies demonstrating strong GDPR compliance frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (Passive Wearables) | Introduces new form factors like payment rings, expanding consumer segments beyond traditional smartwatches. |
| Strategic Partnership (Financial Institutions) | Accelerates market penetration by integrating payment functionality directly with established banking networks. |
| Acquisition of Specialist Firm (Biometric Tech) | Enhances device security and differentiation through proprietary authentication methods, boosting user trust. |
| Geographic Expansion (Emerging Markets) | Captures growth in regions with high mobile connectivity but lower traditional banking penetration. |
| Platform Integration (Health & Wellness) | Consolidates device utility, making payment features a seamless part of a holistic digital experience. |
Research Approach
Document review covered regulatory filings from the U.S. Federal Trade Commission, GDPR compliance reports, industry association publications, and academic studies on NFC and biometric security. This was complemented by interviews with device manufacturers' R&D leads, payment network executives from Visa Inc., retail payment system integrators, and consumer behavior analysts. Bottom-up data from device sales and top-down market sizing were triangulated for comprehensive validation.
Historical market data was cross-referenced with expert panel input to project future trends across the analysis window. The market was modeled across device types, payment technologies, end-user demographics, and distribution channels, with an additional focus on regional regulatory compliance. Compound annual growth rates were derived from a regression analysis of adoption rates and technology diffusion curves. Urban transit modernization schedules and biometric sensor integration costs served as key forecast inputs.
Inputs from public financial disclosures and industry reports were available through the study window; gaps in real-time consumer spending data introduce uncertainty bands. Forecasts reflect assumptions regarding NFC terminal deployment and biometric authentication acceptance rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Estonia POS Terminal Market
Payments
GCC Payment Gateway Market
Payments
Poland Payments Market
Payments
US Virtual Cards Market
Payments
Digital Transfer Services Market
Payments
Finland POS Terminals Market
Payments
Argentina Payments Market
Payments
Smart Payment Market
Payments
Kenya Mobile Money Market
Payments
Canada Payments Market
Payments
Germany POS Terminal Market
Payments
North America Payment Gateway Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Outdoor Payment Terminal Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Japan Real Time Payment Market