
 Cross-Border Payment Platform Market | 2026-2036
Cross-Border Payment Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Cross-Border Payment Platform Market Insights
Multi-source API orchestration is recalibrating how platforms aggregate liquidity across correspondent networks. Wise leverages proprietary banking partnerships to sustain narrow foreign-exchange spreads across corridors. Airwallex anchors its position through embedded finance stacks that integrate treasury and expense management. dLocal specializes in local payment-method aggregation across emerging-market jurisdictions.
A cross-border payment platform is a software infrastructure that routes, clears, and settles monetary transactions across distinct national jurisdictions, typically operating through SWIFT messaging, real-time gross settlement systems, or distributed ledger protocols with sub-second confirmation latencies. Its commercial purpose centers on reducing friction, cost, and opacity in international value transfer for businesses and consumers. Cloud-based deployment models are capturing disproportionate growth capital as elasticity requirements outpace on-premises capacity planning. API-driven architectures are pulling margin pools away from hosted legacy stacks by enabling direct treasury-system integration for e-commerce firms and remittance companies.
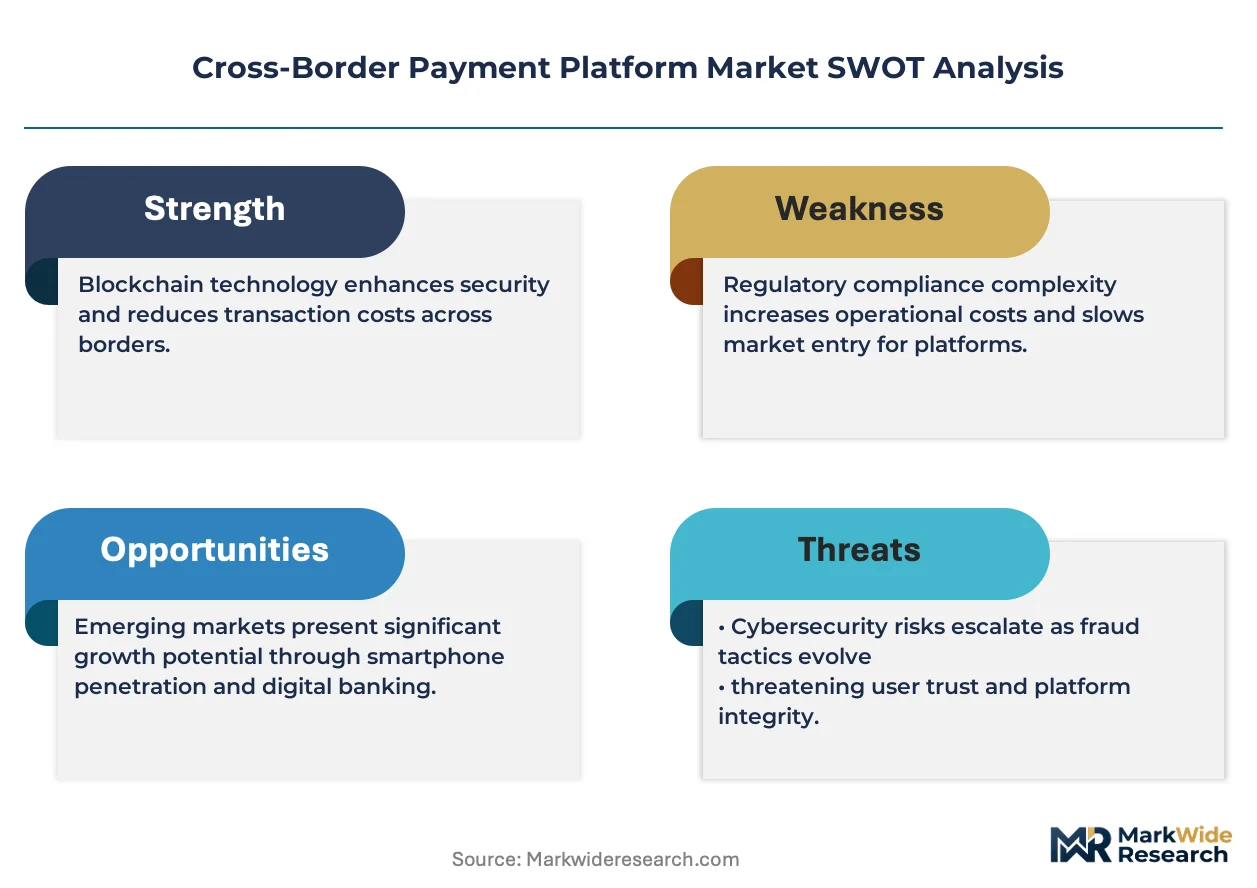
ISO 20022 standards, the EU's Digital Operational Resilience Act, and RBI's PA-PG licensing framework collectively determine messaging interoperability, operational risk baselines, and market-entry permissions for platform operators. These regulatory layers shape product-roadmap priorities across compliance automation, data-localization architecture, and capital-reserve provisioning. Stakeholders must monitor how central bank digital currency interoperability pilots reshape corridor economics and correspondent-bank dependency structures.
Market Dynamics
ISO 20022 migration timelines are compressing interoperability windows across correspondent banking networks, forcing platforms to rebuild messaging stacks before legacy MT formats sunset. This structural deadline is redistributing competitive advantage toward API-native architectures.
Growth Catalysts
- RBI's Liberalized Remittance Framework:India's outbound remittance limits now cover education, medical treatment, and investment abroad, accelerating transaction volumes through licensed payment aggregators.
- Real-Time Settlement Infrastructure:E-commerce marketplaces are mandating sub-second confirmation for cross-border payouts to sellers, pulling demand toward platforms with direct central-bank connectivity.
- Cloud-Native Treasury Stacks:Elastic compute capacity allows payment platforms to scale liquidity provisioning during corridor-specific demand spikes without stranded capital.
Market Restraints
- Correspondent Banking Concentration:Dollar-clearing access concentrates through a shrinking pool of tier-one banks, elevating counterparty risk for regional platforms.
- Capital Reserve Requirements:RBI's PA-PG licensing mandates minimum net worth thresholds that lock out bootstrapped entrants from India's remittance corridors.
- FX Volatility Exposure:Emerging-market currency pairs lack deep hedging markets, forcing platforms to absorb basis risk or pass through unpredictable spreads.
Strategic Opportunities
- CBDC Interoperability Pilots:China's digital yuan and India's digital rupee test programs create white space for bridge infrastructure between wholesale central-bank currencies.
- Embedded Finance Convergence:Payroll and expense-management platforms in Southeast Asia seek native cross-border disbursement, bypassing traditional banking relationships.
- Local Payment Method Aggregation:Brazil's Pix instant-payment network and India's UPI offer direct-rail alternatives to card networks, rewarding platforms with jurisdictional licensing depth.
Industry Challenges
- Legacy System Integration:ERP treasury modules at multinational corporates require custom middleware development, extending sales cycles and implementation risk.
- Compliance Automation Talent:Shortage of engineers with dual expertise in sanctions-screening algorithms and cloud architecture limits roadmap velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross-Border Payment Platform Market |
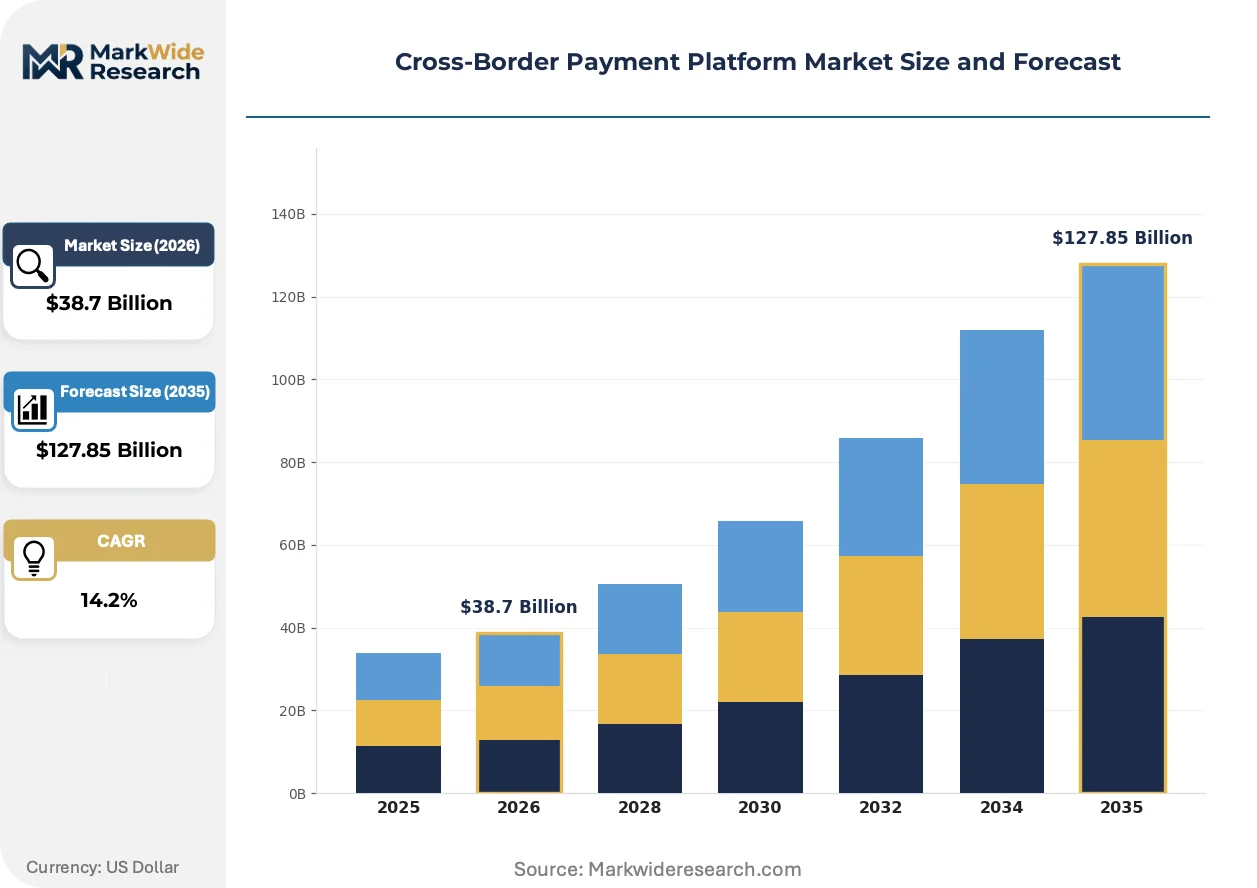
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Hosted, Cloud-Based, On-Premises, Hybrid, API-Driven Payment Method: Bank Transfers, Mobile Wallets, Cryptocurrency, Prepaid Cards, E-Money End User: Financial Institutions, E-Commerce Firms, Remittance Companies, Small Businesses, Freelancers Integration Model: Direct Integration, Partner Network, Aggregator, White Label, SaaS |
| Companies Covered | Payoneer, Wise, Airwallex, dLocal, Thunes, Nium, Banking Circle, TransferMate, Ripple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross-Border Payment Platform Market Trends and Innovations
Distributed ledger protocols are converging with traditional correspondent networks, creating hybrid settlement layers that compress confirmation latency without abandoning regulatory familiarity. This fusion is redrawing technical architecture choices across the platform landscape.
ISO 20022 is converging with API-first messaging standards, enabling richer data payloads in cross-border payment instructions. Tier-one banks in the EU and Singapore are migrating core systems ahead of SWIFT's November 2025 deadline. The structural consequence is compressing interoperability testing windows for platforms serving corporate treasury clients.
The EU's Digital Operational Resilience Act mandates incident reporting thresholds and third-party risk management for payment service providers. Platforms must map critical dependencies and demonstrate continuity planning to national competent authorities. Neobanks and remittance specialists with lean compliance functions face disproportionate adaptation costs.
Corporate treasury teams are unbundling payment execution from relationship banking, selecting platforms based on corridor-specific FX transparency rather than incumbent ties. This behavioral shift displaces bundled pricing models. Manufacturing exporters in Germany and pharmaceutical distributors in Switzerland are most visible in this migration pattern.
Cross-Border Payment Platform Market Segmentation
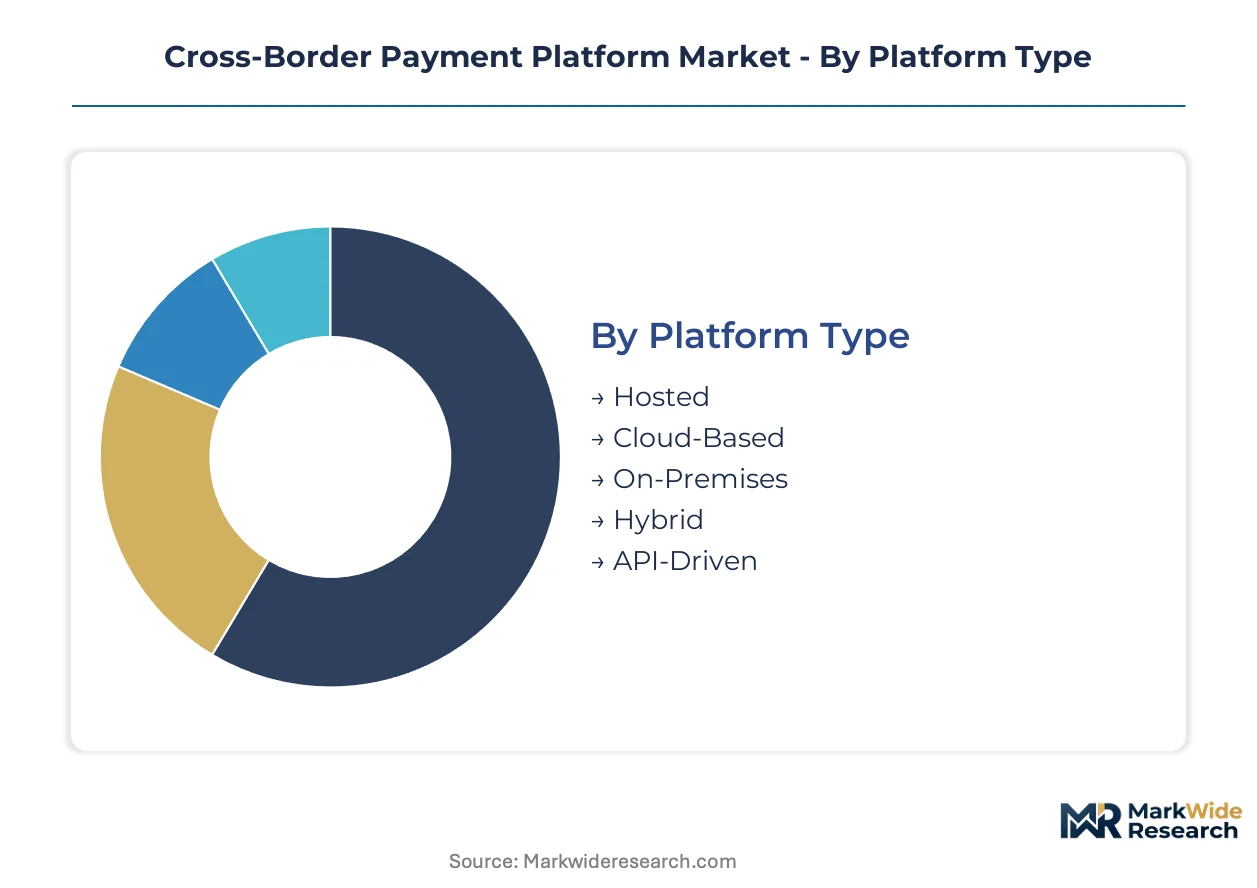
Payment platforms segment across deployment architecture, payment rails, user profiles, and integration depth. Each axis shapes capital requirements, compliance burdens, and competitive moats differently. Understanding these divisions clarifies where margin pools concentrate and which configurations attract growth capital.
Platform Type:
Deployment architecture determines scalability, regulatory exposure, and total cost of ownership for operators across corridors.
- Cloud-Based:Elastic compute capacity enables platforms to provision liquidity dynamically during corridor-specific demand spikes without stranded infrastructure capital. E-commerce marketplaces in India and Southeast Asia mandate this architecture for sub-second settlement guarantees.
- API-Driven:Direct treasury-system integration allows e-commerce firms and remittance companies to bypass hosted legacy stacks entirely. RBI's PA-PG licensing framework accelerates adoption among licensed payment aggregators seeking real-time connectivity.
- Hosted:Third-party managed infrastructure reduces operational overhead for smaller remittance specialists with limited engineering resources.
- On-Premises:Capital-intensive deployments persist among tier-one banks with legacy core systems requiring localized data sovereignty.
- Hybrid:Mixed architectures serve multinational corporates with bifurcated compliance requirements across jurisdictions.
Cloud-Based leads on scale; API-Driven leads on momentum.
Payment Method:
Settlement rail selection shapes speed, cost structure, and addressable user base across emerging and developed corridors.
- Mobile Wallets:Proprietary closed-loop systems dominate retail remittance corridors into sub-Saharan Africa and South Asia. Kenya's M-Pesa interoperability with international platforms illustrates how wallet-to-wallet settlement compresses friction.
- Bank Transfers:SWIFT MT and ISO 20022 messaging remain the default for high-value B2B disbursements. Corporate treasury teams in Germany and Switzerland unbundle execution from relationship banking based on corridor-specific transparency.
- Cryptocurrency:Distributed ledger protocols attract platforms serving freelancers and gig workers seeking settlement outside correspondent banking networks.
- E-Money:Stored-value instruments facilitate micro-transactions where traditional account penetration remains limited.
- Prepaid Cards:Plastic and virtual card issuance supports traveler and migrant worker segments with immediate spend capability.
Bank Transfers anchor transaction value; Mobile Wallets expand most quickly in user adoption.
End User:
Customer category determines feature requirements, pricing tolerance, and regulatory treatment under national licensing frameworks.
- E-Commerce Firms:Marketplace operators require embedded treasury stacks with multi-currency pooling and automated reconciliation. India's liberalized remittance frameworks accelerate platform adoption for cross-border seller payouts.
- Financial Institutions:Banks and neobanks seek white-label infrastructure to extend correspondent reach without direct bilateral relationships. EU's Digital Operational Resilience Act mandates incident reporting thresholds that reshape vendor selection criteria.
- Remittance Companies:Licensed operators prioritize corridor density and FX spread competitiveness over feature breadth.
- Small Businesses:Exporters and importers demand simplified onboarding and transparent pricing without enterprise implementation cycles.
- Freelancers:Individual contractors favor platforms with local payment method aggregation and minimal KYC friction.
Financial Institutions generate highest revenue per seat; E-Commerce Firms drive steepest expansion trajectory.
Integration Model:
Go-to-market configuration determines speed of deployment, margin retention, and customer lock-in mechanics.
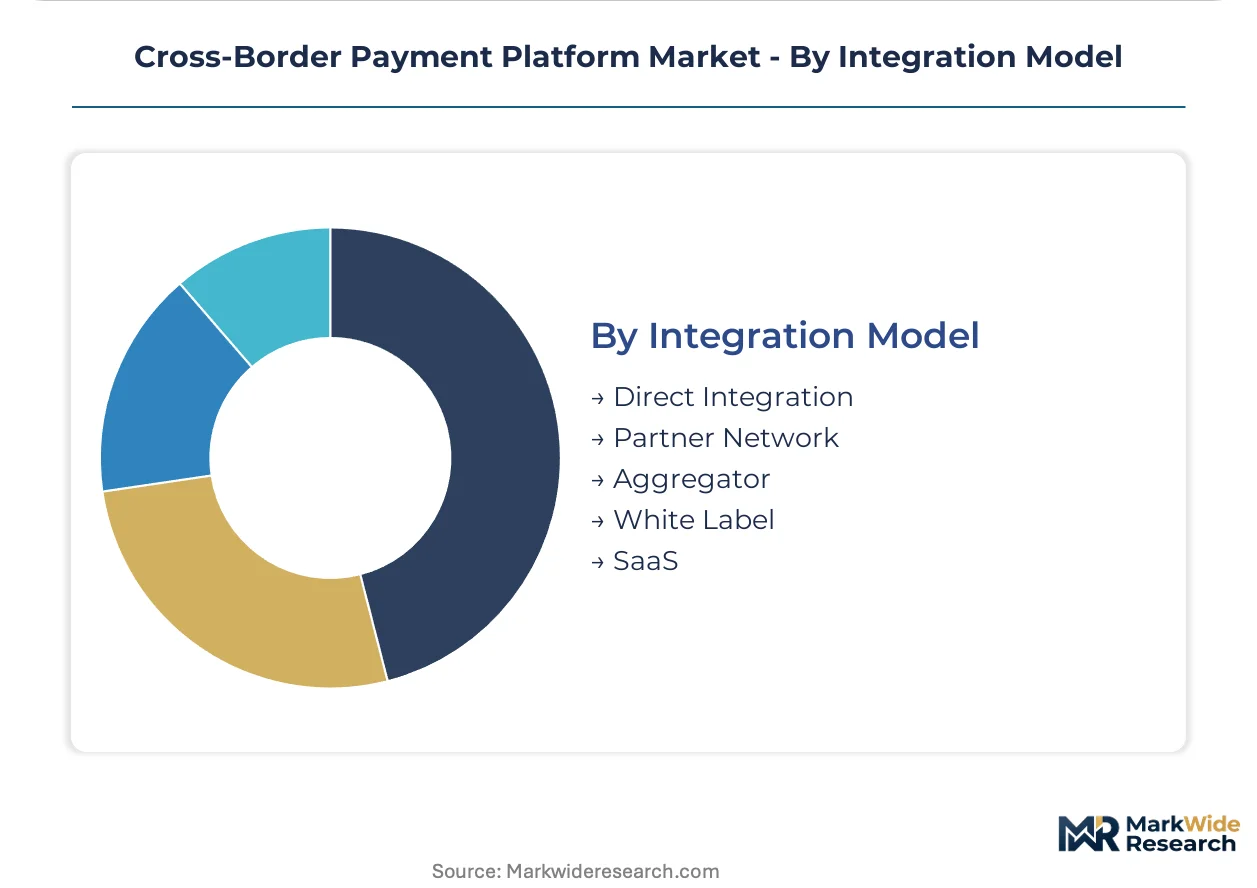
- SaaS:Subscription-based platform access enables rapid scaling without bespoke development. Cloud-native providers in Singapore and the UAE target mid-market remittance operators with standardized compliance modules.
- White Label:Fully branded deployments allow banks to launch cross-border services without core system overhaul. RBI's net worth thresholds for PA-PG licensing push regional banks toward this model.
- Direct Integration:Custom API connections serve largest e-commerce marketplaces with unique workflow requirements.
- Partner Network:Intermediary relationships extend reach into jurisdictions where direct licensing remains capital-prohibitive.
- Aggregator:Consolidated access to multiple underlying rails optimizes routing for cost and speed.
SaaS captures widest addressable market; White Label gains share fastest among incumbent banks modernizing legacy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's fintech corridor anchors cross-border payment infrastructure development, with regulatory sandboxes and central bank connectivity pilots attracting platform operators seeking Asia-Pacific licensing depth.
United States
E-commerce marketplace sellers and freelance platforms drive platform adoption for multi-currency disbursement. The Federal Reserve's FedNow instant payment network creates interoperability pressure for real-time cross-border settlement. New York's financial district hosts correspondent banking relationships that tier-one platforms leverage for dollar-clearing access.
Germany
Manufacturing exporters unbundle payment execution from relationship banking based on corridor-specific FX transparency. The EU's Digital Operational Resilience Act mandates incident reporting thresholds that reshape vendor selection for corporate treasury teams. Frankfurt's banking cluster concentrates white-label infrastructure demand from regional banks modernizing legacy systems.
India
Liberalized remittance frameworks accelerate transaction volumes through licensed payment aggregators serving education and medical treatment corridors. RBI's PA-PG licensing mandates minimum net worth thresholds that reshape competitive entry. Mumbai's financial district anchors payment aggregator headquarters seeking direct central bank connectivity.
Brazil
Local payment method aggregation rewards platforms with jurisdictional licensing depth, particularly Pix instant-payment network integration. The central bank's open finance regulations mandate API standards that compress interoperability testing windows. São Paulo's fintech cluster concentrates platform engineering talent and regulatory relationships.
United Arab Emirates
Remittance corridors into South Asia and sub-Saharan Africa drive demand for mobile wallet interoperability and real-time settlement. The central bank's stored value facility licensing creates structured pathways for payment platform market entry. Dubai's financial free zones host regional headquarters for operators targeting Middle East-Africa corridors.
Cross-Border Payment Platform Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded finance convergence and local payment rail integration. The vendor base stratifies across three tiers: API-native platforms with direct central bank connectivity, white-label infrastructure providers serving incumbent banks, and corridor-specific specialists aggregating local payment methods. Two strategic archetypes dominate: liquidity aggregators sustaining narrow FX spreads through proprietary banking partnerships, and jurisdictional specialists capturing emerging-market payment rail depth. Competitive moves concentrate on M&A for licensing footprint and strategic partnerships for correspondent banking access.
Among API-native specialists, Wise and Airwallex exemplify architectures built for direct treasury-system integration, while dLocal occupies a position within the jurisdictional-specialist tier focused on emerging-market payment method aggregation. These three entities represent distinct competitive vectors: real-time settlement infrastructure, embedded finance stack convergence, and local rail licensing depth respectively.
| Leading Market Players |
|---|
| Payoneer |
| Wise |
| Airwallex |
| dLocal |
| Thunes |
| Nium |
| Banking Circle |
| TransferMate |
| Ripple |
| Others |
Pricing and Supply Chain Analysis
SWIFT messaging fee benchmarks and correspondent banking network access costs cascade through platform pricing tiers, compressing margins for regional operators while API-native architectures capture premium spreads through direct central-bank connectivity.
Pricing Analysis
Input-cost pass-through from dollar-clearing access fees and FX hedging premiums shapes platform pricing structures. SaaS-tiered subscription models dominate, with price differentiation driven by corridor density and ISO 20022 compliance certification. Pricing pressure stems from RBI's net worth thresholds locking out smaller entrants from India's high-volume corridors. E-commerce firms exhibit highest price sensitivity due to thin seller margins, while multinational corporates prioritize FX transparency over absolute cost.
Supply Chain Analysis
Single-source vulnerability sits with tier-one correspondent banks in New York, London, and Singapore controlling dollar-clearing access. The supply chain draws from cloud infrastructure providers, banking partnership networks, and local payment rail aggregators in Brazil and India. Regulatory restriction risk concentrates around RBI's PA-PG licensing and EU's Digital Operational Resilience Act compliance windows. Distribution runs through API-first direct integration and white-label banking partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-border payment platforms constitute a late-cycle quality story as corporate treasury teams unbundle execution from relationship banking, demanding premium specifications around real-time settlement and corridor-specific FX transparency.
For Market Incumbents: Hedge correspondent banking concentration risk by diversifying dollar-clearing relationships across Singapore and Dubai financial centers. Invest in ISO 20022 messaging stack modernization ahead of legacy format sunsets to defend against API-native challengers.
For New Entrants and Emerging Players: Launch via embedded finance partnerships with Southeast Asian payroll platforms seeking native cross-border disbursement. Target Brazil's Pix instant-payment integration and India's UPI corridor density as the most penetrable white-space segments.
For Investors and Strategic Acquirers: Asymmetric upside sits with jurisdictional specialists possessing deep local payment rail licensing in emerging markets. Long-term viability favors platforms with direct central bank connectivity and CBDC interoperability pilots. Monitor FedNow instant payment network expansion as the critical inflection signal for real-time cross-border settlement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Stack Migration | SWIFT's messaging deadline forces platform rebuilds before legacy MT format sunsets. |
| CBDC Bridge Infrastructure | China's digital yuan and India's digital rupee pilots create interoperability white space. |
| Local Payment Rail Licensing | Brazil's Pix and India's UPI integration rewards platforms with jurisdictional depth. |
| Correspondent Banking Diversification | Dollar-clearing concentration through shrinking tier-one pools elevates counterparty risk. |
| Embedded Finance Convergence | Southeast Asian payroll platforms seek native cross-border disbursement capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research incorporated payment platform CTOs, RBI-licensed PA-PG operators, corporate treasury directors at manufacturing exporters, and correspondent banking relationship managers. Secondary validation drew from SWIFT messaging volume disclosures, RBI regulatory circulars, EU Digital Operational Resilience Act implementation guidance, and cloud infrastructure provider capex reports. Bottom-up corridor volume estimates and top-down market sizing triangulated across deployment architecture segments.
Comparable historical periods anchored the projection horizon across cloud-native and on-premises deployment trajectories. The analytical framework modeled platform type, payment method, end-user category, and integration depth as core segmentation dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating real-time settlement infrastructure buildouts and ISO 20022 migration timelines. Forecast inputs included e-commerce marketplace seller payout volumes and central bank digital currency pilot expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt correspondent banking de-risking or accelerated CBDC interoperability breakthroughs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
UAE POS Terminal Market
Payments
Argentina Payments Market
Payments
Payment Security Market
Payments
Norway Mobile Payments Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Denmark POS Terminals Market
Payments
Germany Payments Market
Payments
Latin America Payment Gateway Market
Payments
Proximity Mobile Payment Market
Payments
Spain Payment Gateway Market
Payments
North America Real Time Payment Market
Payments
LAMEA Payment Gateway Market
Payments
Sweden POS Terminals Market
Payments
United States Electronic Toll Collection Market
Payments
Digital Money Transfer Market