
 Mobile Point of Sale Devices (Mpos) Market | 2026-2036
Mobile Point of Sale Devices (Mpos) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Point of Sale Devices (Mpos) Market Foresight
Small and mid-sized restaurants is rotating toward cloud-based mPOS systems as legacy countertop terminals lose share among price-sensitive operators. Square, Inc. leverages integrated software-hardware ecosystems to anchor its position in quick-service environments. Toast, Inc. specializes in restaurant-specific workflow tools that differentiate its tablet POS offering from generic competitors.
Mobile Point of Sale Devices are portable payment terminals that integrate card-reading hardware with wireless connectivity modules, typically supporting EMV chip, NFC contactless, and magnetic stripe protocols to process transactions outside fixed locations. Their primary commercial purpose is enabling merchants to accept card and digital payments at variable points of customer interaction, from curbside to pop-up venues. Tablet POS systems command the richest margin pools due to bundled software subscription models, while mobile application segments grow fastest as smartphone-tethered solutions displace dedicated hardware among micro-merchants. Bluetooth connectivity dominates low-volume retail use cases, though cellular-enabled terminals expand addressable markets for food trucks and event coordinators operating beyond Wi-Fi range.
FCC certification requirements govern wireless transmission standards for mPOS hardware sold in the United States, while PCI DSS mandates shape encryption and tokenization protocols across all connectivity tiers. EMA and national banking regulators in Europe enforce PSD2 strong-customer-authentication rules that redirect hardware design priorities toward biometric-ready terminals. Stakeholders must monitor evolving central bank digital currency pilots, as government-issued payment rails could force firmware architecture decisions before mass deployment timelines clarify.
Market Dynamics
PCI Security Standards Council contactless payment mandates are forcing hardware refresh cycles across merchant networks, compressing replacement timelines for legacy countertop terminals and accelerating cloud-native mPOS deployment among price-sensitive operators.
Growth Catalysts
- Contactless Mandates:PCI DSS contactless acceptance requirements are compelling terminal upgrades across quick-service restaurants and retail chains.
- Gig-Economy Expansion:Food delivery drivers, event vendors, and mobile service providers require untethered payment acceptance beyond fixed locations.
- Bluetooth Low Energy:BLE-enabled mPOS hardware reduces power consumption and hardware costs for micro-merchants processing low transaction volumes.
Market Restraints
- Semiconductor Supply Concentration:NFC controller and secure element fabrication concentrates in East Asian foundries, exposing terminal manufacturers to single-source risk.
- FCC Certification Timelines:Radio frequency equipment authorization processes extend hardware launch windows by 4-8 months for cellular-enabled devices.
- Smartphone Tethering:Soft-POS applications on consumer smartphones are eroding demand for dedicated card-reading hardware among sole proprietors.
Strategic Opportunities
- Central Bank Digital Currency Pilots:Federal Reserve and European Central Bank CBDC test programs will require firmware-ready terminals before mass deployment clarifies.
- Biometric Authentication Convergence:Fingerprint and facial recognition modules integrated with EMV kernels enable PSD2-compliant strong customer authentication.
- Vertical Software Bundling:Restaurant management platforms and inventory systems are embedding payment acceptance into unified workflow tools.
Industry Challenges
- EMV Kernel Certification:Payment network compliance testing for chip card acceptance creates 6-12 month product launch delays.
- Legacy System Integration:Cloud-native mPOS platforms face friction connecting to on-premise ERP and accounting systems at mid-sized merchants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Point of Sale Devices (Mpos) Market |
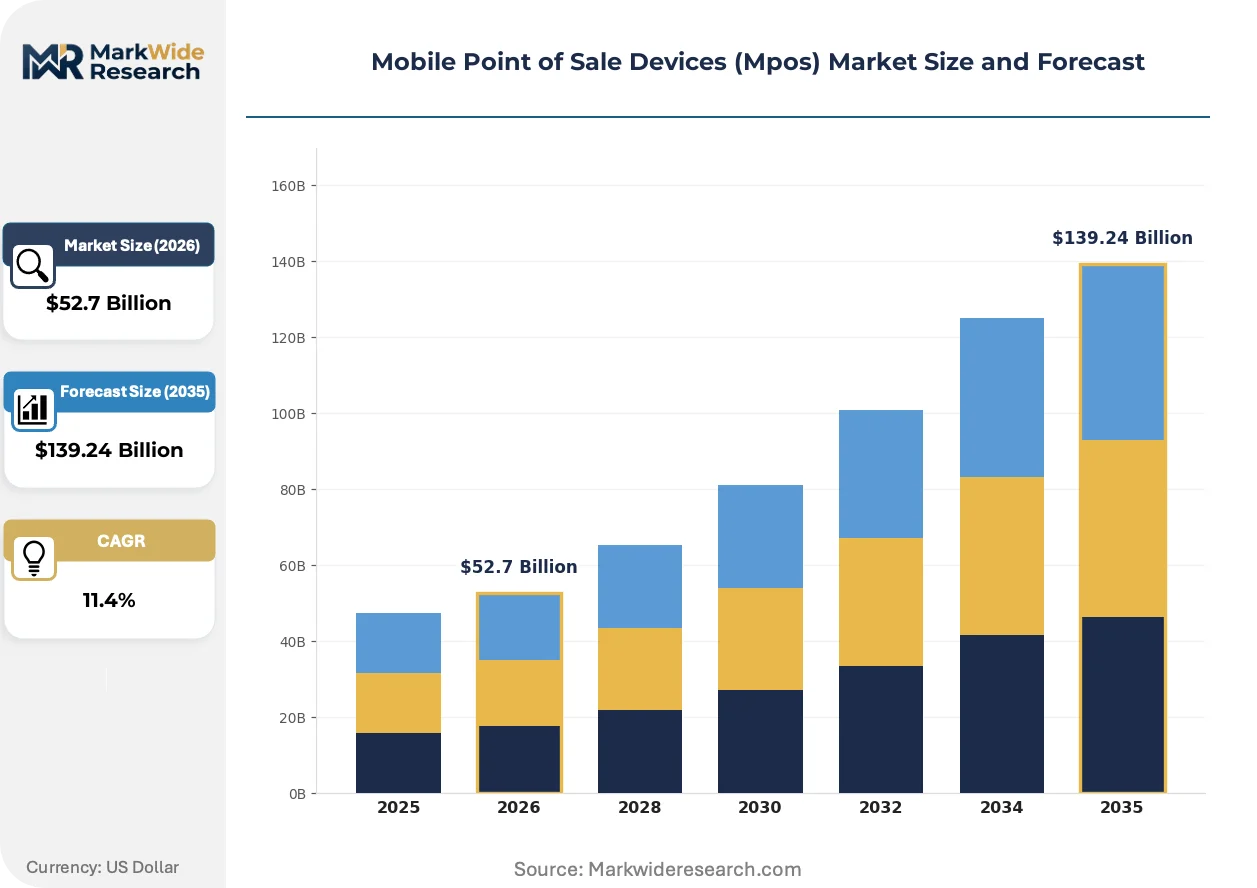
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Card Reader, POS Terminal, Tablet POS, Mobile Application End User: Retailers, Restaurants, Service Providers, Event Coordinators Connectivity: Bluetooth, Wi-Fi, Cellular, USB Deployment Model: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | VeriFone, Inc., Ingenico Group, PAX Technology, Square, Inc., PayPal Holdings, Inc., Toast, Inc., Lightspeed Commerce Inc., Oracle Corporation, Zebra Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Point of Sale Devices (Mpos) Market Shifts & Advancements
Hardware-software unbundling and connectivity module miniaturization are compressing terminal form factors while expanding addressable use cases beyond traditional retail environments.
Soft-POS applications running on standard smartphones with NFC antennas are supplanting dedicated hardware among micro-merchants and pop-up vendors. Street market operators and independent contractors adopt smartphone-tethered solutions within weeks rather than months. This shift is compressing average selling prices and forcing dedicated terminal manufacturers toward higher-margin integrated software subscriptions.
PSD2 strong customer authentication rules from EMA and national banking regulators are redirecting hardware design priorities toward biometric-ready terminals. European merchants must support two-factor authentication for remote transactions above threshold limits. Tablet POS systems with integrated fingerprint sensors are capturing premium positioning in Germany and France ahead of enforcement deadlines.
Merchant procurement of payment hardware is fragmenting across multiple channels. Independent software vendors and vertical SaaS platforms are displacing traditional distributor networks as primary purchase pathways. United States quick-service restaurants now source mPOS primarily through restaurant management software providers rather than payment processor direct sales forces.
Mobile Point of Sale Devices (Mpos) Market Segmentation
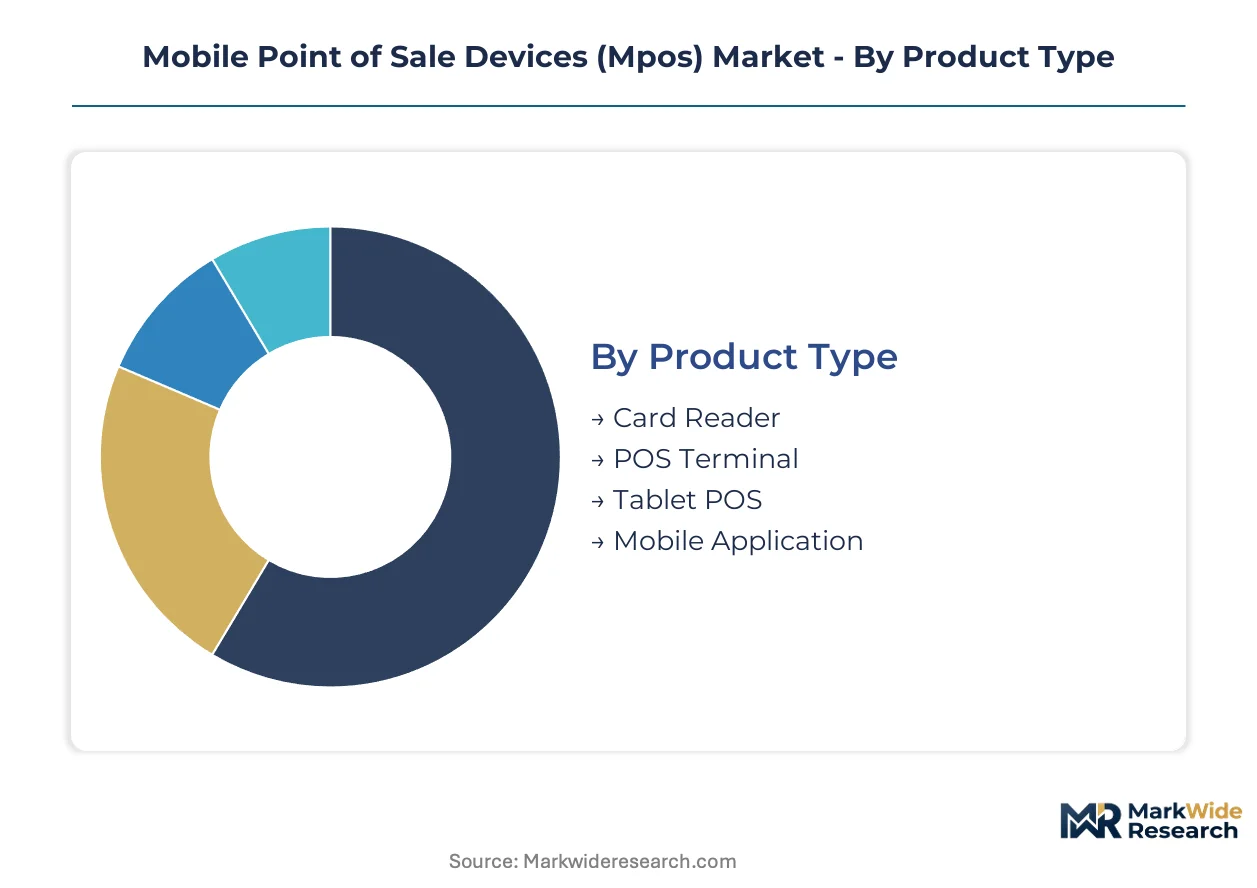
mPOS hardware and software configurations fragment sharply across merchant scale, transaction environment, and technical integration requirements. Each segmentation axis reveals distinct procurement patterns and margin architectures that shape vendor strategy and competitive positioning.
Product Type:
Domestic demand concentrates in integrated terminal systems, while export-led growth flows through modular components and smartphone-tethered solutions targeting emerging merchant segments.
- Card Reader:Compact magnetic stripe and EMV chip peripherals pair with consumer smartphones via audio jack or Bluetooth interfaces. Street vendors and independent contractors in the United States favor these units for sub-$50 entry pricing and zero subscription requirements.
- POS Terminal:Dedicated countertop and portable units integrate secure element chips with NFC antennas and receipt printers. Quick-service restaurants in dense urban corridors drive replacement cycles as PCI DSS contactless mandates compress hardware lifespans.
- Tablet POS:Bundled software-hardware ecosystems anchor premium positioning through recurring subscription revenue. Restaurant management platforms embed payment acceptance into unified workflow tools, capturing margin pools unavailable to standalone hardware vendors.
- Mobile Application:Soft-POS solutions leverage existing smartphone NFC antennas, eliminating dedicated hardware procurement entirely. Micro-merchants and pop-up vendors adopt these applications within days, compressing average selling prices across the hardware base.
Tablet POS commands the established base. The steepest expansion runs through Mobile Application.
End User:
Merchant procurement channels diverge sharply by vertical, with restaurant operators sourcing through software platforms while retailers maintain direct processor relationships.
- Retailers:Brick-and-mortar chains and independent shops demand EMV-compliant terminals with inventory integration. FCC-certified cellular units expand addressable markets for merchants operating beyond fixed Wi-Fi infrastructure.
- Restaurants:Tableside payment acceptance and kitchen display integration dominate technical requirements. Cloud-native mPOS platforms face friction connecting to on-premise ERP systems at mid-sized operators, slowing deployment timelines.
- Service Providers:Mobile contractors and field technicians require untethered payment acceptance at variable customer locations. Bluetooth Low Energy hardware reduces power consumption for low-volume transaction environments.
- Event Coordinators:Temporary venues and pop-up installations prioritize rapid deployment and cellular connectivity. Food trucks and festival vendors operate beyond reliable Wi-Fi range, demanding autonomous transaction processing.
Restaurants anchor current procurement volume. Service Providers are climbing the fastest as gig-economy expansion accelerates hardware refresh cycles.
Connectivity:
Module selection directly determines addressable use case breadth and regulatory certification burden, with wireless protocols commanding premium positioning against tethered alternatives.
- Bluetooth:Low-energy protocols minimize power draw for battery-operated peripherals. Micro-merchants processing intermittent transaction volumes favor these cost-optimized configurations.
- Wi-Fi:Fixed-location merchants leverage existing network infrastructure to avoid cellular data costs. Retail chains standardize on Wi-Fi-dependent terminals to control recurring operational expenses.
- Cellular:Autonomous connectivity modules expand addressable markets for mobile merchants operating beyond Wi-Fi range. FCC certification timelines extend hardware launch windows by 4-8 months, concentrating supply among established manufacturers.
- USB:Tethered connections persist in high-volume countertop environments requiring continuous power and data stability. Legacy system integration demands maintain residual demand for wired configurations.
Cellular commands the established base. Bluetooth is gaining share fastest as hardware miniaturization reduces power consumption and unit costs.
Deployment Model:
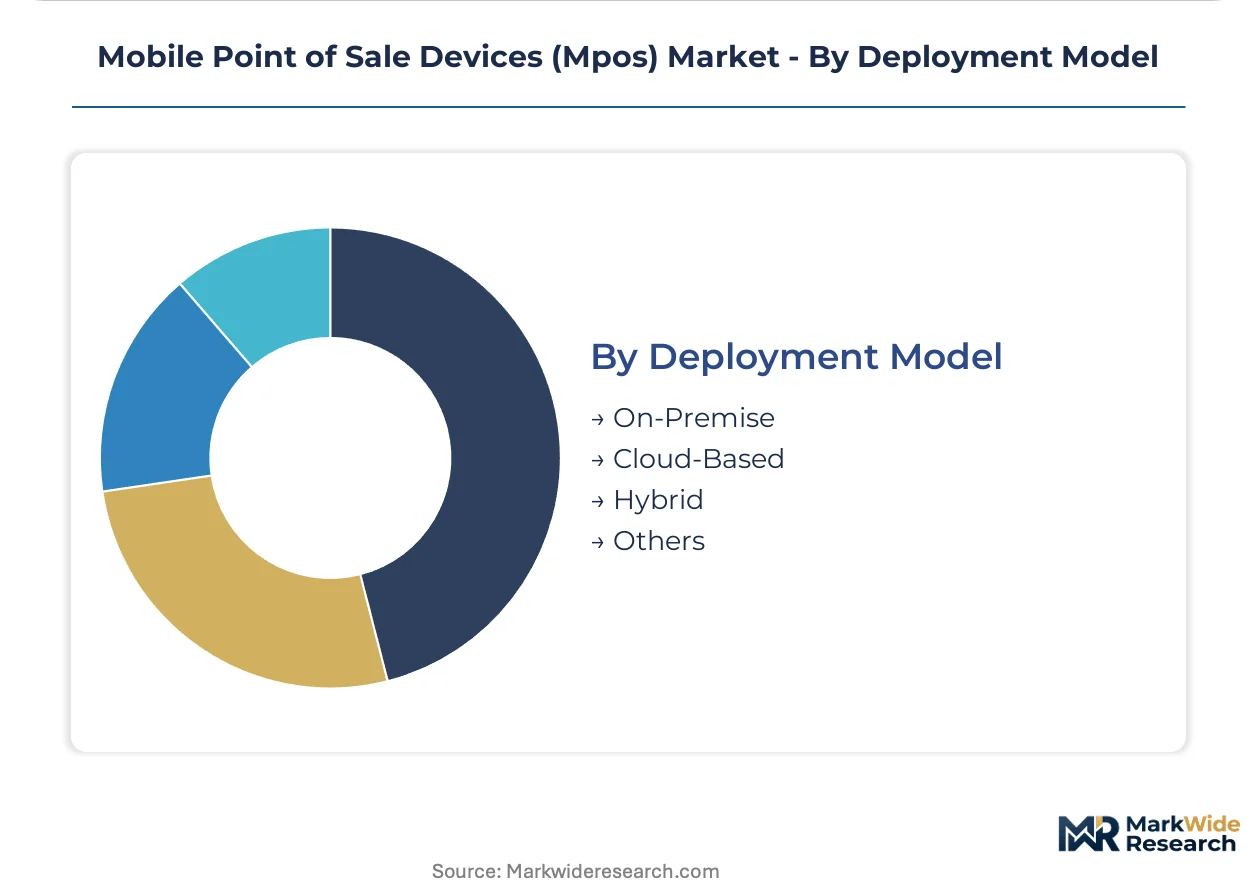
Cloud migration intensity varies by merchant IT maturity, with hybrid architectures bridging legacy on-premise investments and modern subscription economics.
- On-Premise:Local server installations persist at mid-sized merchants with substantial sunk costs in legacy ERP and accounting systems. Integration friction slows cloud-native platform adoption despite superior feature velocity.
- Cloud-Based:Software-as-a-Service delivery enables continuous feature updates and remote device management. Price-sensitive operators rotate toward these solutions as legacy countertop terminals lose share.
- Hybrid:Mixed architectures preserve on-premise transaction processing while enabling cloud analytics and backup. Merchants with intermittent connectivity requirements favor these configurations for operational resilience.
- Others:Edge-computing and containerized deployments serve specialized use cases requiring localized data sovereignty or ultra-low latency processing.
On-Premise retains the installed base. Cloud-Based solutions show the steepest expansion trajectory as subscription economics displace capital expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States payment processing infrastructure, anchored by dense fiber-optic networks and 5G cellular corridors along the Interstate highway system, underwrites the geography's central role in mPOS hardware deployment and merchant service innovation.
United States
Dense urban merchant networks and gig-economy service providers drive hardware refresh cycles across quick-service restaurants and mobile vendors. FCC certification requirements govern wireless transmission standards for mPOS hardware sold nationwide. Silicon Valley and Austin technology clusters host firmware development centers where EMV kernel integration accelerates product launch timelines.
Germany
Mid-sized retail chains and restaurant operators demand PCI DSS-compliant terminals with strong customer authentication capabilities. EMA and national banking regulators enforce PSD2 rules redirecting hardware design toward biometric-ready configurations. The Munich-Stuttgart industrial corridor concentrates terminal manufacturing and payment software engineering talent.
United Kingdom
Contactless payment penetration among street vendors and pop-up merchants creates sustained demand for smartphone-tethered solutions. FCA oversight shapes encryption and tokenization protocols for wireless payment terminals. London's fintech cluster drives cloud-native platform development and merchant acquisition technology.
China
Massive mobile payment user bases and QR-code infrastructure dominance create hybrid demand for NFC-enabled terminals among international-facing merchants. MIIT certification requirements and GB standards govern radio frequency equipment authorization. Shenzhen hardware manufacturing ecosystems compress production costs for Bluetooth and cellular connectivity modules.
India
Micro-merchant digitization campaigns and UPI payment rail expansion accelerate smartphone-based acceptance solutions among unbanked vendors. RBI regulations and BIS certification standards shape terminal security requirements. Bangalore and Mumbai technology corridors host software development centers for tablet POS and mobile application platforms.
Mobile Point of Sale Devices (Mpos) Market Competitive Landscape
Concentration sits with integrated software-hardware ecosystem providers and specialized vertical platform developers. The vendor base spans three distinct tiers: global payment terminal manufacturers with secure element fabrication capabilities, cloud-native SaaS platforms bundling payment acceptance into industry-specific workflows, and smartphone-tethered application developers eroding dedicated hardware demand. Dominant competitive moves include vertical software bundling to capture recurring subscription revenue and strategic partnerships between hardware OEMs and restaurant management platforms.
Within the integrated ecosystem tier, Square, Inc. and Toast, Inc. exemplify divergent specialization strategies. Square anchors positioning in quick-service environments through unified hardware-software stacks, while Toast occupies a restaurant-specific workflow niche that differentiates its tablet POS offering from generic competitors. Among legacy terminal manufacturers, VeriFone, Inc. and Ingenico Group represent established secure element and EMV kernel certification capabilities that sustain presence in high-volume retail chains.
| Leading Market Players |
|---|
| VeriFone, Inc. |
| Ingenico Group |
| PAX Technology |
| Square, Inc. |
| PayPal Holdings, Inc. |
| Toast, Inc. |
| Lightspeed Commerce Inc. |
| Oracle Corporation |
| Zebra Technologies Corporation |
| Others |
Supply & Pricing Matrix
PCI DSS certification gates both supply qualification and price differentiation in the mPOS terminal market, as EMV kernel compliance creates six-to-twelve month product launch delays that concentrate manufacturing among established secure element fabricators while forcing premium pricing for certified units. FCC radio frequency authorization extends hardware launch windows by four to eight months for cellular-enabled devices, compressing margins for new entrants while entrenching volume-discount advantages for incumbent payment terminal manufacturers with in-house certification expertise.
Pricing Analysis
Volume-discount tiering structures dominate mPOS procurement, with enterprise quick-service restaurant chains capturing thirty-to-fifty percent unit cost reductions against street-vendor single-unit purchases. Price differentiation hinges on EMV certification tier and bundled software subscription depth, with tablet POS systems commanding recurring revenue premiums over standalone card readers. Cost compression in entry-level Bluetooth peripherals is intensifying because Soft-POS smartphone applications eliminate dedicated hardware entirely among micro-merchants. Sole proprietors and pop-up vendors exhibit highest price sensitivity, while mid-sized restaurant operators prioritize workflow integration over per-unit hardware costs.
Supply Chain Analysis
Inventory lead times for NFC controller chips and secure element modules stretch eight to fourteen weeks, constraining terminal manufacturers' ability to respond to demand surges from PCI DSS mandate-driven replacement cycles. Supply concentrates in Taiwan, South Korea, and China for semiconductor fabrication, with Shenzhen ecosystems compressing production costs for Bluetooth and cellular connectivity modules. Raw material dependencies span secure element chips, NFC antennas, and lithium-ion battery cells. Single-source vulnerability in East Asian foundries exposes terminal manufacturers to disruption from geopolitical friction or export restrictions. Distribution runs through independent software vendors and vertical SaaS platforms that displace traditional distributor networks as primary purchase pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent mPOS hardware manufacturers face substitution defense imperatives as Soft-POS applications on consumer smartphones erode dedicated terminal demand among sole proprietors and micro-merchants.
For Market Incumbents: Compound software-hardware integration depth to anchor recurring subscription revenue against pure-play application competitors. Deepen vertical integration into secure element sourcing to mitigate single-foundry concentration risk in Taiwan and South Korea. Prioritize EMV kernel pre-certification investments that compress rival launch timelines and defend enterprise account relationships from cloud-native SaaS platforms. For New Entrants and Emerging Players: FCC certification fast-tracks for cellular-enabled devices offer white-space entry points among food trucks and event coordinators operating beyond Wi-Fi range. Target service provider segments with Bluetooth Low Energy hardware optimized for low-volume, battery-constrained environments. Pursue restaurant management software partnership channels that displace direct processor sales forces as primary procurement pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed vertical SaaS platforms seeking payment acceptance capabilities to complete unified workflow tool suites. Five-to-ten year viability hinges on firmware readiness for central bank digital currency pilots before mass deployment timelines clarify. Monitor Federal Reserve and European Central Bank CBDC test program announcements as inflection indicators for terminal architecture refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Integration | PSD2-compliant fingerprint sensors capture premium positioning in German and French markets ahead of enforcement deadlines. |
| Vertical SaaS Partnership | Restaurant management platform embedding anchors tablet POS procurement away from standalone hardware vendors. |
| Cellular Certification Investment | FCC authorization capabilities expand addressable markets for food trucks and festival vendors beyond Wi-Fi range. |
| Soft-POS Application Development | Smartphone-tethered solutions capture micro-merchant segments that dedicated terminal manufacturers cannot serve profitably. |
| Secure Element Backward Integration | In-house fabrication or captive supply agreements mitigate single-source concentration risk in East Asian foundries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of payment processor regulatory filings, FCC equipment authorization databases, and PCI Security Standards Council compliance documentation. Interviews with restaurant technology procurement officers, payment terminal firmware engineers, and independent software vendor channel managers inform demand-side and supply-side dynamics. Bottom-up merchant adoption modeling triangulates against top-down payment volume projections across quick-service restaurant, retail, and mobile service provider segments.
Segmentation dimensions modeled span product type, end-user vertical, connectivity protocol, and deployment architecture across the projection horizon. CAGRs derive from installed base replacement cycle analysis, gig-economy workforce expansion trajectories, and contactless payment mandate compliance deadlines. Forecast inputs incorporate PCI DSS terminal refresh timelines, EMV kernel certification queue depths, and cellular module FCC authorization backlogs.
Decision-makers should treat outputs as directional under assumptions of sustained contactless payment regulatory momentum and stable semiconductor supply from East Asian foundries; material deviation in central bank digital currency deployment timelines or geopolitical disruption of secure element fabrication would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
UAE Card Payments Market
Payments
Epayment System Market
Payments
India POS Terminals Market
Payments
Global Real-Time Payments Market
Payments
Africa Mobile Money Market
Payments
Southeast Asia POS Terminal Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Payment Card Market
Payments
Brazil Real Time Payments Market
Payments
Medical Payment Fraud Detection Market
Payments
Mexico Real Time Payments Market
Payments
North America Accounts Payable Automation Market
Payments
Germany Payment Gateway Market
Payments
Japan Retail Cash Management Market
Payments
South Korea Mobile Payment Market
Payments
United Kingdom Mobile Payments Market