
 Transcatheter Aortic Valve Replacement Market | 2026-2036
Transcatheter Aortic Valve Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Aortic Valve Replacement Market Intelligence
Multi-source procurement of nitinol frames and bovine pericardial tissue is realigning supply economics for valve manufacturers. Edwards Lifesciences Corporation anchors its competitive position through captive manufacturing of tissue leaflets in Irvine, California. Medtronic plc leverages its Galway, Ireland production campus to sustain European market access with localized assembly lines.
Transcatheter aortic valve replacement deploys a collapsible bioprosthetic valve, typically mounted on a balloon-expandable or self-expanding nitinol stent frame, delivered via femoral artery access to the native aortic annulus without sternotomy or cardiopulmonary bypass. Balloon-expandable systems dominate acute hemodynamic precision in calcified annuli, while self-expanding platforms compete on anatomical adaptability in tortuous vasculature. Biological valves, specifically bovine and porcine pericardial constructs, occupy the highest margin tier due to tissue processing complexity and durability validation requirements.
FDA premarket approval pathways and the EU Medical Device Regulation govern clinical evidence thresholds for transcatheter valve platforms, with MDR transition timelines forcing manufacturers to rebuild technical documentation under notified body scrutiny. The FDA's breakthrough device designation compresses interactive review cycles for novel coronary-access technologies. Stakeholders must monitor reimbursement parity between TAVR and surgical aortic valve replacement across national health technology assessment bodies, as payment policy determines hospital program viability irrespective of device innovation pace.
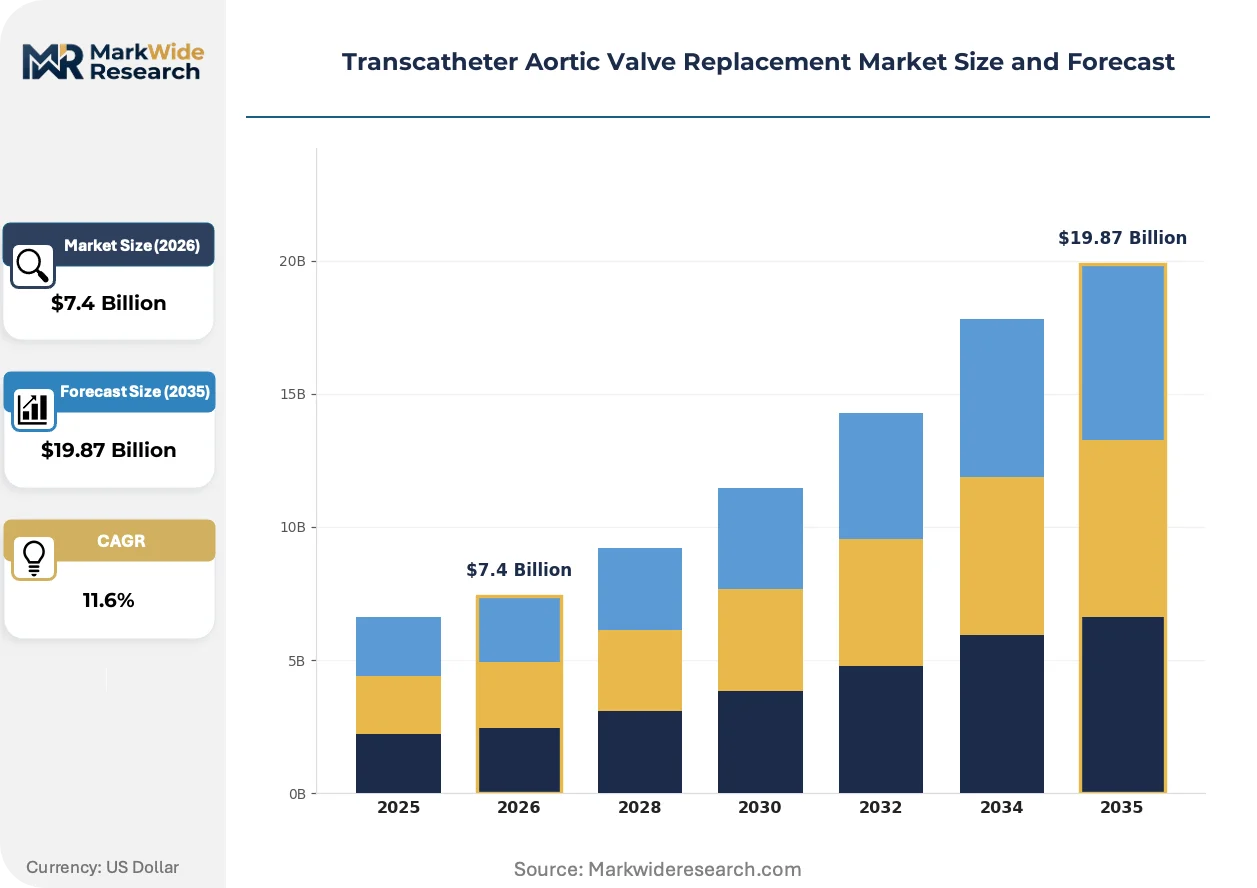
Market Dynamics
Medicare reimbursement parity between transcatheter and surgical aortic valve replacement is compressing hospital decision timelines and redistributing procedural volume toward catheter-based interventions across United States health systems.
Growth Catalysts
- CE marking under MDR Article 52:Accelerated notified body pathways for breakthrough device categories are compressing European market entry timelines for next-generation valve platforms.
- Intermediate-risk patient expansion:Hospital systems in Germany, Japan, and the United States are formalizing TAVR programs for anatomically suitable patients previously routed to sternotomy.
- Computed tomography-based sizing algorithms:Advanced annular assessment protocols are reducing paravalvular leak rates and expanding treatable anatomies.
Market Restraints
- Bovine pericardial tissue supply concentration:Biological leaflet sourcing depends on limited qualified abattoir networks in Australia and New Zealand, creating raw material vulnerability.
- Nitinol frame fabrication bottlenecks:Superelastic alloy processing requires specialized vacuum heat treatment capacity concentrated in United States and European forges.
- Surgical valve durability benchmarks:SAVR platforms maintain hemodynamic performance advantages in younger low-risk cohorts, limiting TAVR addressable population.
Strategic Opportunities
- Japan's super-aged demographic:PMDA regulatory harmonization with FDA data packages is opening procedural expansion in the world's oldest national population.
- Tricuspid valve transcatheter repair:Anatomical expertise from aortic interventions is expanding into adjacent structural heart procedures with unmet clinical need.
- Centers for Medicare and Medicaid Services bundled payment pilots:Episode-based reimbursement models are creating integrated service contracting opportunities for device-hospital partnerships.
Industry Challenges
- Imaging specialist workforce constraints:Cardiac CT and 3D echocardiography interpretation expertise remains concentrated in academic medical centers, limiting community hospital program viability.
- Heart team coordination complexity:Mandatory multidisciplinary case review between interventional cardiologists and cardiac surgeons creates operational friction and scheduling bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Aortic Valve Replacement Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $19.87 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bovine, Porcine, Mechanical, Biological Delivery Mode: Transfemoral, Transapical, Subclavian, Direct Aortic End User: Cardiac Centers, Hospitals, Research Institutions, Surgical Clinics Technology: Balloon-Expandable, Self-Expanding, Hybrid, Coronary-Access |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Meril Life Sciences Pvt. Ltd., JenaValve Technology, MicroPort Scientific Corporation, Venus Medtech (Hangzhou) Inc., Anteris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Aortic Valve Replacement Market Strategic Shifts & Innovations
Transcatheter valve engineering is pivoting from access optimization toward durability enhancement, with tissue processing and frame metallurgy now commanding disproportionate R&D investment relative to delivery system refinement.
Polymeric valve leaflets are expanding into preclinical and early clinical evaluation as alternatives to biological tissue constructs. Medtronic and early-stage developers are advancing polycarbonate-based materials that promise calcification resistance and extended functional lifespan. This platform is expanding into investigator-initiated trials across European centers, potentially compressing the biological valve replacement cycle if long-term data validates thrombogenicity profiles.
MDR technical documentation requirements are forcing manufacturers to rebuild clinical evidence packages under notified body scrutiny. The European Union's stricter post-market surveillance mandates and periodic safety update report obligations are extending certification timelines. High-risk Class III devices face the most pronounced review compression, with several manufacturers withdrawing legacy platforms rather than completing MDR transition.
Hospital procurement committees are consolidating vendor relationships through multi-year supply agreements that bundle valve inventory with technical training and complication coverage. This concentration is displacing spot purchasing and trial evaluations that characterized early TAVR adoption. United States integrated delivery networks are most advanced in this transition, with Catholic health systems and for-profit chains standardizing on single-supplier frameworks.
Transcatheter Aortic Valve Replacement Market Segmentation
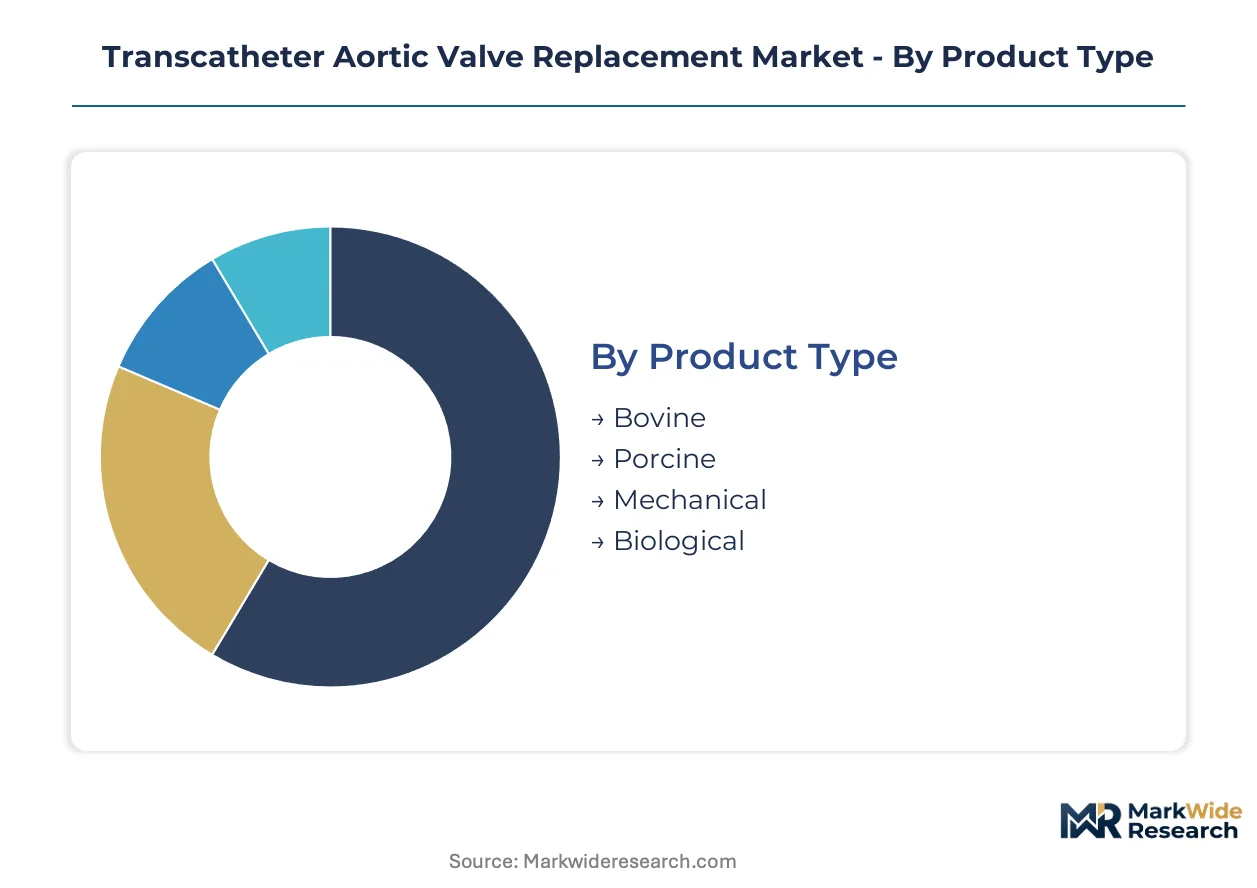
Transcatheter valve procurement decisions split across tissue sourcing, anatomical access routes, and institutional capabilities. Each segmentation axis carries distinct reimbursement, regulatory, and supply chain implications that determine commercial viability.
Product Type:
Buyers differentiate by durability requirements and tissue processing sophistication, with biological constructs commanding premium positioning over mechanical alternatives.
- Bovine:Pericardial leaflets from qualified Australian and New Zealand abattoirs dominate high-durability applications. Hospital systems in the United States prioritize bovine constructs for Medicare-covered procedures where long-term hemodynamic stability determines program accreditation.
- Porcine:Aortic valve cusp configurations offer anatomical familiarity to surgical teams transitioning to catheter-based platforms. Demand concentrates in European centers where porcine sourcing aligns with established tissue bank relationships and CE marking pathways under MDR Article 52.
- Mechanical:Metal leaflet designs eliminate biological tissue supply dependencies. Limited clinical adoption reflects thrombogenicity concerns and mandatory anticoagulation protocols.
- Biological:Encompasses processed xenograft tissues beyond pericardial constructs. Emerging polymeric alternatives from polycarbonate platforms are entering preclinical evaluation.
Volume sits with bovine constructs; growth tilts toward next-generation biological processing and polymeric alternatives.
Delivery Mode:
Anatomical access strategy determines procedural complexity, recovery timelines, and eligible patient populations.
- Transfemoral:Femoral artery cannulation enables minimally invasive deployment with same-day mobilization. United States integrated delivery networks standardize on transfemoral protocols for outpatient TAVR program expansion.
- Transapical:Left ventricular apex access via mini-thoracotomy addresses hostile iliofemoral anatomy. Surgical teams in Germany retain transapical capability for calcified or tortuous peripheral vasculature.
- Subclavian:Axillary artery approach preserves femoral circulation in peripheral arterial disease patients. Japanese centers leverage subclavian access for super-aged populations with extensive atherosclerotic burden.
- Direct Aortic:Ascending aorta cannulation via mini-sternotomy or right thoracotomy serves as salvage access. Declining utilization reflects transfemoral device profile improvements.
Transfemoral platforms capture procedural volume; subclavian and alternative access routes are climbing the fastest as anatomical eligibility expands.
End User:
Institutional infrastructure and reimbursement structure create tiered purchasing power across delivery settings.
- Cardiac Centers:Dedicated structural heart programs with heart team infrastructure and 24/7 interventional coverage. United States academic medical centers anchor TAVR volume through Medicare bundled payment participation.
- Hospitals:General acute care facilities building TAVR capability through catheterization laboratory upgrades. Community hospitals in Japan are expanding programs under PMDA regulatory harmonization with FDA standards.
- Research Institutions:Investigator-initiated trials and post-market surveillance studies. European centers under MDR transition drive clinical evidence generation for next-generation valve platforms.
- Surgical Clinics:Limited TAVR adoption due to anesthesia and critical care requirements. Ambulatory surgical centers in select United States markets are piloting low-risk outpatient protocols.
Cardiac centers concentrate procedural volume; hospital-based programs are gaining share fastest as community access expands.
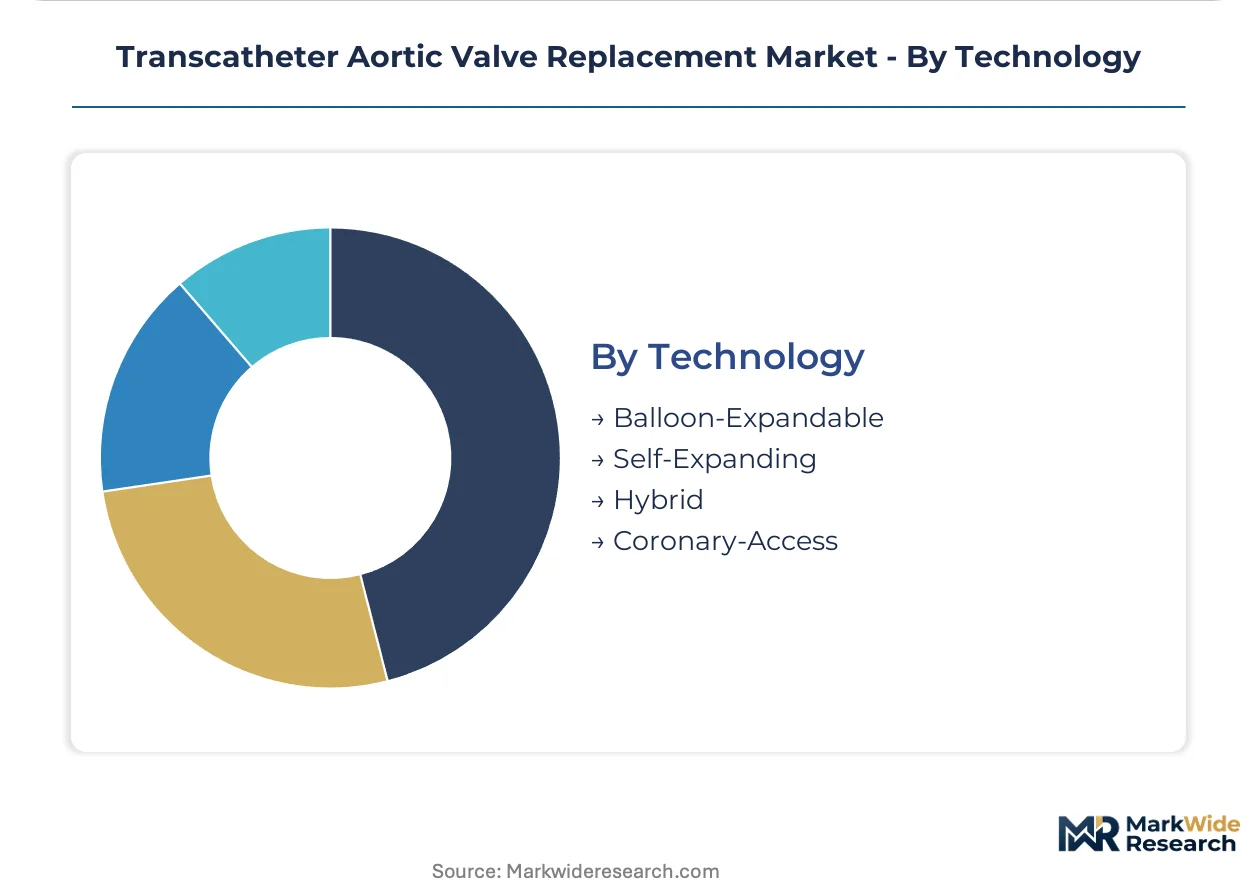
Technology:
Frame expansion mechanism and delivery system architecture determine anatomical adaptability and hemodynamic precision.
- Balloon-Expandable:Stent frame mounted on balloon catheter enables controlled annular sizing with acute hemodynamic optimization. Edwards Lifesciences' SAPIEN platforms dominate calcified annuli where precise deployment positioning is critical.
- Self-Expanding:Nitinol frame delivers through tortuous vasculature with conformable annular seating. Medtronic's CoreValve systems compete on anatomical flexibility in elliptical or asymmetric annuli.
- Hybrid:Combines balloon-expandable precision with self-expanding conformability features. Early-stage platforms are entering European investigational device exemptions.
- Coronary-Access:Dedicated valve designs preserving coronary ostia patency for future revascularization. FDA breakthrough device designation is compressing review timelines for coronary-access technologies.
Balloon-expandable systems hold installed base; self-expanding and coronary-access platforms are expanding most quickly through intermediate-risk indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bovine pericardial tissue sourcing from Australian and New Zealand abattoirs anchors transcatheter valve manufacturing economics. Nitinol frame fabrication capacity concentrates in United States and European forges. Regulatory harmonization between FDA and Japan's PMDA is accelerating procedural expansion in aging populations.
United States
Medicare reimbursement parity with surgical aortic valve replacement drives hospital program expansion across integrated delivery networks. FDA breakthrough device designation compresses review timelines for next-generation coronary-access technologies. The Irvine, California manufacturing cluster anchors captive tissue processing operations for Edwards Lifesciences Corporation.
Germany
Intermediate-risk patient formalization in hospital systems sustains procedural volume growth beyond early adopters. CE marking under MDR Article 52 governs technical documentation thresholds for Class III valve platforms. The Galway, Ireland production campus serves European market access through localized assembly lines for Medtronic plc.
Japan
PMDA regulatory harmonization with FDA data packages opens procedural expansion in the world's oldest national population. Super-aged demographic concentration creates addressable patient pools exceeding European benchmarks. Tokyo and Osaka academic medical centers anchor heart team infrastructure for catheter-based interventions.
China
Domestic valve platform development accelerates under NMPA priority review pathways for breakthrough devices. Local manufacturing investments reduce import dependency for nitinol frame and biological tissue constructs. Hangzhou and Shanghai clusters concentrate early-stage polymeric valve research alongside established pericardial tissue processing.
Australia
Qualified abattoir networks supply bovine pericardial tissue to global valve manufacturers under strict veterinary oversight. TGA post-market surveillance requirements align with MDR transition timelines for exported devices. Melbourne and Sydney structural heart programs participate in international clinical evidence generation for next-generation platforms.
Transcatheter Aortic Valve Replacement Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers rebuild technical documentation under MDR scrutiny and scale nitinol frame fabrication. The vendor base concentrates around integrated tissue-frame-delivery system capabilities, with three to four firms commanding procedural volume. Two strategic archetypes prevail: captive tissue processors controlling pericardial supply chains, and forge-integrated metallurgists commanding nitinol heat treatment capacity. M&A activity and strategic partnerships represent the dominant competitive moves, with manufacturers acquiring imaging and sizing algorithm capabilities to reduce paravalvular leak rates.
Among United States-based integrated manufacturers, Edwards Lifesciences Corporation anchors the balloon-expandable platform segment through Irvine-based tissue processing. Medtronic plc occupies a parallel position in self-expanding systems via its Galway production campus. Abbott Laboratories exemplifies the diversified cardiovascular portfolio archetype, representing breadth across structural heart interventions without single-platform dependency. These three firms collectively sit within the premium tier where captive manufacturing and regulatory scale create defensive positioning.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Meril Life Sciences Pvt. Ltd. |
| JenaValve Technology |
| MicroPort Scientific Corporation |
| Venus Medtech (Hangzhou) Inc. |
| Anteris Technologies |
| Others |
Cost & Logistics Intelligence
Captive tissue processing operations in Irvine, California and Galway, Ireland anchor both supply security and pricing power for balloon-expandable and self-expanding platform manufacturers. This backward integration into bovine pericardial leaflet production insulates premium-tier vendors from raw material volatility while supporting bundled service contracts that command price premiums from United States integrated delivery networks.
Pricing Analysis
Warranty and complication coverage bundling now separates premium valve contracts from standard procurement tiers, with multi-year supply agreements incorporating technical training and paravalvular leak rate guarantees. Price differentiation rests on tissue processing sophistication and frame metallurgy certification, with FDA breakthrough-designated platforms commanding premiums over CE-marked alternatives. Cost compression in standard-tier mechanical alternatives is intensifying because of thrombogenicity concerns limiting clinical adoption. Community hospitals exhibit highest price sensitivity due to Medicare bundled payment margin constraints, while academic medical centers prioritize hemodynamic performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Australian and New Zealand abattoir networks supplying qualified bovine pericardial tissue, with vacuum heat treatment capacity for nitinol frames concentrated in United States and European forges. Raw material dependencies encompass superelastic alloy feedstock, biological leaflet constructs, and polycarbonate polymers for emerging polymeric alternatives. Tariff exposure on imported nitinol from European forges threatens frame cost stability. Distribution runs through hospital procurement committees consolidating vendor relationships and displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from MDR technical documentation requirements is forcing smaller manufacturers to withdraw legacy platforms, creating acquisition opportunities for firms with regulatory scale. The report identifies three stakeholder positions.
For Market Incumbents: Anticipate polymeric valve disruption by securing polycarbonate polymer supply agreements and accelerating investigator-initiated trials in European centers. Defensive positioning requires deepening captive tissue processing capacity in Irvine or Galway to maintain margin structure against emerging mechanical alternatives. Priority investment targets coronary-access platform development under FDA breakthrough pathways. For New Entrants and Emerging Players: Launch via subclavian access specialization targeting Japanese super-aged populations with extensive peripheral arterial disease, where anatomical expertise gaps persist. White-space opportunities concentrate in tricuspid valve transcatheter repair and outpatient TAVR protocols at ambulatory surgical centers. Go-to-market execution should prioritize PMDA regulatory harmonization with existing FDA data packages. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated manufacturers seeking imaging and sizing algorithm capabilities. Five-to-ten year viability favors firms with combined tissue-frame-delivery system integration and MDR transition completion. The signal to watch is CMS bundled payment pilot expansion, which would validate hospital program economics and device-hospital partnership models.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Rebuild | CE marking under Article 52 requires clinical evidence package reconstruction for Class III valve platforms. |
| Coronary-Access Platform Development | FDA breakthrough device designation compresses review timelines for next-generation ostia-preserving designs. |
| Hospital System Partnership | Multi-year supply agreements with integrated delivery networks bundle inventory with complication coverage. |
| Polymeric Valve Clinical Advancement | Polycarbonate-based materials entering European trials promise calcification resistance and extended lifespan. |
| Reimbursement Strategy | Medicare parity with surgical aortic valve replacement determines hospital program viability irrespective of device innovation. |
Research Approach
Multi-period observation of procedural volume trajectories, regulatory submission timelines, and reimbursement policy shifts anchored the trend analysis, supplemented by interviews with interventional cardiologists, cardiac surgeons, hospital procurement managers, GPO contracts specialists, and biomedical engineers. Secondary validation drew from FDA premarket approval filings, EMA MDR transition documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up segmentation modeling triangulated against top-down market sizing across the analysis window.
Input-output matrices mapped nitinol frame fabrication capacity, bovine pericardial tissue supply flows, and procedural volume by access route and patient risk stratification. Segmentation dimensions encompassed tissue sourcing, delivery mode, end-user institutional tier, and frame expansion technology. CAGRs were derived from regression analysis of historical procedural adoption curves applied to demographic projections and regulatory approval timelines. Forecast inputs included PMDA-FDA harmonization pace and MDR notified body capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for polymeric valve platforms would alter the outlook if long-term thrombogenicity data validates clinical equivalence. Forecasts reflect assumptions regarding reimbursement parity maintenance and intermediate-risk indication expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Artificial Blood Vessels Market