
 Global Heart Pump Devices Market | 2026-2036
Global Heart Pump Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heart Pump Devices Market Foresight
The gap between magnetically levitated premium pumps and conventional bearing-dependent systems is expanding. Abbott Laboratories dominates magnetically levitated centrifugal platforms, while Medtronic anchors axial flow legacy installations across mature markets. Berlin Heart specializes in pediatric and biventricular niches that larger competitors navigate less aggressively.
Heart pump devices are implantable mechanical circulatory support systems that replace or assist native ventricular function through continuous or pulsatile blood flow generation, typically operating at 2,000 to 10,000 RPM with biocompatible titanium or polymer blood-contacting surfaces. Left ventricular assist devices occupy the largest installed base due to isolated left heart failure prevalence, whereas destination therapy applications are capturing margin pools as reimbursement frameworks broaden beyond bridge-to-transplant indications. Continuous flow technology leads volume shipments while centrifugal pump architectures displace axial designs in new implants because of improved hemocompatibility profiles.
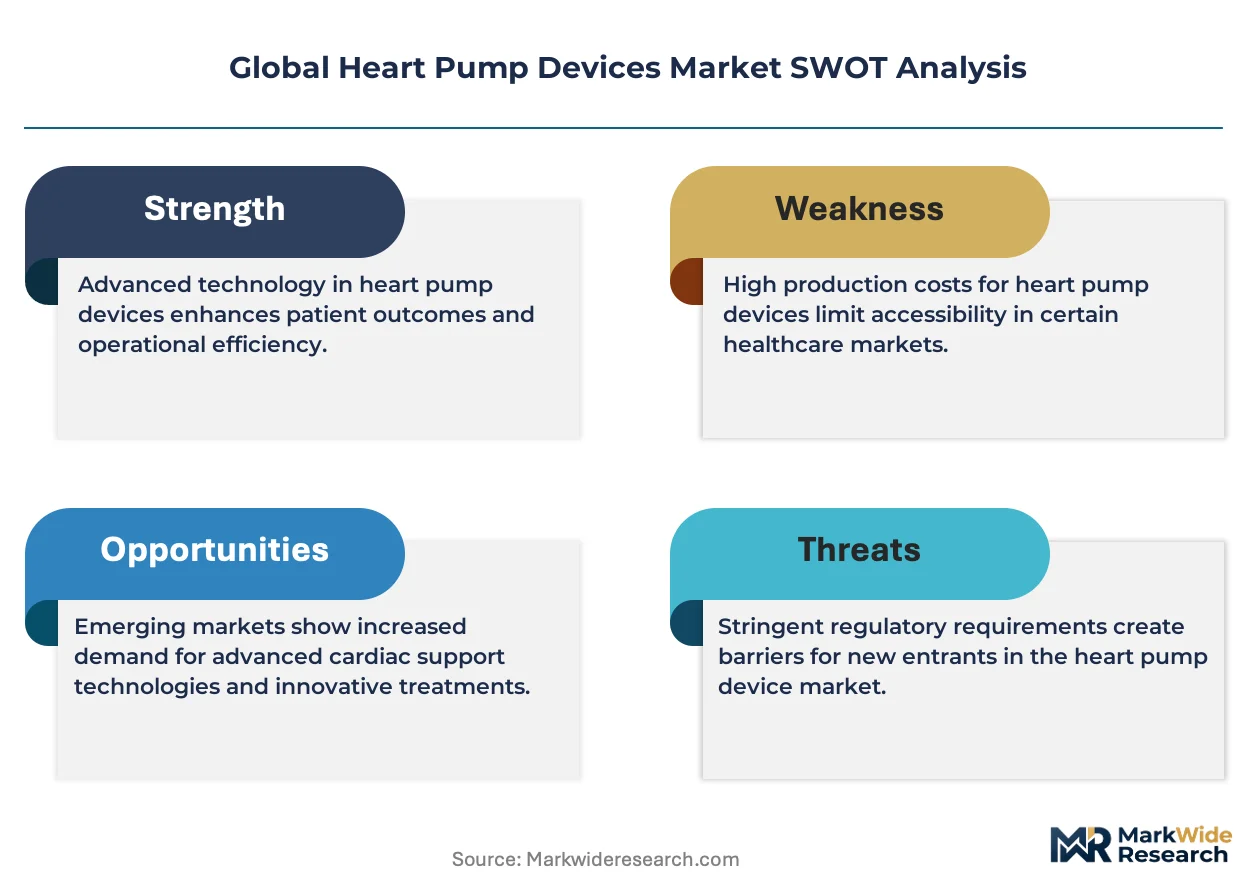
FDA premarket approval requirements and MDR compliance in Europe enforce biocompatibility and durability testing standards that raise capital barriers for entrants. The EU AI Act and FDA software-as-medical-device guidance are beginning to shape automated control algorithms in next-generation pumps. Stakeholders must monitor how regulatory convergence on real-world evidence collection reshapes post-market surveillance obligations and competitive differentiation.
Market Dynamics
Centrifugal pump architectures are displacing axial flow designs across new implant procedures, compressing development timelines and redrawing competitive boundaries around hemocompatibility performance rather than legacy installation bases.
Growth Catalysts
- Destination therapy reimbursement:CMS coverage determinations in the United States now extend beyond bridge-to-transplant indications, expanding addressable patient pools for implantable systems.
- Magnetic levitation advances:Bearing-free rotor designs reduce thrombogenicity risks and extend device durability, accelerating clinical adoption in high-acuity cardiac centers.
- Pediatric mechanical circulatory support:Specialized biventricular platforms address congenital heart failure populations previously excluded from adult-configured device protocols.
Market Restraints
- Titanium supply concentration:Biocompatible alloy feedstock for blood-contacting surfaces concentrates among a limited supplier base, exposing manufacturers to input cost volatility.
- FDA premarket approval timelines:Extended durability testing requirements for continuous flow systems compress capital efficiency and delay revenue recognition for novel entrants.
- Transplant infrastructure dependency:Bridge-to-transplant volumes fluctuate with organ availability, creating demand uncertainty for temporary support devices.
Strategic Opportunities
- Japan's aging demographic:The country's super-aged population structure and established cardiac surgery networks create sustained procedure volume expansion for destination therapy programs.
- EU AI Act compliance:Automated control algorithm classification as software-as-medical-device opens premium pricing tiers for predictive monitoring capabilities.
- Home discharge protocols:Portable driver systems and remote monitoring integration enable care migration from hospital to outpatient settings, unlocking new reimbursement categories.
Industry Challenges
- Biomedical engineer scarcity:Specialized expertise in hemocompatibility testing and rotational blood pump design concentrates among academic medical centers, constraining workforce scaling.
- MDR technical documentation:European Union medical device regulation compliance demands extensive clinical evidence portfolios, extending time-to-market for iterative design improvements.
- Legacy system integration:New magnetically levitated platforms must interface with existing surgical workflows and ICU monitoring infrastructure, complicating hospital adoption decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heart Pump Devices Market |
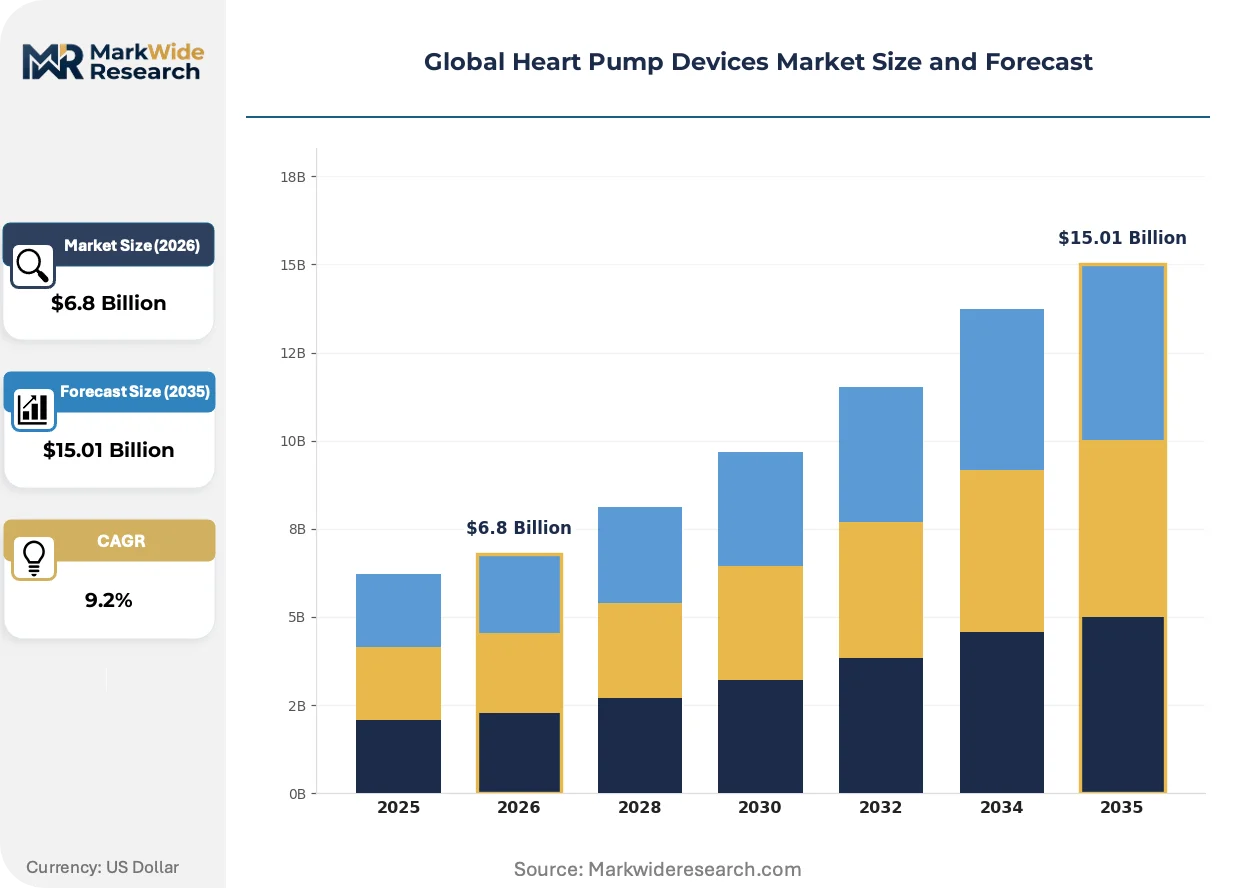
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.01 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Left Ventricular Assist Device, Right Ventricular Assist Device, Biventricular Assist Device, Total Artificial Heart Technology: Continuous Flow, Pulsatile Flow, Centrifugal Pump, Axial Flow, Electromagnetic Drive Application: Bridge to Transplant, Destination Therapy, Bridge to Recovery, Bridge to Candidacy End User: Cardiac Surgery Centers, Specialized Clinics, Rehabilitation Facilities, Emergency Care Units |
| Companies Covered | Getinge, Teleflex Incorporated, Abbott Laboratories, Jarvik Heart, Berlin Heart, Medtronic, SynCardia Systems, LivaNova, Abiomed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heart Pump Devices Market Shifts & Advancements
Hardware-software convergence and miniaturization are compressing device footprints while expanding ambulatory care possibilities, fundamentally restructuring where and how mechanical circulatory support is delivered.
Modular driveline and controller configurations are modularizing system architecture, enabling cardiac surgery centers to swap power and monitoring components without explanting the intracorporeal pump. High-volume implant programs in Germany and the United States are standardizing these interoperable interfaces across vendor platforms. This standardization is reducing hospital inventory burdens and accelerating emergency replacement protocols.
EU MDR post-market surveillance requirements are mandating systematic real-world evidence collection for active implantable devices, forcing manufacturers to invest in cloud-based registry infrastructure. The regulation compresses reporting timelines for adverse events and device malfunctions. Centrifugal pump manufacturers with established European installed bases face disproportionate compliance costs relative to early-stage competitors.
Hospital purchasing consortia are consolidating procurement authority for high-value cardiac devices, displacing individual surgeon preference as the primary selection criterion. Integrated delivery networks in the United States are negotiating multi-year supply agreements that bundle devices with technical training and outcomes guarantees. This concentration is most visible in tertiary referral centers where annual LVAD volumes exceed fifty implants.
Global Heart Pump Devices Market Segmentation
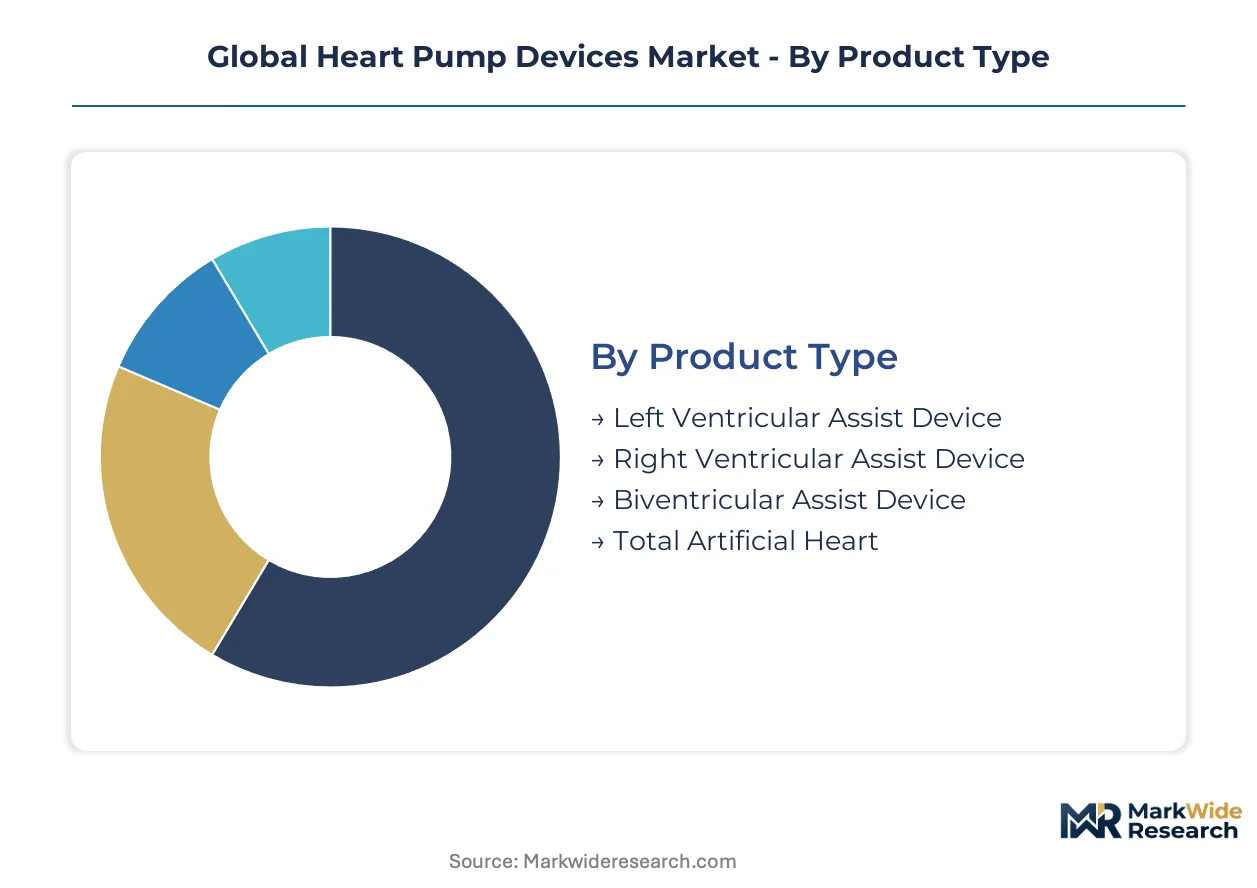
Segmentation in heart pump devices reveals how clinical indication, hemodynamic architecture, and care setting interact to determine pricing power and procurement patterns. Each axis carries distinct regulatory, reimbursement, and competitive dynamics that shape manufacturer strategy.
Product Type:
Device configuration follows ventricular failure patterns and anatomical constraints in the target patient population.
- Left Ventricular Assist Device:Isolated left heart failure prevalence drives the largest installed base. Demand concentrates in the United States and Germany where destination therapy reimbursement frameworks have matured beyond bridge-to-transplant protocols.
- Biventricular Assist Device:Dual-chamber support addresses refractory biventricular failure through synchronized pumping. Pediatric congenital heart programs and adult cardiogenic shock centers in Japan sustain specialized demand despite complex surgical implantation requirements.
- Right Ventricular Assist Device:Isolated right heart failure support, often deployed post-LVAD implantation when secondary right ventricle dysfunction emerges.
- Total Artificial Heart:Orthotopic replacement for irreversible biventricular failure when ventricular recovery is impossible and transplant unavailable.
Left Ventricular Assist Device leads on scale; Biventricular Assist Device leads on momentum.
Technology:
Hemodynamic generation mechanisms differentiate on thrombogenicity, durability, and control sophistication.
- Centrifugal Pump:Bearing-free magnetic levitation eliminates mechanical wear surfaces. New implant procedures in high-acuity cardiac centers across the United States and Germany favor this architecture for improved hemocompatibility profiles.
- Continuous Flow:Non-pulsatile output dominates volume shipments through established axial and centrifugal platforms. Bridge-to-transplant programs rely on this technology for extended support duration.
- Axial Flow:Legacy installations persist in mature markets with extensive surgeon training infrastructure and standardized emergency replacement protocols.
- Pulsatile Flow:Mimics native cardiac contraction patterns but requires larger device footprints and more complex drive systems.
- Electromagnetic Drive:Advanced motor control enables real-time flow adjustment and predictive thrombosis detection algorithms.
Centrifugal Pump captures premium pricing tiers; Electromagnetic Drive gains share fastest.
Application:
Clinical indication determines reimbursement pathway, patient selection criteria, and expected support duration.
- Destination Therapy:Permanent implant for transplant-ineligible patients. CMS coverage determinations in the United States now authorize durable mechanical support independent of transplant candidacy, expanding addressable pools.
- Bridge to Transplant:Temporary stabilization until organ availability. Volumes fluctuate with donor organ supply and allocation policy changes.
- Bridge to Recovery:Short-term support permitting myocardial rest and potential native function restoration.
- Bridge to Candidacy:Hemodynamic optimization to qualify marginal patients for transplant listing.
Destination Therapy leads on margin contribution; Bridge to Candidacy climbs the fastest.
End User:
Care setting determines device complexity requirements, technical support needs, and patient monitoring intensity.
- Cardiac Surgery Centers:High-volume implant programs with dedicated VAD coordinators and standardized protocols. Integrated delivery networks in the United States consolidate procurement authority at this tier.
- Specialized Clinics:Outpatient mechanical circulatory support management with remote monitoring infrastructure and home discharge capabilities.
- Emergency Care Units:Temporary percutaneous support for acute cardiogenic shock requiring rapid deployment.
- Rehabilitation Facilities:Post-implant functional recovery programs with device-specific physical therapy protocols.
Cardiac Surgery Centers lead on procedure volume; Specialized Clinics show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cardiac surgeons and VAD coordinators cluster in established transplant centers across Germany, the United States, and Japan, anchoring procedural volume and technology diffusion patterns.
United States
Destination therapy reimbursement expansion through CMS coverage determinations drives implant volume growth. FDA premarket approval pathways for continuous flow systems enforce durability testing standards that raise capital barriers for novel entrants. The Cleveland Clinic and Texas Heart Institute anchor high-volume programs standardizing emergency replacement protocols.
Germany
Super-aged demographics and established cardiac surgery networks sustain procedure volume expansion for permanent mechanical support. EU MDR post-market surveillance requirements mandate systematic real-world evidence collection through cloud-based registry infrastructure. The Berlin-Brandenburg and North Rhine-Westphalia regions concentrate pediatric and biventricular expertise.
Japan
PMDA regulatory frameworks and aging population structures create sustained demand for destination therapy programs. METI industrial policy supports domestic medical device manufacturing capabilities. The Kanto region around Tokyo hosts high-acuity cardiac centers with standardized magnetically levitated pump adoption.
United Kingdom
NHS specialized commissioning frameworks determine eligibility for implantable mechanical circulatory support. MHRA convergence with EU MDR technical documentation requirements extends time-to-market for iterative design improvements. The London-Southeast corridor concentrates bridge-to-transplant and bridge-to-candidacy volumes.
Canada
Health Canada approval pathways and provincial health authority reimbursement negotiations shape device availability. Organ donation and transplantation infrastructure constraints create demand uncertainty for bridge-to-transplant indications. Ontario and Quebec anchor the national implant program with centralized VAD coordinator networks.
Global Heart Pump Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the heart pump devices landscape, with magnetically levitated centrifugal platforms demanding substantial R&D investment while software-driven control algorithms enable modular entry points. The market structure concentrates around three to four integrated manufacturers with established FDA PMA portfolios and European MDR technical files, while smaller specialists occupy pediatric and biventricular niches. Strategic archetypes separate into premium magnetically levitated platforms, legacy axial flow maintenance providers, and congenital heart specialists. Competitive moves center on M&A activity consolidating control algorithm capabilities and strategic partnerships securing titanium alloy feedstock.
Among the established integrated manufacturers, Abbott Laboratories and Medtronic occupy positions exemplifying the premium platform and legacy maintenance archetypes respectively, while Berlin Heart sits within the specialized congenital and biventricular tier. Abbott Laboratories represents the magnetically levitated centrifugal design vector with established European and North American installed bases. Medtronic anchors axial flow legacy installations across mature markets with extensive surgeon training infrastructure. Berlin Heart exemplifies the pediatric mechanical circulatory support specialist model addressing populations excluded from adult-configured protocols.
| Leading Market Players |
|---|
| Getinge |
| Teleflex Incorporated |
| Abbott Laboratories |
| Jarvik Heart |
| Berlin Heart |
| Medtronic |
| SynCardia Systems |
| LivaNova |
| Abiomed |
| Others |
Supply & Pricing Matrix
Magnetic levitation manufacturing transitions simultaneously compress production costs and concentrate supplier networks around specialized titanium alloy foundries and precision electromagnetic component fabricators. Centrifugal pump architectures displace legacy axial designs by eliminating bearing wear surfaces, yet this shift locks manufacturers into premium-grade biocompatible material sourcing from concentrated German and Japanese metallurgical suppliers.
Pricing Analysis
Bundled service contracts dominate high-acuity cardiac centers, unbundled component procurement persists in lower-volume programs. Pricing stratifies across magnetically levitated premium platforms, conventional bearing-dependent systems, and refurbished legacy installations. Cost compression in conventional tiers intensifies because hospital purchasing consortia consolidate procurement authority. Emergency care units exhibit highest price sensitivity; destination therapy programs demonstrate lowest sensitivity due to reimbursement guarantees.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan maintain hub-and-spoke patterns for sterile device deployment and emergency replacement protocols. Manufacturing draws from titanium alloy feedstock in Germany and Japan, precision electromagnetic components from the United States, and polymer blood-contacting surfaces from Switzerland. Single-source vulnerability concentrates in biocompatible titanium suppliers. Distribution runs through integrated delivery networks with multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through magnetic levitation premium-tier migration and automated control algorithm software premiums. Bearing elimination reduces warranty costs while predictive monitoring capabilities command reimbursement uplifts.
For Market Incumbents: Cement magnetically levitated platform dominance through backward integration into titanium alloy supply and predictive algorithm patent portfolios. Threats concentrate in software-driven entrants with modular control systems. Priority levers include FDA breakthrough device pathway acceleration and European MDR technical file maintenance. For New Entrants and Emerging Players: Pediatric biventricular configurations offer technology-first wedge opportunities with lower competitive density. Most penetrable targets include congenital heart programs in Japan and specialized clinics with home discharge protocols. Go-to-market angle centers on modular driveline interoperability with existing surgical workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among axial flow legacy maintenance providers facing centrifugal displacement. Long-term viability favors automated control algorithm specialists with software-as-medical-device regulatory clearance. Acquisition target archetype includes hemocompatibility testing laboratories with academic medical center affiliations. Signal to watch: FDA software guidance convergence on real-world evidence requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation compresses time-to-market for magnetically levitated centrifugal platforms. |
| Hospital System Partnership | Integrated delivery networks bundle devices with outcomes guarantees across high-volume cardiac surgery centers. |
| Software Companion Development | FDA software-as-medical-device guidance enables predictive thrombosis detection algorithm premiums. |
| Reimbursement Strategy | CMS coverage determinations expand destination therapy eligibility beyond bridge-to-transplant indications. |
| Backward Integration | Captive titanium alloy supply secures biocompatible feedstock against input cost volatility from concentrated suppliers. |
Research Methodology
Multiple input streams — cardiac surgeon interviews, biomedical engineer consultations, hospital purchasing committee discussions, and GPO contracts analysis — were reconciled against FDA PMA filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up implant volume modeling triangulated with top-down market sizing from continuous flow system shipment data.
Data-stream reconciliation across product type, technology architecture, clinical indication, and care setting dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from procedure volume trajectories in destination therapy programs and magnetic levitation adoption curves. Industry-specific inputs incorporated PMDA regulatory timelines and METI industrial policy incentives.
The model holds under stable reimbursement frameworks and titanium supply continuity; deviation in FDA software guidance or EU AI Act enforcement would shift algorithm premium capture timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Atherectomy Systems Market