
 Global Percutaneous Coronary Intervention (PCI) Devices Market | 2026-2036
Global Percutaneous Coronary Intervention (PCI) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Percutaneous Coronary Intervention (PCI) Devices Market Foresight
Drug-eluting stent tier upgrades is reorganizing procurement criteria across health systems. Abbott leverages integrated vascular access platforms to sustain cath lab loyalty in North American hospital networks. Boston Scientific anchors its position through proprietary polymer coating technologies that differentiate restenosis outcomes. Medtronic competes on global manufacturing scale, supplying metallic alloy platforms to cardiac centers across multiple continents.
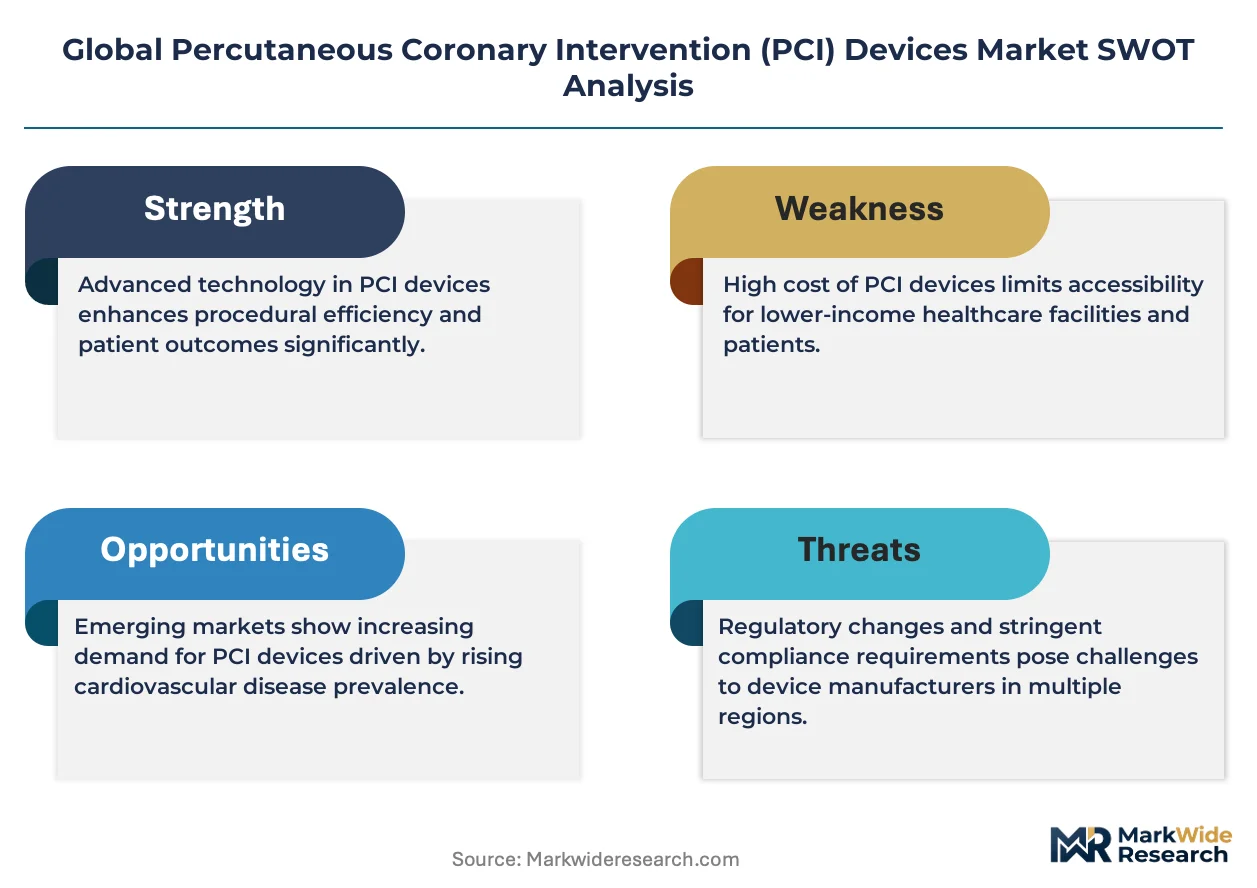
Percutaneous Coronary Intervention (PCI) Devices constitute catheter-based instruments and implantable scaffolds designed to restore coronary lumen patency, typically employing balloon-expandable platforms with strut thickness below 100 micrometers and drug-polymer matrices eluting antiproliferative agents over 3-12 month release kinetics. Their primary commercial purpose centers on revascularization of atherosclerotic coronary lesions without sternotomy, reducing inpatient recovery cycles relative to coronary artery bypass grafting. Drug-eluting stents command the dominant value share within product type segmentation, while bioabsorbable polymer platforms represent the fastest-expanding technology tier as metallic alloy scaffolds face scrutiny over long-term endothelial dysfunction. Coronary artery disease applications generate the largest procedure volume, though chronic total occlusion interventions attract premium pricing due to specialized guidewire and microcatheter requirements.
FDA premarket approval requirements for novel stent platforms shape clinical trial investment thresholds, while EMA's Medical Device Regulation imposes post-market surveillance obligations that extend liability timelines for European distribution. Japan's PMDA mandates Japan-specific clinical data for stent reimbursement eligibility, creating geographic fragmentation in regulatory access pathways. Stakeholders must monitor evolving bioabsorbable scaffold durability data and corresponding payer coverage decisions to align R&D portfolios with demonstrable long-term vessel healing outcomes.
Market Dynamics
Bioabsorbable polymer platforms are displacing metallic alloy scaffolds as the dominant R&D priority, forcing cath lab procurement committees to rewrite stent evaluation protocols around vessel healing endpoints rather than acute lumen gain metrics.
Growth Catalysts
- FDA's 510(k) premarket notification pathway:Class II cardiovascular device classification compresses commercialization timelines for manufacturers seeking rapid cath lab entry.
- Chronic total occlusion interventions:Specialized guidewire and microcatheter requirements for complex lesions command premium pricing tiers within German interventional cardiology networks.
- Metallic alloy platform refinement:Strut thickness reduction below 100 micrometers improves deliverability in tortuous anatomy, expanding addressable lesion complexity.
Market Restraints
- Noble metal input volatility:Platinum-iridium and cobalt-chromium alloy prices fluctuate with mining supply disruptions, compressing gross margins on balloon-expandable platforms.
- Japan-specific clinical data mandates:PMDA requirements for stent reimbursement eligibility fragment regulatory access pathways and extend trial investment thresholds.
- Coronary artery bypass grafting durability:Long-term patency data for surgical revascularization creates substitution pressure in multi-vessel disease cases.
Strategic Opportunities
- Indian cath lab infrastructure buildout:Tier-2 and Tier-3 cities lack interventional cardiology capacity, creating first-mover advantage for device distributors establishing training networks.
- EMA Medical Device Regulation post-market surveillance:Extended liability timelines favor manufacturers with robust clinical evidence generation infrastructure over commodity competitors.
- Drug-polymer matrix and intravascular imaging convergence:Integration of optical coherence tomography guidance with stent deployment protocols enables personalized antiproliferative agent dosing.
Industry Challenges
- Interventional cardiology fellow training pipelines:Complex CTO procedure volumes concentrate in high-volume centers, limiting skill transfer to community hospitals.
- ISO 13485 quality management recertification:Transition to EU MDR harmonized standards demands documentation overhaul for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Percutaneous Coronary Intervention (PCI) Devices Market |
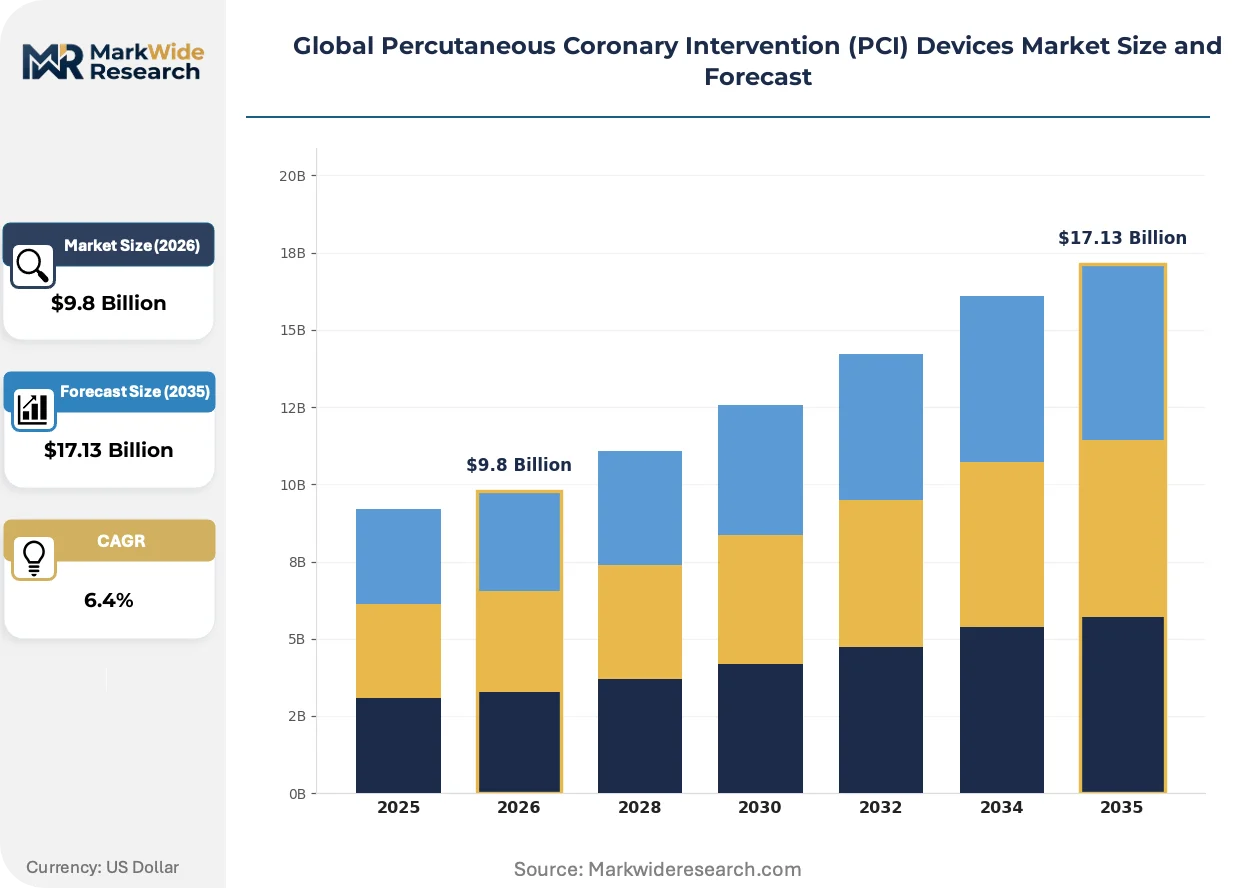
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Dilatation Catheters, Bare Metal Stents, Drug-Eluting Stents, Thrombectomy Devices, Guidewires Technology: Bioabsorbable Polymers, Metallic Alloys, Drug-Coated, Radiopaque Markers, Self-Expanding Stents Application: Stable Angina, Acute Myocardial Infarction, Restenosis Treatment, Chronic Total Occlusion, Coronary Artery Disease End User: Cardiac Centers, Specialty Clinics, Ambulatory Surgical Centers, Rehabilitation Facilities, Diagnostic Laboratories |
| Companies Covered | Boston Scientific, Abbott, Medtronic, Cordis, Terumo Corporation, B. Braun, BIOTRONIK, ASAHI INTECC, Meril Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Percutaneous Coronary Intervention (PCI) Devices Market Shifts & Advancements
Device architecture is splitting between durable metallic platforms and transient bioabsorbable scaffolds, with cath labs now maintaining dual inventory strategies to match lesion-specific healing requirements.
Polymer-free drug-eluting stent technology is bifurcating the coronary scaffold market. Abluminal coating techniques eliminate polymer-related inflammation risks while preserving antiproliferative efficacy. Academic medical centers in the United States and Netherlands are adopting these platforms for high-bleeding-risk patient cohorts. The shift is compressing market share for conventional durable-polymer competitors that cannot demonstrate equivalent late lumen loss outcomes.
REACH registration requirements for polymer constituent disclosure are reshaping European supply chain transparency obligations. Manufacturers must now document full chemical composition of drug-matrix formulations down to 0.1% weight thresholds. Stent coating subcontractors in Germany and Ireland face accelerated compliance audits as notified bodies implement stricter substance scrutiny.
Hospital purchasing consortiums are consolidating stent procurement decisions across multi-hospital networks. Integrated delivery networks in the United States now mandate standardized platform specifications across all catheterization laboratories, displacing individual physician preference contracting. This concentration shifts negotiating leverage toward volume-commitment pricing models visible in California and Texas health system tenders.
Global Percutaneous Coronary Intervention (PCI) Devices Market Segmentation
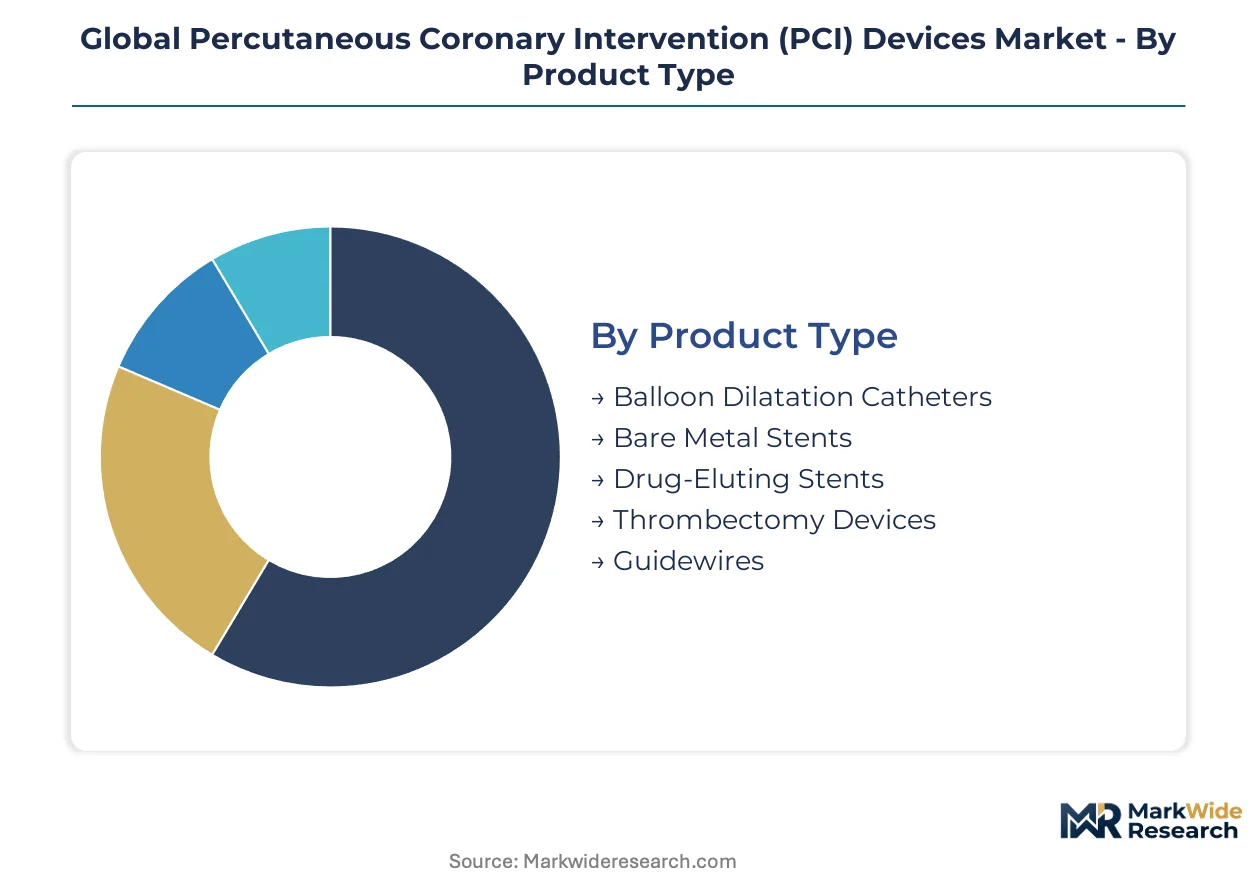
PCI device procurement committees evaluate segments through distinct clinical and economic lenses. Substitution threats from surgical revascularization and pharmaceutical therapy reshape investment priorities across product categories.
Product Type:
Drug-eluting stents face intensifying substitution pressure from bioabsorbable platforms, while bare metal stents confront pricing compression from value-based reimbursement frameworks.
- Drug-Eluting Stents:Polymer matrices elute sirolimus analogs over 3-12 month release kinetics to suppress neointimal proliferation. German cardiac centers prioritize these platforms for complex bifurcation lesions, though Japan's PMDA reimbursement mandates extend commercialization timelines.
- Bare Metal Stents:Cobalt-chromium alloy scaffolds without drug matrices serve cost-sensitive patient cohorts and high-bleeding-risk cases. Demand concentrates in Indian tier-2 cities where cath lab infrastructure buildout favors economical platforms for initial procedure volumes.
- Balloon Dilatation Catheters:Semi-compliant and non-compliant balloon platforms enable predilation and postdilation protocols across all PCI procedures.
- Thrombectomy Devices:Aspiration catheters and mechanical thrombectomy systems address acute myocardial infarction with large thrombus burden.
- Guidewires:Hydrophilic and hydrophobic coated wires navigate tortuous coronary anatomy, with specialized CTO wires commanding premium tiers.
Drug-eluting stents retain volume leadership; bioabsorbable polymer iterations hold the steepest expansion curve.
Technology:
Cost tiers stratify sharply between premium bioabsorbable platforms and commodity metallic alternatives, with reimbursement differentials determining hospital formulary placement.
- Bioabsorbable Polymers:Transient scaffolds of poly-L-lactic acid restore lumen patency before complete resorption within 24-36 months. Academic medical centers in the Netherlands and United States adopt these for vessel healing endpoints, though durability concerns persist in complex lesions.
- Metallic Alloys:Cobalt-chromium and platinum-iridium platforms dominate volume production through proven long-term structural integrity. Supply concentration in German and Irish manufacturing clusters exposes margins to noble metal price volatility.
- Drug-Coated:Abluminal coating techniques deliver antiproliferative agents without durable polymer inflammation risks.
- Radiopaque Markers:Tantalum or platinum marker bands enhance fluoroscopic visualization during deployment.
- Self-Expanding Stents:Nitinol superelastic platforms address specific anatomical challenges outside standard balloon-expandable indications.
Metallic alloys dominate procedure volume; bioabsorbable platforms command the highest per-procedure value capture.
Application:
Procedure volume clusters around emergent presentations, with stable elective cases facing intensifying pharmaceutical substitution and conservative management protocols.
- Acute Myocardial Infarction:Primary PCI within 90 minutes of first medical contact drives emergency cath lab activation protocols. United States cardiac centers maintain 24/7 interventional teams, with door-to-balloon metrics determining accreditation status.
- Chronic Total Occlusion:Complete vessel occlusion exceeding three months requires specialized guidewire escalation strategies and retrograde techniques. German interventional networks concentrate CTO expertise in high-volume reference centers, creating training bottlenecks for community hospitals.
- Stable Angina:Elective revascularization faces scrutiny from ischemia trial data favoring optimal medical therapy.
- Restenosis Treatment:In-stent restenosis drives repeat intervention with drug-coated balloon or alternate stent platform.
- Coronary Artery Disease:Broad indication encompassing all atherosclerotic coronary presentations.
Coronary artery disease captures the widest indication breadth; chronic total occlusion generates the highest per-case device utilization.
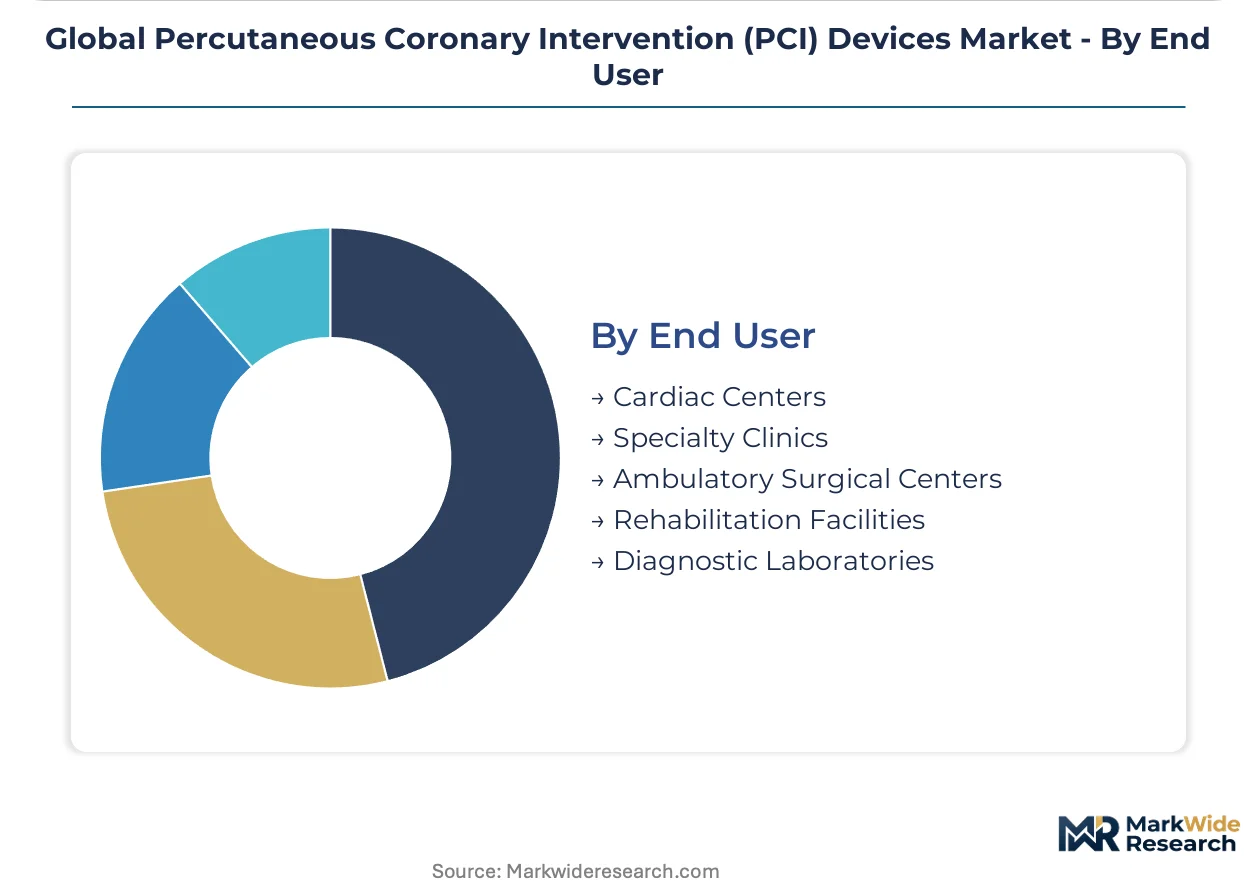
End User:
Customer type determines procurement scale and contracting leverage, with integrated delivery networks consolidating purchasing decisions across multi-hospital systems.
- Cardiac Centers:Dedicated catheterization laboratories perform high-volume PCI with specialized interventional cardiologist staffing. Texas and California health systems mandate standardized stent specifications across all labs, displacing individual physician preference.
- Ambulatory Surgical Centers:Outpatient PCI facilities in the United States pursue same-day discharge protocols under CMS reimbursement frameworks. Lower fixed costs enable competitive pricing for stable angina cases, though emergency backup requirements limit expansion.
- Specialty Clinics:Focused interventional cardiology practices concentrate elective procedures.
- Rehabilitation Facilities:Post-procedure cardiac recovery centers coordinate secondary prevention.
- Diagnostic Laboratories:Non-invasive testing centers refer appropriate candidates for intervention.
Cardiac centers absorb the dominant procedure share; ambulatory surgical centers gain volume fastest where regulatory frameworks permit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing clusters and United States cardiac centers concentrate PCI device production capacity and high-volume procedure demand. Regulatory fragmentation across FDA, EMA, and PMDA jurisdictions shapes divergent commercialization pathways. Emerging cath lab buildout in Indian tier-2 cities and Chinese metropolitan hospitals is redistributing volume growth geographically.
United States
Integrated delivery networks in Texas and California consolidate stent procurement across multi-hospital systems, mandating standardized platform specifications. FDA's 510(k) premarket notification pathway accelerates Class II cardiovascular device commercialization for manufacturers seeking rapid cath lab entry. Academic medical centers in Boston and the Midwest adopt polymer-free drug-eluting platforms for high-bleeding-risk patient cohorts.
Germany
Specialized interventional cardiology networks support high-volume PCI procedures with concentrated chronic total occlusion expertise in reference centers. EMA's Medical Device Regulation imposes extended post-market surveillance obligations and REACH registration requirements for polymer constituent disclosure down to 0.1% weight thresholds. Manufacturing clusters in Baden-Württemberg and Bavaria supply cobalt-chromium alloy platforms to cardiac centers across multiple continents.
Japan
PMDA mandates Japan-specific clinical data for stent reimbursement eligibility, fragmenting regulatory access pathways and extending trial investment thresholds for foreign manufacturers. Domestic cardiac centers maintain stringent door-to-balloon metrics for primary PCI activation protocols. Tokyo and Osaka metropolitan hospitals concentrate complex procedure volumes while regional centers face training bottlenecks for guidewire escalation techniques.
India
Tier-2 and Tier-3 cities lack interventional cardiology capacity, creating first-mover advantage for device distributors establishing training networks and cath lab infrastructure. CDSCO regulatory pathways for cardiovascular device import and distribution determine market access timelines for multinational manufacturers. Maharashtra and Gujarat manufacturing zones produce economical bare metal stent platforms for cost-sensitive initial procedure volumes.
China
NMPA regulatory harmonization efforts accelerate domestic stent platform approvals while central procurement reforms compress pricing tiers across public hospital networks. Yangtze River Delta and Pearl River Delta metropolitan clusters drive cath lab expansion with government-funded cardiovascular disease screening programs. Local manufacturers compete on metallic alloy platform cost structures against multinational polymer coating technologies.
Global Percutaneous Coronary Intervention (PCI) Devices Market Competitive Landscape
Concentration sits with diversified medtech conglomerates possessing integrated vascular access platforms and proprietary polymer coating technologies. Three structural tiers define competitive positioning: multinational device conglomerates with cath lab ecosystem control, specialized interventional cardiology firms with guidewire and microcatheter expertise, and regional manufacturers competing on metallic alloy platform economics. Dominant competitive moves include strategic partnerships with hospital purchasing consortiums and backward integration into noble metal alloy supply chains.
Among diversified medtech conglomerates, Boston Scientific and Abbott exemplify platform-integrated competitors with cath lab loyalty programs, while Medtronic occupies a position emphasizing global manufacturing scale. Japanese specialists ASAHI INTECC and Terumo Corporation sit within the guidewire and microcatheter tier, anchoring complex lesion navigation capabilities. German manufacturer BIOTRONIK represents the European-centered archetype with bioabsorbable polymer R&D focus. These named entities illustrate how competitive positioning fragments across technology vectors rather than consolidating around uniform scale advantages.
| Leading Market Players |
|---|
| Boston Scientific |
| Abbott |
| Medtronic |
| Cordis |
| Terumo Corporation |
| B. Braun |
| BIOTRONIK |
| ASAHI INTECC |
| Meril Life Sciences |
| Others |
Supply & Pricing Matrix
Cath lab capacity utilization rates above 85% in German and United States cardiac centers create scale economies that compress per-procedure device costs while concentrating procurement leverage among high-volume hospital networks. This utilization density shapes both supply concentration in manufacturing clusters and price floors that commodity competitors struggle to breach.
Pricing Analysis
EMA's Medical Device Regulation dictates the pricing tier structure across European cardiac centers, with CE marking tiers separating premium bioabsorbable scaffolds from standard metallic platforms and economy bare metal alternatives. Price differentiation rests on polymer coating certification grades and Japan-specific clinical data completeness. Cost compression in the economy tier is intensifying because Indian tier-2 cath labs prioritize bare metal platforms for initial procedure volumes. Ambulatory surgical centers exhibit the highest price sensitivity, while academic medical centers in Boston and the Netherlands accept premiums for polymer-free drug-eluting technologies.
Supply Chain Analysis
Strait of Malacca transit routes underpin cobalt-chromium alloy shipments from German Baden-Württemberg manufacturing clusters to Asian cardiac centers. Supply concentration spans Germany, Ireland, and Maharashtra for metallic platforms, with poly-L-lactic acid bioabsorbable polymers sourcing from Netherlands and United States specialty chemical producers. Noble metal price volatility in platinum-iridium markets creates margin compression risks for balloon-expandable platform manufacturers. Distribution runs through hospital purchasing consortiums and integrated delivery networks that mandate standardized specifications across multi-lab systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Complex chronic total occlusion procedure expertise concentrates in fewer than 200 global reference centers, creating acute skill scarcity that shapes competitive defensibility and acquisition premiums across the interventional cardiology value chain.
For Market Incumbents: Consolidate cath lab loyalty through integrated vascular access platform contracts that bundle guidewire, microcatheter, and stent procurement decisions. Backward integration into cobalt-chromium alloy supply chains in German manufacturing zones defends margin position against noble metal input volatility. Priority investment in polymer-free coating R&D addresses the substitution threat from bioabsorbable scaffold durability improvements. For New Entrants and Emerging Players: Anchor in Indian tier-2 and tier-3 city cath lab infrastructure buildout, where interventional cardiology capacity gaps exceed 60% of addressable procedural demand. White-space targets include economical bare metal stent platforms for cost-sensitive initial volumes and specialized CTO guidewire training networks that transfer skills from German reference centers. Go-to-market execution partners with Maharashtra and Gujarat domestic manufacturers for CDSCO regulatory pathway navigation. For Investors and Strategic Acquirers: Guidewire and microcatheter specialists with complex lesion navigation capabilities represent the highest-conviction acquisition archetype, as these assets command premium positioning in chronic total occlusion procedure growth. Long-term viability hinges on demonstrating durable vessel healing outcomes that secure payer coverage across EMA and FDA jurisdictions. Signal to monitor: bioabsorbable scaffold durability data publication timelines that could reset competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerated Class II cardiovascular device commercialization compresses time-to-revenue for manufacturers targeting United States cath lab entry. |
| CE Marking Pathway | EMA MDR compliance and REACH polymer disclosure requirements determine European market access eligibility and liability exposure timelines. |
| Hospital System Partnership | Integrated delivery network standardization mandates in Texas and California consolidate procurement leverage toward volume-commitment contracting. |
| Software Companion Development | Optical coherence tomography guidance integration enables personalized antiproliferative dosing protocols that differentiate stent platform outcomes. |
| Reimbursement Strategy | PMDA Japan-specific clinical data generation secures stent reimbursement eligibility in the world's third-largest interventional cardiology market. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submissions, hospital GPO contract databases, and CMS Medicare reimbursement data. Interviews with interventional cardiologists, cath lab purchasing committee chairs, biomedical engineers, and GPO contracts managers informed procedural volume and device utilization assumptions. Bottom-up stent deployment forecasts triangulate against top-down cardiac center capacity expansion plans across the analysis window.
Segmentation dimensions modeled include product type, technology platform, application indication, and end-user facility category across the projection horizon. CAGRs derive from procedure volume growth trajectories, device ASP evolution patterns, and cath lab infrastructure buildout pipelines. Forecast inputs incorporate chronic total occlusion intervention complexity premiums, bioabsorbable scaffold durability data publication schedules, and polymer-free coating adoption curves in high-bleeding-risk patient cohorts.
Material uncertainties — bioabsorbable scaffold long-term vessel healing outcomes, noble metal alloy supply disruptions, and PMDA reimbursement pathway modifications — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory approval timelines and payer coverage decisions that practitioners should keep alternative scenarios live as clinical evidence generation and procurement consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Ventricular Drainage Sets Market