
 Percutaneous Coronary Intervention Market | 2026-2036
Percutaneous Coronary Intervention Market Size, Share, and Industry Trends Forecast 2026-2036
Percutaneous Coronary Intervention Market Outlook
A shift from single-source to multi-source procurement of coronary stents and guidewires is restructuring supply relationships between hospitals and device manufacturers. Boston Scientific Corporation leverages its broad interventional portfolio to sustain cath lab loyalty across integrated delivery networks. Abbott Laboratories anchors its position through proprietary drug-eluting stent architectures that differentiate on restenosis metrics.
Percutaneous coronary intervention denotes a minimally invasive cardiology procedure involving catheter-based revascularization of stenotic coronary arteries, typically deploying balloon dilation followed by metallic or bioresorbable stent implantation under fluoroscopic guidance. The technique restores myocardial perfusion without thoracotomy, reducing recovery intervals versus coronary artery bypass grafting. Stent platforms command the dominant product value pool given their recurring implant volumes and premium pricing tiers, while balloon catheters represent a mature segment with compressed margins and consolidated supplier bases. Transradial delivery mode gains procedural share as operators prioritize access-site bleeding reduction and same-day discharge protocols.
FDA premarket approval pathways govern coronary stent safety and efficacy claims through mandated clinical trial endpoints, while EU MDR technical documentation requirements extend conformity assessment timelines for manufacturers seeking CE marking renewal. Japan's PMDA maintains distinct pharmaceutical and medical device agency review standards that condition market entry sequencing for Western device firms. Stakeholders must monitor evolving health technology assessment criteria from Germany's Federal Joint Committee and Japan's Chuikyo as these bodies increasingly tie reimbursement to comparative effectiveness evidence against optimal medical therapy.
Market Dynamics
Transradial access protocols are compressing hospital length-of-stay metrics and forcing cath lab workflow redesigns across integrated delivery networks. This procedural pivot demands synchronized investment in operator training, disposable inventory restructuring, and same-day discharge infrastructure.
Growth Catalysts
- Drug-eluting stent iterations:Polymer biocompatibility advances and limus-analog formulations reduce target lesion revascularization rates. Cardiac centers in Germany and Japan prioritize these platforms in device selection protocols.
- FDA breakthrough device designation:Expedited review pathways for bioresorbable scaffolds compress time-to-market for novel coronary platforms. Manufacturers leverage this mechanism to secure conditional coverage during pivotal trial enrollment.
- Aging demographics in Japan:PMDA reimbursement stability for PCI procedures sustains intervention volumes among patients over 75. Prefecture-level cardiac networks expand transradial capacity to manage throughput.
Market Restraints
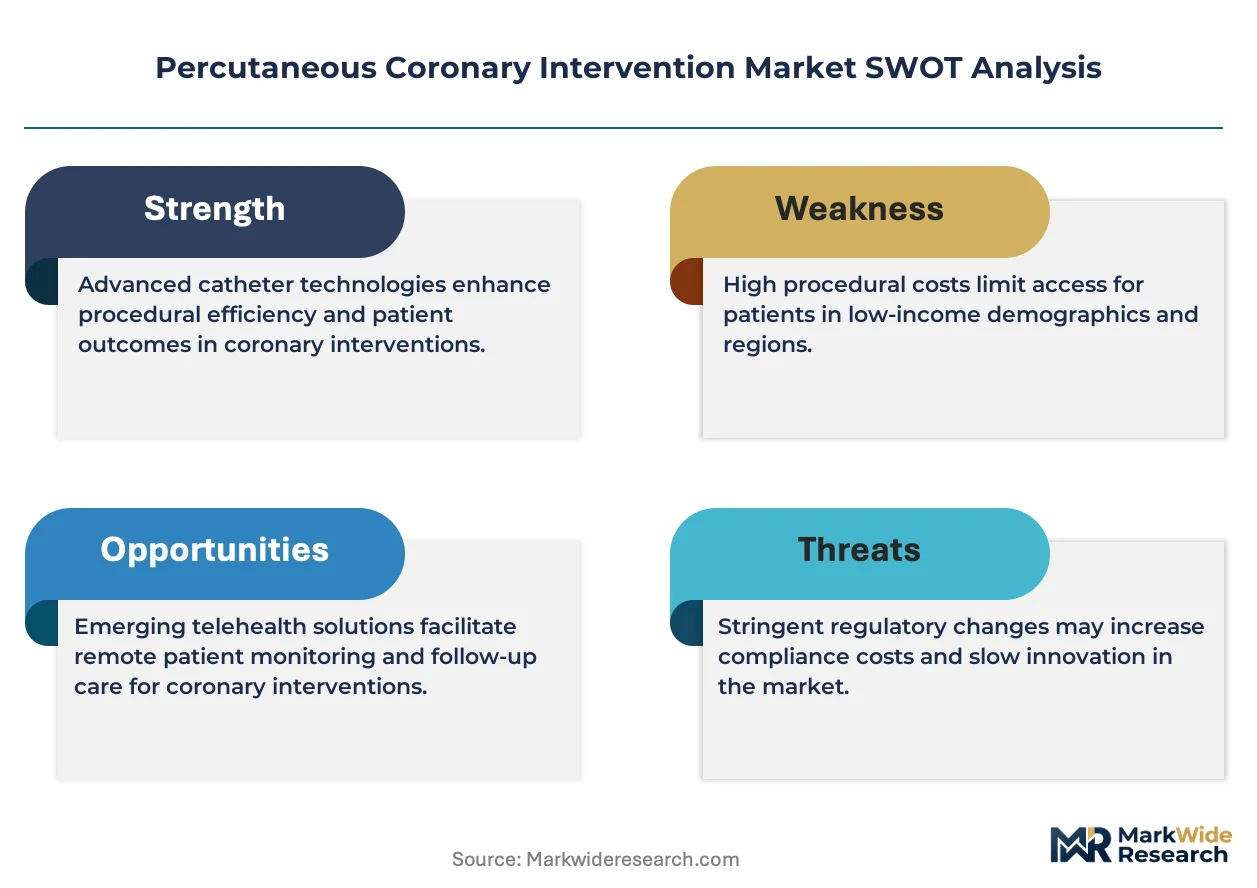
- Platinum-iridium alloy concentration:Stent manufacturing depends on concentrated precious metal supply chains vulnerable to price volatility. Foundry capacity in select geographies constrains rapid volume scaling.
- EU MDR technical documentation:Extended conformity assessment timelines for CE marking renewal delay product launches. Notified body capacity bottlenecks create 12-18 month approval backlogs for Class III devices.
- Optimal medical therapy substitution:Aggressive pharmacologic management with high-intensity statins and PCSK9 inhibitors reduces anatomically appropriate PCI referrals. Cardiology guidelines increasingly emphasize conservative strategies for stable ischemic disease.
Strategic Opportunities
- Bioresorbable scaffold platforms:Magnesium-based and polymeric vascular scaffolds eliminate permanent metal caging. Early adopters in German university hospitals drive clinical evidence generation for health technology assessment submissions.
- Intravascular imaging integration:Optical coherence tomography and intravascular ultrasound converge with stent delivery systems. This technology pairing enables lesion-specific device sizing and optimizes acute procedural outcomes.
- Hub-and-spoke cath lab networks:Regionalization of PCI capacity concentrates complex cases in high-volume centers. Community hospitals in the United States affiliate with academic medical centers for emergency transfer protocols.
Industry Challenges
- Operator skill stratification:Transradial proficiency requires dedicated proctoring and volume thresholds for competency maintenance. Smaller cardiac programs struggle to retain interventional cardiologists with advanced access expertise.
- Health technology assessment evidence requirements:Germany's Federal Joint Committee and Japan's Chuikyo demand comparative effectiveness data against optimal medical therapy. Manufacturers face extended timeline and cost burdens for reimbursement dossier preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Percutaneous Coronary Intervention Market |
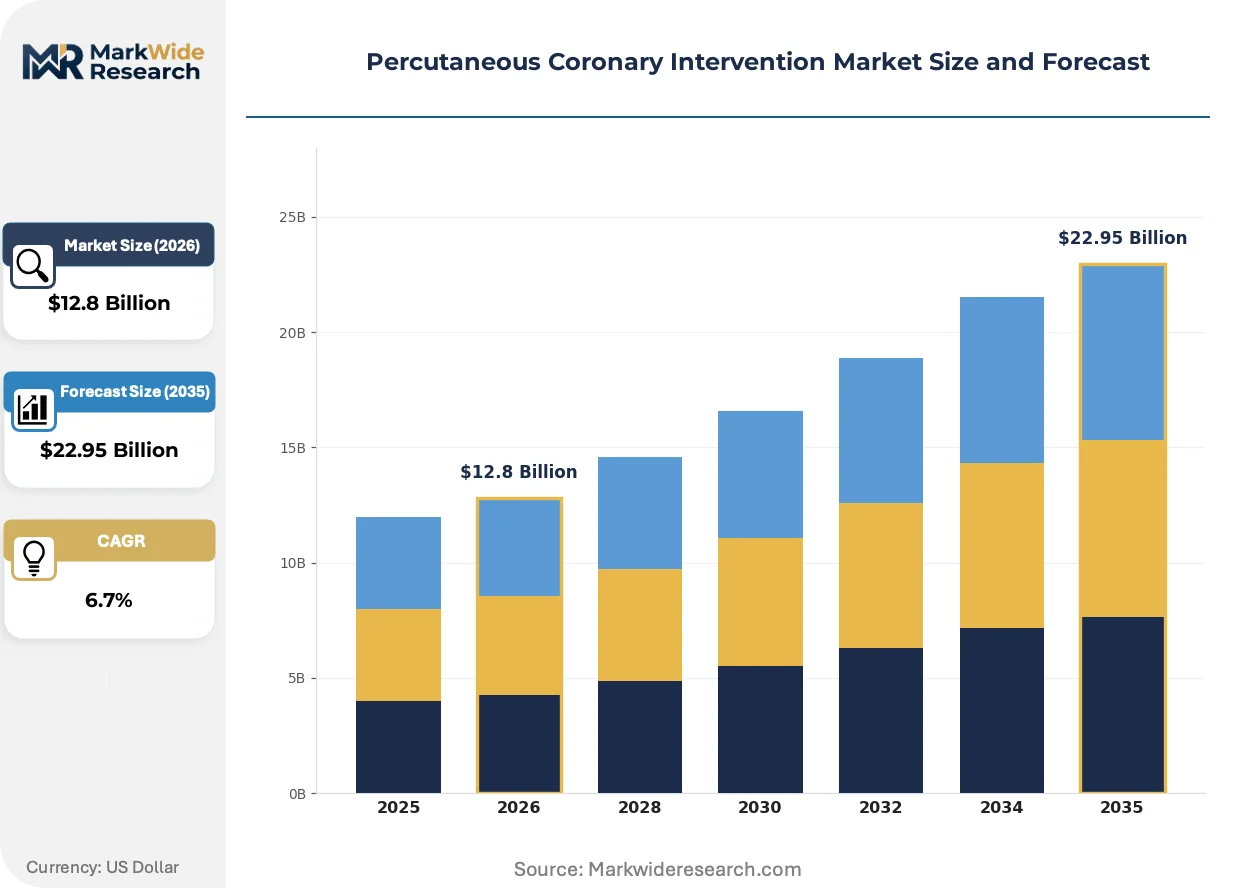
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Stents, Guidewires, Closure Devices Delivery Mode: Transradial, Transfemoral, Direct Access, Other End User: Hospitals, Cardiac Centers, Outpatient Facilities, Ambulatory Surgical Centers Procedure Type: Elective PCI, Urgent PCI, Emergency PCI, Diagnostic PCI |
| Companies Covered | Boston Scientific Corporation, Abbott Laboratories, Medtronic PLC, Terumo Corporation, B. Braun Melsungen AG, ASAHI INTECC Company Limited, Biosensors International Group, Ltd, Johnson & Johnson, Meril Lifesciences Pvt. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Percutaneous Coronary Intervention Market Strategic Shifts
Coronary intervention platforms are converging with physiologic assessment tools and intravascular imaging to enable precision revascularization. This integration demands new data infrastructure and operator workflow adaptation.
Polymer-free drug-eluting stents are unifying the mechanical scaffolding function with controlled antiproliferative release while eliminating chronic inflammatory triggers from durable polymers. High-volume cardiac centers in Germany and Japan adopt these platforms for complex lesion subsets including diabetes mellitus and small vessel disease. The technology is unifying previously separate device categories into single-procedure solutions, compressing supplier bases and rewarding integrated platform manufacturers.
EU MDR Article 54 clinical evaluation consultation procedures extend review timelines for novel coronary stent submissions. Manufacturers must demonstrate equivalence to predicate devices or generate new clinical evidence through prospective trials. Small and mid-sized device firms face disproportionate compliance costs, accelerating consolidation toward integrated cardiovascular portfolios.
Hospital purchasing cooperatives consolidate stent and guidewire procurement across multi-hospital systems. Integrated delivery networks in the United States negotiate multi-year supply agreements with performance guarantees on restenosis metrics. This concentration shifts bargaining power toward large health systems and compresses margins for standalone device suppliers.
Percutaneous Coronary Intervention Market Segmentation
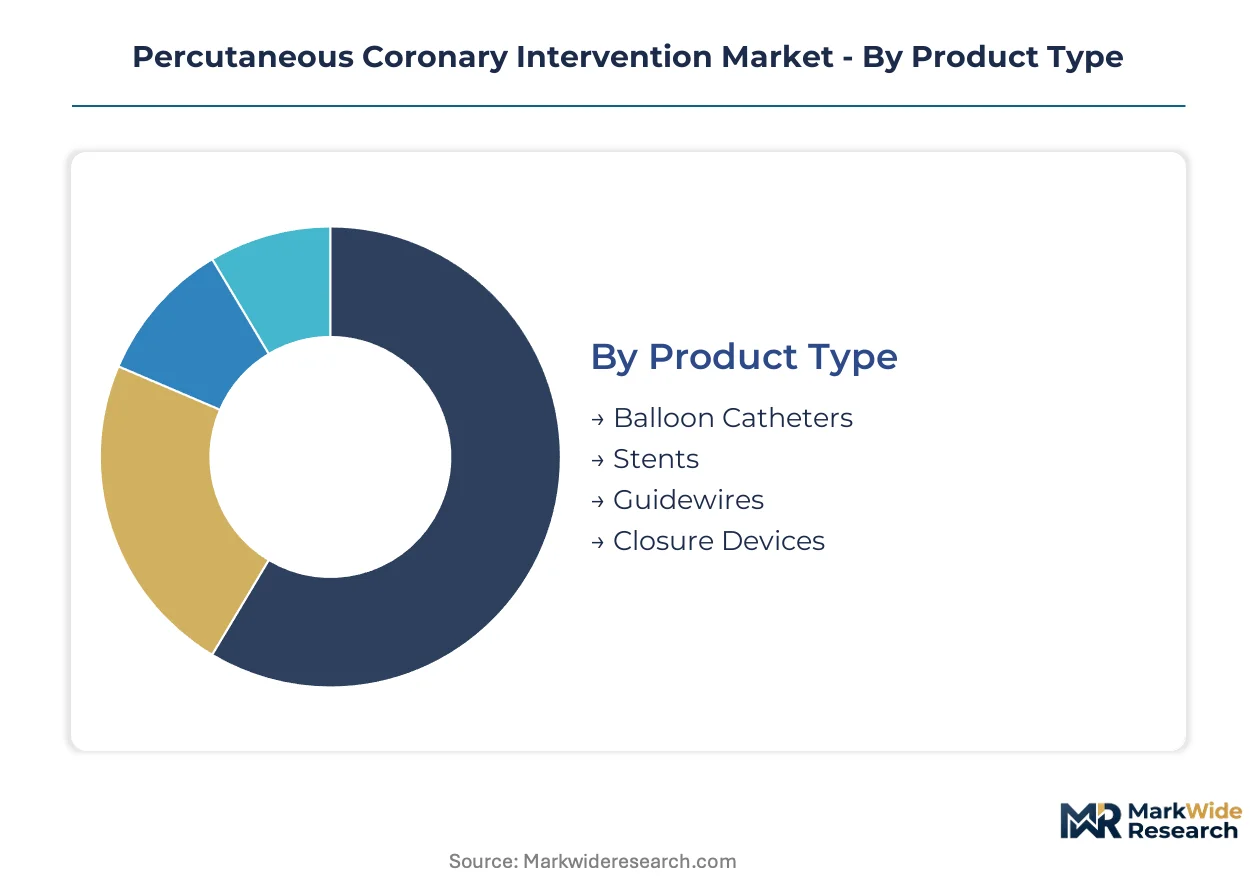
PCI market segmentation reveals distinct value capture mechanisms across implantable devices, procedural techniques, and care settings. Manufacturers optimize portfolio depth against reimbursement tiers while cath labs reconfigure workflows around access-site preferences and case-mix stratification.
Product Type:
Customization intensity varies sharply across this category, from patient-specific stent sizing to commoditized balloon platforms.
- Stents:Drug-eluting and bioresorbable platforms dominate revenue concentration through polymer-controlled limus-analog release kinetics. German cardiac centers and Japanese prefectural networks prioritize these devices for complex lesion subsets including diabetes mellitus and small vessel disease, driven by restenosis-rate guarantees in hospital purchasing agreements.
- Balloon Catheters:Semi-compliant and non-compliant dilatation systems represent a mature manufacturing segment with compressed margins and consolidated supplier bases. US integrated delivery networks negotiate multi-year supply agreements with performance thresholds, forcing standardization across cath lab inventories.
- Guidewires:Hydrophilic-coated and torque-responsive designs enable lesion crossing in tortuous anatomy.
- Closure Devices:Vascular sealing systems support transradial same-day discharge protocols.
Leading the category by volume: Stents. Expanding most quickly: Bioresorbable scaffold variants within stent portfolios.
Delivery Mode:
Volume distribution across this category tracks operator training investment and infrastructure retrofit requirements.
- Transradial:Radial artery access compresses hospital length-of-stay metrics and enables same-day discharge protocols. Japanese prefecture-level cardiac networks expand transradial capacity to manage throughput among patients over 75, supported by PMDA reimbursement stability for PCI procedures.
- Transfemoral:Femoral access retains dominance in complex multivessel interventions requiring large-bore catheter support. US academic medical centers maintain transfemoral backup capacity for emergency transfer protocols from community hospital affiliates.
- Direct Access:Brachial or ulnar alternatives serve anatomically variant patients.
- Other:Hybrid access strategies accommodate specific lesion locations.
Dominant by procedure count: Transradial. Steepest expansion trajectory: Transradial as operators complete dedicated proctoring programs.
End User:
Capital intensity and regulatory accreditation requirements stratify this category across facility types.
- Hospitals:Tertiary centers concentrate complex PCI capacity with 24/7 surgical backup and intravascular imaging infrastructure. Hub-and-spoke regionalization in the United States drives affiliation between community hospitals and academic medical centers for emergency transfer protocols.
- Cardiac Centers:Dedicated catheterization laboratories achieve volume thresholds for operator competency maintenance. German university hospitals generate clinical evidence for health technology assessment submissions, particularly for bioresorbable scaffold platforms.
- Outpatient Facilities:Limited-service sites handle diagnostic catheterization and stable elective cases.
- Ambulatory Surgical Centers:ASCs capture low-complexity elective PCI under selective reimbursement carve-outs.
Highest procedure volume: Hospitals. Gaining share fastest: Cardiac centers as hub-and-spoke networks formalize.
Procedure Type:
Clinical urgency determines device selection latitude and supply chain responsiveness requirements.
- Emergency PCI:ST-elevation myocardial infarction protocols demand immediate device availability and operator mobilization. US cath lab networks maintain platinum-iridium alloy stent inventory buffers despite precious metal supply chain concentration risks.
- Elective PCI:Scheduled stable ischemic disease interventions permit pre-procedure intravascular imaging and physiologic assessment. Germany's Federal Joint Committee ties reimbursement to comparative effectiveness evidence against optimal medical therapy, extending case planning timelines.
- Urgent PCI:Non-ST-elevation acute coronary syndrome cases require rapid but not emergent resource deployment.
- Diagnostic PCI:Coronary angiography without intervention establishes lesion significance.
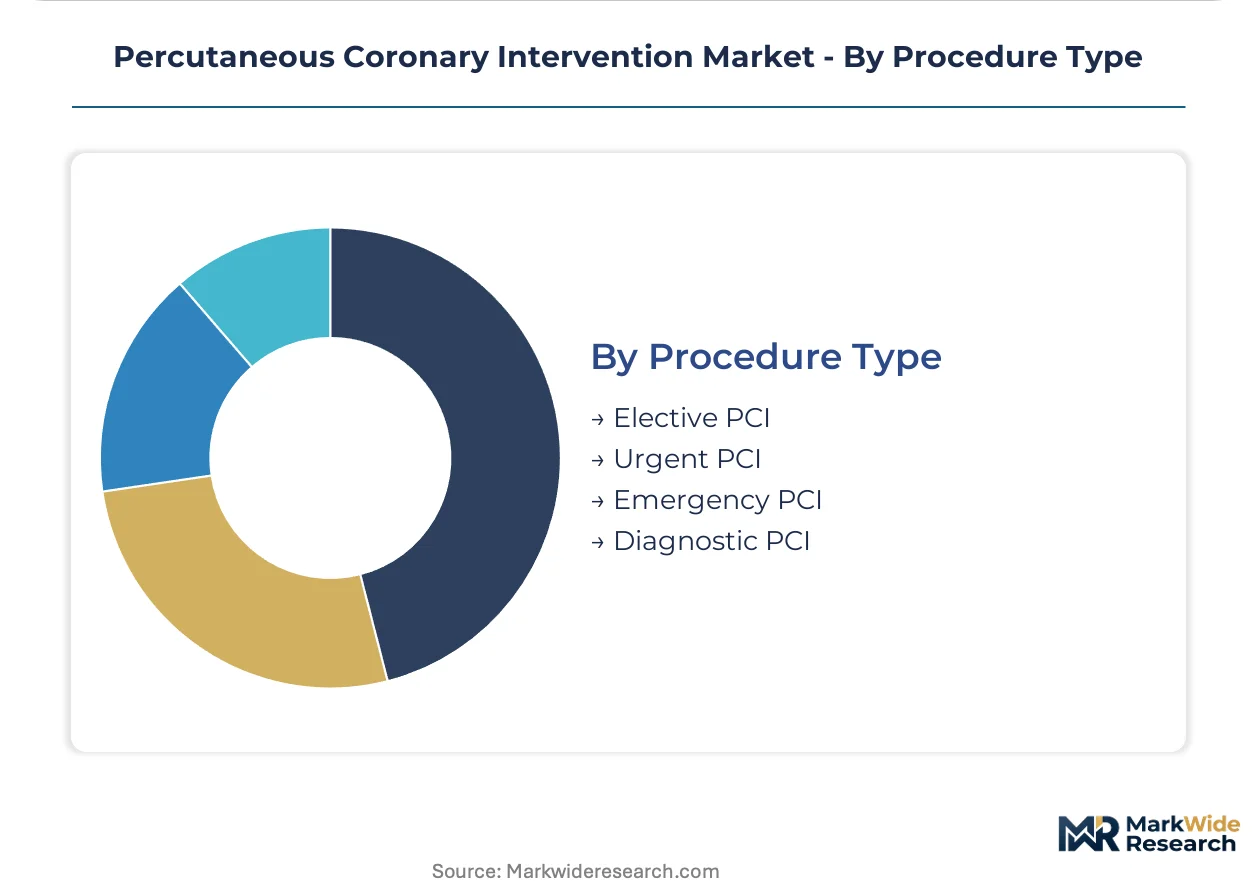
Largest volume share: Elective PCI. Climbing the fastest: Emergency PCI as regional networks reduce door-to-balloon times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-iridium alloy foundry capacity in Germany anchors European stent manufacturing. Japanese prefectural networks expand transradial capacity for aging cohorts. US integrated delivery networks consolidate procurement across multi-hospital systems.
United States
FDA premarket approval pathways govern coronary stent safety claims through mandated clinical trial endpoints. Hospital purchasing cooperatives negotiate multi-year supply agreements with performance guarantees on restenosis metrics. Academic medical centers in Boston and Cleveland maintain 24/7 surgical backup for complex PCI capacity.
Germany
German cardiac centers prioritize polymer-free drug-eluting stents for diabetes mellitus and small vessel disease subsets. The Federal Joint Committee ties reimbursement to comparative effectiveness evidence against optimal medical therapy. University hospitals in Munich and Heidelberg generate clinical evidence for bioresorbable scaffold health technology assessment submissions.
Japan
PMDA reimbursement stability for PCI procedures sustains intervention volumes among patients over 75. Prefecture-level cardiac networks in Tokyo and Osaka expand transradial capacity to manage throughput. Chuikyo increasingly ties device reimbursement to comparative effectiveness evidence requirements.
China
NMPA review standards condition market entry sequencing for Western device firms through distinct pharmaceutical and medical device pathways. Provincial hospital systems concentrate PCI capacity in tier-one cities including Beijing and Shanghai. Centralized procurement pilots compress stent pricing tiers across public health networks.
Switzerland
Swissmedic maintains rigorous conformity assessment timelines for CE marking recognition through bilateral agreements with EU notified bodies. Precision manufacturing clusters in Basel and Zurich supply catheter components to integrated cardiovascular portfolios. Cantonal hospital networks affiliate with German university centers for complex case transfers.
Percutaneous Coronary Intervention Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers unify drug-eluting stent platforms with intravascular imaging systems. The vendor base concentrates around integrated cardiovascular portfolios with full cath lab coverage. Three archetypes define competitive positioning: diversified multinationals with broad interventional portfolios, specialized stent-focused manufacturers, and regional suppliers with cost-optimized balloon catheter lines. M&A activity and strategic technology licensing represent the dominant competitive moves for capability gaps.
Among US-based diversified multinationals, Boston Scientific Corporation and Abbott Laboratories exemplify integrated portfolio strategies. Boston Scientific leverages its broad interventional portfolio to sustain cath lab loyalty across integrated delivery networks. Abbott Laboratories anchors its position through proprietary drug-eluting stent architectures. Japanese specialist Terumo Corporation occupies a distinct position representing precision guidewire and catheter expertise.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Abbott Laboratories |
| Medtronic PLC |
| Terumo Corporation |
| B. Braun Melsungen AG |
| ASAHI INTECC Company Limited |
| Biosensors International Group, Ltd |
| Johnson & Johnson |
| Meril Lifesciences Pvt. Ltd |
| Others |
Value Chain & Pricing Dynamics
Drug-eluting stent premium tiers diverge sharply from commodity balloon catheter pricing, with the former commanding restenosis-rate guarantees and the latter facing compressed margins through consolidated supplier bases. This bifurcation manifests in divergent procurement strategies: integrated delivery networks negotiate multi-year performance contracts for stent platforms while standardizing balloon inventories across cath labs, and supply chain configurations mirror this split through captive precious metal foundries for alloy stents versus outsourced polymer extrusion for balloon components.
Pricing Analysis
Warranty-bundled restenosis guarantees differentiate premium drug-eluting stent pricing from unbundled commodity balloon platforms. Three-tier pricing structure across premium, standard, and economy levels tracks polymer biocompatibility grades and limus-analog release kinetics, with FDA breakthrough designation conferring brand premiums. Cost compression in balloon catheters intensifies because US hospital purchasing cooperatives consolidate volumes across multi-hospital systems. Community hospital affiliates exhibit highest price sensitivity due to constrained cath lab budgets, while academic medical centers prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for platinum-iridium alloy stent delivery. Manufacturing draws from concentrated precious metal foundries in Germany, polymer substrate suppliers in Japan, and catheter component clusters in Switzerland. Single-source vulnerability in platinum-iridium alloy supply creates exposure to price volatility and foundry capacity constraints. Distribution runs through hospital purchasing cooperatives and integrated delivery network central warehouses, with emergency PCI protocols mandating localized inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment timelines function as a cost-of-compliance moat, extending 12-18 month approval backlogs that disproportionately burden mid-sized device firms and accelerate consolidation toward integrated cardiovascular portfolios with dedicated regulatory affairs infrastructure.
For Market Incumbents: To counter optimal medical therapy substitution reducing anatomically appropriate PCI referrals, incumbents should deepen backward integration into platinum-iridium alloy foundry capacity to secure supply continuity, and invest in intravascular imaging convergence with stent delivery systems to capture lesion-specific device sizing premiums. For New Entrants and Emerging Players: Direct-to-cath-lab digital procurement platforms offer the most penetrable route for bioresorbable scaffold specialists seeking bypass of established GPO contracts. White-space targets include German university hospitals generating health technology assessment evidence and Japanese prefectural networks expanding transradial capacity for aging cohorts, with reimbursement dossier preparation services as the critical go-to-market wedge. For Investors and Strategic Acquirers: Re-rating potential sits with polymer-free drug-eluting stent specialists given Germany's Federal Joint Committee reimbursement criteria favoring comparative effectiveness evidence. Long-term viability hinges on regulatory approval velocity rather than manufacturing scale, with acquisition targets clustering around firms with EU MDR technical documentation readiness and PMDA submission track records. The signal to watch is FDA breakthrough device designation velocity as an inflection indicator for conditional coverage access.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 54 clinical evaluation consultation compresses time-to-market for novel stent platforms through notified body pre-submission. |
| Hospital System Partnership | Integrated delivery network multi-year supply agreements with restenosis performance guarantees lock in cath lab loyalty across US cardiac centers. |
| Software Companion Development | Intravascular imaging integration with optical coherence tomography enables lesion-specific device sizing and optimizes acute procedural outcomes. |
| Reimbursement Strategy | Germany's Federal Joint Committee and Japan's Chuikyo comparative effectiveness evidence requirements condition market access for premium tiers. |
| FDA Submission | Breakthrough device designation expedites review pathways for bioresorbable scaffolds and secures conditional coverage during pivotal trial enrollment. |
Study Parameters
FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with interventional cardiologists, cath lab directors, GPO contracts managers, and biomedical engineers validated device adoption trends and pricing dynamics. Bottom-up procedure volume modeling across US integrated delivery networks, German cardiac centers, and Japanese prefectural networks combined with top-down manufacturer revenue triangulation to anchor value estimates.
Historical trendline analysis of PCI procedure volumes, stent implant rates, and device pricing trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product type hierarchy, delivery mode transition curves, end-user facility accreditation tiers, and procedure urgency stratification. CAGRs derived from weighted average of procedure volume growth and unit price elasticity assumptions, with specific inputs from aging demographic projections in Japan and transradial access protocol diffusion rates in Germany.
The model holds under stable PMDA and Federal Joint Committee reimbursement conditions; deviation in health technology assessment criteria or optimal medical therapy guideline revisions would shift volume trajectories. Forecasts reflect documented assumptions regarding cath lab expansion rates, operator training completion timelines, and precious metal supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Spain Cardiovascular Devices Market