
 Iliac Artery Stents Market | 2026-2036
Iliac Artery Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Iliac Artery Stents Market Analytics
Single-source reliance on captive nitinol supply is decoupling as manufacturers diversify toward multi-source procurement frameworks. Medtronic leverages backward integration into superelastic alloy processing to sustain cost advantages across its peripheral vascular portfolio. Abbott Laboratories anchors its competitive stance through polymer science leadership in drug-eluting platforms. Boston Scientific Corporation differentiates via controlled deployment systems that reduce procedural variability in tortuous iliac anatomies.
Iliac artery stents are tubular metallic or bioresorbable scaffolds deployed percutaneously to restore luminal patency in stenosed or occluded iliac vessels, typically manufactured from nitinol or cobalt-chromium alloys with strut thicknesses ranging from 0.003 to 0.006 inches. These devices function primarily to relieve claudication symptoms and prevent limb-threatening ischemia in peripheral artery disease patients. Self-expandable stents dominate procedural volumes in the external iliac segment where vessel tortuosity demands conformability, while drug-eluting stents capture concentrated margin pools in complex TASC C and D lesions requiring restenosis suppression. Balloon-expandable platforms lead in the common iliac ostium where radial strength and precise landing zone control prove critical.
FDA premarket approval pathways and CE marking under the EU MDR govern stent biocompatibility, fatigue resistance, and clinical validation requirements, directly shaping R&D allocation and market access timelines for manufacturers. ISO 25539-2 standards for vascular stents mandate radial force testing and corrosion resistance protocols that filter out undercapitalized entrants. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA breakthrough device designations as these regulatory levers increasingly determine which platforms achieve commercial traction ahead of competitors.
Market Dynamics
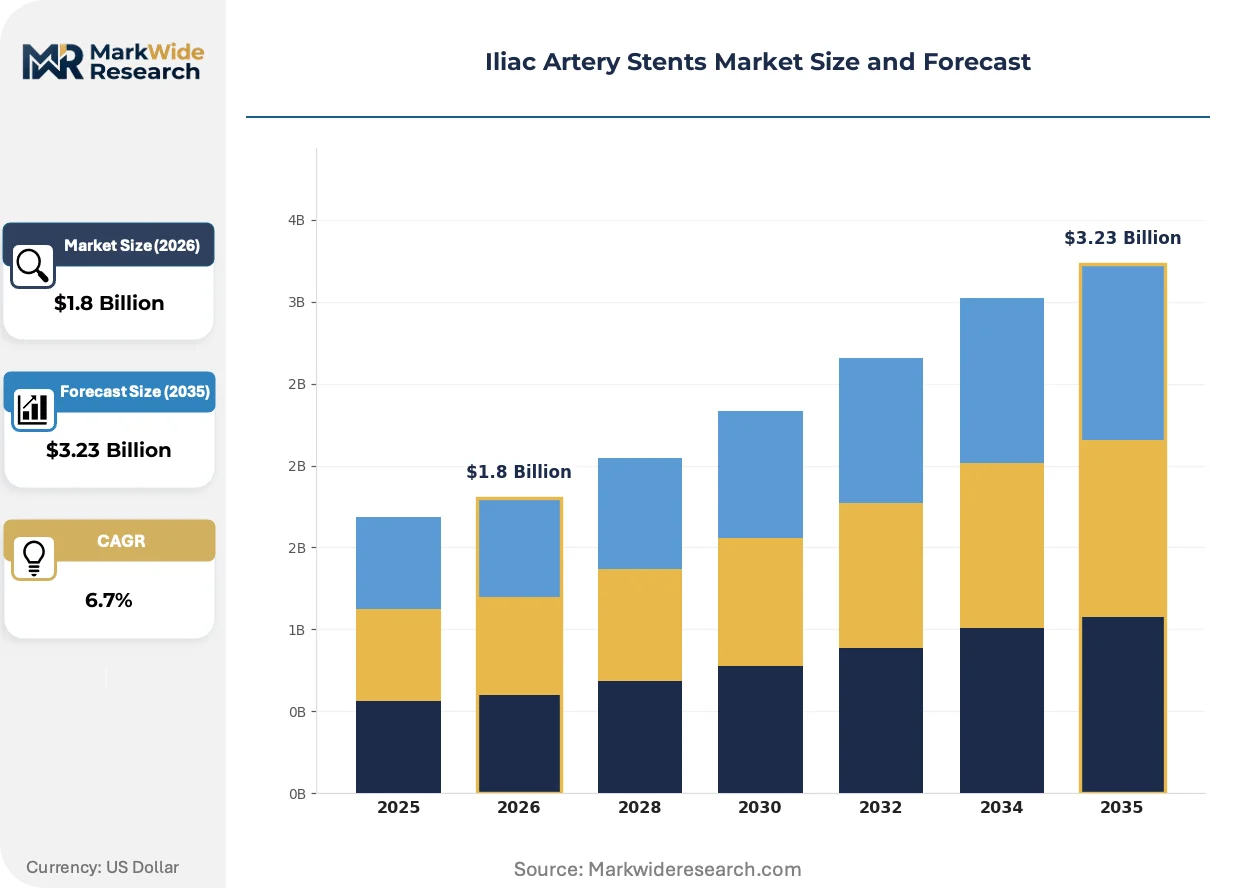
The Iliac Artery Stents Market pivots on the tension between EU MDR compliance timelines and nitinol supply chain reconfiguration, as manufacturers absorb 18-24 month certification delays while diversifying raw material sourcing away from single-origin dependencies.
Growth Catalysts
- EU MDR Transition Deadlines:The 2024-2026 notified body capacity squeeze accelerates consolidation among prepared manufacturers, filtering out undercapitalized competitors and concentrating commercial traction among CE-marking-ready platforms.
- Japan's Super-Aged Society:PMDA fast-track pathways for peripheral vascular devices expand addressable procedural volumes in a population where claudication prevalence exceeds 12% among adults over 70.
- Polymer Science Advancement:Bioabsorbable polymer coatings for drug-eluting stents reduce long-term inflammation risks, opening reimbursement pathways in Germany's Diagnosis-Related Group system for complex TASC C/D lesions.
Market Restraints
- Nitinol Price Volatility:Nickel-titanium alloy ingot costs fluctuate with Russian and Chinese rare earth export quotas, compressing gross margins for manufacturers lacking backward integration into superelastic wire processing.
- US FDA PMA Pathway Duration:Premarket approval timelines for novel stent designs extend 36-48 months, freezing R&D ROI calculations and deterring venture capital inflow into early-stage device developers.
- Balloon Angioplasty Resurgence:Drug-coated balloon technology for femoropopliteal disease captures procedural volumes in cost-constrained hospital systems, substituting stent placement in selected iliac anatomies.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentive corridors in Andhra Pradesh and Tamil Nadu offer 5-20% tariff concessions for domestic stent manufacturing, attracting contract manufacturers serving European markets.
- Bioresorbable Scaffold Convergence:Magnesium alloy platforms combined with sirolimus analogues promise complete vessel restoration without permanent metal cages, targeting younger patients with long life expectancy.
- Direct-to-Hospital Procurement Platforms:Digital tendering systems in France's AP-HP network and Germany's university hospital consortia disintermediate traditional distributor markups, capturing 8-12% price transparency gains.
Industry Challenges
- Interventional Cardiologist Training Bottlenecks:Complex iliac chronic total occlusion procedures require 200+ case volumes for proficiency, constraining adoption in community hospitals outside major metropolitan catheterization lab clusters.
- MDR Technical Documentation Burden:Clinical evaluation report requirements for legacy stent platforms demand retrospective patient registry mining, consuming 15-20 FTE months per device family.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iliac Artery Stents Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-expandable Stents, Balloon-expandable Stents, Drug-eluting Stents, Biodegradable Stents Material: Metal, Polymer, Composite, Coated Delivery Method: Percutaneous, Endovascular, Open Surgery, Hybrid Approach End User: Hospitals, Outpatient Clinics, Ambulatory Surgery Centers, Research Institutes |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, W. L. Gore & Associates, Cook, Becton Dickinson and Company, Terumo Corporation, Biotronik, Cordis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iliac Artery Stents Market Evolving Landscape
Device architecture and commercial models are diverging simultaneously. Manufacturers compress stent delivery profiles while procurement channels fragment across consolidated hospital networks and specialized endovascular centers.
Laser-cut nitinol stent platforms with closed-cell geometries are consolidating market share in tortuous external iliac anatomies. Interventionalists at high-volume centers in Milan, Munich, and Houston adopt these designs for TASC C lesions where conformability outweighs radial strength requirements. The technology is consolidating procurement decisions around three to four platform families, marginalizing older open-cell architectures.
EU MDR Article 117 requirements for drug-device combination products impose notified body consultation mandates on stent coating validations. Manufacturers now submit polymer biocompatibility data through EMA scientific advice pathways before CE marking, extending development timelines but reducing post-market surveillance liabilities. German notified bodies TÜV SÜD and DEKRA command 60% of vascular device certifications, creating queue bottlenecks.
Hospital procurement committees now mandate five-year total cost-of-ownership analyses replacing upfront device price comparisons. French public hospital groups and US integrated delivery networks weight reintervention rates, complication costs, and inventory carrying charges in vendor selection. This behavioral shift concentrates contract awards among manufacturers with robust real-world evidence registries, particularly visible in Kaiser Permanente's Northern California catheterization network.
Iliac Artery Stents Market Segmentation
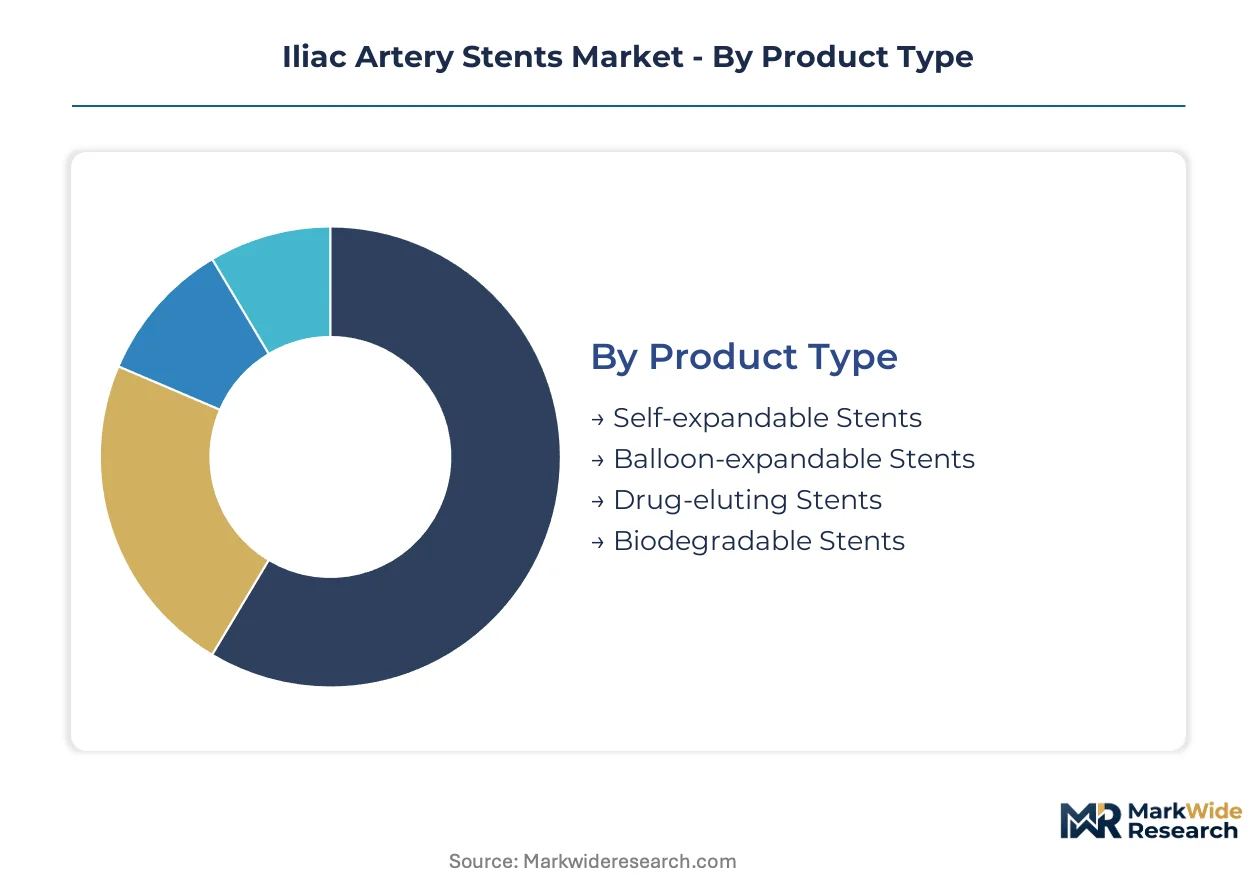
Iliac artery stent procurement hinges on matching mechanical properties to lesion complexity. Product architecture, material composition, and delivery approach each filter which platforms win approval from hospital catheterization committees.
Product Type:
Customization intensifies from standardized balloon-expandable platforms toward patient-specific drug-eluting configurations.
- Self-expandable Stents:Nitinol-based architectures deliver radial force through thermal shape memory, conforming to tortuous external iliac anatomies without balloon assistance. Demand clusters in German endovascular centers managing TASC C lesions where vessel curvature exceeds 45 degrees.
- Balloon-expandable Stents:Cobalt-chromium platforms deploy via controlled inflation, enabling precise landing zone placement at the common iliac ostium. US hospital systems prioritize these designs for calcified lesions requiring maximum radial strength.
- Drug-eluting Stents:Sirolimus or paclitaxel coatings suppress neointimal hyperplasia in complex TASC D disease. Polymer biocompatibility validations under EU MDR Article 117 extend certification timelines.
- Biodegradable Stents:Magnesium alloy scaffolds resorb within 12-24 months, appealing to younger patients with long life expectancy. PMDA fast-track pathways accelerate Japanese market entry.
Most installed capacity flows through self-expandable platforms. Expansion is steepest in drug-eluting configurations.
Material:
Cost tier stratification separates commodity metals from advanced polymer-composite hybrids commanding premium reimbursement.
- Metal:Nitinol and cobalt-chromium alloys dominate procedural volumes, with nickel-titanium superelastic wire processing concentrated among backward-integrated manufacturers.
- Polymer:Bioabsorbable lactide-glycolide copolymers enable temporary scaffolding without permanent foreign body retention, gaining traction in France's DRG reimbursement framework for complex lesions.
- Composite:Metal-polymer laminates combine radial strength with drug delivery reservoirs. ISO 25539-2 fatigue testing requirements filter out undercapitalized developers.
- Coated:Surface modifications including carbon, silicon carbide, or phosphorylcholine reduce thrombogenicity. CE marking under EU MDR mandates extensive hemocompatibility documentation.
Metal platforms retain the largest installed base. Polymer architectures are climbing the fastest as bioresorbable technology matures.
Delivery Method:
Volume concentration shifts from open surgical revascularization toward catheter-based approaches as interventionalist training expands.
- Percutaneous:Transfemoral access with 6-8 French delivery systems enables same-day discharge, driving adoption in US ambulatory surgery centers.
- Endovascular:Advanced navigation through contralateral crossover or brachial access handles bilateral iliac disease. Italian and Spanish public hospital networks standardize on these techniques.
- Open Surgery:Aortofemoral bypass remains indicated for extensive TASC D occlusions unsuitable for endovascular reconstruction. Procedure volumes concentrate in Eastern European markets with limited catheterization infrastructure.
- Hybrid Approach:Combined open and endovascular techniques address multilevel disease. German university hospitals pioneer these protocols for chronic limb-threatening ischemia.
Endovascular delivery commands the greatest installed capacity. Percutaneous methods are gaining share fastest as access site complication rates decline.
End User:
Customer type determines purchasing authority, with consolidated hospital networks extracting volume discounts unavailable to fragmented outpatient settings.
- Hospitals:Academic medical centers and community hospitals perform the majority of complex iliac interventions. Kaiser Permanente's Northern California network exemplifies integrated delivery organization procurement centralization.
- Outpatient Clinics:Office-based catheterization labs in Texas and Florida capture lower-complexity cases, constrained by Medicare site-of-service payment differentials.
- Ambulatory Surgery Centers:Freestanding facilities in the US target commercially insured populations for straightforward unilateral stenting. FDA PMA pathway requirements limit device selection to established platforms.
- Research Institutes:Cleveland Clinic and Mayo Clinic sites generate pivotal clinical trial data for novel stent designs, influencing subsequent payer coverage determinations.
Hospitals absorb the bulk of installed capacity. Ambulatory surgery centers are expanding most quickly as reimbursement shifts favor lower-acuity settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospital clusters around Munich, Heidelberg, and Berlin concentrate specialized endovascular capacity for complex iliac interventions. Hospital procurement committees in these centers mandate five-year total cost-of-ownership analyses that weight reintervention rates against upfront device costs. This behavioral pattern concentrates contract awards among manufacturers with robust real-world evidence registries.
United States
Kaiser Permanente's Northern California network exemplifies integrated delivery organization procurement centralization for catheterization services. FDA premarket approval pathways for novel stent designs extend 36-48 months, freezing R&D ROI calculations for early-stage developers. Houston's Methodist Hospital and Cleveland Clinic generate pivotal clinical trial data that influences subsequent payer coverage determinations nationwide.
Germany
Diagnosis-Related Group reimbursement frameworks open payment pathways for complex TASC C/D lesions treated with advanced polymer-coated platforms. EU MDR Article 117 requirements impose notified body consultation mandates on stent coating validations through EMA scientific advice pathways. TÜV SÜD and DEKRA command 60% of vascular device certifications, creating queue bottlenecks for manufacturers seeking CE marking.
Japan
PMDA fast-track pathways for peripheral vascular devices expand addressable procedural volumes in a population where claudication prevalence exceeds 12% among adults over 70. METI industrial policy supports domestic manufacturing capacity for nitinol processing equipment. Tokyo and Osaka metropolitan catheterization lab clusters concentrate interventionalist training programs required for complex chronic total occlusion proficiency.
India
Production-linked incentive corridors in Andhra Pradesh and Tamil Nadu offer 5-20% tariff concessions for domestic stent manufacturing under the PLI scheme. CDSCO regulatory harmonization with IMDRF standards accelerates market entry for multinational device portfolios. Hyderabad and Chennai medical device parks attract contract manufacturers serving European markets seeking supply chain diversification.
France
AP-HP hospital network digital tendering systems disintermediate traditional distributor markups, capturing 8-12% price transparency gains for public procurement. ANSM vigilance reporting requirements for vascular implantables mandate post-market surveillance data submission. Paris and Lyon university hospital consortia standardize on endovascular techniques for bilateral iliac disease management.
Iliac Artery Stents Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioresorbable scaffold convergence and direct-to-hospital procurement platforms. The vendor base stratifies across three tiers: backward-integrated alloy processors commanding cost advantages, polymer science specialists capturing premium reimbursement for drug-eluting configurations, and regional contract manufacturers exploiting tariff concessions in emerging production corridors. Consolidation pressure intensifies as EU MDR certification delays filter undercapitalized competitors from commercial traction. Dominant competitive moves include capacity expansion into Indian PLI corridors and strategic partnerships with German notified bodies for MDR technical documentation support.
Among diversified medical technology conglomerates, Medtronic, Abbott Laboratories, and Boston Scientific Corporation exemplify distinct competitive archetypes. Medtronic represents the backward-integrated processor model with captive superelastic alloy processing capabilities. Abbott Laboratories occupies the polymer science leadership position for drug-eluting platform development. Boston Scientific Corporation anchors the controlled deployment systems specialization for tortuous anatomies. These three entities collectively demonstrate how material science control, pharmaceutical coating expertise, and mechanical engineering precision define separable competitive vectors in iliac artery stent procurement decisions.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| W. L. Gore & Associates |
| Cook |
| Becton Dickinson and Company |
| Terumo Corporation |
| Biotronik |
| Cordis |
| Others |
Value Network & Pricing Analysis
Bioresorbable magnesium alloy processing is displacing conventional nitinol fabrication economics while concentrating production capability among German and Japanese metallurgical specialists with vacuum casting expertise. This materials transition simultaneously elevates R&D amortization burdens and filters pricing power toward backward-integrated manufacturers controlling superelastic wire supply.
Pricing Analysis
Nitinol ingot cost pass-through from Russian and Chinese rare earth export quotas compresses gross margins for non-integrated stent producers. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy balloon-expandable levels separates CE-marked MDR-compliant platforms from legacy devices. Pricing pressure stems from hospital procurement committees mandating five-year total cost-of-ownership analyses that weight reintervention costs against upfront device expenditure. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare site-of-service payment differentials, while German university hospital consortia prioritize clinical outcome metrics over acquisition cost.
Supply Chain Analysis
Specialized nitinol metallurgists in Germany, Japan, and the United States face constrained workforce pipelines as vacuum arc remelting expertise concentrates among retiring technician cohorts. Raw material dependencies center on nickel-titanium alloy ingots, cobalt-chromium tubing, and bioabsorbable lactide-glycolide copolymers for polymer coatings. Single-source vulnerability persists in superelastic wire drawing capacity controlled by three dominant suppliers. Distribution runs through hospital procurement committees and GPO contracts in consolidated US delivery networks, with direct-to-hospital digital tendering gaining traction in French and German public hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Iliac Artery Stents Market represents a late-cycle quality story as hospital procurement shifts toward drug-eluting platforms with robust real-world evidence registries and demonstrated restenosis suppression. Premium specifications now dominate vendor selection criteria over upfront price competition.
For Market Incumbents: Deploy backward integration into nitinol wire processing to defend margin position against Russian and Chinese rare earth export volatility. Consolidate CE marking technical documentation capabilities through partnerships with TÜV SÜD and DEKRA to accelerate EU MDR certification timelines and filter undercapitalized competitors from commercial traction. For New Entrants and Emerging Players: India's PLI scheme for medical devices in Andhra Pradesh and Tamil Nadu opens a window for contract manufacturing entry serving European supply chain diversification demand. Target bioresorbable scaffold segments where magnesium alloy platforms lack established incumbents, leveraging PMDA fast-track pathways for Japanese market validation before EU MDR submission. For Investors and Strategic Acquirers: Roll-up economics work for polymer science specialists because EU MDR Article 117 coating validation requirements create insurmountable technical documentation barriers for standalone developers. Five-to-ten year viability hinges on reimbursement pathway capture in Germany's DRG framework. Watch for FDA breakthrough device designations as inflection signals for platform commercial traction ahead of PMA pathway completion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body queue bottlenecks at TÜV SÜD and DEKRA filter undercapitalized competitors from market access. |
| Hospital System Partnership | Kaiser Permanente's integrated procurement centralization exemplifies five-year total cost-of-ownership vendor selection criteria. |
| Backward Integration | Captive nitinol wire processing insulates gross margins from Russian and Chinese rare earth export quota volatility. |
| Reimbursement Strategy | Germany's DRG framework opens payment pathways for complex TASC C/D lesions treated with polymer-coated platforms. |
| Software Companion Development | Digital tendering systems in France's AP-HP network disintermediate distributor markups through price transparency platforms. |
Research Methodology
Multiple input streams — structured interviews with interventional cardiologists and hospital purchasing committees, biomedical engineering assessments, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged catheterization lab directors, GPO contracts managers, and notified body technical documentation specialists across German, US, and Japanese markets. Secondary validation drew from FDA PMA filings, EMA scientific advice pathways, hospital procurement databases, and CMS Medicare reimbursement schedules.
Historical procedural volume trajectories were cross-referenced against panel-based clinician adoption surveys to anchor projections across the analysis window. Segmentation modeling incorporated product architecture, material composition, delivery approach, and end-user concentration dimensions. CAGRs were derived from installed base expansion rates adjusted for EU MDR certification delays and PMDA fast-track pathway accelerations, with nitinol supply elasticity and hospital consolidation patterns serving as key sensitivity inputs.
Revisions become necessary when EU MDR notified body capacity constraints extend beyond modeled queue durations, when Russian or Chinese rare earth export quotas disrupt nitinol ingot pricing assumptions, or when drug-coated balloon technology captures unanticipated iliac procedural volumes. Material deviation in these named triggers warrants pause and re-evaluation of platform adoption forecasts and manufacturer margin assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market