
 US Ventricular Assist Devices Market | 2026-2036
US Ventricular Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Ventricular Assist Devices Market Insights
Magnetically levitated rotor technology is reconfiguring pump design by eliminating mechanical bearings and reducing thrombogenic risk. Abbott leverages its HeartMate platform to sustain leadership in continuous-flow systems. Medtronic anchors its position through integrated care pathways spanning implant through outpatient management. Abiomed differentiates with percutaneous temporary support that occupies the bridge-to-decision segment.
Ventricular assist devices are implantable mechanical circulatory support systems that supplement or replace native ventricular function, typically operating at rotational speeds of 2,000–10,000 RPM to generate blood flows of 4–10 liters per minute. These devices serve as bridge-to-transplant, bridge-to-recovery, or destination therapy for patients with refractory heart failure. Left Ventricular Assist Device configurations dominate procedural volumes due to established clinical evidence and broader reimbursement coverage. Continuous Flow technology leads the technology dimension with magnetic levitation and hydrodynamic bearing variants displacing first-generation pulsatile designs. Specialty Hospitals command the deepest margin pools as they bundle device procurement with surgical expertise and post-implant monitoring programs.
FDA premarket approval and humanitarian device exemption pathways govern commercialization timelines and clinical evidence requirements for VAD manufacturers. CMS national coverage determinations and transplant center reimbursement rates directly shape hospital adoption economics and patient access. The Department of Health and Human Services oversees organ allocation policies that influence bridge-to-transplant demand dynamics. Stakeholders must monitor evolving FDA guidance on durability testing and real-world evidence requirements as these will determine competitive positioning for next-generation devices.
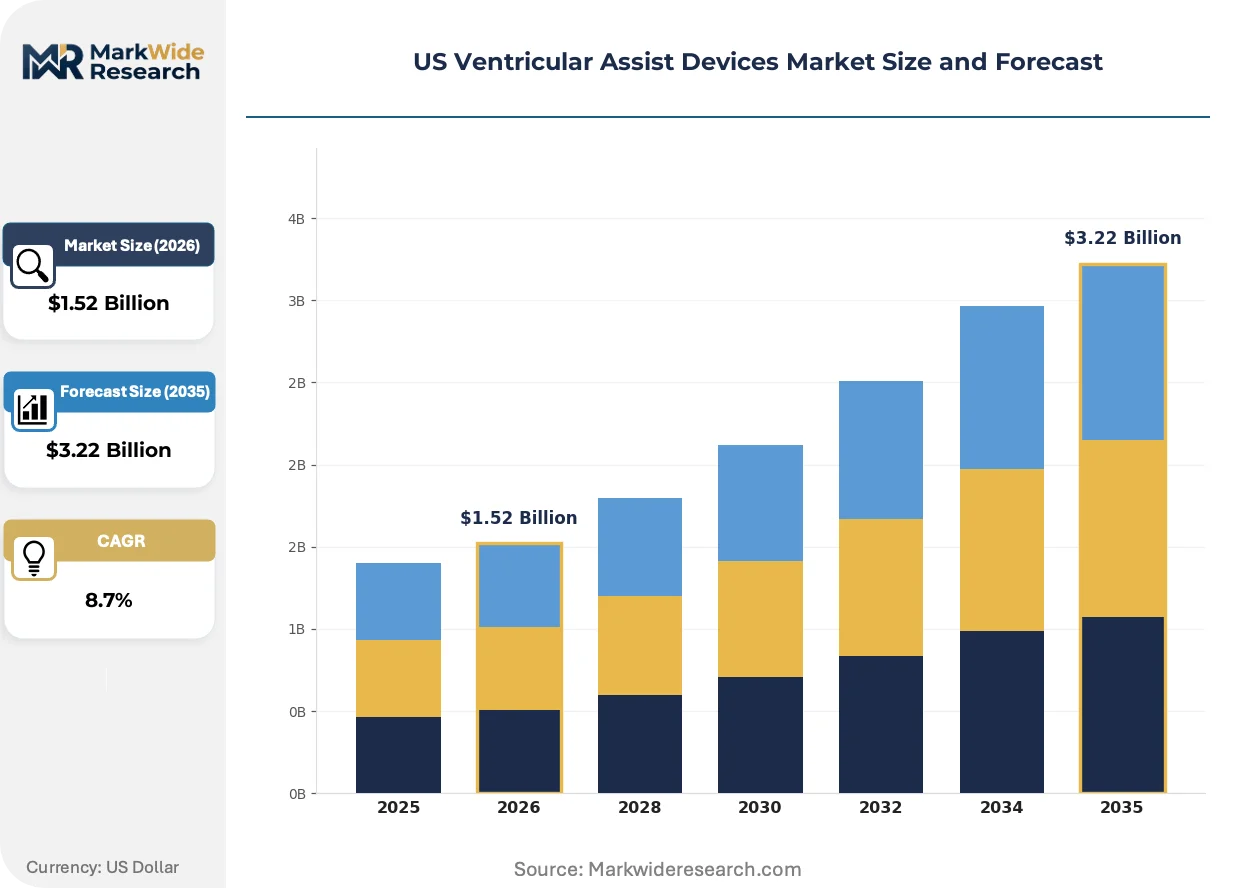
Market Dynamics
Magnetically levitated rotor architectures are compressing thrombogenic risk profiles and extending device durability horizons, forcing incumbent manufacturers to reconfigure bearing systems and accelerate FDA premarket approval timelines for next-generation platforms.
Growth Catalysts
- CMS Reimbursement Expansion:National coverage determinations for destination therapy have unlocked procedural volumes at specialty hospitals across Massachusetts, New York, and Pennsylvania transplant corridors.
- Continuous-Flow Technology Maturation:Hydrodynamic bearing variants are displacing first-generation pulsatile designs in bridge-to-recovery applications, reducing pump failure rates and rehospitalization burden.
- End-Stage Heart Failure Prevalence:Aging demographics in the Northeast and Great Lakes regions are expanding the addressable patient pool for durable mechanical circulatory support.
Market Restraints
- Titanium and Rare Earth Magnet Costs:Supply concentration in Chinese processing facilities for neodymium-based magnetic materials creates input price volatility for rotor assembly manufacturers.
- FDA PMA Pathway Duration:Premarket approval timelines averaging 18-24 months compress commercialization windows and elevate clinical trial expenditure requirements.
- Transplant Center Capacity Limits:Bridge-to-transplant demand concentrates in 150-200 certified US centers, creating procedural bottlenecks and geographic access inequities.
Strategic Opportunities
- Southeast and Southwest Expansion:Underpenetrated markets in Texas, Florida, and Arizona present white space for new implant program development at emerging cardiac surgery centers.
- Real-World Evidence Pathways:FDA guidance on post-market surveillance and registry-based submissions offers accelerated approval routes for iterative device modifications.
- Remote Monitoring Integration:Convergence of implantable sensors with cloud-based analytics platforms enables outpatient hemodynamic optimization and reduces in-person follow-up burden.
Industry Challenges
- VAD-Specific Surgical Training Shortage:Pump implantation and explantation expertise concentrates among 400-500 specialized cardiac surgeons, constraining program scale-up velocity.
- Biocompatibility Certification Complexity:ISO 10993 testing requirements for blood-contacting surfaces extend development timelines and elevate regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ventricular Assist Devices Market |
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Left Ventricular Assist Device, Right Ventricular Assist Device, Bi-Ventricular Assist Device, Total Artificial Heart Technology: Pulsatile Flow, Continuous Flow, Electromagnetic, Hydraulic, Pneumatic Patient Profile: Heart Failure, Cardiomyopathy, Myocardial Infarction Recovery, Congenital Heart Defect End User: Cardiology Clinics, Specialty Hospitals, Rehabilitation Centers, Research Institutions |
| Companies Covered | Abbott, Abiomed, Berlin Heart, Jarvik Heart, Medtronic, SynCardia Systems, Cardiac Assist, ReliantHeart, Evaheart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ventricular Assist Devices Market Trends and Innovations
Digital integration across the device lifecycle is compressing clinical decision cycles and enabling predictive intervention models that shift care delivery from reactive to preemptive frameworks.
Artificial intelligence-enabled hemodynamic monitoring is digitizing post-implant patient management by analyzing pump parameters, patient activity, and physiologic biomarkers in real time. Specialty hospitals in the Northeast corridor are deploying these platforms to reduce readmission rates and optimize anticoagulation protocols. The technology is digitizing clinical workflow by automating threshold alerts and routing escalation decisions to centralized monitoring centers rather than on-call surgical teams.
FDA guidance on computational modeling and simulation is accelerating premarket submission pathways for manufacturers leveraging in-silico testing to supplement animal and human trials. The policy shift reduces reliance on traditional bench testing and compresses evidence generation timelines for iterative design changes. Continuous-flow pump developers are responding by investing in finite element analysis capabilities and partnering with academic biomechanics laboratories to validate thrombosis prediction algorithms.
Hospital procurement committees are consolidating vendor relationships around integrated service contracts that bundle device supply with training, monitoring infrastructure, and outcomes guarantees. Specialty hospitals are displacing transactional purchasing with multi-year partnerships that tie reimbursement to readmission and device malfunction metrics. This consolidation is most visible in Massachusetts and New York, where dominant transplant centers are leveraging volume commitments to secure dedicated field clinical specialist coverage and priority technical support access.
US Ventricular Assist Devices Market Segmentation
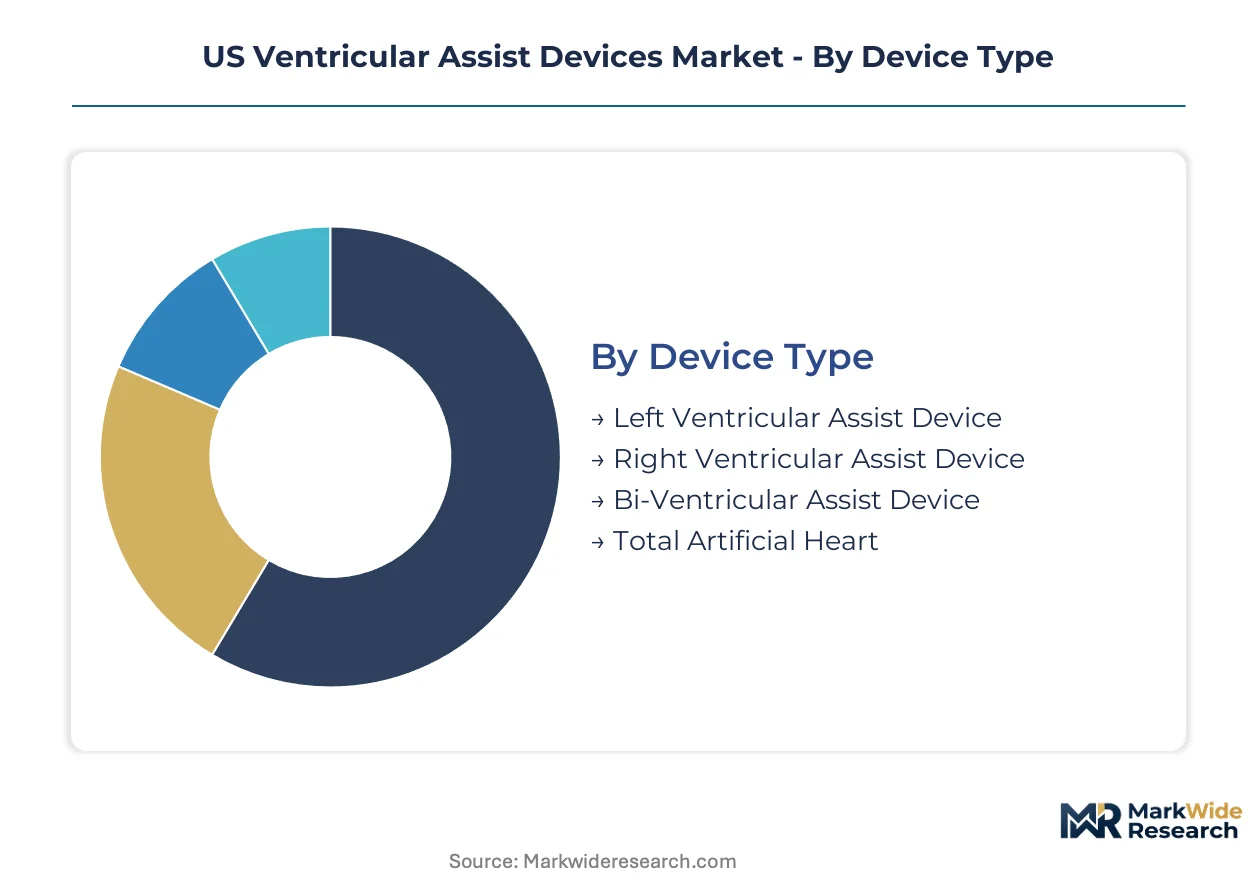
Segmentation in the US Ventricular Assist Devices Market reveals how clinical indications, technological architectures, and care delivery settings partition commercial opportunity. Each dimension carries distinct reimbursement codes, regulatory pathways, and margin structures that manufacturers must navigate.
Device Type:
The use-case spectrum spans bridge-to-transplant support through permanent replacement of native ventricular function.
- Left Ventricular Assist Device:Implanted mechanical pumps augment systemic circulation by unloading the left ventricle through an apical cannula and outflow graft to the ascending aorta. Massachusetts and New York transplant centers concentrate procedural volumes as destination therapy for INTERMACS profile 2-4 patients awaiting transplant or ineligible for listing. FDA premarket approval pathways and CMS reimbursement alignment have cemented LVAD dominance in durable mechanical circulatory support.
- Right Ventricular Assist Device:These systems support pulmonary circulation through cannulation of the right atrium and pulmonary artery, typically deployed in postcardiotomy shock or as biventricular support adjuncts. Demand concentrates in Pennsylvania and Ohio cardiac surgery centers managing acute right heart failure following left-sided implantation or cardiac transplantation.
- Bi-Ventricular Assist Device:Dual-pump configurations address biventricular failure through separate left and right support systems.
- Total Artificial Heart:Orthotopic replacement of both ventricles with pneumatic or electromechanical pumps serves as last-resort therapy for irreversible biventricular failure.
Established volume favors Left Ventricular Assist Device; emerging adoption favors Bi-Ventricular Assist Device as dual-pump configurations improve outcomes in complex failure patterns.
Technology:
Cost tier differentiation separates legacy pulsatile platforms from continuous-flow systems commanding premium reimbursement.
- Continuous Flow:Axial or centrifugal pumps operating at 2,000-10,000 RPM generate non-pulsatile output through magnetic levitation or hydrodynamic bearing architectures. Specialty hospitals in the Northeast corridor prioritize these systems for reduced thrombogenicity and extended durability horizons compared with first-generation alternatives.
- Pulsatile Flow:Volume-displacement pumps mimicking native cardiac contraction through pneumatic or electromechanical actuation now serve niche bridge-to-recovery applications.
- Electromagnetic:Magnetically levitated rotor designs eliminate mechanical bearings through magnetic suspension fields.
- Hydraulic:Hydrodynamic bearing variants use blood film lubrication to support rotating assemblies.
- Pneumatic:Compressed air-driven diaphragm pumps power temporary paracorporeal support and total artificial heart configurations.
Continuous Flow commands the premium tier through magnetic levitation; Pulsatile Flow occupies declining cost-sensitive niches as continuous-flow maturation displaces earlier generations.
Patient Profile:
Application severity stratifies from acute coronary events through chronic progressive cardiomyopathies.
- Heart Failure:Refractory Stage D heart failure with reduced ejection fraction represents the dominant indication, encompassing INTERMACS profiles ranging from critical cardiogenic shock to stable inotrope dependence. The Northeast and Great Lakes regions concentrate eligible patients given aging demographics and established transplant infrastructure.
- Cardiomyopathy:Dilated, ischemic, and hypertrophic cardiomyopathies progressing to end-stage ventricular dysfunction drive elective implant timing decisions.
- Myocardial Infarction Recovery:Temporary mechanical support during stunned myocardium recuperation following acute coronary occlusion.
- Congenital Heart Defect:Single-ventricle physiology and complex congenital lesions requiring palliative mechanical support in pediatric and adult congenital populations.
Heart Failure generates the deepest procedure volumes; Myocardial Infarction Recovery is climbing fastest as temporary percutaneous platforms expand bridge-to-decision applications.
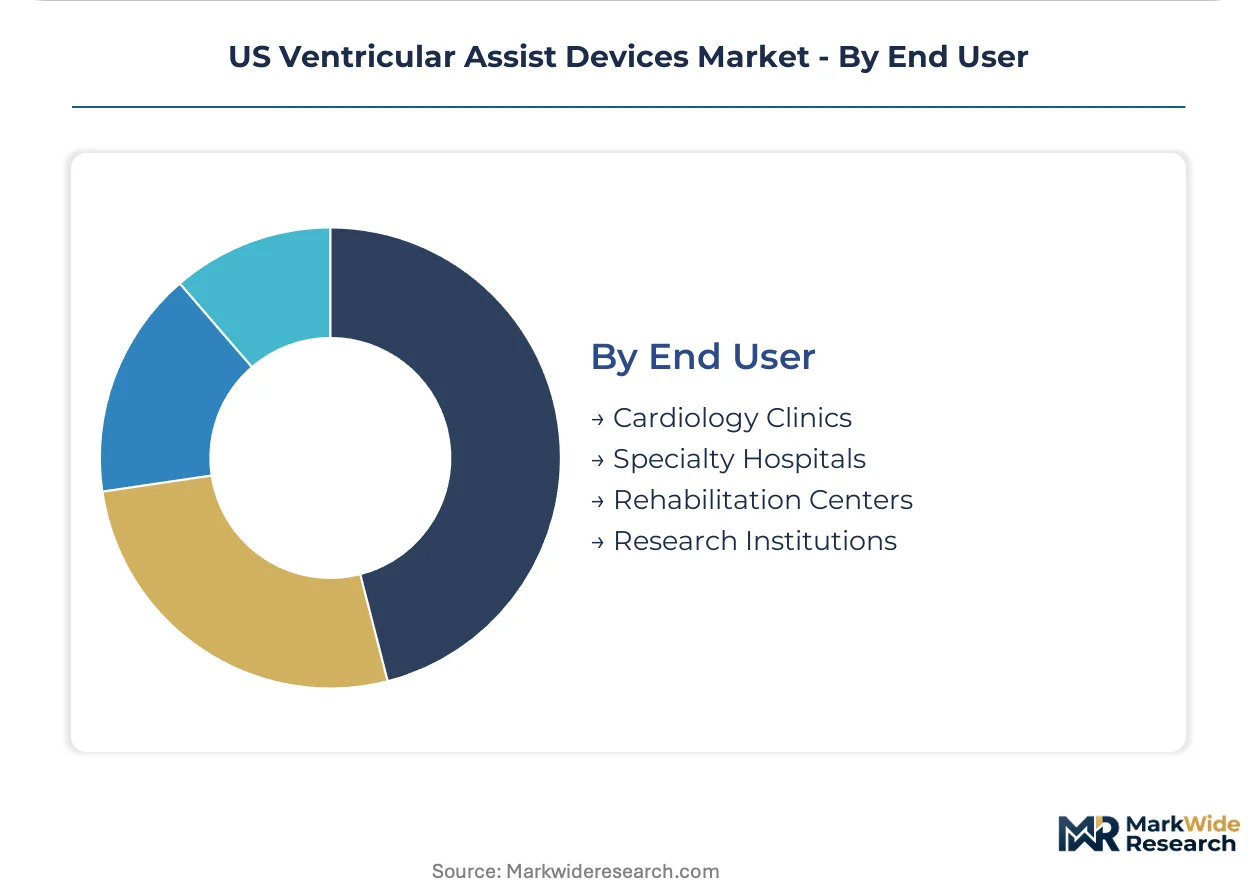
End User:
Customer type concentration determines procurement complexity and service bundling requirements.
- Specialty Hospitals:Certified ventricular assist device programs at academic medical centers integrate implant surgery with dedicated VAD coordinators, anticoagulation clinics, and remote monitoring infrastructure. These institutions command bundled reimbursement rates and capture the deepest margin pools through outcomes-based contracts with manufacturers.
- Cardiology Clinics:Outpatient facilities manage patient selection, pre-implant optimization, and post-discharge surveillance.
- Rehabilitation Centers:Post-acute facilities coordinate physical reconditioning and device education for destination therapy patients.
- Research Institutions:Academic centers and contract research organizations conduct IDE trials and post-market surveillance studies.
Specialty Hospitals anchor procurement volume; Cardiology Clinics represent the fastest-expanding segment as remote monitoring decentralizes follow-up care from surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-manufactured ventricular assist devices flow primarily to transplant centers concentrated in the Northeast corridor, with secondary distribution channels serving emerging cardiac surgery programs in the Southeast and Southwest.
Northeast Corridor
Massachusetts and New York anchor procedural volume through established transplant infrastructure at academic medical centers in Boston and Manhattan. CMS national coverage determinations for destination therapy have unlocked bundled reimbursement rates at specialty hospitals across this corridor. Cleveland Clinic and University of Pennsylvania Health System in Ohio and Pennsylvania extend this cluster's influence westward through high-volume implant programs.
Southeast
Florida and Georgia present underpenetrated white space as aging demographics expand the addressable heart failure population. Duke University Hospital in North Carolina and Emory Healthcare in Atlanta are developing certified VAD programs to capture destination therapy demand. FDA premarket approval pathways enable these emerging centers to adopt continuous-flow platforms as they build surgical expertise.
Southwest
Texas Medical Center in Houston concentrates bridge-to-transplant demand through the Texas Heart Institute and Baylor St. Luke's Medical Center. Arizona's Mayo Clinic campus in Phoenix is expanding its mechanical circulatory support service line. CMS reimbursement alignment with specialty hospital designations accelerates program development in these Sun Belt markets.
Midwest
Illinois and Michigan maintain robust implant volumes through Northwestern Memorial Hospital in Chicago and University of Michigan Health in Ann Arbor. The Great Lakes region's aging industrial workforce generates elevated end-stage heart failure prevalence. State Medicaid expansion decisions in Ohio and Indiana influence patient access economics for destination therapy candidates.
Pacific Coast
California's Cedars-Sinai Medical Center and Stanford Health Care anchor West Coast procedural activity. Supply chain concentration for titanium components and rare earth magnetic materials in Chinese processing facilities creates input cost exposure for rotor assembly manufacturers serving these programs. Remote monitoring infrastructure deployment lags the Northeast due to geographic dispersion of transplant-eligible patients.
US Ventricular Assist Devices Market Competitive Landscape
On the supply side, the industry is consolidated around three dominant platform developers with established FDA premarket approval pathways and integrated care delivery networks. Continuous-flow technology maturation has compressed the viable competitive set to manufacturers bearing the clinical trial expenditure and regulatory submission costs required for durable mechanical circulatory support. Strategic archetypes separate into integrated platform developers, percutaneous temporary support specialists, and emerging magnetically levitated rotor innovators. Dominant competitive moves include multi-year integrated service contracts bundling device supply with outcomes guarantees, and geographic expansion of field clinical specialist coverage to underpenetrated implant programs.
Among integrated platform developers, Abbott and Medtronic occupy positions exemplifying the full-lifecycle care pathway archetype spanning implant through outpatient management. Abiomed represents the percutaneous temporary support specialization, anchoring bridge-to-decision applications distinct from durable VAD configurations. These three entities collectively illustrate how FDA premarket approval timelines and CMS reimbursement alignment function as structural barriers concentrating competitive position among incumbents with established clinical evidence portfolios.
| Leading Market Players |
|---|
| Abbott |
| Abiomed |
| Berlin Heart |
| Jarvik Heart |
| Medtronic |
| SynCardia Systems |
| Cardiac Assist |
| ReliantHeart |
| Evaheart |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in US-based rare earth magnet processing is forcing device manufacturers to absorb Chinese supply volatility while passing limited cost recovery through to hospital procurement committees. This utilization squeeze tightens margin structures across magnetic levitation rotor assemblies and compresses negotiating leverage for domestic assemblers.
Pricing Analysis
Continuous-flow magnetic levitation systems command premium positioning over hydrodynamic bearing variants and legacy pulsatile platforms. Pricing stratifies across FDA PMA tier, INTERMACS patient acuity designation, and bundled service commitment scale. Cost compression in standard-tier devices is intensifying because Chinese titanium forging capacity constraints elevate input expenses. Academic medical centers in Massachusetts and New York demonstrate lowest price sensitivity due to outcomes-based contract structures, while emerging programs in Arizona and Florida face acute budget scrutiny.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for neodymium magnet and titanium component sourcing. Manufacturing concentration in Chinese rare earth processing facilities, German precision bearing production, and domestic sterile packaging operations creates multi-node dependency. Single-source vulnerability concentrates in magnet alloy refinement stages. Distribution runs through manufacturer-direct field inventory systems positioned at certified implant centers rather than wholesale medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
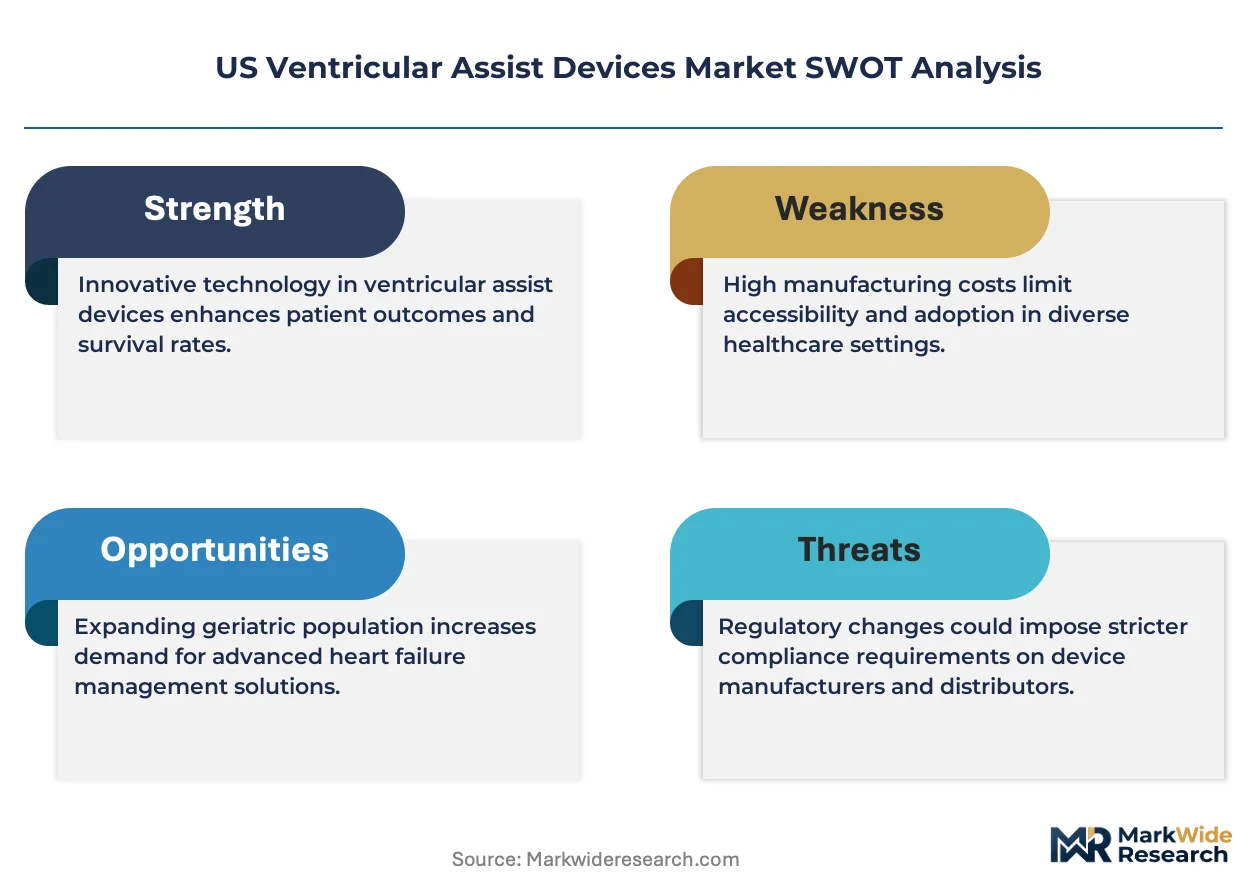
Platform economics in ventricular assist devices are inflecting toward integrated care ecosystems as remote monitoring infrastructure and AI-enabled hemodynamic analytics reconfigure interoperability requirements between device, hospital, and patient.
For Market Incumbents: Harden FDA PMA portfolio depth against magnetically levitated rotor innovators by accelerating in-silico validation capabilities and securing exclusive field clinical specialist deployments at high-volume Northeast corridor programs. Anchor backward integration into titanium forging partnerships to insulate margin structures from Chinese supply volatility.
For New Entrants and Emerging Players: Pursue percutaneous temporary support white space in bridge-to-decision applications where regulatory evidence requirements remain lighter than durable VAD pathways. Target Southeast expansion corridors in Florida and Georgia where transplant infrastructure buildout creates first-mover windows for training partnership contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across next-generation magnetic levitation platforms as FDA computational modeling guidance elevates finite element analysis infrastructure requirements. Acquisition targets should demonstrate validated thrombosis prediction algorithms and established academic biomechanics laboratory partnerships. The signal to watch is CMS national coverage determination expansion for destination therapy reimbursement in underpenetrated Sun Belt markets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Computational modeling submissions compress evidence generation timelines for iterative magnetic levitation designs. |
| Hospital System Partnership | Multi-year integrated service contracts at Massachusetts and New York centers lock in volume commitments and outcomes guarantees. |
| Software Companion Development | AI-enabled hemodynamic monitoring platforms automate threshold alerts and reduce in-person follow-up burden. |
| Reimbursement Strategy | CMS national coverage determination alignment unlocks procedural volumes at emerging specialty hospital programs. |
| Backward Integration | Captive supply of titanium components and rare earth magnetic materials insulates rotor assembly cost structures. |
Research Methodology
Operator-level perspectives from VAD coordinators, cardiac surgeons, hospital purchasing committees, and GPO contracts managers anchored the qualitative base. These inputs combined with secondary validation against FDA PMA filings, CMS Medicare reimbursement databases, INTERMACS registry data, and hospital procurement records. Bottom-up implant volume modeling and top-down market sizing triangulation ensured cross-verification.
Scenario-bracketing framed analytical projections across the modeling period through sensitivity testing of FDA approval timeline acceleration, CMS coverage expansion velocity, and Chinese rare earth export restriction probability. Segmentation dimensions spanned device configuration, bearing technology architecture, patient INTERMACS profile, and end-user facility certification tier. CAGRs derived from procedure volume trajectories and device replacement cycle assumptions.
Sensitivities concentrate around FDA guidance evolution on real-world evidence requirements and CMS reimbursement rate adjustments for destination therapy. Forecasts reflect documented assumptions on transplant center capacity expansion and magnetic levitation technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Implantable Infusion Pumps Market