
 Investigational New Drug CDMO Market | 2026-2036
Investigational New Drug CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Investigational New Drug CDMO Market Intelligence
Market Context
Swiss drug substance capacity is shifting toward high-potency APIs and antibody-drug conjugates as sponsors seek integrated development-to-commercial pathways. Lonza leverages its Visp campus to anchor microbial and mammalian cell culture services across early-phase programs. Charles River Laboratories sustains competitive positioning through its Wilmington, Massachusetts biologics hub, which controls a dense network of IND-enabling toxicology and CMC capabilities. Thermo Fisher Scientific extends its reach via Patheon's global manufacturing footprint, allowing seamless tech transfer from clinical to commercial scale.
Technical Definition and Segment Structure
An investigational new drug contract development and manufacturing organization performs chemistry, manufacturing, and controls activities for drug candidates prior to FDA New Drug Application submission, encompassing API synthesis, formulation development, stability testing, and clinical trial material production under current Good Manufacturing Practice. The primary commercial purpose is to reduce capital intensity for sponsors while accelerating regulatory-ready documentation. Manufacturing Services captures the deepest margin pools due to long-term commercial supply agreements and specialized containment requirements for oncology programs. Development Services represents the fastest-growing segment as biotech firms outsource medicinal chemistry and preformulation work. Regulatory Services remains comparatively mature, with pricing pressure from template-driven submission preparation.
Regulatory Framework
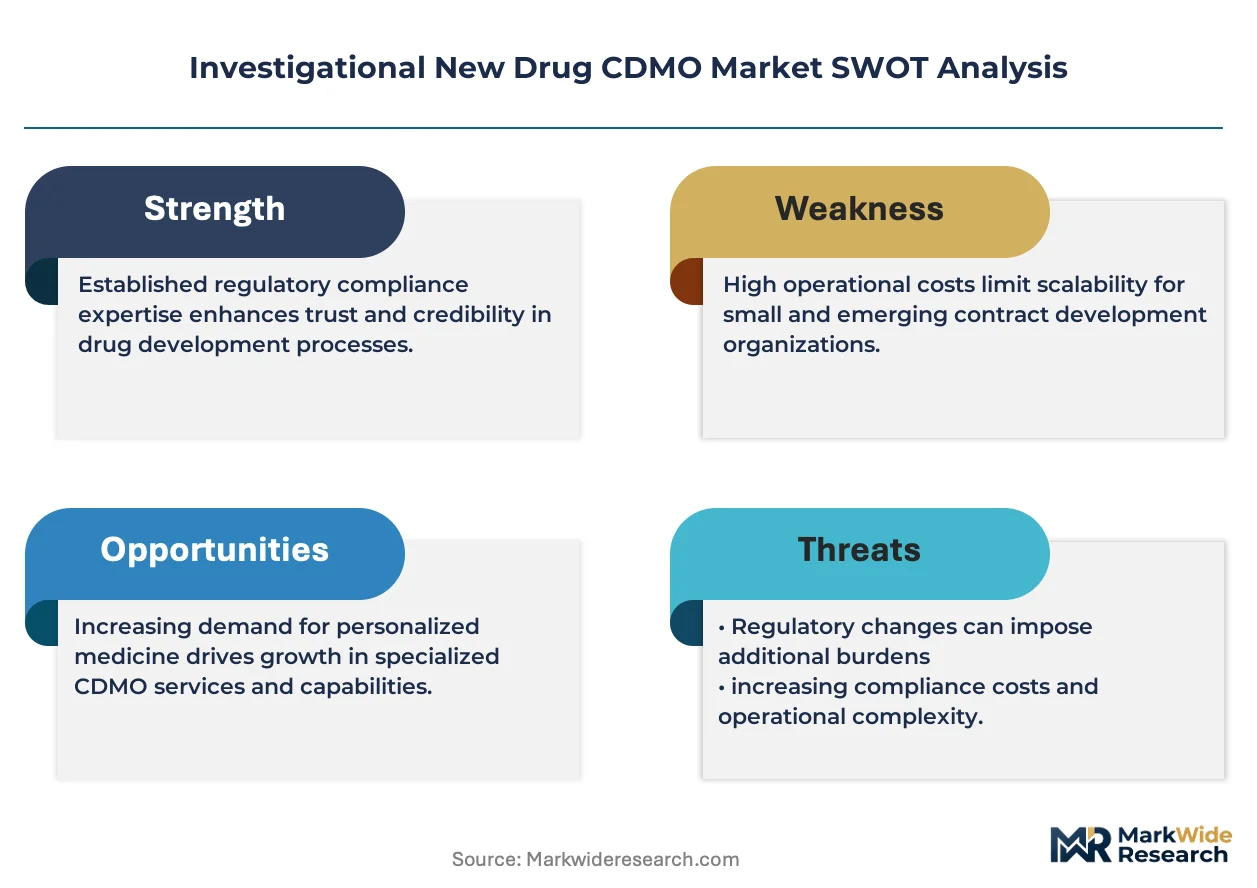
FDA's Quality Management Maturity program and EMA's revised Annex 1 on sterile manufacturing are reshaping facility investment requirements, while ICH Q14 guidelines on analytical procedure development are altering method validation expectations for IND-enabling packages. These frameworks collectively elevate documentation burdens and inspection readiness standards, favoring CDMOs with established regulatory track records across multiple jurisdictions. Stakeholders must monitor how FDA's emerging advanced manufacturing designation pathway alters competitive positioning for domestic versus ex-US capacity.
Market Dynamics
Biotech sponsors are consolidating outsourcing relationships with full-service CDMOs capable of integrated chemistry, manufacturing, and controls workflows, compressing vendor panels from fragmented specialty providers toward strategic partnerships that span drug substance through commercial supply.
Growth Catalysts
- FDA Quality Management Maturity program:The agency's rating system for quality culture incentivizes sponsors to select CDMOs with documented inspection readiness, accelerating demand for partners with proven regulatory track records across multiple IND submissions.
- Antibody-drug conjugate pipelines:Oncology sponsors are advancing ADC candidates requiring specialized high-potency containment and conjugation chemistry capabilities that few in-house facilities can accommodate.
- Switzerland-Massachusetts-Singapore corridor:Geographic clustering around academic medical centers and venture capital ecosystems creates dense networks of development-stage biotech firms seeking proximal manufacturing partnerships.
Market Restraints
- Specialized labor scarcity:Cell culture operators and analytical development scientists command premium compensation in Boston and Basel, constraining capacity expansion timelines for mammalian biologics programs.
- Single-use equipment lead times:Extended delivery schedules for bioreactor bags and sterile connectors from concentrated polymer suppliers create bottlenecks in clinical material production schedules.
- Containment capital intensity:High-potency API facilities require isolator technology and dedicated HVAC infrastructure that demands $150-300 million per greenfield site, limiting market entry.
Strategic Opportunities
- India's emerging biologics corridor:Hyderabad and Bangalore are attracting investment in biosimilar development capabilities, creating pathways for Western sponsors to access cost-advantaged mammalian cell culture capacity.
- Continuous manufacturing adoption:FDA's advanced manufacturing designation pathway rewards sponsors adopting process analytical technology and real-time release testing, differentiating innovative CDMO partners.
- Gene therapy vector production:Viral vector manufacturing for AAV and lentiviral platforms represents underserved capacity as cell and gene therapy pipelines expand beyond oncology into rare disease indications.
Industry Challenges
- Tech transfer velocity:Compressed timelines between candidate nomination and first-in-human dosing strain documentation rigor, with sponsors demanding 12-16 month CMC development cycles that stress method validation protocols.
- Multi-product facility scheduling:Campaign changeover complexity for high-potency compounds requires extended cleaning validation and line clearance procedures that reduce effective capacity utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Investigational New Drug CDMO Market |
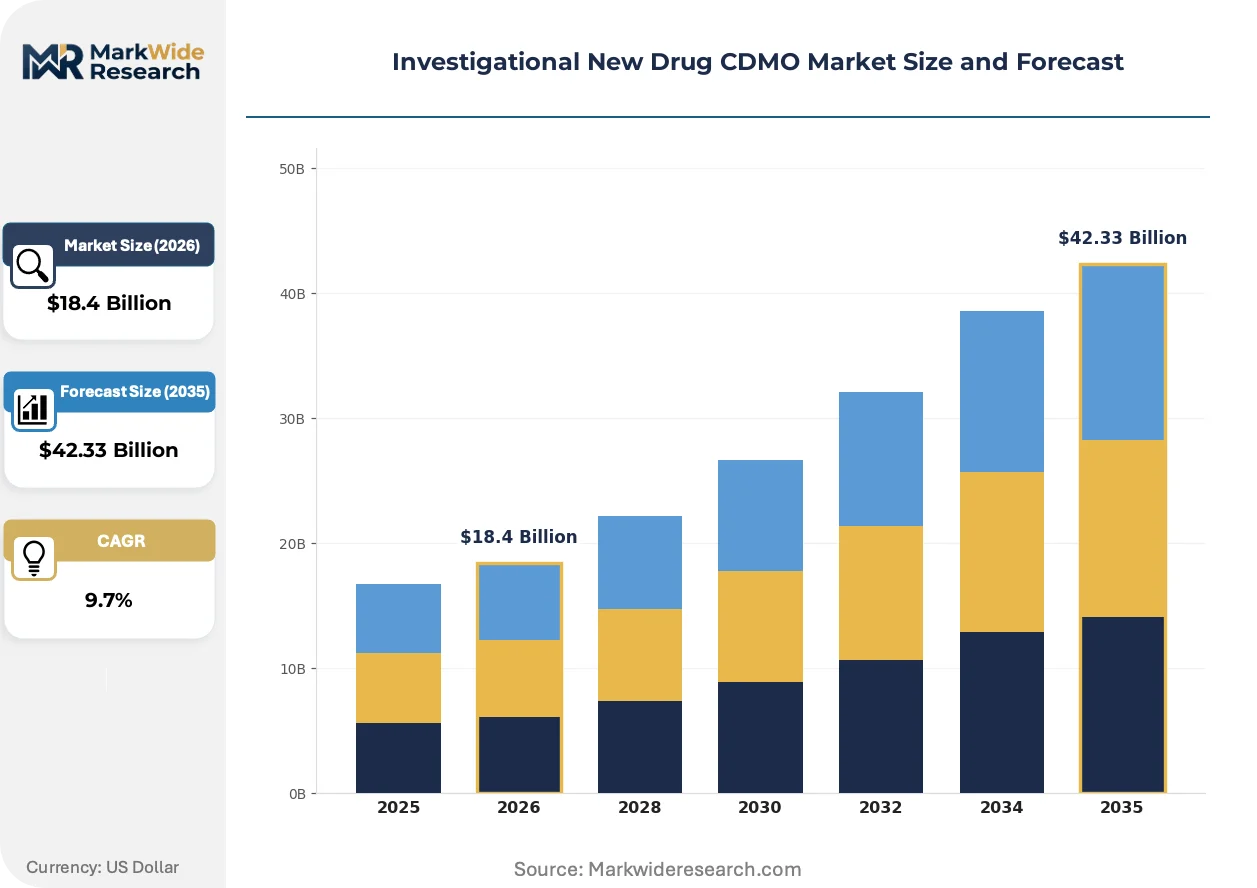
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $42.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Development Services, Manufacturing Services, Regulatory Services, Quality Assurance Therapy Area: Oncology, Neurology, Cardiovascular, Infectious Diseases Delivery Mode: Injectable, Oral, Topical, Inhalation Client Type: Pharmaceutical Companies, Biotech Firms, Research Institutions, CROs |
| Companies Covered | Siegfried Holding AG, Charles River Laboratories, Lonza, IQVIA Holdings Inc., Cambrex Corporation, Catalent, Recipharm, Syneos Health, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Investigational New Drug CDMO Market Strategic Shifts & Innovations
Process analytical technology and artificial intelligence are converging to transform how CDMOs control critical quality attributes, shifting from end-point testing toward real-time release paradigms that compress development timelines and reduce batch failure risk.
Digital twin modeling is automating scale-up prediction for mammalian cell culture processes, allowing sponsors to simulate bioreactor performance across 50L to 2000L scales before committing physical assets. Large-capacity CDMOs are deploying these platforms to reduce tech transfer risk for complex glycoproteins. The technology is automating decision-making around feeding strategies and harvest timing that previously required empirical iteration.
EMA's revised Annex 1 on sterile manufacturing mandates barrier technology and contamination control strategy documentation for all aseptic operations, forcing facility retrofits across European Union manufacturing sites. The regulation elevates cleanroom classification requirements for isolator-based filling lines. Parenteral formulation specialists in Germany and Ireland are prioritizing gloveless isolator installations to meet the 2024 implementation deadlines.
Sponsor purchasing departments are consolidating IND-phase contracts under master service agreements with volume commitments and preferred capacity access clauses. Biotech firms with multiple candidates are displacing project-by-project RFP processes with partnership frameworks that embed dedicated FTE teams. Massachusetts-based venture-backed companies are pioneering this model to secure manufacturing slots during capacity-constrained periods.
Investigational New Drug CDMO Market Segmentation
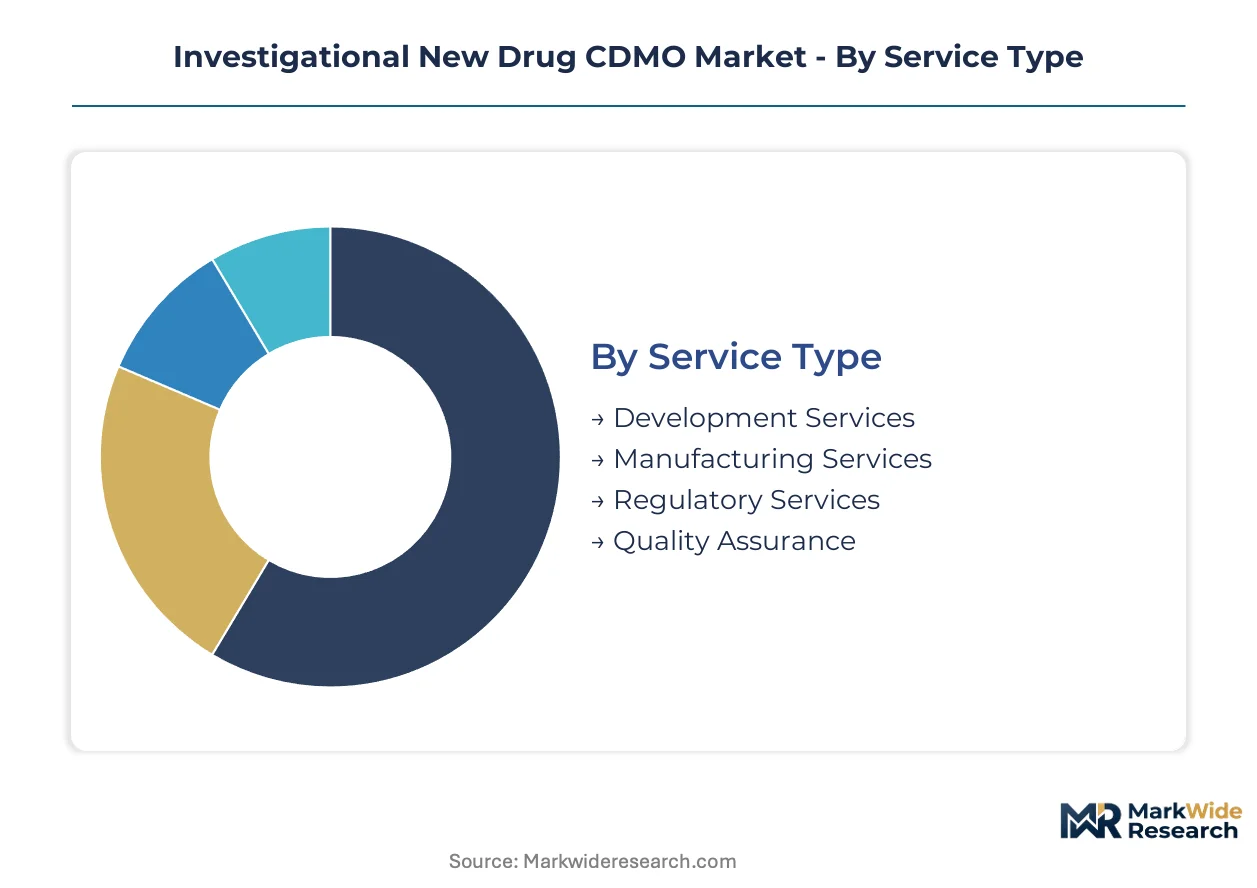
IND-phase outsourcing decisions hinge on service integration depth, therapy complexity, and regulatory risk tolerance. Sponsors weight these dimensions differently across preclinical, Phase I, and Phase II transitions, creating distinct vendor selection patterns that reshape CDMO competitive tiers.
Service Type:
Capital efficiency drives sponsor choices between bundled capabilities and specialized point solutions, with cost of capital and pipeline density determining optimal configuration.
- Development Services:Medicinal chemistry, preformulation, and analytical method development for IND-enabling packages. Biotech firms in Massachusetts and Switzerland outsource these functions most aggressively as they compress candidate-to-clinic timelines. This segment climbs the fastest as virtual biotech models proliferate and internal chemistry headcount shrinks.
- Manufacturing Services:GMP production of clinical trial materials including drug substance synthesis, formulation, and sterile fill-finish. High-potency oncology programs command premium pricing due to isolator containment requirements and dedicated facility infrastructure. This segment leads on scale through long-term commercial supply agreements and multi-year capacity reservations.
- Regulatory Services:CMC documentation, FDA pre-IND meeting preparation, and submission dossier assembly. Template-driven commoditization pressures pricing as electronic submission tools standardize formatting.
- Quality Assurance:Batch release testing, stability program management, and audit support for sponsor quality systems. FDA Quality Management Maturity ratings elevate demand for partners with documented inspection readiness.
Manufacturing Services leads on scale; Development Services leads on momentum.
Therapy Area:
Clinical trial failure rates and manufacturing complexity vary sharply across disease categories, altering risk-adjusted outsourcing economics for sponsors.
- Oncology:Antibody-drug conjugates, bispecific antibodies, and cell therapies dominate IND filings. ADC payloads require high-potency containment and conjugation chemistry expertise concentrated in Swiss and Singaporean facilities. This segment expands most quickly as immune-oncology pipelines mature and combination therapy trials multiply.
- Neurology:Blood-brain barrier penetration challenges and large-molecule delivery constraints complicate CMC development for Alzheimer's and rare neurological indications. Gene therapy vectors for CNS targeting strain viral manufacturing capacity.
- Cardiovascular:Established small-molecule and biologic modalities with lower containment requirements but demanding large-scale fermentation for commercial supply.
- Infectious Diseases:Pandemic preparedness funding and antimicrobial resistance initiatives sustain government-sponsored development programs with distinct procurement timelines.
Oncology commands the deepest margins; Neurology presents the steepest technical barriers.
Delivery Mode:
Route of administration dictates facility infrastructure requirements, with sterile manufacturing capacity constraints reshaping sponsor formulation strategies.
- Injectable:Parenteral formulations including vials, prefilled syringes, and lyophilized products. EMA's revised Annex 1 mandates isolator technology for aseptic processing, forcing facility retrofits across European Union sites. This segment captures the largest revenue pool due to biologics dominance and high-value oncology dosing.
- Oral:Tablets, capsules, and multiparticulate systems for small molecules and peptide formulations. Continuous manufacturing adoption differentiates innovative CDMO partners pursuing FDA advanced manufacturing designations.
- Topical:Transdermal patches, creams, and gels with specialized excipient requirements and skin permeation testing protocols.
- Inhalation:Dry powder inhalers, metered-dose devices, and nebulizer solutions demanding particle engineering and lung deposition modeling capabilities.
Injectable dominates value concentration; Oral formulations gain share through continuous processing advances.
Client Type:
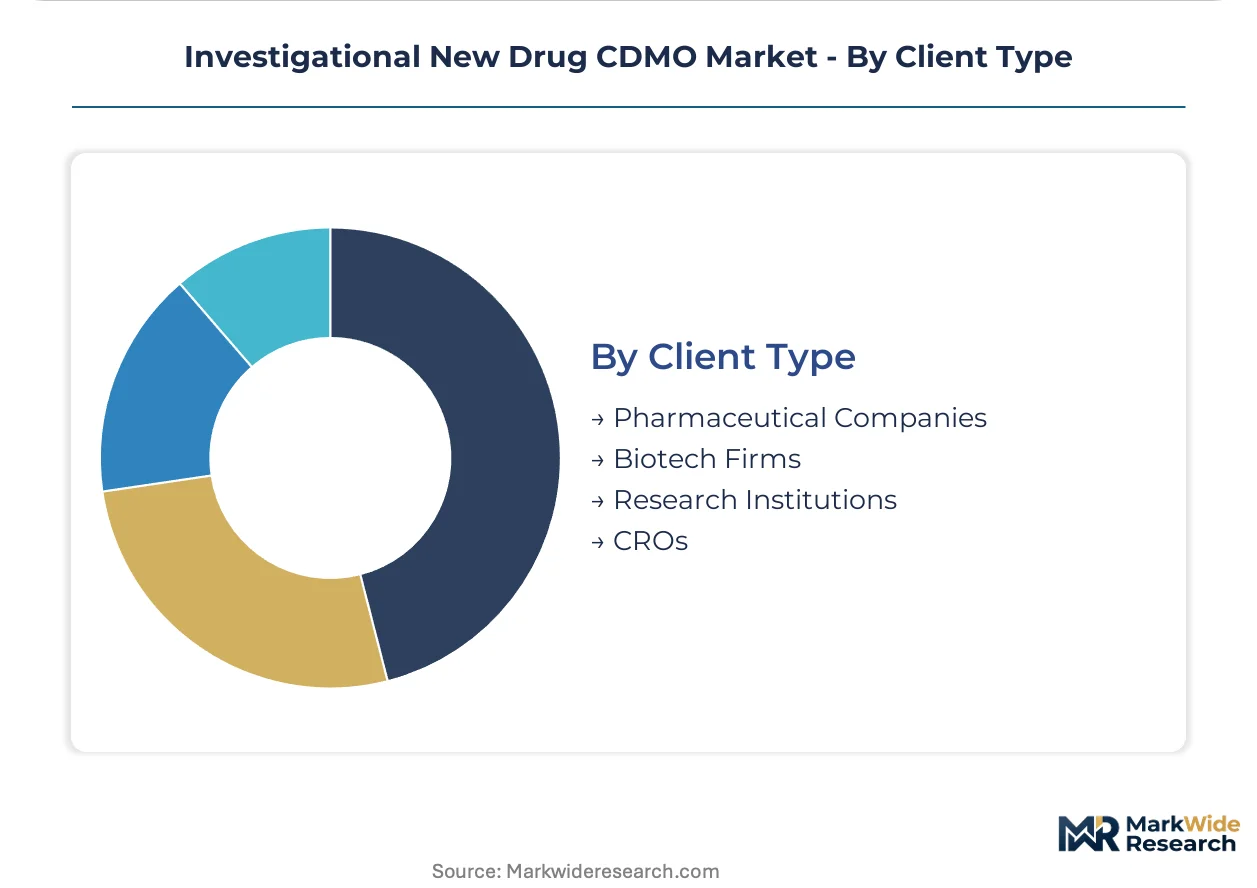
Organizational scale and funding stage determine outsourcing scope, with venture-backed biotechs driving fragmentation and Big Pharma consolidation compressing vendor panels.
- Pharmaceutical Companies:Large sponsors with internal manufacturing assets selectively outsource for capacity flexibility or specialized modalities. They favor master service agreements with volume commitments and dedicated FTE teams.
- Biotech Firms:Venture-backed development-stage companies without captive manufacturing infrastructure. These sponsors consolidate relationships with full-service CDMOs capable of integrated drug substance-to-drug product workflows, displacing fragmented specialty provider panels.
- Research Institutions:Academic medical centers and nonprofit research organizations with grant-funded discovery programs requiring small-batch GMP production for first-in-human investigator-initiated trials.
- CROs:Contract research organizations extending service portfolios into manufacturing through strategic partnerships or captive CDMO acquisitions.
Biotech Firms drive volume expansion; Pharmaceutical Companies anchor contract value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland commands deeper margins per manufacturing slot than Singapore, though the city-state's biologics capacity expansion is accelerating faster than Basel's constrained real estate allows.
United States
FDA's Quality Management Maturity program drives sponsor selection toward CDMOs with documented inspection readiness across multiple IND submissions. Massachusetts anchors the densest cluster, with Greater Boston biotechs outsourcing integrated CMC workflows to Wilmington-based manufacturing hubs. The FDA's advanced manufacturing designation pathway rewards domestic adopters of process analytical technology.
Switzerland
Swissmedic maintains stringent GMP enforcement that elevates compliance costs but secures premium pricing for Visp and Basel facilities. The country's drug substance capacity is shifting decisively toward high-potency APIs and antibody-drug conjugates as sponsors demand integrated development-to-commercial pathways. Lonza leverages its Visp campus to anchor microbial and mammalian cell culture services.
Singapore
Biologics manufacturing investments from Western CDMOs concentrate in Tuas Biomedical Park, drawn by tax incentives and proximity to Asia-Pacific clinical trial networks. The Economic Development Board's biomedical sciences initiative funds specialized containment infrastructure for oncology programs. The city-state's viral vector production capacity remains undersupplied relative to cell and gene therapy pipeline growth.
Germany
EMA's revised Annex 1 on sterile manufacturing mandates gloveless isolator installations across German parenteral formulation sites by 2024 implementation deadlines. The country's CDMOs concentrate in Baden-Württemberg and Bavaria, serving mid-sized pharma sponsors with hybrid small-molecule and biologic portfolios. German facilities face extended campaign changeover timelines for high-potency compounds.
India
CDSCO's evolving biosimilar guidelines attract Western sponsor investment in Hyderabad and Bangalore mammalian cell culture capacity. The country's biologics corridor offers cost-advantaged development services as biotech firms seek alternatives to Basel and Boston labor premiums. Indian CDMOs are capturing preclinical and Phase I chemistry outsourcing from European virtual biotechs.
Investigational New Drug CDMO Market Key Industry Players
Swiss producers anchor the premium-tier manufacturing segment; United States specialists hold dominant positions in integrated development-to-commercial workflows. The vendor base structures around three tiers: global full-service platforms with multi-continent footprints, regional high-potency containment specialists, and niche viral vector manufacturers. Consolidation pressure is compressing vendor panels as biotech sponsors demand single-source accountability across drug substance and drug product. Capacity reservation agreements and dedicated FTE teams represent the dominant competitive moves.
Within the full-service platform tier, Lonza and Thermo Fisher Scientific exemplify geographic diversification strategies that span Swiss high-potency API synthesis with North American biologics fill-finish. Charles River Laboratories occupies a distinct position anchoring integrated toxicology and CMC capabilities around the Massachusetts research corridor. These three entities represent the consolidation endpoint that venture-backed biotechs increasingly favor over fragmented specialty provider relationships.
| Leading Market Players |
|---|
| Siegfried Holding AG |
| Charles River Laboratories |
| Lonza |
| IQVIA Holdings Inc. |
| Cambrex Corporation |
| Catalent |
| Recipharm |
| Syneos Health |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Stainless steel bioreactor vessel pricing indices cascade through CDMO supply chains into three-tier pricing structures across premium, standard, and economy levels, with high-potency containment requirements and single-use polymer feedstock volatility compressing margins at the mid-tier while Swiss and Singaporean facilities capture premium markups through FDA Quality Management Maturity ratings.
Pricing Analysis
Direct-to-sponsor contracting eliminates distributor margins, compressing price realization for standard-tier development services while premium manufacturing slots command capacity reservation premiums. Price differentiation hinges on isolator containment certification and FDA inspection history, with biotech sponsors in Massachusetts showing lowest price sensitivity for ADC programs and European virtual biotechs driving hardest bargain on preclinical chemistry. Pricing pressure stems from Indian CDMOs capturing Phase I outsourcing with cost-advantaged mammalian cell culture, forcing Basel and Boston facilities to defend positioning through integrated toxicology bundles.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for biologics manufacturing are reshaping sourcing patterns for Western sponsors seeking cost-advantaged capacity. Supply concentrates in Switzerland, Singapore, and Massachusetts, with single-use bioreactor bags and sterile connectors drawing from concentrated polymer suppliers in Germany and Japan. Single-source vulnerability for high-potency containment isolators creates bottlenecks during capacity expansion cycles. Distribution runs through direct sponsor-CDMO master service agreements with dedicated FTE teams displacing spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on gene therapy vector production premiums and continuous manufacturing adoption reducing batch failure costs.
For Market Incumbents: Acquire viral vector manufacturing capacity to anchor cell and gene therapy pipelines against emerging Indian biologics corridors. Defend positioning by embedding dedicated FTE teams within Massachusetts venture-backed sponsors through multi-candidate master service agreements. Prioritize gloveless isolator retrofits ahead of EMA Annex 1 deadlines to secure premium sterile fill-finish pricing. For New Entrants and Emerging Players: Mid-sized pharmaceutical companies with hybrid small-molecule and biologic portfolios represent the most penetrable buyer archetype, as these sponsors fragment sourcing between German parenteral specialists and Swiss ADC facilities. Target Baden-Württemberg and Bavaria for CMO partnerships serving sponsors seeking alternatives to Lonza-Thermo Fisher duopoly. Lead with continuous manufacturing adoption and FDA advanced manufacturing designation pathway support as differentiated entry angle. For Investors and Strategic Acquirers: Asymmetric upside sits with regional high-potency containment specialists possessing isolator infrastructure and Swissmedic inspection track records. Long-term viability favors CDMOs with viral vector capabilities as cell and gene therapy pipelines expand beyond oncology. Watch FDA advanced manufacturing designation awards as inflection signal for competitive repositioning between domestic and ex-US capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Vector Capacity Buildout | Viral vector manufacturing for AAV platforms addresses undersupplied capacity as rare disease pipelines expand. |
| Continuous Manufacturing Adoption | FDA advanced manufacturing designation pathway rewards sponsors adopting process analytical technology and real-time release testing. |
| High-Potency Containment Investment | Isolator technology and dedicated HVAC infrastructure for ADC payloads commands premium pricing from oncology sponsors. |
| Integrated CMC-Toxicology Partnership | Wilmington-based hubs combining IND-enabling toxicology with drug substance manufacturing compress sponsor vendor panels. |
| India Biologics Corridor Expansion | Hyderabad and Bangalore mammalian cell culture capacity offers cost-advantaged alternatives to Basel and Boston labor premiums. |
Research Approach
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and CDMO procurement directors; secondary validation through FDA IND filings, EMA GMP inspection databases, and ClinicalTrials.gov protocols; and trade data on bioreactor equipment imports — were reconciled through bottom-up and top-down triangulation across the analysis window.
Historical capacity utilization trends were cross-referenced against panel input from biotech CFOs and venture capital partners to anchor growth assumptions. The analytical framework modeled segmentation across service type, therapy area, delivery mode, and client funding stage, with CAGRs derived from sponsor outsourcing intensity curves and facility expansion timelines. Forecast inputs included antibody-drug conjugate pipeline density and viral vector manufacturing capacity gaps.
Underlying measurement precision varies by segment; Development Services and Manufacturing Services carry tighter precision than Regulatory Services due to more visible contract flow. Forecasts reflect assumptions on sponsor consolidation behavior and regulatory implementation timelines, with single-use equipment lead times and specialized labor scarcity representing primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Small Molecule CDMO Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market