
 Cryptogenic Stroke Treatment Market | 2026-2036
Cryptogenic Stroke Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptogenic Stroke Treatment Market Outlook
A shortage of neurointerventional specialists is reorganizing how cryptogenic stroke care gets delivered across tertiary centers. Bristol-Myers Squibb Company leverages its anticoagulant portfolio to sustain presence in secondary prevention protocols. Boehringer Ingelheim GmbH anchors European hospital formularies with direct oral anticoagulant access programs. Daiichi Sankyo Company, Limited competes aggressively in East Asian markets through region-specific dosing regimens.
Cryptogenic stroke treatment encompasses diagnostic and therapeutic interventions targeting strokes of undetermined source after standard vascular, cardiac, and serologic workup, including cardiac monitoring for occult atrial fibrillation and percutaneous patent foramen ovale closure using nitinol-based occluder devices. The primary purpose is reducing recurrent stroke risk in patients with negative conventional evaluations. Anticoagulants command the largest current revenue pool given established reimbursement for oral factor Xa inhibitors. Catheter-based devices represent the fastest-expanding segment as randomized trial data validates PFO closure efficacy. Home care end-user channels remain nascent but carry margin upside through remote cardiac monitoring integration.
FDA breakthrough device pathways and AHA/ACC joint guideline updates shape trial design and commercial launch sequencing in the United States, while EMA centralized procedures govern pan-European market access for novel occluder technologies. Clinicians and procurement officers must weigh long-term recurrence data against device durability signals as portfolio decisions crystallize.
Market Dynamics
Catheter-based PFO closure devices are displacing extended cardiac monitoring as the preferred intervention for eligible cryptogenic stroke patients, driven by accumulating randomized trial evidence and streamlined FDA breakthrough pathways that compress commercialization timelines.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for nitinol occluder technologies compress the gap between pivotal trial completion and commercial availability in US stroke centers.
- East Asian Hospital Networks:Specialized stroke centers in Japan and South Korea are integrating percutaneous closure into standard diagnostic protocols for patients under 60 with confirmed PFO.
- Direct Oral Anticoagulant Formulary Expansion:European hospital procurement frameworks now list factor Xa inhibitors as first-line secondary prevention, expanding addressable patient pools beyond warfarin-tolerant cohorts.
Market Restraints
- Neurointerventional Specialist Shortage:Tertiary centers in Germany and the United States face 18-24 month recruitment timelines for trained operators capable of performing transcatheter closure procedures.
- Nitinol Raw Material Concentration:Superelastic alloy supply chains concentrate among three primary metallurgical suppliers, exposing device manufacturers to price volatility and allocation risk.
- Reimbursement Uncertainty for Extended Monitoring:CMS and private payors apply inconsistent coverage determinations for implantable loop recorders beyond 30-day monitoring windows, constraining diagnostic revenue streams.
Strategic Opportunities
- Remote Cardiac Monitoring Integration:Home-based telemetry platforms paired with AI-arrhythmia detection algorithms create new service revenue models outside hospital-based episode reimbursement.
- Indian Subcontinent Penetration:Underdeveloped stroke center infrastructure in tier-2 cities presents first-mover advantage for mobile diagnostic units combined with telemedicine-enabled specialist consultation.
- EMA MDR Harmonization:Streamlined conformity assessment procedures for Class III implantable devices reduce duplicate clinical testing costs across EU member states.
Industry Challenges
- Interventional Neuroradiology Training Pipeline:Fellowship programs graduate fewer than 150 new specialists annually across OECD markets, creating persistent staffing bottlenecks for 24/7 stroke center coverage.
- Legacy EHR Integration Complexity:Proprietary data formats from implantable diagnostic devices require costly middleware development to achieve interoperability with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptogenic Stroke Treatment Market |
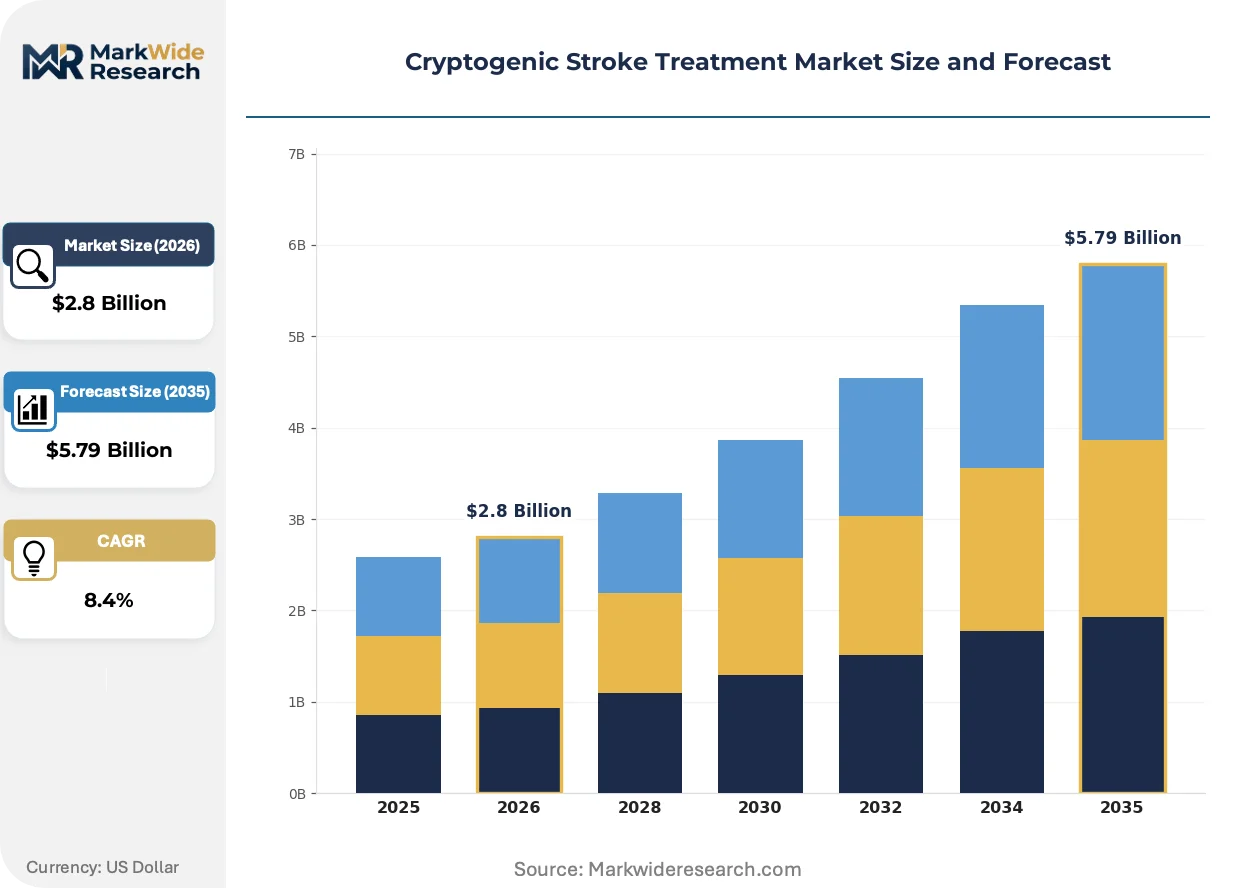
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Antiplatelets, Catheter-based Devices, Surgical Interventions End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Technology: Mechanical Thrombectomy, Ultrasound, MRI-guided Therapy, Drug-eluting Devices Application: Acute Treatment, Preventive Care, Research Studies, Patient Monitoring |
| Companies Covered | Bristol-Myers Squibb Company, Sanofi, Johnson & Johnson Services, Inc., Boehringer Ingelheim GmbH, F. Hoffmann-La Roche, Daiichi Sankyo Company, Limited, Amgen Inc., AstraZeneca, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptogenic Stroke Treatment Market Strategic Shifts
Diagnostic and therapeutic modalities for cryptogenic stroke are converging around minimally invasive platforms that compress the time from index event to definitive intervention, reducing reliance on prolonged observational strategies.
Bioresorbable PFO closure technologies are fragmenting the occluder device landscape by eliminating permanent implant burden. Academic medical centers in Boston and Rotterdam are piloting magnesium-alloy frameworks that degrade within 24 months. This approach is compressing the addressable market for traditional nitinol-based permanent implants among younger patient cohorts concerned about long-term foreign body retention.
The AHA/ACC joint guideline update establishing Class I indication for PFO closure in selected patients is restructuring referral patterns across US health systems. Emergency departments now route appropriate candidates directly to interventional cardiology rather than neurology-led extended monitoring protocols. This shift most acutely affects integrated delivery networks in California and Texas where stroke center certification density is highest.
Hospital procurement officers are unbundling device procurement from procedural reimbursement, negotiating standalone pricing for occluders and delivery systems. This behavior concentrates among IDNs with captive catheterization lab networks in the Midwestern United States, where purchasing consortia aggregate volume across 15-20 facilities to extract tiered pricing concessions from manufacturers.
Cryptogenic Stroke Treatment Market Segmentation
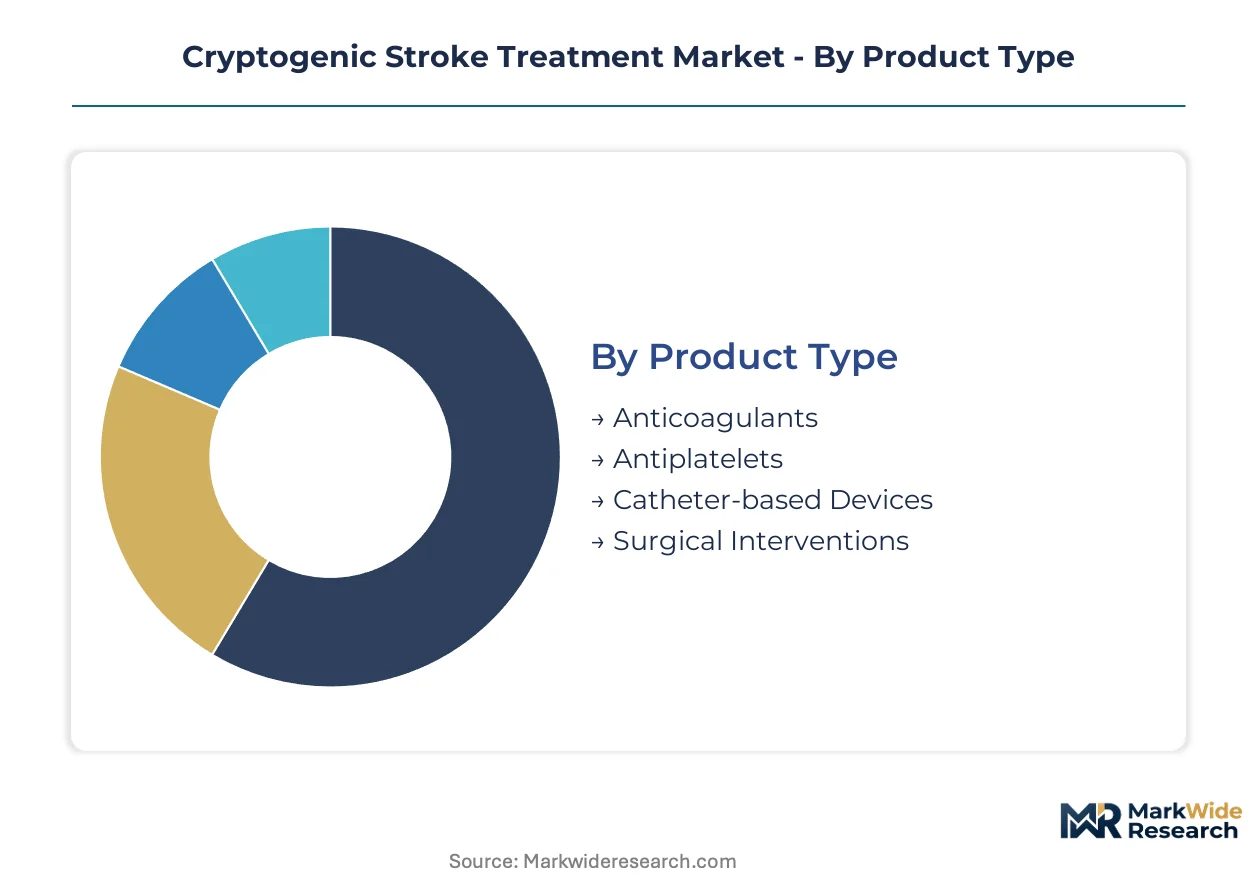
Segmentation in cryptogenic stroke treatment reveals distinct margin architectures across therapeutic modalities. Product type stratification exposes anticoagulant commoditization pressures against device premiumization opportunities, while end-user channels diverge sharply between hospital-based procedural revenue and emerging remote monitoring services.
Product Type:
Margin pools concentrate in catheter-based interventions where nitinol occluder devices command premium pricing against genericized pharmaceutical alternatives.
- Anticoagulants:Oral factor Xa inhibitors and vitamin K antagonists constitute the foundational pharmacological approach for secondary prevention. Demand concentrates in United States integrated delivery networks where CMS reimbursement favors DOACs over warfarin, though pricing compression from patent expirations constrains manufacturer margins.
- Catheter-based Devices:Nitinol-based PFO occluders and delivery systems enable percutaneous closure without thoracotomy. Adoption accelerates in German and Japanese stroke centers where specialized interventional cardiology infrastructure supports 24/7 procedural availability, with FDA breakthrough pathways compressing commercialization timelines for novel device entrants.
- Antiplatelets:Aspirin and P2Y12 inhibitors serve as bridge therapy or alternatives for anticoagulation-ineligible patients.
- Surgical Interventions:Direct suture closure and epicardial approaches persist for anatomically complex PFO anatomies unsuitable for transcatheter delivery.
The dominant share belongs to anticoagulants, while catheter-based devices are closing the gap fastest.
End User:
Revenue concentration tracks procedural complexity and reimbursement intensity across acute care settings versus longitudinal monitoring environments.
- Hospitals:Tertiary stroke centers generate the majority of procedural revenue through catheterization lab-based PFO closure and acute mechanical thrombectomy. United States hospital networks in California and Texas leverage stroke center certification density to capture referral volume from emergency department triage protocols.
- Home Care:Remote cardiac monitoring platforms with implantable loop recorders and AI-arrhythmia detection algorithms represent the emerging margin frontier. Japanese health systems pilot subscription-based telemetry services that decouple diagnostic revenue from hospital episode reimbursement.
- Clinics:Outpatient neurology practices manage anticoagulation titration and post-procedural follow-up.
- Rehabilitation Centers:Post-acute facilities coordinate secondary prevention adherence and functional recovery protocols.
Hospitals retain the dominant share, though home care is expanding most quickly.
Technology:
Technology differentiation separates established mechanical platforms from imaging-guided and pharmaceutical-device hybrid innovations.
- Mechanical Thrombectomy:Stent retrievers and aspiration catheters address large vessel occlusion in acute cryptogenic stroke presentations. Demand clusters in United States comprehensive stroke centers where neurointerventional specialist availability enables rapid endovascular intervention.
- Drug-eluting Devices:Combination products delivering localized antithrombotic agents from occluder surfaces aim to reduce device-related thrombosis risk. European academic medical centers in Rotterdam and Milan evaluate magnesium-alloy bioresorbable frameworks that eliminate permanent implant burden.
- Ultrasound:Transcranial Doppler and bubble studies support PFO detection and right-to-left shunt quantification.
- MRI-guided Therapy:Real-time magnetic resonance imaging enables radiation-free interventional navigation for selected anatomies.
Mechanical thrombectomy holds the dominant share, while drug-eluting devices are gaining share fastest.
Application:
Application segmentation maps to distinct reimbursement episodes and clinical trial enrollment pathways across the treatment continuum.
- Acute Treatment:Emergency mechanical thrombectomy and immediate anticoagulation initiation following index cryptogenic stroke event. German hospital networks optimize door-to-device times through pre-hospital notification systems and direct catheterization lab activation protocols.
- Preventive Care:PFO closure and long-term anticoagulation for recurrence risk reduction. Japanese stroke centers integrate percutaneous closure into standard diagnostic workflows for patients under 60 with confirmed shunt anatomy.
- Patient Monitoring:Extended cardiac telemetry and implantable loop recorder surveillance for occult atrial fibrillation detection.
- Research Studies:Academic consortia enrollment for novel device and pharmaceutical trial protocols.
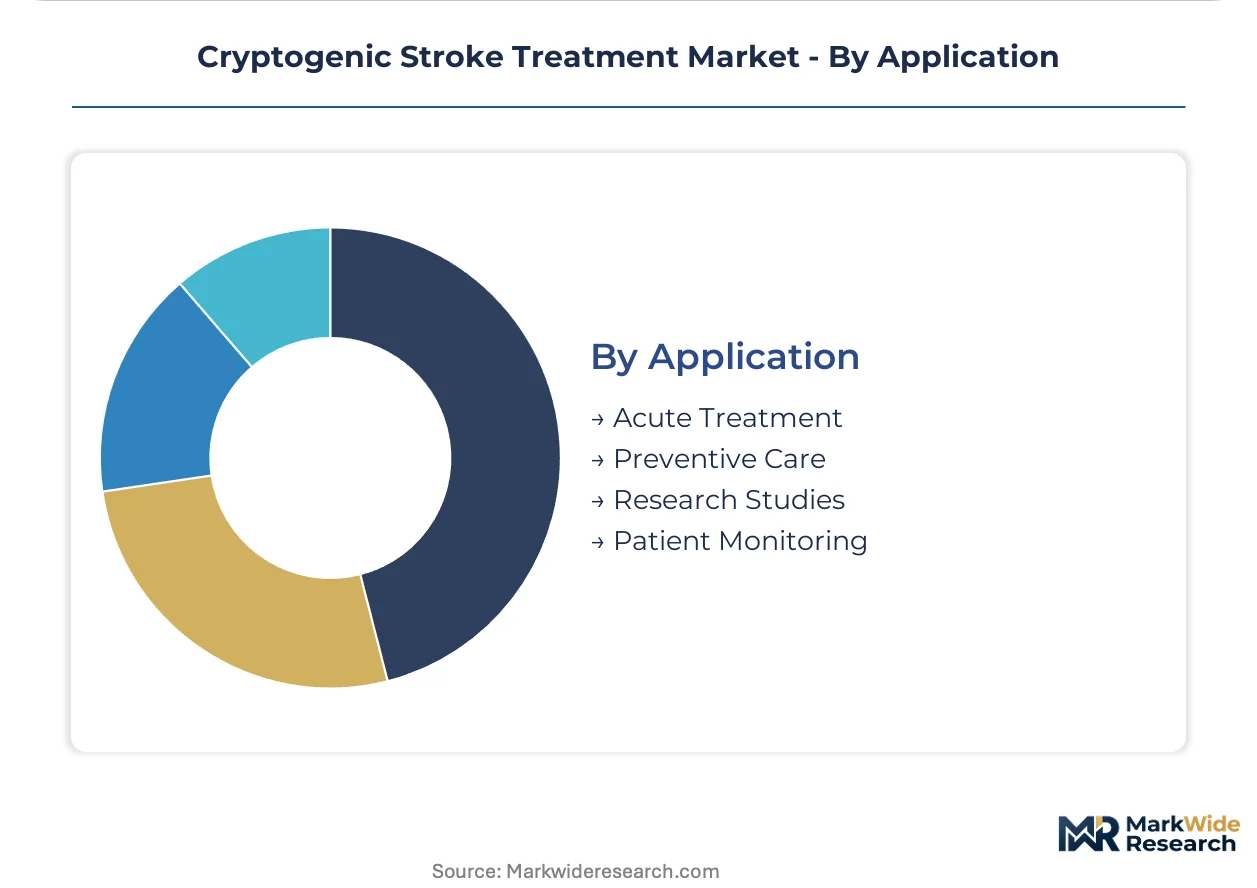
Acute treatment commands the dominant share, while preventive care is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough pathways in the United States anchor the regulatory environment for cryptogenic stroke device commercialization, while specialized stroke center networks in Germany and Japan concentrate procedural expertise and patient volume.
United States
Comprehensive stroke centers in California and Texas capture emergency department referral volume through direct catheterization lab activation protocols. CMS reimbursement frameworks favor direct oral anticoagulants over warfarin for secondary prevention, expanding formulary access across integrated delivery networks. The Greater Boston medical corridor pilots bioresorbable magnesium-alloy occluder frameworks through academic consortia.
Germany
Tertiary centers in Bavaria and North Rhine-Westphalia optimize door-to-device times through pre-hospital notification systems for mechanical thrombectomy. EMA centralized procedures govern pan-European market access for novel Class III implantable devices under MDR harmonization. The Heidelberg-Mannheim stroke network integrates percutaneous PFO closure into standard diagnostic workflows for patients under 60.
Japan
Specialized stroke centers in Tokyo and Osaka deploy percutaneous closure for confirmed PFO anatomy in younger patient cohorts. PMDA regulatory pathways align with FDA breakthrough designations to compress commercialization timelines for nitinol occluder technologies. Kansai region health systems pilot subscription-based remote cardiac telemetry services that decouple diagnostic revenue from hospital episode reimbursement.
United Kingdom
London and Southeast England stroke networks concentrate interventional neuroradiology expertise amid fellowship program bottlenecks limiting specialist supply. NICE technology appraisals influence formulary positioning for oral factor Xa inhibitors against vitamin K antagonists. The Oxford-Cambridge corridor participates in European academic consortia evaluating drug-eluting device surfaces.
South Korea
Seoul Capital Area stroke centers integrate cardiac monitoring for occult atrial fibrillation into index event protocols. MFDS regulatory alignment with FDA and PMDA frameworks accelerates market entry for catheter-based closure devices. Busan-Ulsan hospital networks develop 24/7 interventional cardiology coverage to match Japanese and German procedural availability standards.
Cryptogenic Stroke Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the cryptogenic stroke treatment market. Pharmaceutical conglomerates with anticoagulant portfolios occupy the upper tier, while device specialists concentrate in catheter-based occluder manufacturing. Two strategic archetypes dominate: diversified pharma-device hybrids leveraging cross-portfolio bundling, and pure-play interventional device houses pursuing FDA breakthrough pathways. Competitive moves center on M&A for neurointerventional specialist networks and strategic partnerships for nitinol raw material security.
Among North American pharmaceutical conglomerates, Bristol-Myers Squibb Company and Johnson & Johnson Services, Inc. exemplify the diversified archetype with anticoagulant and device portfolios spanning secondary prevention. Boehringer Ingelheim GmbH and Daiichi Sankyo Company, Limited represent geography-specific formulary anchors—German and Japanese respectively—where regional dosing regimens and hospital procurement relationships sustain competitive position. These four companies illustrate how regulatory origin and therapeutic focus shape market access architecture.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Sanofi |
| Johnson & Johnson Services, Inc. |
| Boehringer Ingelheim GmbH |
| F. Hoffmann-La Roche |
| Daiichi Sankyo Company, Limited |
| Amgen Inc. |
| AstraZeneca |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month recruitment timelines for neurointerventional specialists concentrate pricing power among tertiary stroke centers with captive catheterization lab capacity, compressing margins for device manufacturers while amplifying hospital procurement leverage.
Pricing Analysis
United States-Germany price spreads for nitinol occluder devices reflect divergent hospital procurement consolidation levels. Three-tier pricing structure across premium, standard, and economy levels segments by certification tier and procedural volume commitments. Pricing pressure stems from patent expirations in oral factor Xa inhibitors, forcing pharmaceutical portfolios toward commoditization. Integrated delivery networks exhibit highest price sensitivity; specialized Japanese stroke centers demonstrate lowest sensitivity due to reimbursement alignment.
Supply Chain Analysis
United States, Germany, and Japan anchor nitinol superelastic alloy processing and finished occluder device manufacturing. Supply chains draw from concentrated metallurgical feedstock sources, proprietary delivery system components, and sterilization packaging materials. Single-source vulnerability in superelastic alloy suppliers exposes manufacturers to allocation risk and price volatility. Distribution runs through hospital procurement consortia and specialized cardiovascular device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
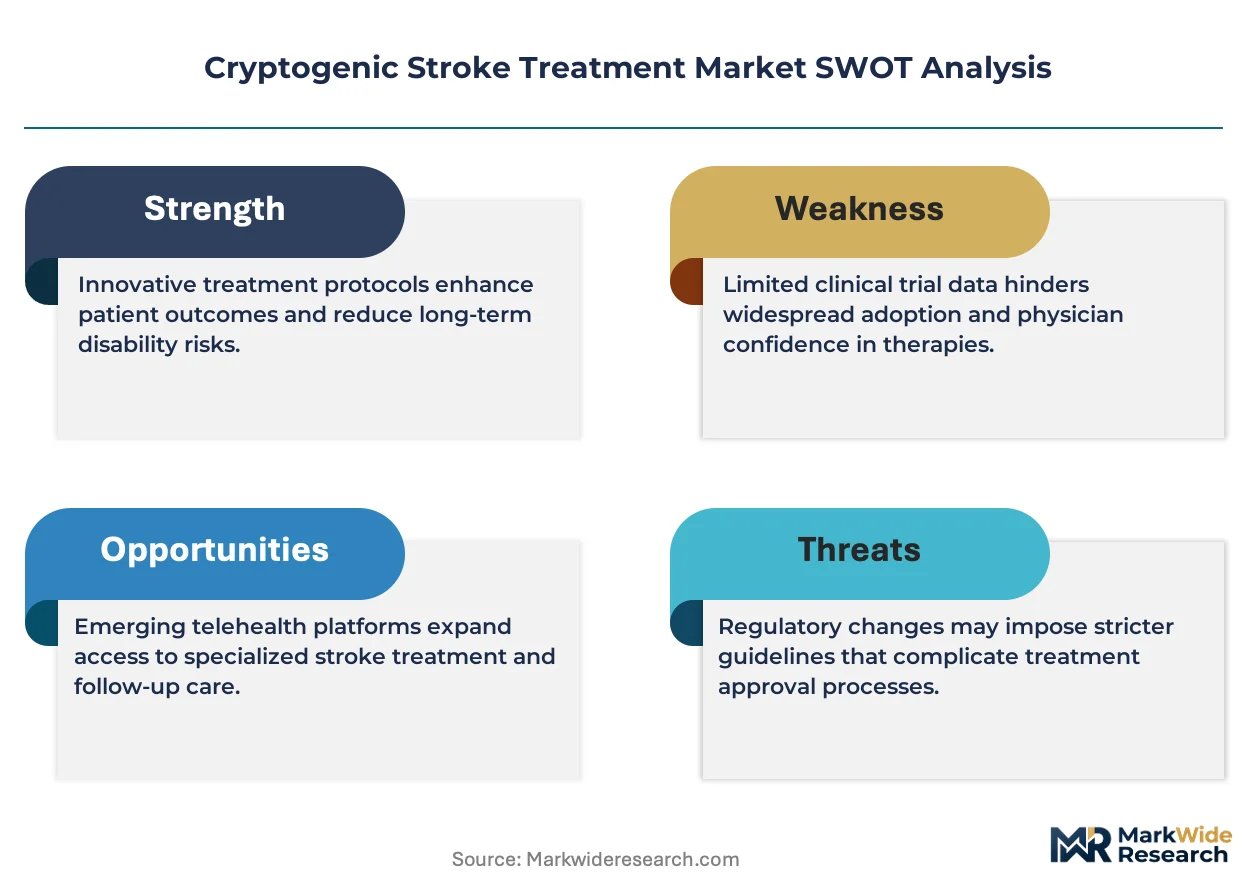
Cryptogenic stroke treatment fragments across diagnostic and therapeutic modalities, with bioresorbable device innovation and remote monitoring integration creating distinct competitive niches for differentiated entrants.
For Market Incumbents: Consolidate specialist physician network relationships through training program endowments and catheterization lab equipment leasing arrangements. Secure nitinol raw material offtake agreements to defend against supply allocation disruptions. Backward integration into superelastic alloy processing buffers margin compression from metallurgical supplier concentration. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks commercialization timelines for novel occluder technologies targeting younger patient cohorts averse to permanent implants. Indian tier-2 cities and Southeast Asian stroke center networks present underpenetrated demand pools. Partner with telemedicine platforms to circumvent specialist shortage constraints. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because anticoagulant commoditization and device premiumization are bifurcating returns across pharmaceutical and interventional portfolios. Acquisition targets center on bioresorbable occluder development programs and AI-enabled remote cardiac monitoring platforms. Watch for PMDA-FDA regulatory harmonization signals as inflection indicators for East Asian market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses commercialization timelines for nitinol occluder entrants. |
| Hospital System Partnership | Integrated delivery network contracts secure procedural volume and procurement preference. |
| Bioresorbable Technology Development | Magnesium-alloy frameworks eliminate permanent implant burden for younger demographics. |
| Neurointerventional Training Endowment | Fellowship program funding addresses specialist shortage constraining procedural capacity. |
| Remote Monitoring Platform Integration | AI-arrhythmia detection creates subscription revenue outside hospital episode reimbursement. |
Study Parameters
Initial hypotheses were tested against primary input from interventional cardiologists, neurointerventional specialists, hospital procurement managers, and GPO contracts administrators and refined through secondary validation across FDA 510(k) filings, EMA MDR submissions, CMS reimbursement determinations, and clinical trial registry data. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Variance decomposition across product type, end-user channel, technology platform, and application segments structured the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated AHA/ACC guideline revision timelines and PMDA regulatory pathway harmonization signals.
Decision-makers should treat outputs as directional under assumptions of stable reimbursement frameworks and specialist training pipeline recovery; material deviation in FDA breakthrough designation velocity or nitinol supply allocation would warrant model refresh. Recalibration cycles align with material shifts in guideline updates and regulatory harmonization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
China Cardiovascular Devices Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market