
 Cardiovascular Prosthetic Devices Market | 2026-2036
Cardiovascular Prosthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Prosthetic Devices Market Analysis
Interventional cardiologist training capacity is reorganizing how quickly transcatheter valve programs can launch across health systems. Edwards Lifesciences Corporation leverages its specialized heart valve centers to sustain premium positioning in tissue valve replacement. Medtronic plc anchors its competitive stance through integrated cath lab ecosystems that span imaging, delivery, and implant systems. Abbott Laboratories differentiates via structural heart portfolios that span closure, valve repair, and mechanical circulatory support.
Cardiovascular prosthetic devices encompass implantable or interventional products that replace, repair, or assist cardiac and vascular structures, typically manufactured from biocompatible metals, biological tissues, or polymer composites and sized to anatomical specifications ranging from pediatric to large-adult dimensions. These devices restore hemodynamic function in patients with valvular disease, coronary obstruction, aortic aneurysm, or ventricular failure. Valves command the deepest margin pools as transcatheter platforms shift replacement economics from surgery toward outpatient reimbursement models. Stents remain the highest-volume category though drug-eluting platforms face biosimilar pressure across European tenders. Pump devices represent the fastest-growing segment as temporary mechanical circulatory support expands from cardiogenic shock into prophylactic high-risk PCI.
The FDA maintains stringent premarket approval and humanitarian device exemption pathways that shape clinical evidence requirements and trial design for novel cardiovascular prosthetics. EMA's Medical Device Regulation imposes enhanced notified body scrutiny and post-market surveillance obligations that extend time-to-market for European launches. Japan's PMDA operates a priority review system for orphan and breakthrough cardiovascular devices that accelerates access for innovative structural heart technologies. Stakeholders must monitor how converging regulatory demands for real-world performance data reshape post-approval study commitments and commercial forecasting assumptions.
Market Dynamics
Transcatheter delivery platforms are compressing the entire care pathway from diagnosis to discharge, forcing manufacturers to restructure clinical support models around same-day procedures rather than surgical suites.
Growth Catalysts
- Japan's PMDA Priority Review:Accelerated approval timelines for breakthrough structural heart devices compress time-to-revenue for novel valve technologies targeting orphan indications.
- Cath Lab Infrastructure Expansion:Metropolitan hospital networks in India and China are installing interventional suites capable of complex structural heart procedures, extending addressable patient pools beyond surgical candidates.
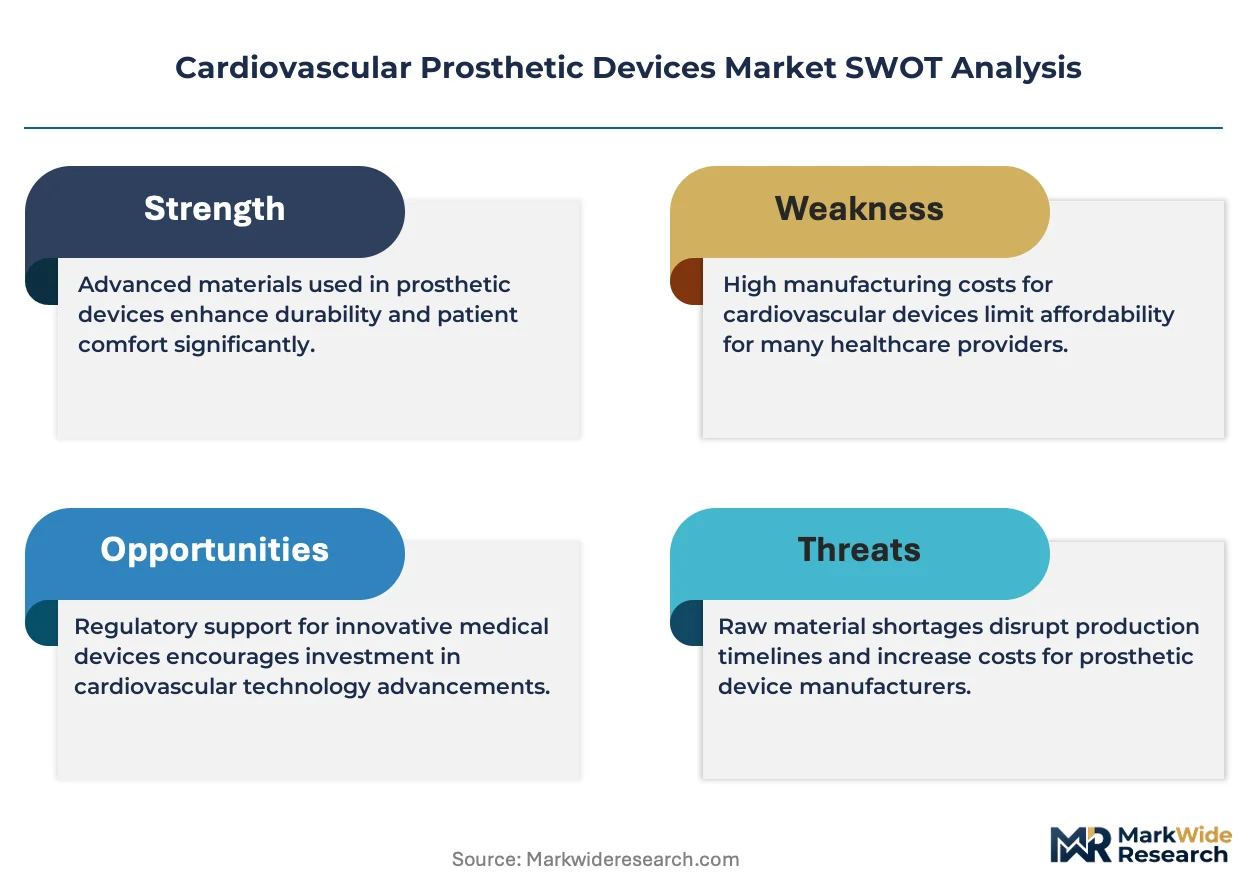
- Biological Tissue Engineering:Advances in xenograft tissue processing are extending valve durability, reducing reintervention rates and expanding eligibility to younger patient cohorts previously reserved for mechanical alternatives.
Market Restraints
- Platinum-Iridium Alloy Supply Concentration:Cathode component sourcing for electrode-equipped devices clusters with South African and Russian refiners, exposing lead times to geopolitical friction.
- EMA MDR Transition Costs:Enhanced notified body scrutiny and post-market surveillance obligations under the Medical Device Regulation extend European launch timelines and inflate regulatory compliance overhead.
- Surgical Robot Substitution:Minimally invasive surgical platforms with robotic assistance are recapturing some valve patients who might otherwise migrate to transcatheter approaches.
Strategic Opportunities
- Pediatric Structural Heart:Underpenetrated congenital valve repair markets in Brazil and Mexico present first-mover potential for downsized transcatheter systems.
- FDA Breakthrough Device Designation:Expedited review pathways for innovative cardiovascular prosthetics compress development cycles and enable earlier pricing power capture.
- AI-Enabled Imaging Integration:Convergence of intraprocedural echocardiography with machine learning guidance systems enables real-time valve positioning without surgical backup.
Industry Challenges
- Interventional Cardiologist Training Bottlenecks:Proctoring requirements and case volume thresholds limit how quickly health systems can launch new transcatheter valve programs.
- Biocompatibility Certification Timelines:ISO 10993 testing protocols for novel polymer composites extend preclinical validation phases before regulatory submission.
- Legacy Hospital Information System Integration:Cath lab workflow software often requires custom middleware to connect with enterprise electronic health records, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Prosthetic Devices Market |
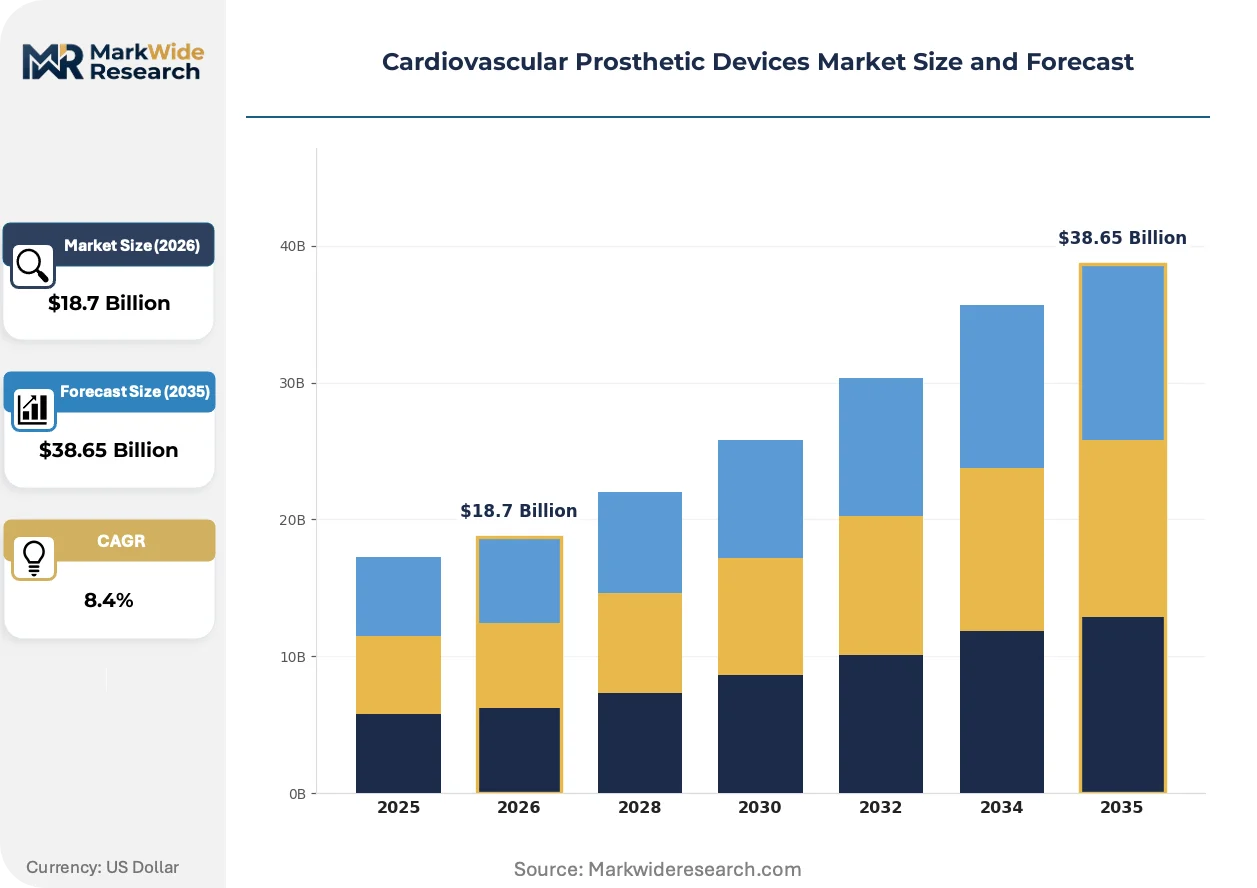
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valves, Stents, Grafts, Pump Devices End User: Hospitals, Cardiac Clinics, Research Institutions, Outpatient Centers Material: Biomaterials, Metals, Polymers, Composites Technology: Mechanical, Biological, Hybrid, Drug-Eluting |
| Companies Covered | Edwards Lifesciences Corporation, Abbott Laboratories, Medtronic plc, Boston Scientific Corporation, W. L. Gore & Associates, Inc., Abiomed, Inc., BIOTRONIK SE & Co. KG, Lifetech Scientific Co., Ltd., Venus Medtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Prosthetic Devices Market Emerging Trajectories
Structural heart interventions are migrating from specialized surgical centers to ambulatory settings, compressing the entire value chain around procedural efficiency rather than inpatient recovery.
Transcatheter mitral valve repair technology is miniaturizing delivery systems from 24-French to sub-14-French profiles. Community hospitals with limited surgical backup are adopting these platforms for intermediate-risk patients. Device miniaturization is miniaturizing the required infrastructure investment, enabling procedure migration from academic medical centers to regional cardiac clinics.
The FDA's updated premarket submission pathways for breakthrough devices are compressing review timelines for novel valve technologies. Manufacturers are restructuring clinical trial designs around smaller cohorts and surrogate endpoints. Transcatheter aortic valve replacement programs in the United States are responding by accelerating pipeline progression from first-in-human to pivotal trials.
Hospital procurement committees are consolidating vendor relationships around integrated cath lab ecosystems that span imaging, delivery, and implant systems. Independent distributors are losing share to direct manufacturer contracts with metropolitan health networks. This concentration is most visible in the United States, where hospital system mergers have created regional purchasing monopolies negotiating enterprise-wide structural heart portfolios.
Cardiovascular Prosthetic Devices Market Segmentation
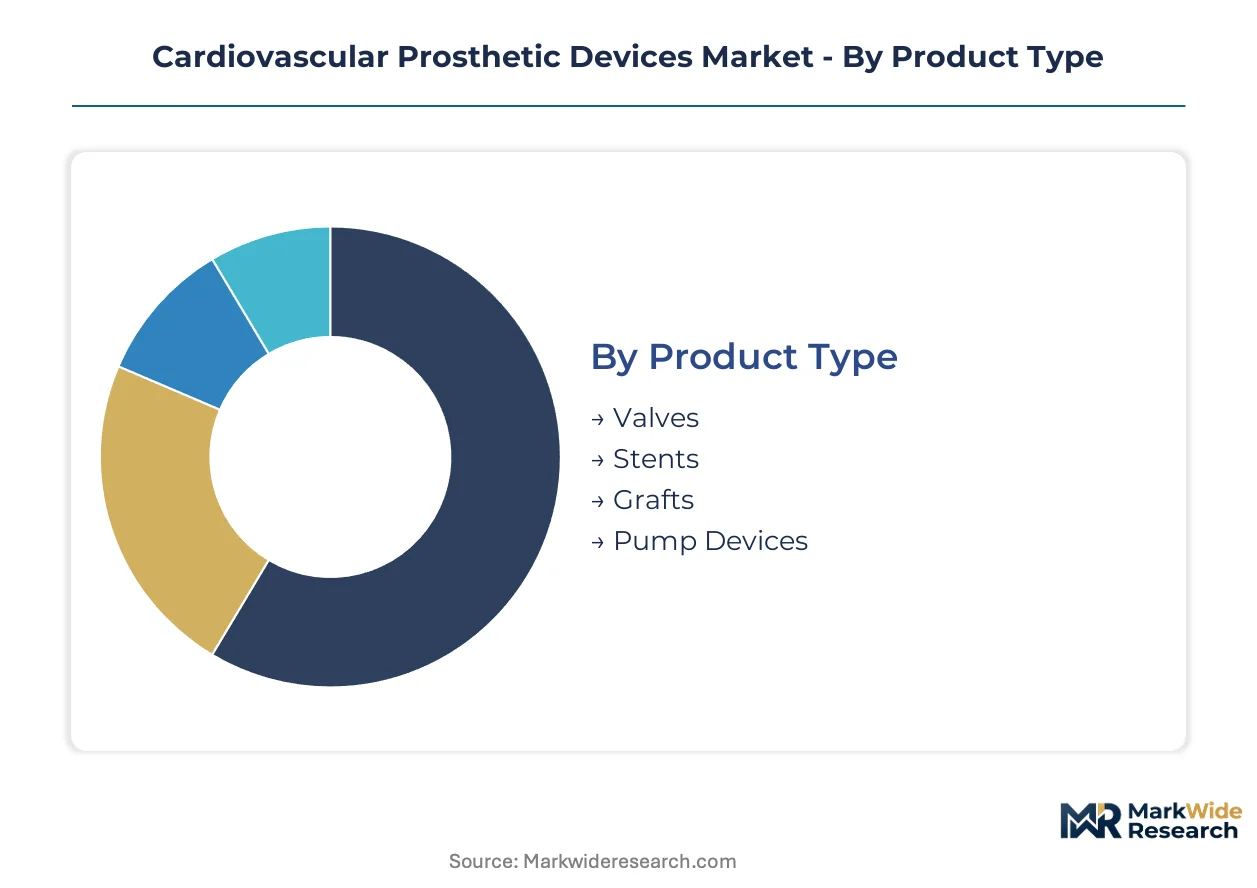
Segmentation in cardiovascular prosthetics reveals how margin pools shift between surgical and interventional platforms, with transcatheter technologies rewriting traditional category economics. Understanding these boundaries helps manufacturers allocate R&D resources across valve, stent, graft, and pump portfolios where reimbursement models diverge sharply.
Product Type:
Valves command the deepest margin pools as transcatheter platforms shift replacement economics from surgery toward outpatient reimbursement models.
- Valves:Tissue-engineered and mechanical configurations replace native or prosthetic cardiac valves across aortic, mitral, tricuspid, and pulmonary positions. Demand concentrates in metropolitan hospital networks within the United States, China, and India where cath lab infrastructure now supports complex structural heart interventions. Transcatheter delivery systems are capturing patients previously routed to surgical centers.
- Stents:Coronary and peripheral vascular scaffolds restore luminal patency in obstructed vessels, with drug-eluting platforms dominating revenue despite biosimilar pressure across European tenders. Hospital procurement committees in Germany and Japan are consolidating vendor relationships around integrated delivery systems that span imaging and implant technologies.
- Grafts:Synthetic or biological conduits bypass or replace diseased aortic and peripheral vascular segments.
- Pump Devices:Temporary mechanical circulatory support systems address cardiogenic shock and high-risk PCI prophylaxis.
The dominant share belongs to Valves, while Pump Devices are closing the gap fastest as temporary support expands beyond salvage therapy into elective intervention.
End User:
Procedure volume and reimbursement rates vary dramatically across facility types, with cardiac clinics capturing share from traditional inpatient settings.
- Hospitals:Academic medical centers and community hospitals maintain surgical backup capabilities for complex cases requiring conversion from transcatheter to open procedures. Cardiac clinics across Germany, Japan, and Brazil are expanding their interventional capabilities as transcatheter procedures replace open-heart surgery, eroding the hospital monopoly on valve replacement.
- Cardiac Clinics:Specialized interventional facilities perform diagnostic catheterization and therapeutic procedures without full surgical infrastructure. Metropolitan networks in the United States are installing hybrid suites capable of complex structural heart interventions, extending addressable patient pools beyond surgical candidates.
- Research Institutions:Academic centers conduct first-in-human and pivotal clinical trials for novel prosthetic technologies.
- Outpatient Centers:Ambulatory surgical facilities perform same-day transcatheter procedures with compressed recovery protocols.
Hospitals retain procedural volume leadership, though Cardiac Clinics are expanding most quickly as same-day discharge protocols mature.
Material:
Biocompatibility certification timelines and supply chain concentration shape competitive positioning across material categories.
- Biomaterials:Processed bovine, porcine, or equine tissues form valve leaflets and vascular patches with reduced thrombogenicity compared to synthetic alternatives. Advances in xenograft tissue processing are extending valve durability, reducing reintervention rates and expanding eligibility to younger patient cohorts previously reserved for mechanical alternatives.
- Metals:Cobalt-chromium, nitinol, and platinum-iridium alloys provide structural scaffolding for stents, valve frames, and electrode components. Platinum-iridium alloy sourcing for cathode-equipped devices clusters with South African and Russian refiners, exposing lead times to geopolitical friction.
- Polymers:Biocompatible elastomers and thermoplastics enable catheter delivery systems and temporary device components.
- Composites:Metal-polymer or ceramic-matrix hybrids optimize strength-to-flexibility ratios in next-generation delivery platforms.
Biomaterials anchor revenue concentration, while Composites are gaining share fastest as engineers optimize delivery system trackability.
Technology:
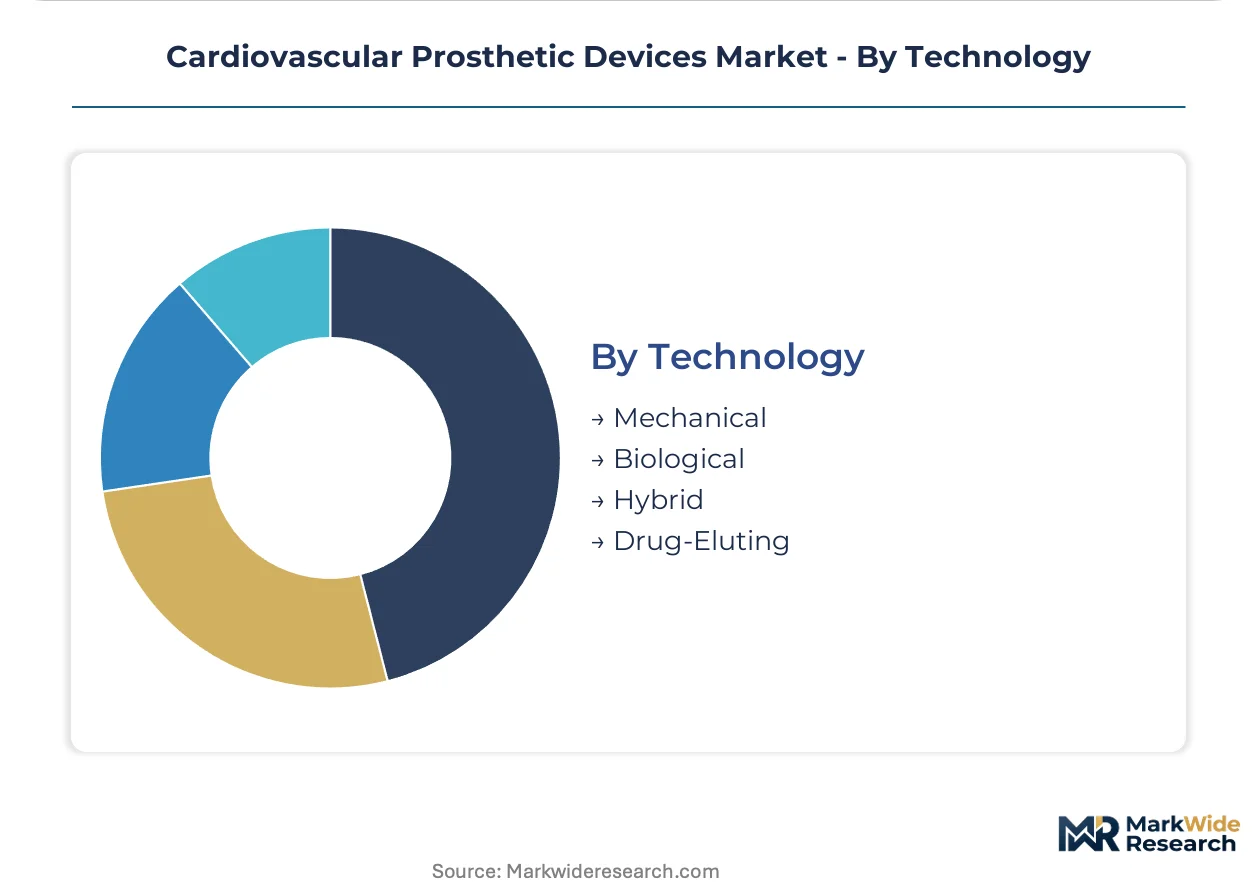
Regulatory pathways and clinical evidence requirements diverge sharply between mechanical durability and biological integration approaches.
- Mechanical:Carbon-based or metallic valve designs offer lifetime durability but require lifelong anticoagulation therapy. Surgical robot substitution with minimally invasive platforms is recapturing some valve patients who might otherwise migrate to transcatheter biological approaches, preserving mechanical valve relevance in younger populations.
- Biological:Tissue-derived valves and grafts eliminate anticoagulation burden but face structural valve deterioration requiring reintervention. The FDA's updated premarket submission pathways for breakthrough devices are compressing review timelines for novel valve technologies, accelerating biological platform iteration.
- Hybrid:Combined mechanical-biological designs optimize durability and hemodynamic performance.
- Drug-Eluting:Antiproliferative agent coatings reduce restenosis in coronary and peripheral stent applications.
Biological technology holds dominant positioning, though Hybrid configurations are climbing the fastest as engineers balance longevity and biocompatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor the United States as the dominant geography, while PMDA priority review and EMA MDR obligations shape competitive access across Japan and Europe. Metropolitan hospital networks in China and India are installing cath lab infrastructure that extends structural heart intervention beyond traditional surgical centers.
United States
Metropolitan hospital networks in Texas and Florida are consolidating vendor relationships around integrated cath lab ecosystems. FDA breakthrough device designation compresses review timelines for novel valve technologies, accelerating time-to-market. The Cleveland Clinic and Mayo Clinic anchor interventional cardiologist training capacity that limits how quickly competing health systems can launch transcatheter programs.
Germany
Cardiac clinics in Bavaria and North Rhine-Westphalia are expanding interventional capabilities as transcatheter procedures displace open-heart surgery volumes. EMA Medical Device Regulation imposes enhanced notified body scrutiny that extends European launch timelines. Berlin and Munich host specialized heart valve centers that sustain premium positioning for tissue-engineered replacement platforms.
Japan
PMDA priority review accelerates approval timelines for breakthrough structural heart devices targeting orphan indications. Tokyo and Osaka metropolitan networks install hybrid suites capable of complex mitral interventions without surgical backup. METI industrial policy supports domestic manufacturers developing downsized delivery systems for the aging population.
China
NMPA regulatory pathways are converging toward real-world performance data requirements that reshape post-approval study commitments. Shanghai and Beijing hospital systems are installing cath lab infrastructure that supports complex structural heart interventions. Provincial procurement tenders concentrate demand within metropolitan networks that negotiate enterprise-wide structural heart portfolios.
India
Metropolitan hospital networks in Maharashtra and Karnataka are extending addressable patient pools beyond surgical candidates through interventional suite expansion. CDSCO regulatory frameworks for cardiovascular prosthetics require biocompatibility certification that extends preclinical validation phases. Mumbai and Delhi cardiac clinics capture procedure volume from traditional inpatient settings as same-day discharge protocols mature.
Cardiovascular Prosthetic Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across valve, stent, graft, and pump device categories. The upper tier commands cath lab ecosystem relationships spanning imaging, delivery, and implant systems. Three archetypes dominate: integrated platform vendors, tissue-engineered valve specialists, and mechanical circulatory support innovators. Competitive moves concentrate on M&A to fill portfolio gaps and strategic partnerships to secure platinum-iridium alloy supply chains.
Within the integrated platform tier, Medtronic plc and Abbott Laboratories exemplify archetypes that anchor competitive positioning through cath lab ecosystem control. Edwards Lifesciences Corporation occupies a distinct position representing tissue-engineered valve specialization. Boston Scientific Corporation and W. L. Gore & Associates, Inc. sit within the interventional delivery system segment. Abiomed, Inc. anchors the mechanical circulatory support archetype. BIOTRONIK SE & Co. KG represents European-based fabricators with integrated cardiac rhythm and structural heart portfolios. Lifetech Scientific Co., Ltd. and Venus Medtech exemplify Asia-Pacific specialists developing downsized transcatheter systems for regional market access.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Abbott Laboratories |
| Medtronic plc |
| Boston Scientific Corporation |
| W. L. Gore & Associates, Inc. |
| Abiomed, Inc. |
| BIOTRONIK SE & Co. KG |
| Lifetech Scientific Co., Ltd. |
| Venus Medtech |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for platinum-iridium alloy cathodes lock in both supply access and price visibility for electrode-equipped cardiovascular devices, insulating manufacturers from spot-market volatility while committing them to fixed-volume procurement regardless of demand fluctuations.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement for critical metal components, with price differentiation resting on ISO 10993 certification tier and cathode purity grade. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated devices from CE-marked alternatives and unvalidated imports. Pricing pressure stems from biosimilar competition in European drug-eluting stent tenders. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement models, while provincial procurement committees in emerging markets drive hardest bargain.
Supply Chain Analysis
Strategic stockpiling of platinum-iridium alloys buffers against South African and Russian refiner concentration, though just-in-time preferences prevail for polymer catheter components. Raw material sourcing draws from South Africa, Russia, and Australia for precious metals; Germany and Switzerland for precision-machined cobalt-chromium frames; China for nitinol wire and polymer extrusions. Single-source vulnerability concentrates in cathode component supply. Distribution runs through direct manufacturer contracts with metropolitan hospital networks, bypassing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transcatheter platform miniaturization is compressing procedure economics and accelerating ambulatory migration, creating a high-growth disruption anchored by FDA breakthrough device designation pathways that reward first-mover clinical evidence.
For Market Incumbents: Shield premium positioning in tissue-engineered valves through exclusive heart valve center partnerships that limit competing proctor access. Deepen backward integration into xenograft tissue processing to control durability claims and reduce reintervention liability exposure. Surgical robot substitution threatens transcatheter volume capture in younger mechanical valve candidates. For New Entrants and Emerging Players: FDA breakthrough device fast-track offers compressed review timelines for novel structural heart technologies targeting orphan indications. Pediatric congenital valve repair in Brazil and Mexico presents underpenetrated white-space with limited incumbent proctor presence. Hospital system partnership models bypass distributor margin extraction. For Investors and Strategic Acquirers: Capital is best deployed toward integrated cath lab ecosystem vendors with imaging-delivery-implant convergence capabilities over standalone component specialists. Long-term viability favors platforms with recurring revenue from valve-in-valve reintervention pipelines. Watch PMDA priority review queue depth as inflection indicator for Asia-Pacific market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses premarket review timelines for novel valve technologies from first-in-human to pivotal trials. |
| Hospital System Partnership | Locks in cath lab ecosystem procurement across imaging, delivery, and implant systems within metropolitan networks. |
| CE Marking Pathway | Enables European commercial launch despite EMA MDR extended notified body scrutiny timelines. |
| Software Companion Development | Integrates AI-enabled intraprocedural echocardiography guidance for real-time valve positioning without surgical backup. |
| Reimbursement Strategy | Secures outpatient procedure codes that shift valve replacement economics from inpatient surgery toward same-day discharge. |
Methodological Framework
The analysis maps transcatheter valves, mechanical circulatory support, coronary stents, and vascular grafts, each validated through interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders triangulate against FDA 510(k) and PMA filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up patient volume modeling and top-down manufacturer revenue reconciliation ensure consistency.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include product type, end-user facility tier, material composition, and technology platform. CAGRs derive from procedure volume elasticity to cath lab infrastructure expansion, biological tissue durability improvements, and regulatory pathway acceleration. Forecast inputs incorporate PMDA priority review approval velocity and EMA MDR transition cost pass-through assumptions.
Underlying assumptions cover reimbursement code stability, cath lab proctor training capacity expansion, and platinum-iridium supply continuity, with deviation risk concentrated in geopolitical friction affecting precious metal sourcing and interventional cardiologist training bottlenecks limiting program launch velocity. Revision becomes warranted when FDA breakthrough designation grant rates or PMDA priority review queue processing times cross threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
Cardiovascular Devices Market