
 Artificial Blood Vessels Market | 2026-2036
Artificial Blood Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Blood Vessels Market Intelligence
Aftermarket graft surveillance and revision service revenue is rewriting profitability models across the vascular implant sector. Cook Medical leverages its endovascular training infrastructure to sustain high-touch customer relationships in academic medical centers. W. L. Gore & Associates anchors its position through proprietary expanded polytetrafluoroethylene manufacturing that competitors struggle to replicate. Medtronic differentiates via integrated catheter-to-graft portfolios that streamline hospital procurement workflows.
Artificial blood vessels are tubular prosthetic constructs engineered from polymers, collagen matrices, or composite biomaterials to restore or bypass damaged native vasculature, typically requiring tensile strength exceeding 2 MPa and porosity calibrated to prevent hemorrhage while enabling tissue ingrowth. Synthetic ePTFE grafts dominate open surgical procedures where immediate mechanical reliability outweighs biological integration needs, while biological and composite segments capture expanding share in regenerative medicine applications where endothelialization and remodeling capacity determine clinical success. Hospitals remain the primary end-user channel, though ambulatory surgical centers are gaining capacity for peripheral vascular interventions that shift lower-acuity grafting away from inpatient settings.
FDA premarket notification and EU MDR technical documentation requirements enforce rigorous biocompatibility and long-term patency evidence, elevating barriers for novel material entrants while accelerating consolidation among established manufacturers with regulatory infrastructure. Japan's PMDA and China's NMPA impose additional clinical trial localization mandates that fragment approval timelines and favor regional partnership strategies. Stakeholders must weigh the capital intensity of biodegradable graft R&D against the defensive moat created by durable synthetic graft cash flows as biological regeneration technologies mature toward commercial viability.
Market Dynamics
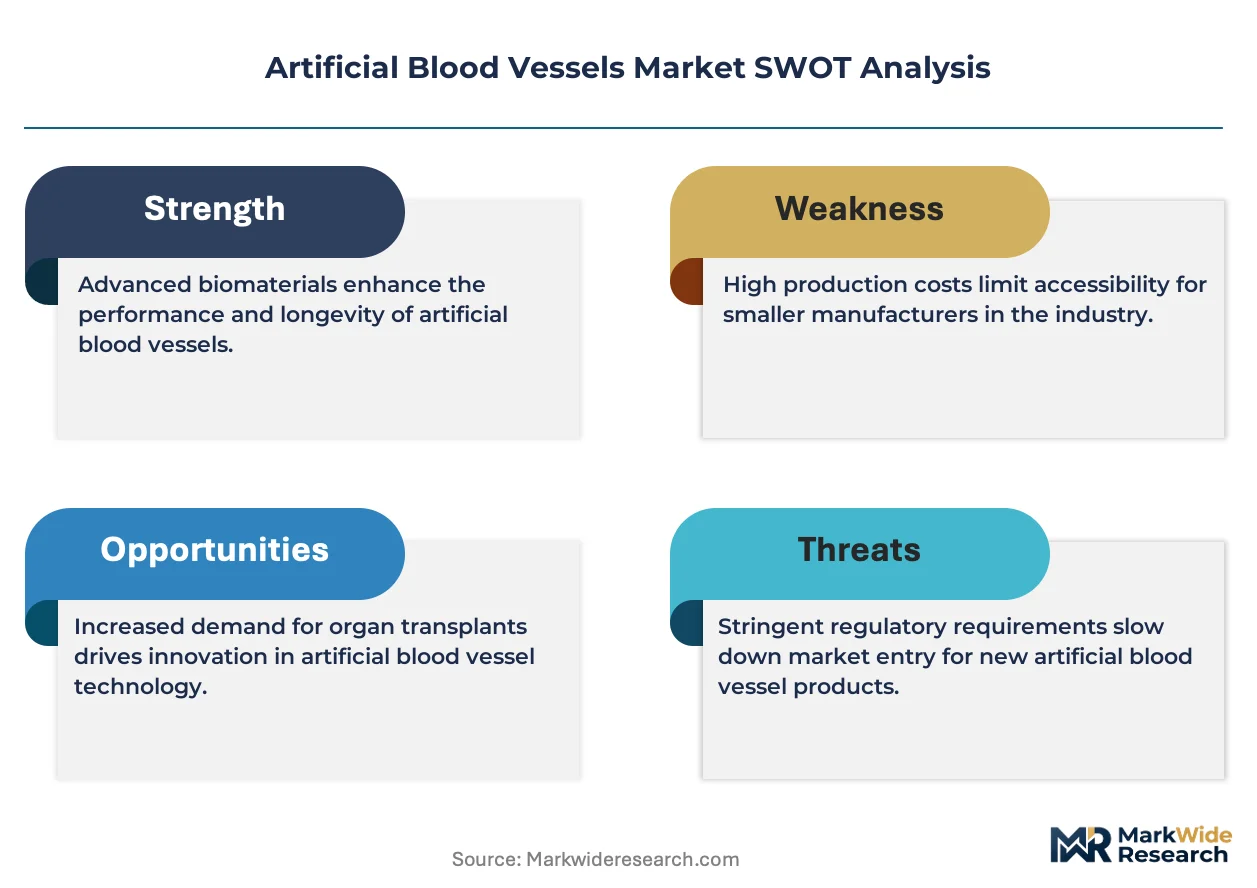
The artificial blood vessels sector is being restructured by tightening evidence requirements under FDA premarket approval and EU MDR frameworks, which are consolidating competitive advantage among manufacturers with established regulatory infrastructure while elevating barriers for novel material entrants.
Growth Catalysts
- EU MDR Conformity Pathways:The Medical Device Regulation's heightened clinical evidence standards are filtering out marginal competitors and concentrating procurement relationships with certified suppliers in German hospital systems.
- Peripheral Vascular Interventions:Ambulatory surgical centers are expanding grafting capacity for lower-acuity procedures, creating new volume channels beyond traditional inpatient cardiovascular units.
- ePTFE Manufacturing Scale:Proprietary expanded polytetrafluoroethylene production processes deliver tensile reliability exceeding 2 MPa, satisfying immediate mechanical demands in open surgical settings where biological integration timelines are unacceptable.
Market Restraints
- Biodegradable R&D Capital Intensity:Regenerative graft development requires sustained investment in collagen matrix engineering without near-term revenue offset, constraining mid-tier manufacturer participation.
- Approval Timeline Fragmentation:Japan's PMDA and China's NMPA impose localized clinical trial mandates that extend commercialization timelines and favor partnership-dependent market entry strategies.
- Synthetic Graft Cash Flow Defense:Durable polymer graft revenue streams create internal resource competition that slows biological regeneration technology prioritization among established producers.
Strategic Opportunities
- Aftermarket Surveillance Services:Revision procedure revenue and graft monitoring contracts are rewriting profitability models beyond initial implant sales in academic medical center relationships.
- Endovascular Training Infrastructure:High-touch clinical education programs create switching costs and deepen account penetration within hospital procurement workflows.
- Composite Biomaterial Convergence:Hybrid constructs combining synthetic scaffolds with biological coatings are capturing regenerative medicine applications where endothelialization capacity determines clinical success.
Industry Challenges
- Patency Evidence Generation:Long-term biocompatibility studies required for FDA premarket notification consume 18-36 month development cycles, compressing competitive response windows.
- Porosity Calibration Complexity:Manufacturing precision demands for hemorrhage prevention concurrent with tissue ingrowth enablement strain quality control systems and yield rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Blood Vessels Market |
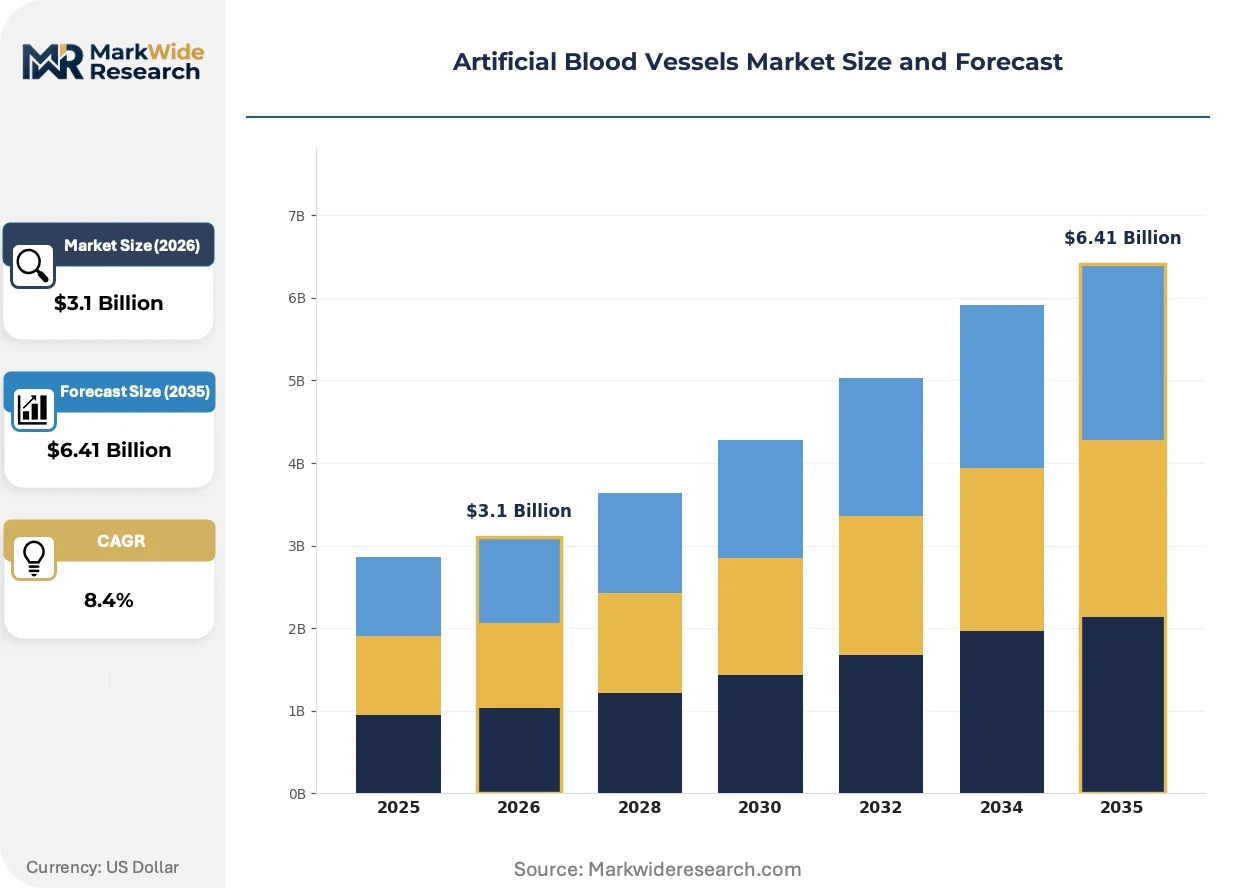
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological, Synthetic, Biodegradable, Composite End User: Hospitals, Ambulatory Surgical Centers, Research Institutions, Clinics Application: Cardiovascular Surgery, Vascular Grafting, Tissue Engineering, Regenerative Medicine Material: Polymer, Collagen, Elastin, Others |
| Companies Covered | Cook Medical, LeMaitre Vascular, B. Braun Melsungen, Becton Dickinson, W. L. Gore & Associates, Terumo Corporation, Humacyte, Jotec GmbH, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Blood Vessels Market Strategic Shifts & Innovations
Biological regeneration technologies are maturing toward commercial viability, creating competitive pressure on durable synthetic graft incumbents while regulatory frameworks accelerate consolidation around manufacturers with integrated catheter-to-graft portfolios.
Biodegradable collagen matrix grafts with controlled resorption profiles are advancing through clinical validation for vascular remodeling applications. Academic medical centers in Germany are piloting these constructs in procedures where endothelialization timelines align with patient recovery pathways. This biological alternative is rendering obsolete the assumption that permanent synthetic implants represent the default standard for all vascular reconstruction cases.
EU MDR technical documentation requirements now mandate comprehensive biocompatibility evidence and post-market surveillance systems for all synthetic polymer implants. Manufacturers without established quality management infrastructure face exclusion from European procurement channels. German hospital systems are prioritizing suppliers with demonstrated conformity assessment completion, compressing vendor shortlists to pre-certified incumbents.
Integrated catheter-to-graft procurement contracts are consolidating vendor relationships within cardiovascular surgery units. Hospital systems are streamlining sourcing workflows by awarding bundled supply agreements to manufacturers with comprehensive endovascular portfolios. This concentration pattern is most visible in German reimbursement-dense regions where procurement efficiency incentives align with premium graft adoption economics.
Artificial Blood Vessels Market Segmentation
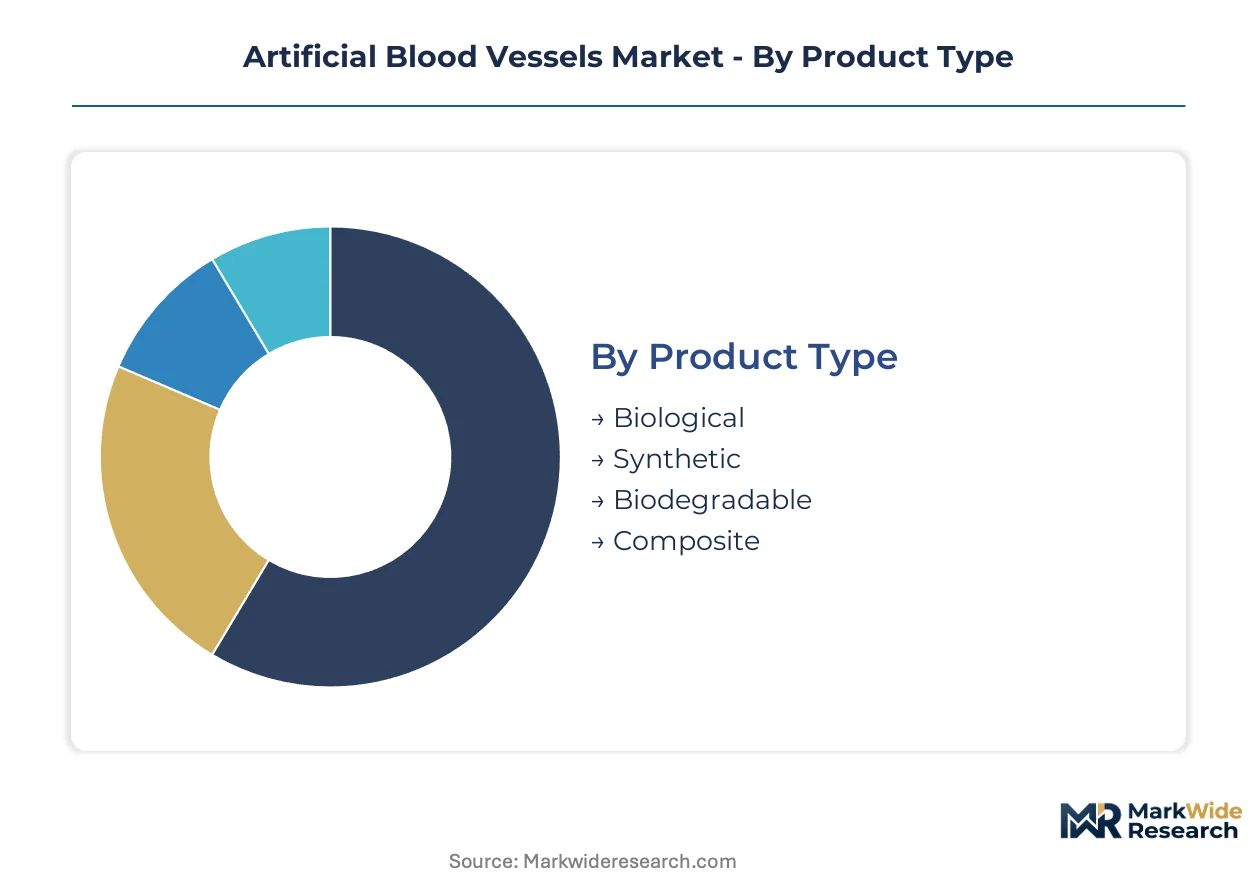
Artificial blood vessel segmentation reveals competing technology platforms at different commercial maturity stages. Product type divisions separate established synthetic graft revenue streams from emerging biological regeneration approaches. End-user and application categories track the migration of procedures from inpatient cardiovascular units toward ambulatory settings and research-driven regenerative applications.
Product Type:
Mature synthetic platforms dominate current revenue, while biodegradable and composite constructs occupy earlier commercialization phases with distinct clinical validation timelines.
- Synthetic:Expanded polytetrafluoroethylene grafts deliver tensile strength exceeding 2 MPa for immediate mechanical reliability in open surgical procedures. German hospital systems concentrate procurement of these durable constructs where biological integration timelines are clinically unacceptable. Synthetic grafts handle the majority of throughput; biodegradable alternatives are the fastest mover on share.
- Biological:Collagen matrix and xenograft-derived constructs enable endothelialization and vascular remodeling in regenerative medicine applications. Academic medical centers in Germany pilot these grafts where patient recovery pathways align with biological integration timelines.
- Biodegradable:Controlled resorption profiles support temporary scaffolding with progressive tissue replacement. R&D capital intensity constrains mid-tier manufacturer participation despite promising clinical validation trajectories.
- Composite:Hybrid architectures combine synthetic scaffolds with biological coatings to capture mechanical reliability alongside regenerative capacity. EU MDR technical documentation requirements favor established manufacturers with integrated quality systems.
Synthetic grafts command installed base dominance; composite constructs are climbing the fastest toward commercial viability.
End User:
Procurement authority and procedure reimbursement density determine channel prioritization across inpatient, outpatient, and research settings.
- Hospitals:Cardiovascular surgery units in German hospital systems anchor premium graft procurement through bundled supply agreements and integrated catheter-to-graft portfolios.
- Ambulatory Surgical Centers:Peripheral vascular intervention capacity is expanding for lower-acuity grafting procedures that shift volume away from traditional inpatient settings.
- Research Institutions:Biodegradable collagen matrix validation and composite biomaterial convergence originate in academic medical center pilot programs with specialized endothelialization research infrastructure.
- Clinics:Follow-up surveillance and revision service delivery concentrate in specialized vascular clinics with direct manufacturer training relationships.
Hospitals retain procurement volume leadership; ambulatory surgical centers are gaining share fastest as procedure migration accelerates.
Application:
Clinical use cases span immediate mechanical replacement through long-term regenerative reconstruction with diverging evidence requirements.
- Cardiovascular Surgery:Open surgical procedures requiring immediate mechanical reliability favor synthetic ePTFE grafts with established patency documentation. FDA premarket approval pathways enforce rigorous long-term evidence standards for novel material entrants.
- Vascular Grafting:Peripheral and coronary bypass applications concentrate demand in German reimbursement-dense regions where procurement efficiency incentives align with premium graft adoption.
- Tissue Engineering:Scaffold-based vascular construct development occurs primarily in research institution settings with specialized bioreactor and cell culture infrastructure.
- Regenerative Medicine:Biological and composite graft segments capture expanding share where endothelialization capacity determines clinical success and remodeling timelines align with patient recovery pathways.
Cardiovascular surgery generates the heaviest procedure volume; regenerative medicine applications are expanding most quickly as biological technologies mature.
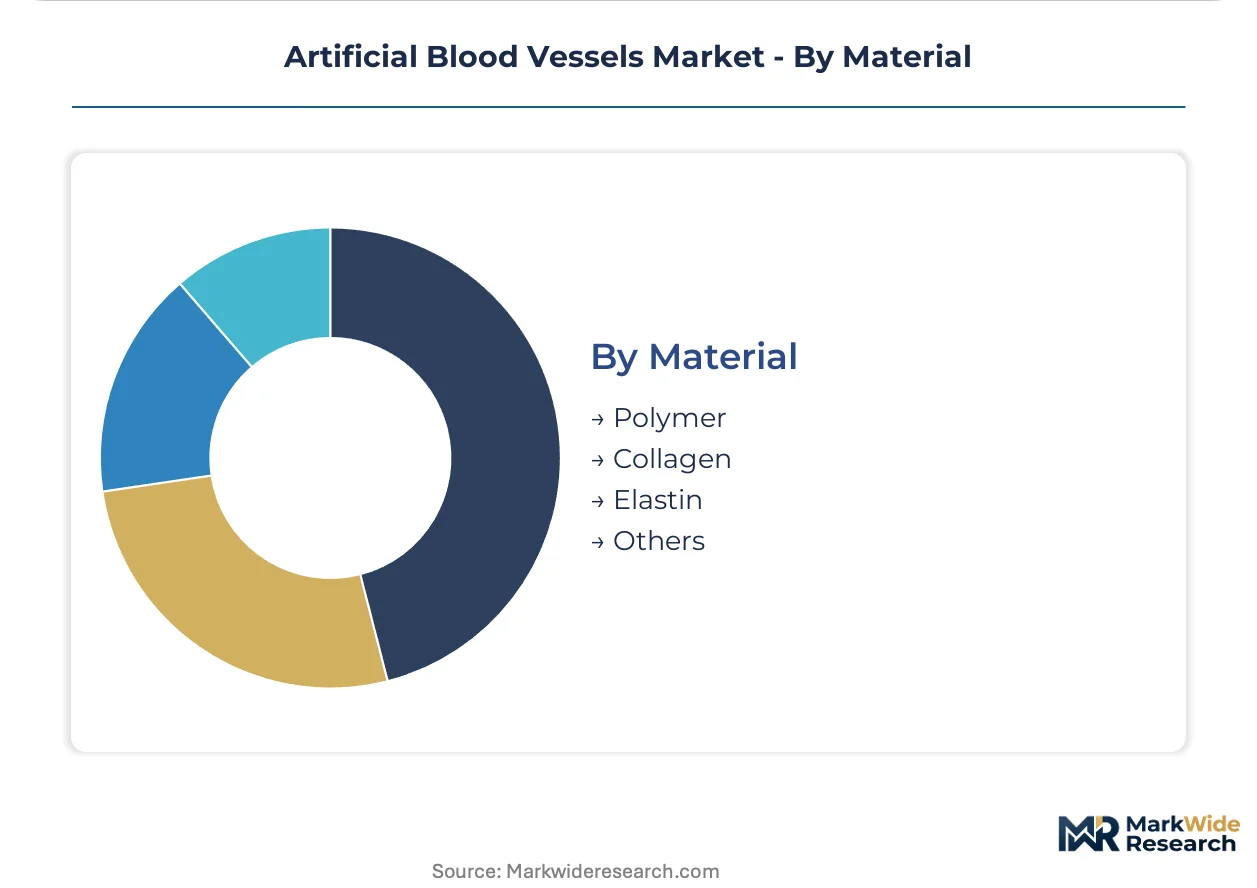
Material:
Material selection trades off manufacturing scalability against biological integration performance with distinct regulatory evidence burdens.
- Polymer:ePTFE and polyester formulations dominate synthetic graft production with proprietary manufacturing processes that competitors struggle to replicate. EU MDR conformity assessment completion filters procurement relationships toward certified suppliers.
- Collagen:Matrix engineering for biodegradable grafts requires sustained R&D investment without near-term revenue offset, constraining participation to well-capitalized developers.
- Elastin:Elastic fiber incorporation addresses compliance matching with native vasculature in specialized composite construct applications.
- Others:Silk fibroin, decellularized matrices, and novel biopolymers occupy early research phases with fragmented commercialization timelines.
Polymer materials underpin current manufacturing scale; collagen platforms are gaining share fastest as regenerative applications advance toward market entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in German hospital systems demonstrate the lowest price elasticity, absorbing premium graft costs through dense reimbursement frameworks, while procurement authorities in emerging markets exhibit acute sensitivity to unit economics despite expanding procedural volumes.
United States
Academic medical centers in Boston and the Research Triangle drive demand for biological and composite grafts with regenerative capacity. FDA premarket approval pathways enforce rigorous long-term patency evidence standards that filter procurement toward established manufacturers. The Cleveland Clinic and Mayo Clinic anchor high-volume synthetic graft utilization in cardiovascular surgery units.
Germany
Vascular surgery volumes in Baden-Württemberg and Bavaria concentrate procurement of ePTFE grafts with immediate mechanical reliability. EU MDR conformity assessment completion filters vendor shortlists to certified suppliers with demonstrated quality management infrastructure. Heidelberg and Tübingen university hospitals pilot biodegradable collagen matrix constructs in regenerative applications.
Japan
Aging demographics in the Kanto region sustain elevated peripheral vascular intervention volumes requiring durable synthetic grafts. PMDA clinical trial localization mandates extend commercialization timelines for novel material entrants and favor partnership-dependent market entry strategies. Tokyo and Osaka medical centers anchor premium graft adoption through national health insurance reimbursement density.
China
Provincial hospital systems in Shanghai and Guangdong expand cardiovascular surgery capacity with procurement concentrated in mid-tier synthetic graft segments. NMPA localized clinical evidence requirements fragment approval timelines and accelerate joint venture formation with foreign technology holders. The Yangtze River Delta cluster concentrates domestic manufacturing scale for polyester-based vascular constructs.
India
Private hospital chains in Maharashtra and Karnataka absorb growing coronary bypass volumes with price-calibrated synthetic graft procurement. CDSCO regulatory pathways for Class C and D medical devices impose quality system certification requirements that elevate barriers for unorganized suppliers. Mumbai and Bengaluru anchor tier-1 metropolitan demand while tier-2 cities expand ambulatory surgical center capacity for peripheral interventions.
Artificial Blood Vessels Market Key Industry Players
Capability concentration sits with integrated manufacturers possessing proprietary polymer processing expertise; scale advantage sits with diversified medtech conglomerates with established hospital procurement relationships. The market structure consolidates around three tiers: synthetic graft incumbents with decades of patency documentation, regenerative technology developers with biological matrix capabilities, and regional fabricators serving price-sensitive procurement channels. Dominant competitive moves include strategic partnerships to navigate fragmented regulatory timelines and portfolio diversification into catheter-delivered graft systems.
Among integrated synthetic graft specialists, Cook Medical, W. L. Gore & Associates, and Medtronic occupy positions defined by proprietary manufacturing infrastructure and endovascular portfolio breadth. Cook Medical exemplifies the high-touch clinical education archetype through embedded training relationships with academic medical centers. W. L. Gore & Associates anchors the proprietary materials tier with expanded polytetrafluoroethylene production capabilities that competitors struggle to replicate. Medtronic represents the diversified conglomerate archetype with integrated catheter-to-graft procurement contracts that streamline hospital sourcing workflows.
| Leading Market Players |
|---|
| Cook Medical |
| LeMaitre Vascular |
| B. Braun Melsungen |
| Becton Dickinson |
| W. L. Gore & Associates |
| Terumo Corporation |
| Humacyte |
| Jotec GmbH |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese polyester resin production for vascular graft substrates is compressing raw material input costs while simultaneously eroding pricing power for mid-tier synthetic graft manufacturers in peripheral markets. This utilization imbalance rewards incumbent suppliers with backward integration into ePTFE polymerization, enabling margin defense through captive supply chains that insulate premium tier positioning from commodity volatility.
Pricing Analysis
Aftermarket surveillance and revision service contracts now generate lifetime value multiples exceeding initial implant sales in academic medical center relationships. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU MDR certification completion and proprietary manufacturing scale, with Heidelberg and Tübingen university hospitals absorbing premium graft costs through dense reimbursement frameworks. Cost compression in mid-tier synthetic segments is intensifying because provincial hospital systems in Shanghai and Guangdong prioritize unit economics over performance differentiation. Ambulatory surgical centers exhibit acute price sensitivity compared to German cardiovascular surgery units with bundled procurement authority.
Supply Chain Analysis
Upstream PTFE resin feedstock draws from concentrated fluoropolymer production in the United States, Japan, and Germany, with specialty grade supply anchored by Chemours and Daikin proprietary formulations. Collagen matrix inputs for biological grafts rest on bovine and porcine tissue sourcing from Australia and New Zealand, while elastin fiber incorporation hinges on recombinant protein production in South Korea. Single-source vulnerability in medical-grade PTFE supply creates exposure to export control restrictions under dual-use technology classifications. Distribution runs through hospital GPO contracts in the United States, direct manufacturer relationships in Germany, and joint venture channels in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against biodegradable collagen matrix grafts that threaten to displace permanent synthetic implants in regenerative medicine applications. Incumbents must navigate the shift from mechanical reliability toward biological integration as the default clinical standard.
For Market Incumbents: Entrench proprietary ePTFE manufacturing scale as a defensive moat while accelerating composite biomaterial R&D to capture regenerative application share. Cook Medical's embedded training infrastructure exemplifies channel control that deepens switching costs within academic medical centers. Prioritize CE marking pathway completion under EU MDR before competitor quality system gaps harden procurement exclusion.
For New Entrants and Emerging Players: Peripheral vascular intervention capacity in Indian tier-2 cities represents the most penetrable entry point for price-calibrated synthetic graft penetration. Biodegradable collagen matrix validation partnerships with Heidelberg and Tübingen university hospitals offer accelerated clinical evidence generation. Target direct manufacturer-to-clinic distribution models that bypass consolidated GPO structures in saturated markets.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory infrastructure concentration under FDA and EU MDR frameworks will filter marginal competitors toward distressed asset availability. Acquisition target archetype: mid-tier manufacturers with established quality systems but underutilized biological R&D pipelines. Watch biodegradable graft patency data readouts from German academic medical center pilots as the signal for technology inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Rigorous long-term patency evidence requirements elevate barriers for novel material entrants without established regulatory infrastructure. |
| EU MDR Conformity Assessment | Technical documentation mandates filter procurement relationships toward certified suppliers with demonstrated quality management systems. |
| Hospital System Partnership | Bundled catheter-to-graft procurement contracts streamline sourcing workflows and compress vendor shortlists in German reimbursement-dense regions. |
| Endovascular Training Infrastructure | Embedded clinical education programs create switching costs and deepen account penetration within academic medical center relationships. |
| Reimbursement Strategy | Dense national health insurance frameworks in Germany and Japan anchor premium graft adoption economics against price-sensitive emerging markets. |
Research Approach
Cross-validation between primary interviews with vascular surgeons, hospital procurement managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and CMS Medicare reimbursement data. Bottom-up graft volume modeling by procedure type and hospital system triangulates against top-down market sizing through manufacturer revenue aggregation.
Calibration against historical synthetic graft adoption curves in cardiovascular surgery and peripheral vascular intervention informs elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user channel, application setting, and regional regulatory cluster. CAGRs derive from procedure volume forecasting combined with average selling price trajectory analysis, with specific inputs from PMDA and NMPA approval timeline fragmentation effects on commercialization pacing.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, reimbursement rate adjustments, or fluoropolymer feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway duration and clinical evidence generation timelines. Cross-checking against hospital procurement database benchmarks and manufacturer revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Neuroendovascular Coil Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Normal Balloon Catheter Market