
 Zoonotic Disease Treatment Market | 2026-2036
Zoonotic Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Zoonotic Disease Treatment Market Analytics
Veterinary clinics are collapsing into integrated health networks as the dominant buyer archetype for zoonotic therapeutics. Pfizer Inc. leverages its human vaccine infrastructure to cross-develop veterinary immunizations, while Zoetis Inc. anchors its portfolio in species-specific biologics for livestock and companion animals. Novartis International AG competes through specialized antiparasitic formulations that bridge companion animal and public health applications.
Zoonotic disease treatment encompasses pharmaceutical and biological interventions targeting pathogens transmitted between animals and humans, typically requiring broad-spectrum efficacy profiles, cold-chain stability, and dual-species safety validation through GLP toxicology studies. The primary purpose is to interrupt transmission cycles while preserving animal agricultural productivity and protecting human populations from spillover events. Vaccines command the largest revenue pool among product types due to preventive health mandates in livestock operations, while monoclonal antibodies represent the fastest-growing category as platform technologies shorten development cycles for emerging threats. Hospitals dominate end-user demand through emergency stockpiling protocols, though research institutions capture disproportionate margin pools through government-funded pandemic preparedness contracts.
FDA's One Health initiative and EMA's cross-species guidance frameworks are tightening manufacturing standards for dual-use therapeutics, compelling developers to maintain separate quality systems for human and veterinary production lines. WHO's R&D Blueprint for epidemic threats further shapes demand by prioritizing zoonotic pathogens with pandemic potential, directing public procurement toward pre-positioned countermeasures. Stakeholders must decide whether to build parallel regulatory capabilities or partner with specialized contract manufacturers as jurisdictional requirements diverge.
Market Dynamics
Hospital procurement of zoonotic therapeutics is intensifying as One Health frameworks reshape institutional buying patterns and emergency stockpiling protocols. FDA and EMA pathways for cross-species drug approval are streamlining development timelines while tightening manufacturing standards for dual-use production lines.
Growth Catalysts
- WHO's R&D Blueprint:This framework prioritizes zoonotic pathogens with pandemic potential, directing public procurement toward pre-positioned countermeasures and accelerating vaccine platform investments.
- Integrated health networks:Veterinary clinics are collapsing into unified systems, creating concentrated demand for broad-spectrum therapeutics that serve both companion animal and livestock operations.
- Cold-chain biologics infrastructure:Platform technologies for monoclonal antibodies are shortening development cycles, enabling rapid response to emerging spillover threats.
Market Restraints
- Dual-species safety validation costs:GLP toxicology studies must demonstrate efficacy across human and veterinary applications, doubling preclinical expenditure requirements.
- Regulatory friction from divergent quality systems:FDA and EMA compel developers to maintain separate manufacturing lines for human and veterinary therapeutics, constraining capacity utilization.
- Substitution threat from preventive vaccines:Livestock operations increasingly prioritize immunization over treatment, compressing revenue pools for post-infection therapeutics.
Strategic Opportunities
- Underpenetrated companion animal segment:Pet owners in Germany and Japan demonstrate willingness to pay premium prices for zoonotic prophylaxis, creating margin expansion potential.
- Technology convergence of mRNA platforms:Cross-species vaccine development is enabling developers to repurpose human immunization infrastructure for veterinary applications.
- Government-funded pandemic preparedness contracts:Research institutions capture disproportionate margin pools through advance purchase agreements for stockpiled countermeasures.
Industry Challenges
- Specialized talent scarcity in cross-species pharmacology:The field requires expertise bridging human and veterinary toxicology, creating recruitment bottlenecks for development teams.
- Certification timeline compression:Emergency use authorization pathways demand accelerated safety documentation, straining regulatory affairs capacity.
- Supply chain reconfiguration friction:Cold-chain stability requirements for biologics necessitate redundant distribution infrastructure across divergent jurisdictional standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zoonotic Disease Treatment Market |
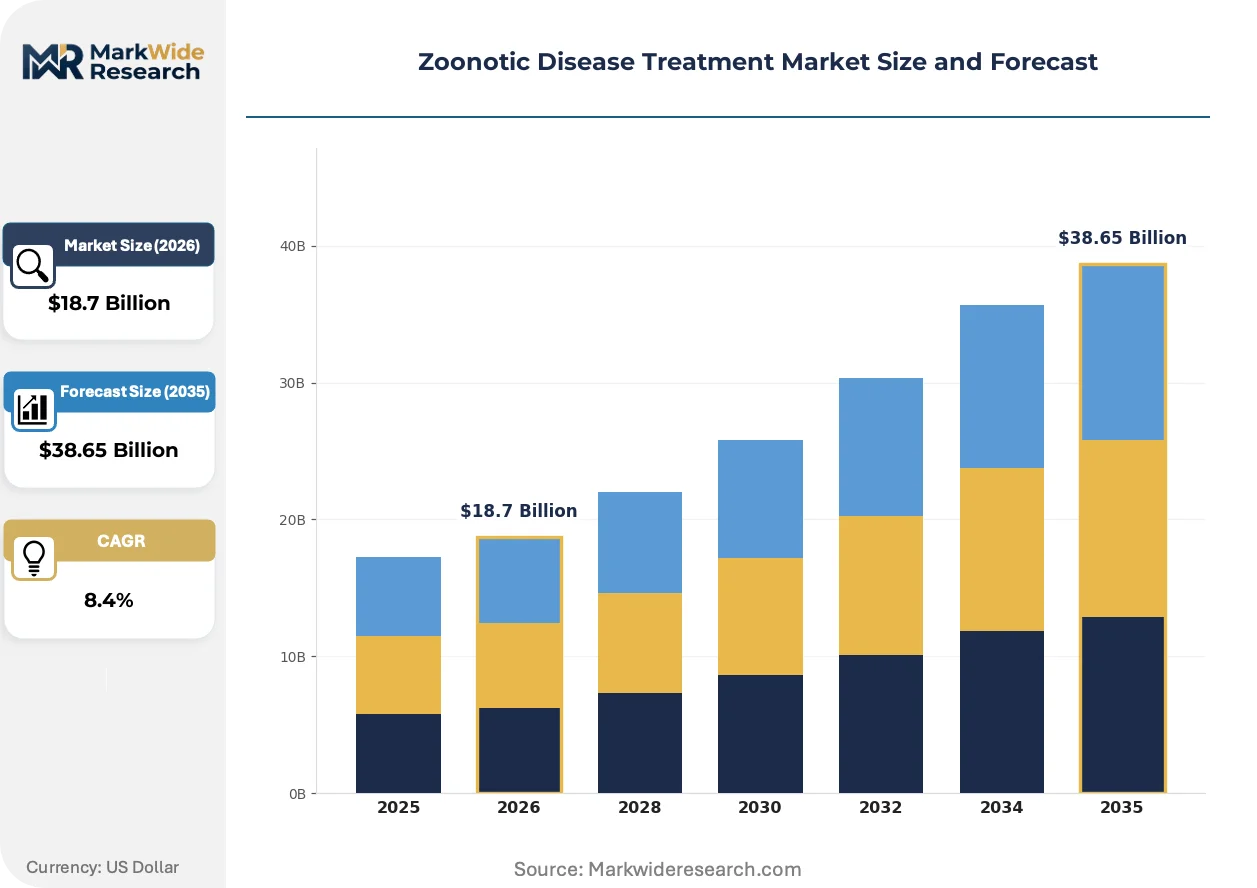
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antivirals, Antibiotics, Monoclonal Antibodies Application: Veterinary Medicine, Human Treatment, Public Health, Research End User: Hospitals, Clinics, Research Institutions, Laboratories Delivery Mode: Oral, Injectable, Topical, Inhalation |
| Companies Covered | Bayer AG, AstraZeneca plc, Pfizer Inc., GlaxoSmithKline plc, Novartis International AG, Johnson & Johnson Services Inc., Sanofi S.A., Zoetis Inc., Merck And Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zoonotic Disease Treatment Market Evolving Landscape
Platform technologies are compressing development timelines for emerging zoonotic threats while regulatory convergence creates new compliance architectures. The market is witnessing fundamental shifts in how therapeutics traverse species boundaries and procurement channels.
mRNA vaccine platforms are fragmenting traditional development paradigms by enabling rapid sequence adaptation against novel pathogens. Veterinary operations in the United States are adopting these systems for livestock immunization at accelerated pace compared to conventional attenuated vaccines. This technology is fragmenting the competitive landscape by lowering barriers to entry for specialized biologics developers.
EMA's cross-species guidance frameworks are tightening manufacturing standards for dual-use therapeutics across European markets. Developers must now demonstrate equivalent quality systems for human and veterinary production lines, increasing compliance overhead. Small and mid-sized manufacturers are responding by partnering with specialized contract manufacturing organizations.
Hospital emergency stockpiling protocols are consolidating procurement authority within integrated health networks. Traditional distributor relationships are being displaced by direct manufacturer contracts with centralized purchasing consortia. This concentration is most visible in Japan, where metropolitan hospital systems coordinate pandemic preparedness purchasing through government-mediated frameworks.
Zoonotic Disease Treatment Market Segmentation
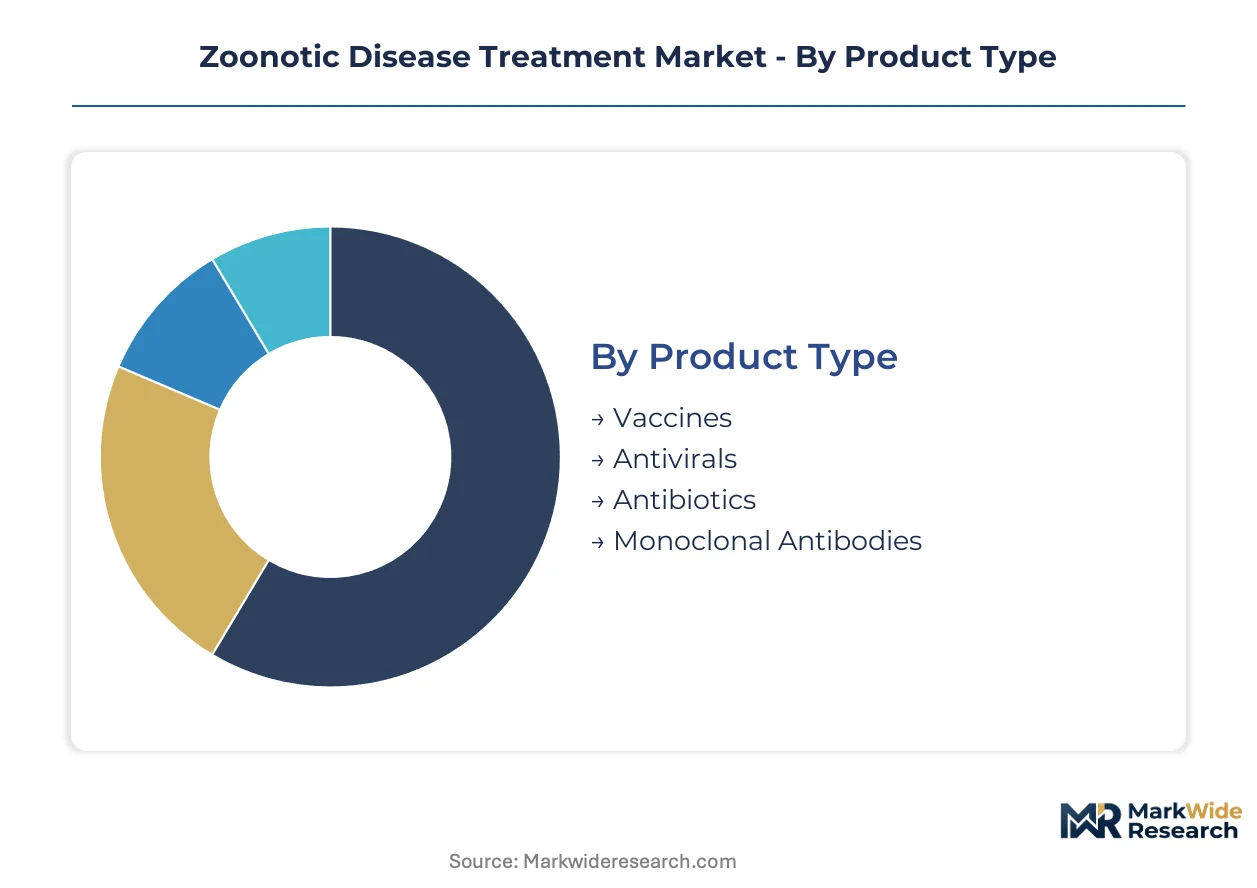
Zoonotic disease treatment segments fracture along species boundaries and regulatory jurisdictions. Substitution pressures vary sharply across product categories, with preventive modalities displacing reactive therapeutics in livestock operations while human emergency stockpiling sustains demand for post-exposure interventions.
Product Type:
Vaccines face intensifying substitution pressure from platform biologics as mRNA technologies enable rapid pivoting between species-specific formulations.
- Vaccines:Attenuated and recombinant formulations dominate livestock operations through preventive health mandates. Demand concentrates in United States cattle feedlots and Japanese poultry operations where regulatory compliance drives bulk procurement.
- Monoclonal Antibodies:Engineered immunoglobulins targeting conserved viral epitopes enable post-exposure prophylaxis across species. Research institutions in Germany capture disproportionate funding for pandemic preparedness platforms.
- Antivirals:Small-molecule inhibitors with broad-spectrum activity against RNA viruses.
- Antibiotics:Bacterial zoonosis treatments facing regulatory restriction in food-animal applications.
Vaccines anchors the volume base while monoclonal antibodies gains share at the steepest rate.
Application:
Cost tier stratification separates mass-market veterinary prophylaxis from premium-priced human biodefense contracts.
- Veterinary Medicine:Species-specific formulations for companion animals and livestock require cold-chain stability across distributed rural networks. United States integrated health networks consolidate procurement authority for cattle and swine operations.
- Human Treatment:Post-exposure therapeutics for spillover events command price premiums through emergency use authorization pathways. Japanese metropolitan hospital systems coordinate stockpiling through government-mediated frameworks.
- Public Health:Population-level intervention programs for outbreak containment.
- Research:Preclinical and clinical investigation materials for cross-species safety validation.
Veterinary medicine captures the widest volume footprint while human treatment delivers the highest margin per dose.
End User:
Customer type fragmentation concentrates purchasing power within integrated delivery networks while fragmenting research procurement across institutional silos.
- Hospitals:Emergency departments and infectious disease units stockpile broad-spectrum countermeasures against spillover events. German university hospitals coordinate regional pandemic preparedness purchasing through consortium structures.
- Research Institutions:Government-funded laboratories advance development pipelines for WHO-prioritized pathogens. United States NIH contracts provide advance purchase commitments for pre-positioned stockpiles.
- Clinics:Outpatient facilities for companion animal and occupational exposure management.
- Laboratories:Diagnostic and reference facilities supporting surveillance networks.
Hospitals dominate absolute procurement value while research institutions expand most quickly through preparedness funding.
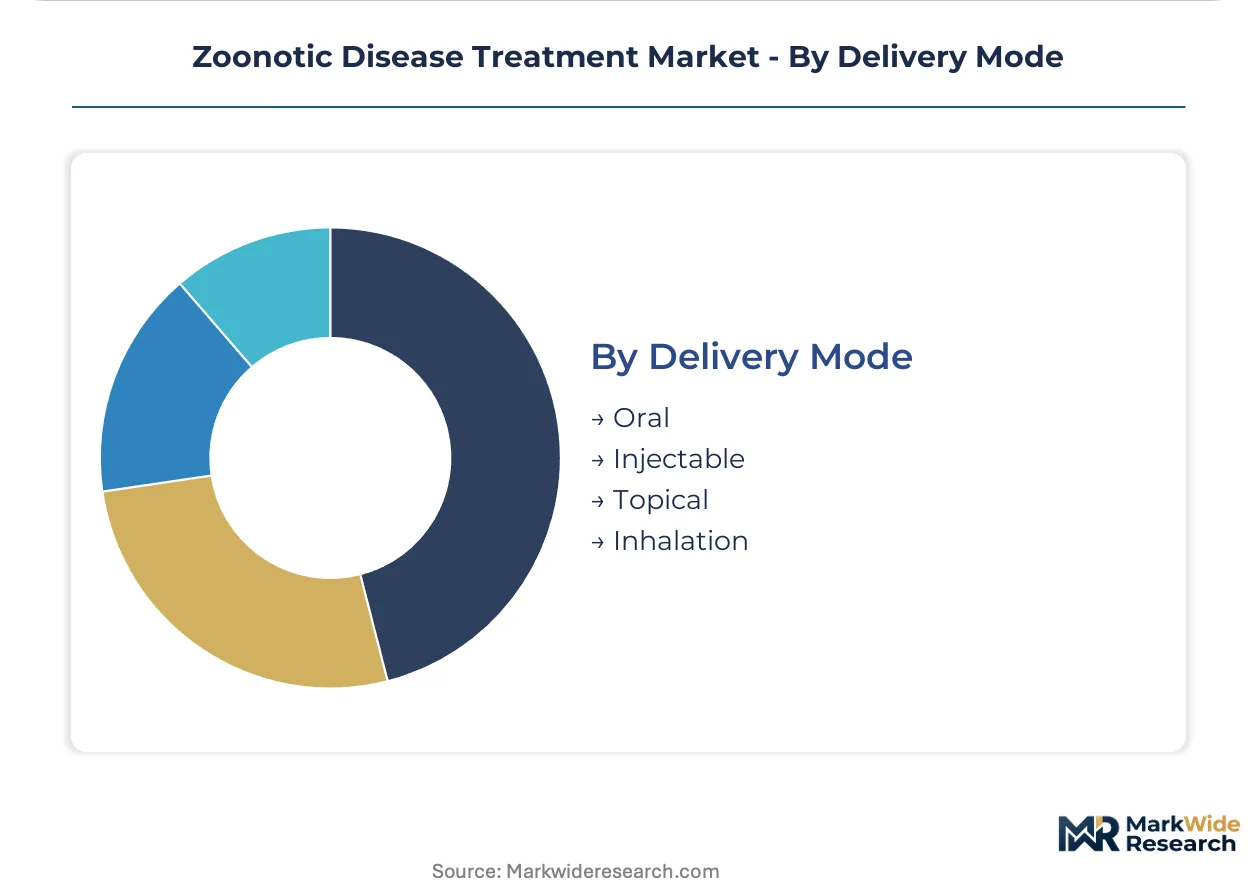
Delivery Mode:
Supply concentration in sterile injectable manufacturing creates capacity bottlenecks as oral formulations face bioavailability constraints across species.
- Injectable:Parenteral formulations for biologics requiring precise dosing and rapid systemic distribution. Cold-chain infrastructure in Japan and Germany enables mRNA vaccine deployment across veterinary and human applications.
- Oral:Small-molecule therapeutics for mass administration in livestock operations face palatability and metabolism variability across ruminant and monogastric species.
- Topical:Localized delivery for dermatological zoonoses and wound-associated infections.
- Inhalation:Aerosolized delivery for respiratory pathogen prophylaxis in confined animal feeding operations.
Injectable commands the manufacturing capacity base while oral climbs the fastest as feed-additive formulations penetrate emerging livestock markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cold-chain logistics networks spanning Frankfurt Airport and the Rhine-Main corridor underpin Germany's distribution dominance for temperature-sensitive zoonotic biologics. These infrastructure assets connect European veterinary health networks to global pharmaceutical supply chains.
United States
Integrated health networks in Texas and Iowa consolidate procurement for cattle feedlot operations while metropolitan hospital systems in Boston and Atlanta maintain emergency stockpiles against spillover events. FDA's One Health initiative streamlines cross-species approval pathways for developers. The Research Triangle Park cluster in North Carolina anchors pandemic preparedness contracting through NIH-funded advance purchase agreements.
Germany
EMA's cross-species guidance frameworks tighten manufacturing standards for dual-use therapeutics across Bavarian and North Rhine-Westphalian production facilities. University hospitals in Berlin and Munich coordinate regional preparedness purchasing through consortium structures. The Frankfurt-Rhine-Main logistics corridor enables cold-chain distribution of mRNA vaccines across veterinary and human applications.
Japan
PMDA oversight shapes manufacturing compliance for biologics targeting metropolitan hospital systems in Tokyo and Osaka. Government-mediated frameworks coordinate stockpiling across prefectural health networks. The Kanto region concentrates research institution demand for WHO-prioritized pathogen countermeasures through METI-supported technology platforms.
United Kingdom
London and Southeast England cluster research institutions capturing government-funded pandemic preparedness contracts for emerging zoonotic threats. The Medicines and Healthcare products Regulatory Agency maintains distinct quality system requirements for human and veterinary production lines. Cambridge and Oxford anchor cross-species pharmacology expertise development for platform biologics.
India
CDSCO regulatory pathways attract contract manufacturing investment for antiparasitic formulations serving companion animal markets in Maharashtra and Gujarat. The country's national pharmaceutical regulator advances harmonization with WHO prequalification standards. Hyderabad and Bangalore clusters specialize in GLP toxicology services for dual-species safety validation.
Zoonotic Disease Treatment Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing parallel human and veterinary regulatory capabilities. Tiered competition separates platform technology developers from species-specific formulation specialists. Three archetypes dominate: human vaccine infrastructure repurposers, veterinary biologics pure-plays, and antiparasitic formulation specialists. Strategic moves center on cross-species technology licensing and integrated health network procurement consolidation.
Among human pharmaceutical conglomerates, Pfizer Inc. and AstraZeneca plc exemplify infrastructure repurposing archetypes, leveraging existing vaccine platforms for veterinary adaptation. Zoetis Inc. occupies the veterinary pure-play position, while Bayer AG represents the agrochemical-to-pharmaceutical diversification model. These three anchors illustrate how regulatory capability breadth determines competitive positioning in dual-use therapeutic development.
| Leading Market Players |
|---|
| Bayer AG |
| AstraZeneca plc |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Novartis International AG |
| Johnson & Johnson Services Inc. |
| Sanofi S.A. |
| Zoetis Inc. |
| Merck And Co. Inc. |
| Others |
Value Network & Pricing Analysis
Cold-chain biologics manufacturing exhibits steep scale economies that concentrate production among FDA and EMA dual-certified facilities, compressing price floors for monoclonal antibodies while elevating premiums for small-batch veterinary formulations. This scale concentration simultaneously tightens supply availability for emergency stockpiles and fragments pricing power across species-specific product tiers.
Pricing Analysis
Volume-discount tiering structures separate emergency procurement contracts from routine veterinary replenishment orders, with Three-tier pricing structure across premium, standard, and economy levels anchored by FDA certification grade and cold-chain reliability guarantees. Price differentiation intensifies between GLP-validated biologics and conventional small-molecule therapeutics as hospital systems consolidate purchasing authority. Margins are tightening due to EMA's cross-species manufacturing standards compelling redundant quality systems. Research institutions demonstrate lowest price sensitivity through government-funded advance purchase agreements, while livestock operations in distributed rural networks exhibit highest sensitivity to per-dose procurement costs.
Supply Chain Analysis
Strategic stockpile preferences dominate hospital procurement patterns, contrasting with just-in-time replenishment cycles in companion animal clinics that strain cold-chain capacity during demand surges. Manufacturing concentration rests on Germany, the United States, and Japan for dual-use therapeutic production, with India emerging for GLP toxicology services. Raw material dependencies center on mRNA platform lipids, sterile injectable vials, and species-specific adjuvant formulations. Single-source vulnerability pervades mRNA lipid nanoparticle supply, with distribution running through Frankfurt-Rhine-Main and Tokyo-Osaka logistics corridors for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-species pharmacology expertise scarcity constrains development velocity, creating acquisition premiums for teams bridging human and veterinary toxicology capabilities. This talent bottleneck amplifies strategic value for contract research organizations possessing dual-species GLP certification.
For Market Incumbents: Consolidate regulatory affairs capacity across FDA and EMA parallel pathways to compress approval timelines for emerging zoonotic threats. Acquire specialized contract manufacturing organizations in Germany and Japan to secure dual-certified production capacity. Channel control through direct hospital system contracts displaces traditional distributor relationships as integrated health networks centralize procurement authority.
For New Entrants and Emerging Players: Anchor in companion animal prophylaxis segments across Germany and Japan where pet owner willingness-to-pay sustains premium pricing. Target mRNA platform licensing agreements with veterinary pure-plays lacking human vaccine infrastructure. White-space availability concentrates in rapid-response monoclonal antibody development for WHO-prioritized pathogens.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform technology developers with government pandemic preparedness contracts. Long-term viability over the coming decade favors contract manufacturers possessing simultaneous FDA and EMA dual-use certification. Acquisition targets should demonstrate cross-species pharmacology talent depth and cold-chain logistics integration. The signal to watch is emergency use authorization pathway utilization rates as an indicator of regulatory capacity scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA One Health initiative streamlines cross-species development timelines for dual-use therapeutics. |
| Manufacturing Scale-Up | Cold-chain biologics capacity expansion in Germany and Japan addresses hospital stockpiling demand concentration. |
| Pipeline Diversification | mRNA platform adaptation across veterinary species fragments traditional vaccine development paradigms. |
| Strategic Partnership | Contract manufacturing alliances enable small developers to meet EMA cross-species quality standards. |
| Geographic Expansion | Research Triangle Park and Kanto region clusters capture NIH and METI pandemic preparedness funding. |
Research Methodology
Desk research of FDA and EMA regulatory filings, WHO R&D Blueprint documentation, and hospital procurement databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from ClinicalTrials.gov, EMA submission summaries, and formulary databases. Bottom-up segmentation modeling triangulated against top-down epidemiological projections for zoonotic spillover frequency.
Variance decomposition across product type, application, end user, and delivery mode segments isolated growth contribution by category throughout the forecast period. CAGRs were derived from epidemiological trend extrapolation, regulatory pathway velocity assumptions, and procurement pattern analysis across integrated health networks. Forecast inputs incorporated WHO-prioritized pathogen lists, cold-chain infrastructure expansion trajectories, and cross-species manufacturing certification timelines.
Underlying assumptions cover sustained One Health policy commitment, with deviation risk concentrated in regulatory harmonization setbacks and pandemic preparedness funding volatility. Forecasts reflect these documented assumptions with acknowledged sensitivity to emergency use authorization pathway availability and GLP toxicology capacity constraints. Revision becomes warranted when cross-species manufacturing standard divergence crosses thresholds that fragment quality system compliance requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Global Companion Animal Health Market
Animal Health
Companion Animal Medicine Market
Animal Health
Swine Health Market
Animal Health
Canada Animal Health Care Market
Animal Health
US Military Animals Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Equine Healthcare Market
Animal Health
Swine Healthcare Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Laboratory Animal Models Market
Animal Health
Rat Model Market
Animal Health
Animal Healthcare Market
Animal Health
Global Poultry Healthcare Market
Animal Health
US Companion Animal Health Market