
 Hypertension Management Devices Market | 2026-2036
Hypertension Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hypertension Management Devices Market Outlook
Silicon photonics is repositioning sensor economics in wearable blood pressure monitors by replacing discrete optical components with integrated chip-scale solutions. Medtronic leverages its cardiac rhythm management infrastructure to anchor hypertension device distribution across integrated health networks. Omron Healthcare sustains brand dominance in home-use oscillometric systems through direct-to-consumer channel control and pharmacy partnerships. Abbott differentiates via sensor miniaturization for combined glucose-blood pressure wearable platforms.
Hypertension management devices comprise electronic and mechanical instruments designed to measure, record, and transmit arterial blood pressure data, typically employing oscillometric detection with cuff inflation pressures ranging from 0 to 300 mmHg and accuracy within ±3 mmHg per ISO 81060-2 validation protocols. These instruments serve clinical diagnosis, therapeutic monitoring, and longitudinal cardiovascular risk management across ambulatory and residential settings. Digital blood pressure monitors occupy the largest revenue pool due to established reimbursement codes and physician preference for validated automated readings in clinic workflows. Bluetooth-enabled technology segments are capturing accelerated demand as health systems mandate interoperable data streams for remote patient monitoring programs. Home healthcare end users represent the fastest-growing demand node as payers expand coverage for connected devices that reduce in-person visit frequency.
FDA 510(k) clearance requirements and ISO 81060-2 validation standards shape product development timelines and market access thresholds for manufacturers targeting the United States. EMA medical device regulation and the EU MDR conformity assessment framework impose additional clinical evidence burdens on oscillometric and wearable systems sold in Europe. Stakeholders must monitor evolving cybersecurity guidance from FDA and Health Canada as IoT-integrated monitors transmit protected health information across cloud architectures.
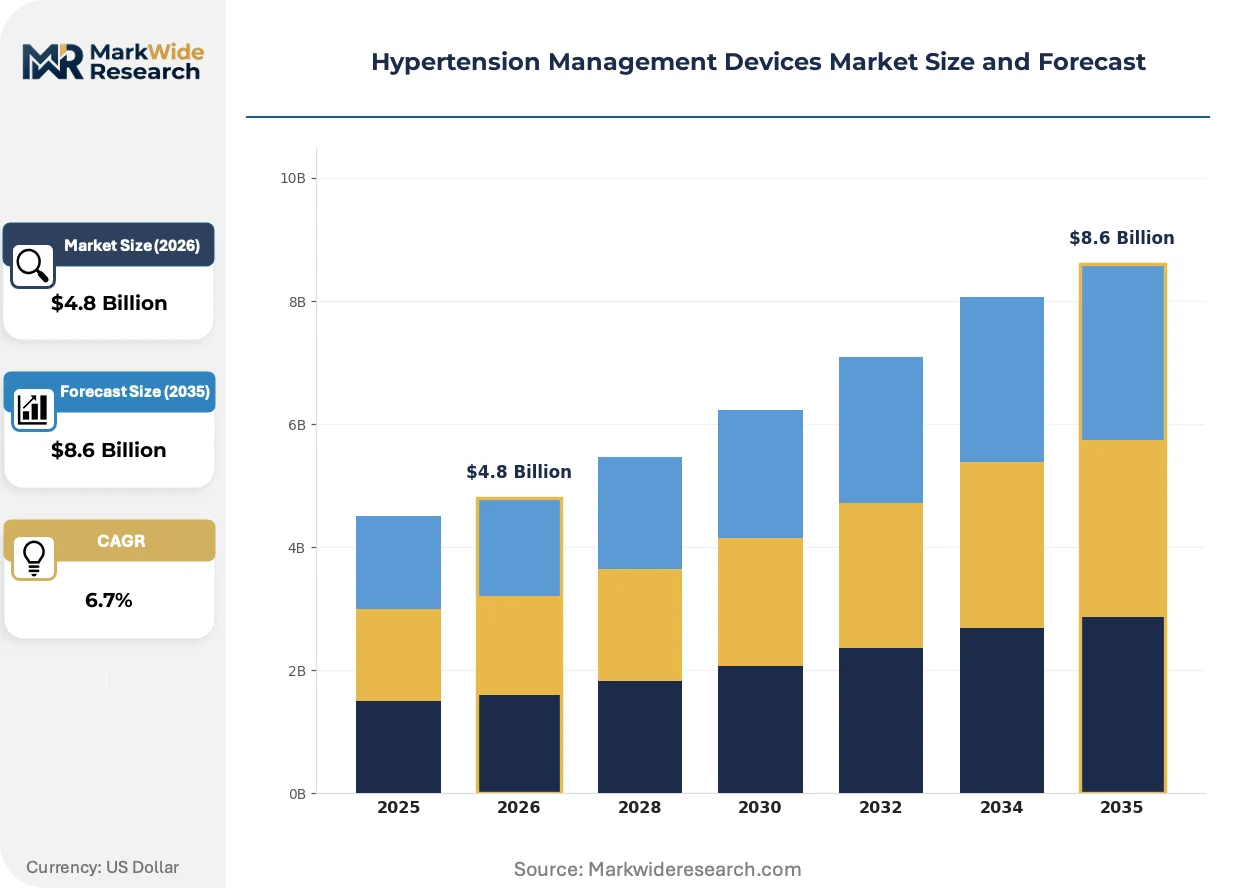
Market Dynamics
Silicon photonics integration is compressing sensor economics in wearable blood pressure monitors, enabling chip-scale optical solutions that displace discrete component assemblies and reshape manufacturing cost structures for connected monitoring systems.
Growth Catalysts
- Remote patient management reimbursement:Germany's statutory health insurance framework now covers connected blood pressure monitors for home-based cardiovascular monitoring, accelerating procurement by regional care networks.
- Bluetooth-enabled interoperability mandates:Health systems in the United States require validated data streams for remote patient monitoring programs, pulling demand toward ISO 81060-2 certified digital platforms.
- Integrated care network consolidation:Accountable care organizations are centralizing device purchasing decisions around single-vendor digital ecosystems that bundle monitoring hardware with analytics software.
Market Restraints
- EU MDR clinical evidence burdens:The European Medical Device Regulation imposes additional conformity assessment requirements on oscillometric systems, extending time-to-market for manufacturers targeting European markets.
- MEMS pressure sensor supply concentration:Foundry capacity for microelectromechanical pressure transducers concentrates among Taiwanese and Japanese suppliers, creating input bottlenecks during demand surges.
- Optical sensor accuracy limitations:Photoplethysmography-based wearables struggle to match cuff-based oscillometric precision in arrhythmic patients, restricting clinical validation for diagnostic applications.
Strategic Opportunities
- Japan's aging-in-place infrastructure:METI's Silver ICT standards initiative creates procurement pathways for connected hypertension monitors in municipal home care programs.
- Combined glucose-blood pressure wearables:Convergence of continuous glucose monitoring and arterial pressure sensing into single-platform devices opens metabolic-cardiovascular management applications.
- Direct-to-consumer pharmacy channels:Retail pharmacy networks are building private-label connected device portfolios, creating alternative distribution paths outside traditional medical supply chains.
Industry Challenges
- FDA 510(k) cybersecurity documentation:IoT-integrated monitors transmitting protected health information across cloud architectures face evolving premarket submission requirements for software bill of materials and vulnerability management protocols.
- ISO 81060-2 validation timeline compression:Third-party testing laboratory capacity constraints extend protocol verification schedules, delaying product launches for manufacturers pursuing simultaneous multi-market registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypertension Management Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Blood Pressure Monitors, Manual Blood Pressure Monitors, Wearable Monitors, Mobile Health Devices Technology: Oscillometric, Aneroid, Bluetooth-Enabled, IoT-Integrated End User: Hospitals, Home Healthcare, Ambulatory Surgical Centers, Clinics Application: Monitoring, Diagnosis, Treatment, Health Management |
| Companies Covered | Medtronic, Boston Scientific, Abbott, Omron Healthcare, Philips Healthcare, GE Healthcare, CVRX, Recor Medical, A&D Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypertension Management Devices Market Strategic Shifts
Photonic integration and algorithmic signal processing are converging to enable cuffless continuous monitoring, while regulatory frameworks accelerate toward software-as-medical-device classification for analytics layers.
Silicon photonics is overtaking discrete LED-photodiode assemblies in wearable blood pressure sensors by integrating optical emitters, waveguides, and detectors onto single CMOS substrates. Cardiac rhythm management divisions within integrated health networks are adopting these chip-scale solutions for ambulatory monitoring programs. This photonic consolidation is overtaking traditional optomechanical packaging costs, compressing bill-of-materials by eliminating lens assemblies and optical alignment labor.
EU MDR's software classification guidance is redefining regulatory boundaries for hypertension management devices that incorporate diagnostic algorithms. Manufacturers must now submit clinical evidence for blood pressure estimation models as distinct from hardware validation, creating dual-track conformity assessments. Wearable systems with embedded arrhythmia detection face the steepest compliance burdens, with notified bodies requiring prospective clinical studies for algorithm performance claims.
Integrated care networks are consolidating vendor relationships around platform ecosystems that bundle hardware, cloud analytics, and electronic health record integration. Traditional durable medical equipment distributors are losing purchasing influence as health systems negotiate enterprise contracts directly with device manufacturers. This concentration is most visible in United States Medicare Advantage plans, where risk-bearing provider groups mandate interoperable data formats as a procurement precondition.
Hypertension Management Devices Market Segmentation
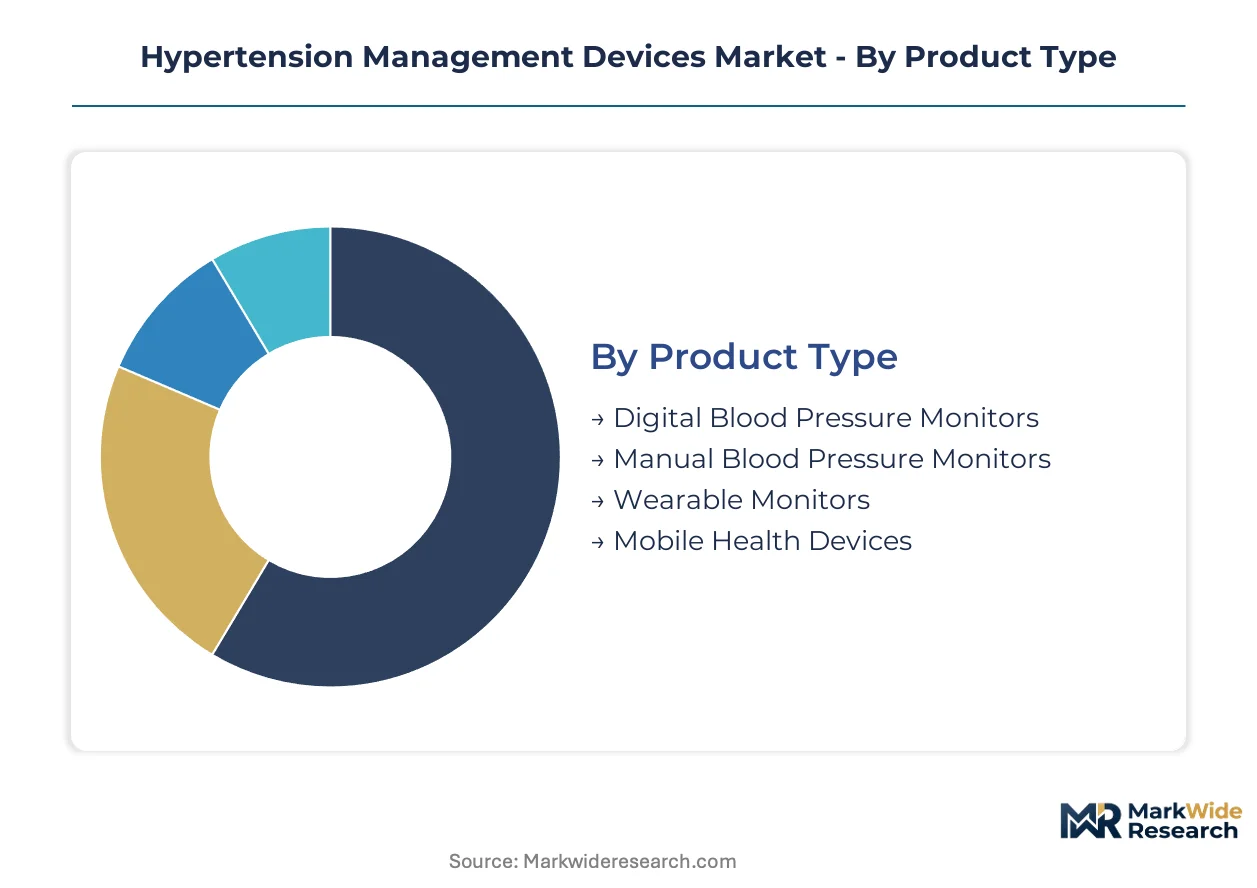
Device architecture and connectivity specifications determine reimbursement pathways and procurement authority in hypertension management. Product form factor, sensor technology, care setting, and clinical application each create distinct commercial boundaries that manufacturers must navigate simultaneously.
Product Type:
Standardized cuff-based systems dominate high-volume procurement, while customized wearable form factors command premium positioning through continuous monitoring capabilities.
- Digital Blood Pressure Monitors:Automated oscillometric systems with LCD displays and memory storage function as the clinical standard for validated readings. United States integrated care networks concentrate purchasing around ISO 81060-2 certified units that feed directly into electronic health record workflows.
- Wearable Monitors:Photoplethysmography and tonometry-based wrist or finger devices enable ambulatory pressure tracking without cuff inflation. Germany's statutory health insurance reimbursement for home cardiovascular monitoring accelerates procurement by regional care networks seeking to reduce clinic visit frequency.
- Manual Blood Pressure Monitors:Aneroid gauges with stethoscope-dependent auscultation persist in low-resource clinical settings and medical education.
- Mobile Health Devices:Smartphone-connected sensors and camera-based estimation applications serve consumer wellness segments outside formal reimbursement frameworks.
Leading the category by volume: Digital Blood Pressure Monitors. Expanding most quickly: Wearable Monitors.
Technology:
Cost tier stratification separates validated clinical-grade systems from consumer-accessible connectivity layers, with hybrid architectures capturing intermediate price positions.
- Oscillometric:Cuff-based pressure detection through arterial wall vibration analysis remains the accuracy benchmark for diagnostic applications. FDA 510(k) clearance requirements and ISO 81060-2 validation protocols shape development timelines for manufacturers targeting United States market access.
- Bluetooth-Enabled:Wireless data transmission to paired smartphones or hub devices satisfies health system interoperability mandates for remote patient monitoring programs. United States Medicare Advantage risk-bearing provider groups mandate such data formats as procurement preconditions.
- Aneroid:Mechanical pressure gauges without electronic components occupy lowest-cost tiers in emerging market clinics and training institutions.
- IoT-Integrated:Cloud-connected monitors with embedded analytics face evolving FDA cybersecurity documentation requirements for software bill of materials and vulnerability management protocols.
Climbing the fastest: Bluetooth-Enabled. Anchoring clinical validation: Oscillometric.
End User:
Customer type determines purchasing authority, with institutional procurement consolidating around enterprise contracts while individual consumers drive retail channel dynamics.
- Home Healthcare:Patients and informal caregivers operating outside clinical supervision represent the steepest demand trajectory as payers expand coverage for connected devices. Japan's METI Silver ICT standards initiative creates municipal procurement pathways for aging-in-place infrastructure.
- Hospitals:Acute care facilities prioritize validated automated systems for perioperative monitoring and emergency department triage workflows.
- Ambulatory Surgical Centers:Same-day procedure facilities require compact, rapid-cycling monitors for pre-operative assessment and post-discharge instructions.
- Clinics:Primary and specialty outpatient practices balance accuracy requirements against patient throughput efficiency in device selection.
Gaining share fastest: Home Healthcare. Commanding highest unit prices: Hospitals.
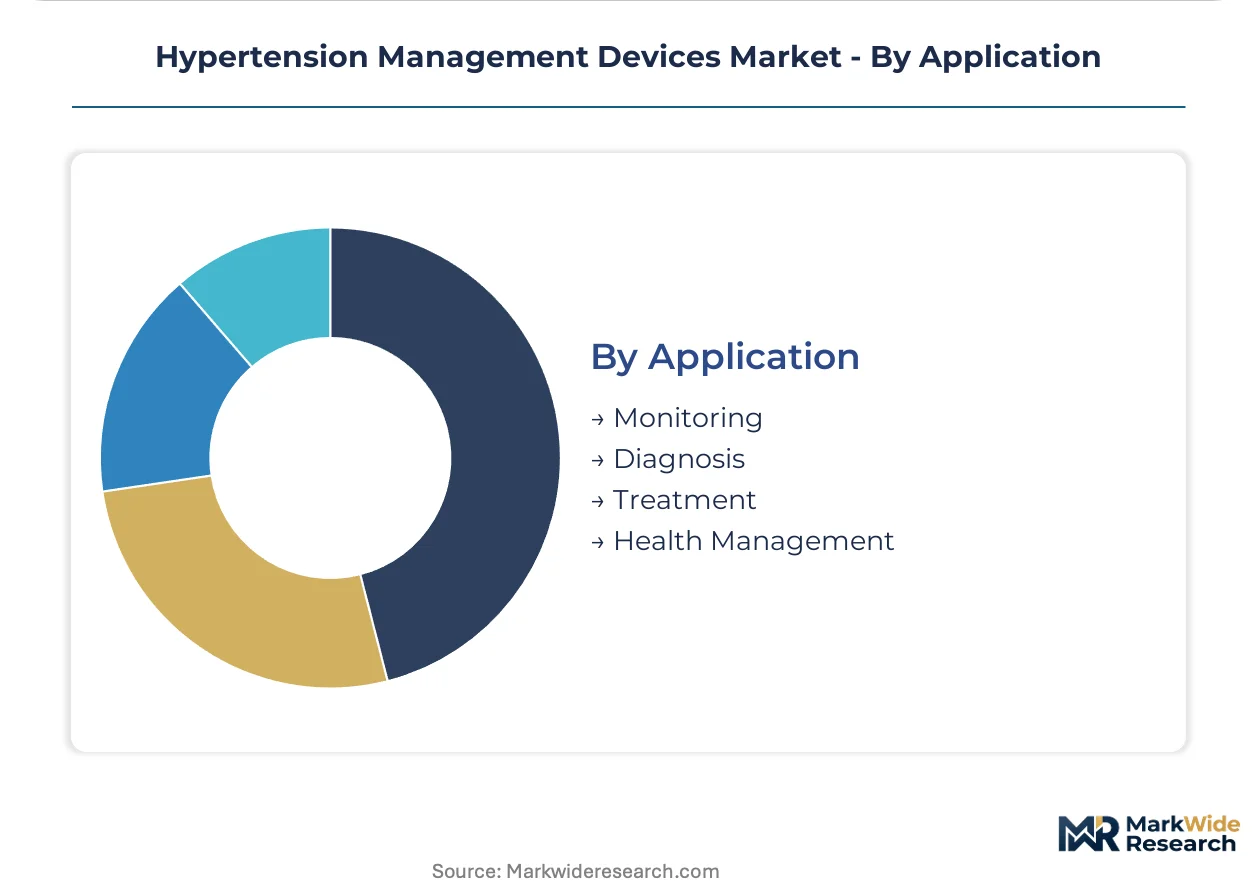
Application:
Maturity gradients separate established diagnostic and monitoring use cases from emerging treatment integration and holistic health management paradigms.
- Monitoring:Longitudinal pressure tracking for therapeutic adjustment and cardiovascular risk stratification constitutes the largest installed base. EU MDR software classification guidance imposes additional conformity assessment burdens on devices incorporating diagnostic algorithms.
- Health Management:Lifestyle intervention support and patient engagement platforms represent the frontier application as combined glucose-blood pressure wearables enable metabolic-cardiovascular convergence.
- Diagnosis:Initial hypertension detection and white-coat syndrome identification rely on validated clinic-based or ambulatory measurement protocols.
- Treatment:Closed-loop medication delivery integration remains experimental, with regulatory pathways for device-drug combination products still evolving.
Deepest penetration: Monitoring. Steepest expansion trajectory: Health Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Suzhou concentrate sensor foundry capacity for MEMS pressure transducers serving wearable blood pressure monitor supply chains.
United States
Medicare Advantage risk-bearing provider groups mandate interoperable data formats as procurement preconditions for connected monitors. FDA 510(k) cybersecurity documentation requirements now cover software bill of materials for IoT-integrated devices. Minneapolis anchors cardiac rhythm management infrastructure that supports hypertension device distribution across integrated health networks.
Germany
Statutory health insurance frameworks now cover connected blood pressure monitors for home-based cardiovascular monitoring. EU MDR conformity assessment imposes additional clinical evidence burdens on oscillometric systems entering European markets. Munich and Berlin host regional care networks accelerating procurement of validated digital platforms.
Japan
METI's Silver ICT standards initiative creates municipal procurement pathways for aging-in-place infrastructure. PMDA medical device regulation shapes validation timelines for wearable systems targeting diagnostic applications. Kyoto-Osaka manufacturing clusters supply precision MEMS components for cuffless monitoring technologies.
China
NMPA medical device registration drives extended validation protocols for oscillometric systems targeting domestic hospital procurement. Dual carbon goals pressure manufacturers toward energy-efficient production of connected monitoring hardware. Shenzhen special economic zones concentrate silicon photonics foundry capacity for chip-scale optical sensor integration.
India
CDSCO medical device rules impose quality management system requirements on imported hypertension monitors entering hospital channels. PLI scheme incentives attract assembly operations for digital blood pressure devices serving domestic and export markets. Bengaluru and Hyderabad clusters develop algorithmic signal processing capabilities for cuffless estimation technologies.
Hypertension Management Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated care network consolidation favoring single-vendor digital ecosystems over fragmented distributor relationships. The vendor base organizes around three strategic archetypes: cardiac rhythm management divisions leveraging existing hospital infrastructure, direct-to-consumer brands controlling pharmacy and retail channels, and sensor technology specialists enabling combined metabolic-cardiovascular platforms. Dominant competitive moves include enterprise contract negotiations with risk-bearing provider groups and silicon photonics foundry partnerships compressing sensor economics.
Within the cardiac rhythm management tier, Medtronic anchors distribution across United States integrated health networks. Omron Healthcare exemplifies direct-to-consumer channel control through pharmacy partnerships. Abbott occupies a position in sensor miniaturization for combined glucose-blood pressure wearable convergence.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Abbott |
| Omron Healthcare |
| Philips Healthcare |
| GE Healthcare |
| CVRX |
| Recor Medical |
| A&D Company |
| Others |
Value Chain & Pricing Dynamics
Integrated care network procurement consolidation in the United States is forcing manufacturers toward enterprise contract structures that bundle hardware with analytics, compressing spot-market premiums and rewarding captive foundry relationships for silicon photonics components.
Pricing Analysis
Short lead-time premiums for ISO 81060-2 validated oscillometric systems command 15-25% markups over standard delivery schedules as hospital purchasing committees face procedure backlogs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared connected monitors with EHR integration from basic pharmacy-channel units and unvalidated consumer wearables. Price differentiation hinges on cybersecurity documentation completeness and cloud analytics bundling. Cost compression in the economy tier is intensifying because of private-label pharmacy entrants sourcing from contract manufacturers in Shenzhen.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's NMPA localization preferences are reshaping sourcing toward Bengaluru assembly operations and Suzhou MEMS foundries. Taiwan, Japan, and China anchor microelectromechanical pressure transducer production, with Kyoto-Osaka clusters supplying precision components for cuffless technologies. Silicon wafers, optical waveguide substrates, and medical-grade inflation bladders constitute critical input dependencies. Single-source vulnerability concentrates in Taiwanese MEMS foundry capacity. Distribution runs through GPO contracts for hospital systems, direct-to-consumer pharmacy networks, and municipal procurement channels for aging-in-place programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as sensor miniaturization and algorithm development costs force players to capture upstream photonics capabilities and downstream data platform revenues.
For Market Incumbents: Deploy silicon photonics foundry partnerships to compress sensor economics and lock in component supply against MEMS capacity bottlenecks. Secure enterprise contracts with Medicare Advantage risk-bearing provider groups before procurement consolidates around single-vendor ecosystems. Counter Abbott's combined glucose-blood pressure convergence play by accelerating cardiac rhythm management infrastructure integration. For New Entrants and Emerging Players: Photoplethysmography algorithm refinement for arrhythmic patients offers a technology-first wedge into diagnostic applications where optical accuracy limitations currently block clinical validation. Target Japan's municipal Silver ICT procurement pathways where METI standards create transparent qualification criteria against entrenched oscillometric vendors. Pursue direct-to-consumer pharmacy private-label partnerships to bypass GPO-controlled hospital channels. For Investors and Strategic Acquirers: The window for entry favors sensor technology specialists with captive silicon photonics capabilities and FDA 510(k) clearance track records. Long-term viability rests on algorithm-as-medical-device revenue streams where EU MDR software classification creates compliance moats. Watch FDA cybersecurity guidance evolution as the inflection signal for IoT-integrated monitor market access thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Submission | Software bill of materials documentation satisfies evolving premarket requirements for cloud-connected monitors. |
| Silicon Photonics Foundry Partnership | CMOS-integrated optical sensors displace discrete LED-photodiode assemblies and compress manufacturing costs. |
| Hospital System Enterprise Contract | Medicare Advantage risk-bearing groups mandate interoperable data formats as procurement preconditions. |
| EU MDR Conformity Assessment | Dual-track validation for hardware and algorithm performance claims secures European market access. |
| Reimbursement Strategy Development | Germany's statutory health insurance coverage for home monitoring accelerates regional care network adoption. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and connected device regulatory affairs leads. FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and METI Silver ICT procurement guidelines provided validation layers. Bottom-up unit shipment modeling across product types and top-down healthcare expenditure allocation were triangulated for consistency.
Granularity-level modeling disaggregated volume and value across the projection horizon by product architecture, connectivity specification, sensor technology, end-user purchasing authority, and clinical application maturity. CAGRs were derived from segment-level growth trajectory analysis incorporating reimbursement expansion timelines, regulatory approval velocity, and technology substitution elasticities. MEMS foundry capacity utilization rates and silicon photonics yield improvement curves informed supply-side constraints.
Several conditions sit outside the modeled scope, including experimental closed-loop medication delivery integration, pharmaceutical combination product regulatory pathways, and acute geopolitical disruptions to Taiwanese foundry operations. Forecasts reflect documented assumptions regarding reimbursement code expansion velocity and cybersecurity guidance finalization timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Wearable Cardiac Devices Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market