
 Global Sclerotherapy Market | 2026-2036
Global Sclerotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sclerotherapy Market Foresight
German chemical manufacturers is expanding their output of polidocanol and sodium tetradecyl sulfate active pharmaceutical ingredients to serve sclerotherapy formulators worldwide. Boston Scientific Corporation leverages its interventional cardiology infrastructure to distribute complementary vascular access devices. Merz Pharma anchors its position through concentrated R&D on detergent-based sclerosant formulations. Chemische Fabrik Kreussler & Co. GmbH dominates European supply of polidocanol raw material for both branded and generic finished dosage forms.
Sclerotherapy denotes the injection of chemical irritants into blood vessels to induce endothelial damage, fibrosis, and eventual vessel obliteration, with modern formulations typically containing polidocanol, sodium tetradecyl sulfate, or hypertonic saline in concentrations ranging from 0.5% to 3% depending on target vessel diameter. Foam sclerosants generated through the Tessari method or mechanical agitation achieve superior surface-area-to-volume ratios for treating saphenous trunks, while direct injection modalities retain primacy for telangiectasia and reticular veins. Varicose vein interventions command the largest revenue pool within therapy areas due to symptomatic patient presentation and reimbursement alignment, whereas spider vein treatments at cosmetic institutes yield premium out-of-pocket pricing with lower per-procedure volumes. Ultrasound-guided delivery is displacing blind injection for truncal incompetence as real-time visualization reduces complications and retreatment rates.
The FDA oversees sclerosant drug approval and post-market surveillance in the United States, while the EMA coordinates centralized marketing authorization for foam and liquid formulations across EU member states. BIS pharmacopeial standards in India govern import quality for sodium tetradecyl sulfate API, directly affecting Troikaa Pharmaceuticals Limited's domestic manufacturing economics. Stakeholders must monitor evolving foam stability testing requirements across FDA and EMA pathways, as divergent validation protocols threaten to fragment product registration strategies and delay market entry for next-generation detergent-based formulations.
Market Dynamics
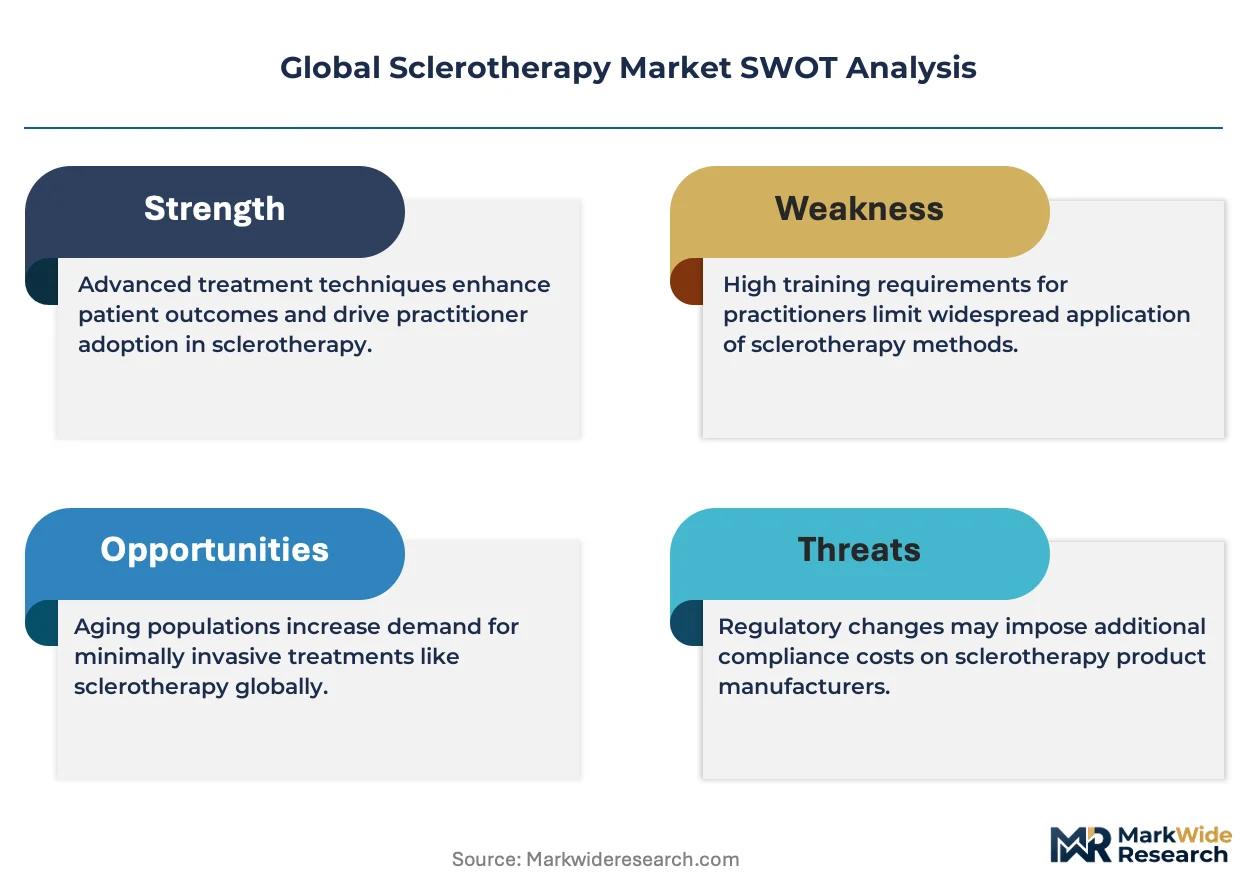
Foam stability testing divergence between FDA and EMA pathways is fragmenting product registration strategies, forcing manufacturers to maintain parallel validation protocols and delaying market entry for next-generation detergent-based sclerosant formulations.
Growth Catalysts
- EMA Centralized Authorization:The EMA's coordinated marketing authorization process accelerates foam and liquid formulation access across EU member states, reducing redundant national filings.
- Ultrasound-Guided Delivery:Real-time visualization technology is displacing blind injection for truncal incompetence, reducing complications and retreatment rates in phlebology clinics.
- German API Manufacturing:Concentrated polidocanol and sodium tetradecyl sulfate production in Germany anchors European supply security for both branded and generic finished dosage forms.
Market Restraints
- API Supply Concentration:German chemical manufacturers dominate polidocanol raw material output, creating geographic single-point vulnerability for global formulators.
- Foam Stability Validation Costs:Divergent FDA and EMA testing protocols force redundant clinical studies, inflating development budgets for foam sclerosant innovators.
- Hypertonic Saline Substitution:Lower-cost osmotic agents threaten detergent-based formulations in price-sensitive cosmetic vein treatment segments.
Strategic Opportunities
- Indian Domestic Manufacturing:BIS pharmacopeial standards for sodium tetradecyl sulfate API create captive supply incentives for Troikaa Pharmaceuticals Limited and local competitors.
- Cosmetic Institute Channel:Spider vein treatments at aesthetic clinics command premium out-of-pocket pricing with minimal reimbursement friction.
- Device-Sclerosant Bundling:Interventional cardiology infrastructure enables vascular access device pairing with sclerosant formulations for integrated procedural offerings.
Industry Challenges
- Sonographer Training Bottleneck:Ultrasound-guided sclerotherapy deployment outpaces certified technician availability, constraining procedure throughput in high-volume centers.
- Dual Registration Timelines:Parallel FDA drug approval and EMA centralized authorization processes extend time-to-market for foam formulation innovators by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sclerotherapy Market |
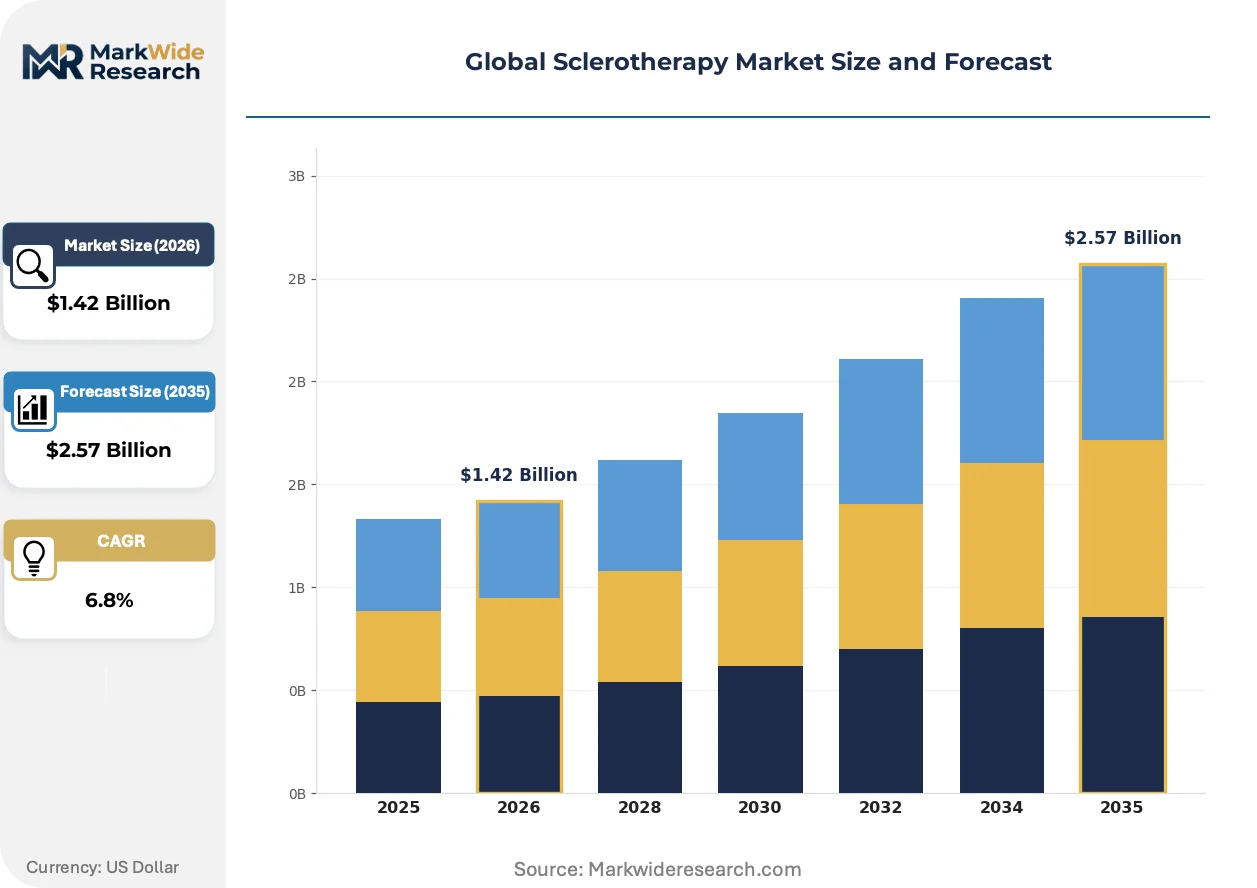
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sclerosant Solutions, Foam Sclerosants, Catheters, Syringes Therapy Area: Varicose Veins, Spider Veins, Hemorrhoids, Lymphatic Malformations End User: Phlebology Clinics, Dermatology Centers, Ambulatory Surgical Centers, Cosmetic Institutes Delivery Mode: Ultrasound-Guided, Direct Injection, Foam Injection, Micro-Needling |
| Companies Covered | Boston Scientific Corporation, Merz Pharma, Chemische Fabrik Kreussler & Co. GmbH, LGM Pharma, Troikaa Pharmaceuticals Limited, AngioDynamics, Medtronic, Perrigo Company plc, ENDO-FLEX GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sclerotherapy Market Shifts & Advancements
Real-time imaging integration and foam generation standardization are compressing procedure variability while regulatory divergence forces bifurcated product development tracks.
Mechanical agitation systems for foam sclerosant preparation are automating Tessari method consistency, eliminating operator-dependent density variation. Phlebology clinics in Germany and the United States are adopting these devices to standardize saphenous trunk treatments. The technology is automating quality control previously requiring specialized technician judgment, reducing retreatment frequency.
The FDA's evolving guidance on foam sclerosant stability is reshaping United States registration pathways, mandating extended shelf-life validation data. Manufacturers must now demonstrate bubble size distribution persistence across temperature excursions. Liquid formulation sponsors face reduced documentation burdens, creating competitive asymmetry in the American market.
Service unbundling is separating diagnostic ultrasound from interventional procedures in European reimbursement frameworks. German and French clinics now bill vein mapping and sclerotherapy as distinct encounters, shifting physician practice economics. This fragmentation is most visible in statutory health insurance systems where procedure coding granularity determines provider compensation.
Global Sclerotherapy Market Segmentation
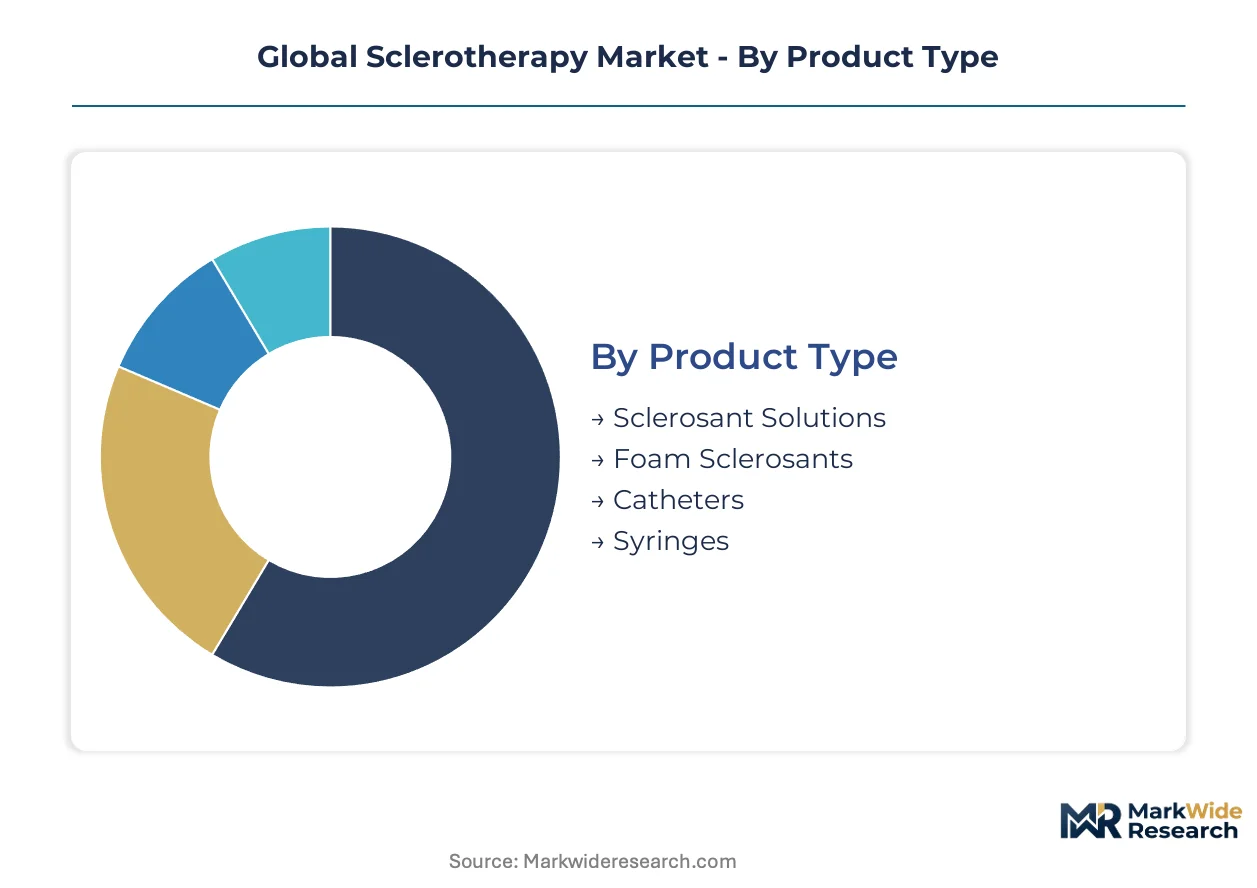
Sclerotherapy market segmentation reveals distinct procurement patterns across product categories. Pharmaceutical formulators, device manufacturers, and service providers each navigate divergent margin structures and regulatory pathways.
Product Type:
Sclerosant solutions function as standalone pharmaceutical products, while foam sclerosants and delivery devices embed into integrated procedural systems.
- Sclerosant Solutions:Liquid polidocanol and sodium tetradecyl sulfate formulations in concentrations from 0.5% to 3% serve as the foundational pharmaceutical intervention. Demand concentrates in phlebology clinics across Germany and the United States, where reimbursement codes favor established liquid protocols over experimental foam variants.
- Foam Sclerosants:Gas-liquid emulsions generated through mechanical agitation or Tessari method preparation achieve superior surface-area-to-volume ratios for saphenous trunk occlusion. Volume placements concentrate in European centers leveraging EMA centralized authorization; the steepest expansion trajectory belongs to United States sites awaiting FDA stability guidance finalization.
- Catheters:Vascular access devices enable ultrasound-guided delivery with integrated echogenic markers.
- Syringes:Specialized luer-lock configurations accommodate foam generation attachments and micro-injection precision.
Volume placements concentrate in Sclerosant Solutions; the faster expansion belongs to Foam Sclerosants.
Therapy Area:
Reimbursement alignment and out-of-pocket payment willingness create a cost tier structure across therapeutic indications.
- Varicose Veins:Symptomatic venous insufficiency with pain, edema, and skin changes commands the largest revenue pool due to established medical necessity criteria and statutory insurance coverage. German clinics report highest procedure volumes where Kreussler's API supply anchors formulation economics.
- Spider Veins:Cosmetic telangiectasia treatments yield premium per-procedure pricing at aesthetic institutes with minimal reimbursement friction. Demand clusters in private-pay cosmetic channels across France and the United States, where patient willingness to pay exceeds $300 per session.
- Hemorrhoids:Internal hemorrhoidal sclerotherapy offers outpatient alternatives to surgical hemorrhoidectomy.
- Lymphatic Malformations:Pediatric and adult vascular anomaly interventions represent a narrow specialty application.
Revenue gravity centers on Varicose Veins; margin premiums peak in Spider Veins.
End User:
Customer type determines procurement scale, with institutional buyers negotiating volume contracts against individual practitioner purchases.
- Phlebology Clinics:Dedicated venous disease centers achieve highest procedure throughput through specialized technician staffing and dedicated ultrasound infrastructure. German phlebology networks source directly from Kreussler-affiliated distributors, bypassing wholesale markup.
- Dermatology Centers:Skin-focused practices emphasize cosmetic spider vein treatments with lower per-site volumes but elevated pricing power. Concentrated demand appears in Paris and Milan aesthetic corridors where cross-selling with laser services drives patient capture.
- Ambulatory Surgical Centers:Medicare-certified facilities capture complex truncal incompetence cases requiring conscious sedation.
- Cosmetic Institutes:Medspa and aesthetic chains operate outside reimbursement frameworks with pure retail pricing.
Procurement volume leaders are Phlebology Clinics; pricing power concentrates in Cosmetic Institutes.
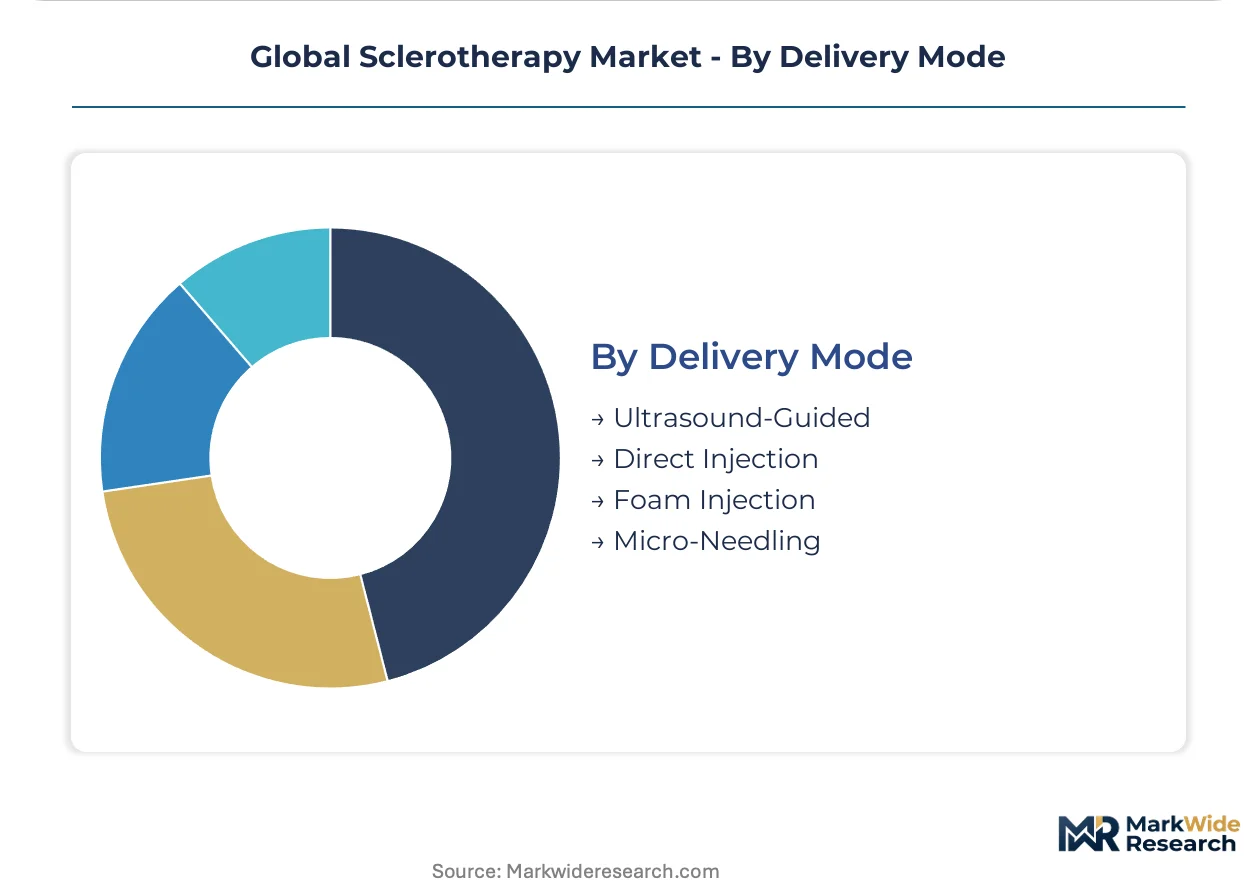
Delivery Mode:
Technology maturity separates established blind injection from visualization-dependent advanced modalities.
- Ultrasound-Guided:Real-time echogenic visualization enables precise truncal vein cannulation with documented reduction in complications and retreatment rates. Adoption accelerates in United States academic medical centers where sonographer training programs expand certified technician supply.
- Direct Injection:Blind subcutaneous delivery retains primacy for superficial telangiectasia and reticular veins where vessel depth obviates imaging. Volume dominance persists in Indian dermatology practices where equipment cost constraints limit ultrasound penetration.
- Foam Injection:Gas-liquid emulsion delivery requires specialized preparation protocols and immediate use windows.
- Micro-Needling:Fine-gauge superficial delivery targets cosmetic spider vein applications with minimal invasiveness.
Procedure counts favor Direct Injection; capability investment flows toward Ultrasound-Guided.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical manufacturing clusters anchor the raw-material foundation for sclerotherapy formulations worldwide, with polidocanol and sodium tetradecyl sulfate production concentrated in the Rhine-Main industrial corridor.
United States
FDA oversight of foam sclerosant stability testing drives extended validation timelines for domestic registrants. The agency's evolving guidance mandates bubble size distribution persistence data across temperature excursions. Academic medical centers in Boston and Philadelphia anchor ultrasound-guided procedure adoption through expanded sonographer training pipelines.
Germany
EMA centralized authorization accelerates foam formulation access across EU member states from Kreussler's Wiesbaden manufacturing base. The BfArM coordinates post-market surveillance with the EMA's pharmacovigilance framework. Frankfurt-Rhine-Main chemical clusters supply both branded and generic finished dosage formulators throughout Europe.
India
BIS pharmacopeial standards for sodium tetradecyl sulfate API create captive manufacturing incentives for domestic formulators. CDSCO oversees import quality gates that directly affect Troikaa Pharmaceuticals Limited's production economics. Gujarat and Maharashtra pharmaceutical corridors concentrate API finishing capacity for regional sclerotherapy markets.
France
ANSM regulates detergent-based sclerosant formulations alongside EMA centralized procedures, with Paris aesthetic institutes commanding premium spider vein treatment pricing. Service unbundling separates diagnostic ultrasound from interventional procedures in statutory health insurance frameworks. Île-de-France cosmetic clinics drive out-of-pocket payment volumes through cross-selling with laser services.
United Kingdom
MHRA post-Brexit regulatory autonomy diverges from EMA foam stability protocols, creating parallel registration requirements for UK market entry. NICE technology appraisals influence varicose vein intervention reimbursement thresholds in NHS England. London phlebology networks source liquid sclerosant formulations through German distributor channels.
Global Sclerotherapy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue device-sclerosant integration and automated foam generation systems. The market structure concentrates around pharmaceutical formulators with captive API access and interventional device manufacturers leveraging vascular infrastructure. Two archetypes dominate: detergent-based formulation specialists and diversified medtech conglomerates with cardiology distribution networks. Competitive moves center on backward integration into API supply and strategic partnerships with ultrasound equipment manufacturers.
Among German chemical manufacturers, Chemische Fabrik Kreussler & Co. GmbH anchors the API supply tier for polidocanol raw material. Boston Scientific Corporation exemplifies the device-centric archetype through its interventional cardiology infrastructure. Merz Pharma occupies a position within the formulation-specialist tier, with Troikaa Pharmaceuticals Limited representing the India-based generic manufacturing archetype.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Merz Pharma |
| Chemische Fabrik Kreussler & Co. GmbH |
| LGM Pharma |
| Troikaa Pharmaceuticals Limited |
| AngioDynamics |
| Medtronic |
| Perrigo Company plc |
| ENDO-FLEX GmbH |
| Others |
Supply & Pricing Matrix
Polidocanol API spot pricing in the Rhine-Main chemical corridor cascades through three-tier pricing structures across premium branded formulations, standard generic sclerosants, and economy hypertonic saline alternatives, with German manufacturing concentration amplifying cost pass-through volatility for downstream phlebology clinics.
Pricing Analysis
Service bundling separates diagnostic ultrasound from interventional procedures in European reimbursement frameworks, creating unbundled pricing exposure for standalone sclerosant purchases. Three-tier pricing structure across premium foam formulations, standard liquid detergents, and economy osmotic agents reflects certification grade and EMA centralized authorization status. Cost compression in the generic liquid tier intensifies because Indian API finishers exploit BIS pharmacopeial arbitrage. Cosmetic institutes exhibit lowest price sensitivity due to pure out-of-pocket payment structures, while ambulatory surgical centers face highest reimbursement constraint pressure.
Supply Chain Analysis
Reverse logistics for temperature-sensitive foam sclerosants remain underdeveloped, with expired or destabilized product flows lacking standardized refurbishment protocols. Manufacturing gravity centers on Germany, India, and the United States for API and finished dosage forms. Active pharmaceutical ingredient production draws from polidocanol, sodium tetradecyl sulfate, and hypertonic saline feedstocks. Single-source vulnerability concentrates in Kreussler's Wiesbaden polidocanol output. Distribution runs through phlebology clinic direct purchasing, German distributor networks, and Indian pharmaceutical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasound-guided delivery technology is displacing blind injection modalities, compressing the legacy procedural window for conventional sclerotherapy training and equipment amortization.
For Market Incumbents: Deploy backward integration into polidocanol API supply to secure margin protection against German chemical manufacturer pricing power. Accelerate sonographer certification partnerships with academic medical centers to constrain technician availability bottlenecks. Foam stability validation redundancy between FDA and EMA pathways threatens registration economics for detergent-based innovators. For New Entrants and Emerging Players: Launch via cosmetic institute direct distribution to capture premium spider vein pricing with minimal reimbursement friction. Target Indian domestic manufacturing incentives under BIS pharmacopeial standards for sodium tetradecyl sulfate API. Device-sclerosant bundling with automated foam generation systems offers the most penetrable white-space angle against established liquid formulation incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated foam generation device manufacturers with CE marking progress in Germany during FDA guidance uncertainty. Long-term viability hinges on regulatory pathway convergence rather than divergence across the extended pharmaceutical investment horizon. Monitor EMA-FDA foam stability protocol harmonization negotiations as the critical inflection signal for detergent-based formulation economics.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Authorization Pathway | Accelerates foam sclerosant access across EU member states from German manufacturing bases. |
| Backward Integration into API Supply | Secures polidocanol raw material economics against Rhine-Main chemical corridor concentration. |
| Automated Foam Generation System Launch | Standardizes Tessari method consistency for saphenous trunk treatments in phlebology clinics. |
| Sonographer Training Program Expansion | Addresses certified technician scarcity constraining ultrasound-guided procedure throughput. |
| Cosmetic Institute Channel Partnership | Captures premium spider vein pricing with minimal reimbursement friction in aesthetic markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with phlebologists, regulatory affairs specialists at EMA and FDA, hospital purchasing committee members, and biomedical engineers with validation from FDA 510(k) submissions, EMA centralized authorization documents, BIS pharmacopeial standards, and German chemical industry association reports. Bottom-up procedure volume estimates and top-down pharmaceutical revenue aggregates were triangulated to constrain forecast variance.
Granularity-level modeling operated at the intersection of product type, therapy area, end user, and delivery mode dimensions across the projection horizon. CAGRs were derived from segmented growth rate reconciliation against aggregate market boundary conditions. Ultrasound-guided adoption curves, foam stability testing protocol evolution, and Indian domestic manufacturing incentive utilization served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for mechanical agitation foam generation would alter the outlook if Tessari method retention persists. Forecasts reflect assumptions about EMA-FDA regulatory convergence, BIS standard enforcement intensity, and sonographer training pipeline expansion. Practitioners should monitor FDA foam stability guidance finalization, Kreussler capacity expansion announcements, and Indian CDSCO import quality gate modifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Patient-Controlled Injectors Market