
 Blood Pressure Transducers Market | 2026-2036
Blood Pressure Transducers Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Pressure Transducers Market Analysis
Ambulatory surgical centers are redrawing demand patterns for blood pressure transducers, pulling purchasing volume away from traditional hospital procurement. ICU Medical sustains a strong position through its specialized critical care monitoring portfolio. Edwards Lifesciences dominates the invasive hemodynamic monitoring segment with deep catheter-transducer integration. Masimo Corporation differentiates through its signal processing technology leadership in non-invasive optical platforms.
Blood pressure transducers convert arterial or venous pressure into measurable electrical signals, typically employing strain gauge, piezoelectric, or capacitive sensing elements with operating ranges of −50 to +300 mmHg and frequency responses exceeding 200 Hz for accurate waveform reproduction in surgical and critical care environments. Invasive transducers remain the margin pool for manufacturers due to their disposable nature and higher per-procedure revenue, while wireless transducers represent the fastest-growing category as hospitals seek to reduce cable-related infection risks and improve patient mobility. Strain gauge technology anchors the installed base across cardiac monitoring applications, though capacitive designs are gaining traction in homecare settings where cost and miniaturization priorities dominate.
The FDA's medical device cybersecurity requirements and the EU MDR's strengthened clinical evidence standards are elevating compliance costs and extending product registration timelines for transducer manufacturers seeking dual-market access. ISO 81060 standards for non-invasive blood pressure measurement and IEC 60601 electrical safety protocols further constrain design flexibility while creating barriers for unvalidated entrants. Stakeholders must weigh the capital intensity of wireless platform development against the risk of commoditization in mature invasive transducer lines as purchasing consolidation accelerates among integrated delivery networks.
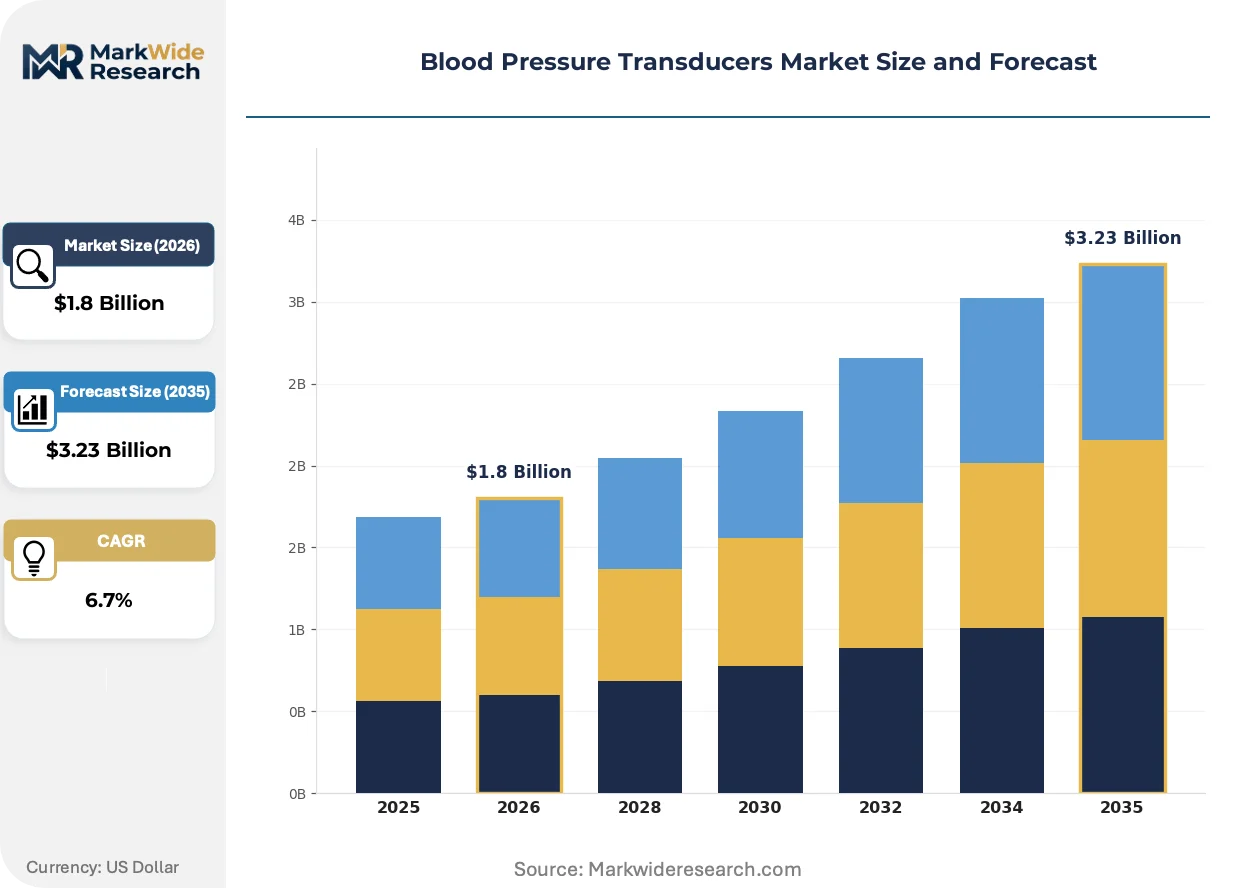
Market Dynamics
Ambulatory surgical centers are pulling purchasing volume away from traditional hospital procurement channels, forcing manufacturers to reconfigure distribution networks and service models around decentralized, high-frequency, lower-volume order patterns.
Growth Catalysts
- EU MDR clinical evidence mandates:Strengthened post-market surveillance requirements are accelerating replacement cycles for legacy transducer inventories across European acute care networks.
- Disposable transducer systems:Infection control protocols in United States surgical centers are driving single-use adoption over reusable alternatives.
- Wireless telemetry platforms:Cable elimination in critical care environments is reducing nosocomial infection vectors while improving patient mobility metrics.
Market Restraints
- Piezoelectric ceramic supply concentration:Sourcing dependency on East Asian substrate manufacturers creates input volatility for strain gauge transducer production.
- FDA cybersecurity validation timelines:Premarket submission requirements for connected monitoring devices extend product launch windows by 12-18 months.
- Optical pressure sensing substitution:Photoplethysmography advances in Masimo and similar platforms threaten invasive transducer volumes in moderate-acuity monitoring.
Strategic Opportunities
- Homecare hemodynamic monitoring:Capacitive miniaturization opens ambulatory patient segments previously served only by intermittent cuff-based measurement.
- Integrated health network standardization:United States IDN procurement consolidation creates vendor reduction opportunities for full-line monitoring suppliers.
- ISO 81060-2 non-invasive protocol expansion:Validation requirements for automated oscillometric devices favor calibrated transducer integration in diagnostic-grade equipment.
Industry Challenges
- Biomedical engineering talent scarcity:Shortage of specialists combining hemodynamic physiology with MEMS fabrication expertise constrains R&D throughput.
- IEC 60601-1 third edition compliance costs:Electrical safety retesting for legacy product portfolios diverts capital from wireless platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Pressure Transducers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Transducers, Non-Invasive Transducers, Wireless Transducers, Digital Transducers End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Technology: Piezoelectric Technology, Capacitive Technology, Strain Gauge Technology, Optical Technology Application: Cardiac Monitoring, Surgical Procedures, Anesthesia Monitoring, Critical Care |
| Companies Covered | Edwards Lifesciences Corporation, ICU Medical, Inc, Medtronic plc, GE Healthcare, Inc., Masimo Corporation, Smiths Group plc, Omron Healthcare, B. Braun SE, Utah Medical Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Pressure Transducers Market Emerging Trajectories
Wireless connectivity architectures and disposable material science are converging to reshape product form factors, while regulatory pressure on cybersecurity and clinical evidence is elevating development thresholds for market entry.
Capacitive pressure sensing is fragmenting the traditional strain gauge dominance in cardiac monitoring applications. Ambulatory surgical centers in the United States are adopting capacitive designs for their lower per-unit cost and reduced calibration requirements. This technology diffusion is fragmenting vendor specialization boundaries as semiconductor manufacturers enter medical device supply chains.
EU MDR post-market clinical follow-up requirements are extending surveillance obligations for transducer manufacturers selling into European markets. Device history record retention periods now span full product lifecycles plus additional years. Invasive disposable transducers face the steepest documentation burden given their high-volume, single-use consumption patterns.
Integrated delivery networks in the United States are consolidating hemodynamic monitoring procurement across acute and outpatient settings. Standardized vendor contracts are displacing individual facility purchasing autonomy. This concentration is most visible in multi-state health systems where central supply committees mandate uniform transducer specifications across all care sites.
Blood Pressure Transducers Market Segmentation
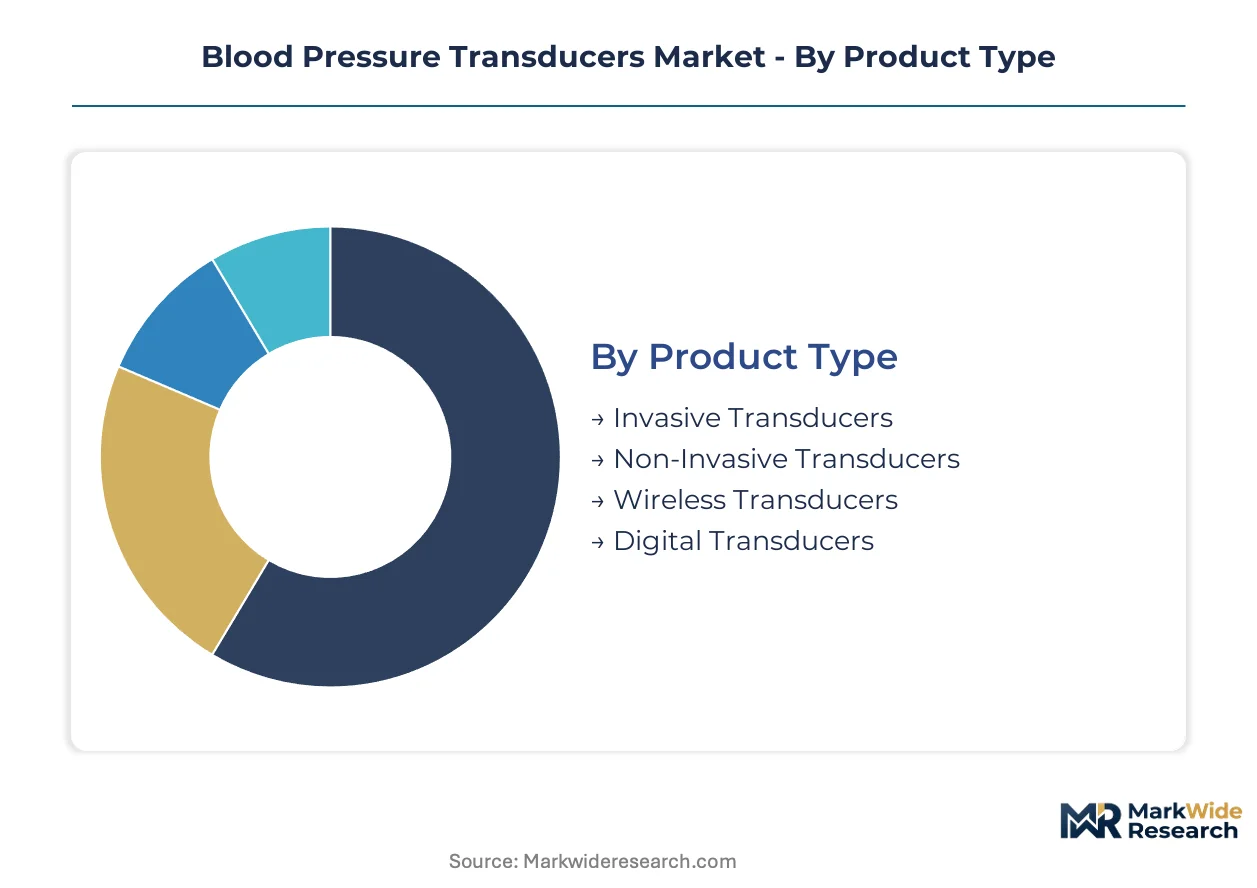
Segmentation in blood pressure transducers reveals how technology substitution and care setting migration are redrawing competitive boundaries. Manufacturers must align R&D portfolios with the divergence between high-acuity invasive platforms and emerging non-invasive alternatives.
Product Type:
Optical and wireless substitutes are exerting the strongest pressure on legacy invasive lines, forcing incumbents to defend installed base relationships through catheter-transducer integration.
- Invasive Transducers:Disposable strain-gauge assemblies with fluid-filled coupling dominate cardiac catheterization labs and operating rooms. United States integrated delivery networks standardize on single-use configurations to satisfy joint commission infection protocols.
- Wireless Transducers:Bluetooth-enabled capacitive sensors eliminate cable clutter in step-down units and telemetry wards. Demand concentrates in tertiary hospitals pursuing patient mobility metrics and reduced central line-associated infection rates.
- Non-Invasive Transducers:Oscillometric and tonometric platforms serve outpatient monitoring with lower per-procedure reimbursement.
- Digital Transducers:Integrated ADC architectures streamline EMR connectivity for automated vital sign documentation.
Invasive transducers retain volume leadership; wireless transducers hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital procurement from the lean inventory models emerging in decentralized surgical settings.
- Hospitals:Acute care networks deploy full-spectrum monitoring across ICU, OR, and emergency departments. Strain-gauge invasive systems anchor enterprise contracts with multi-year disposable supply agreements.
- Ambulatory Surgical Centers:Freestanding facilities prioritize single-use transducer bundles with minimal calibration overhead. United States outpatient migration drives preference for pre-sterilized, procedure-matched kits.
- Clinics:Physician office labs favor non-invasive automated cuffs with transducer-integrated validation.
- Homecare:Capacitive miniaturization enables patient-managed hemodynamic tracking outside institutional settings.
Hospitals dominate procurement value; ambulatory surgical centers are gaining share fastest in unit volume.
Technology:
Application-specific performance requirements fragment supplier specialization across cardiac precision versus consumer-scale cost targets.
- Strain Gauge Technology:Metal foil or semiconductor strain elements deliver ±1% full-scale accuracy for arterial waveform reproduction. Cardiac surgery suites in Germany and the United States specify this architecture for high-fidelity pressure tracing.
- Optical Technology:Photoplethysmographic platforms from Masimo and comparable vendors exploit multi-wavelength LED arrays for continuous non-invasive monitoring. Moderate-acuity step-down units adopt these to reduce arterial line placement.
- Piezoelectric Technology:Ceramic crystal transducers serve dynamic pressure measurement in research and specialized catheter applications.
- Capacitive Technology:MEMS-fabricated diaphragm sensors enable miniaturization for wearable and implantable formats.
Strain gauge technology commands the installed base; optical platforms are climbing the fastest on substitution-driven expansion.
Application:
Volume concentration in surgical and critical care settings sustains premium pricing, while anesthesia monitoring faces commoditization from integrated multi-parameter systems.
- Cardiac Monitoring:Invasive arterial and pulmonary artery pressure transduction supports hemodynamic optimization in heart failure and shock management. United States cardiac catheterization labs require FDA-cleared precision for interventional procedures.
- Critical Care:Continuous invasive monitoring in medical and surgical ICUs drives the highest disposable consumption rates. European networks under EU MDR post-market surveillance mandates accelerate replacement of legacy transducer inventories.
- Surgical Procedures:General and specialty operating rooms deploy standardized pressure monitoring for hemodynamic stability.
- Anesthesia Monitoring:Automated non-invasive oscillometric integration reduces standalone transducer demand in induction and recovery.
Cardiac monitoring retains procedural value concentration; critical care sustains the steepest volume trajectory through ICU bed expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate purchasing power for hemodynamic monitoring equipment, while ambulatory surgical migration and regulatory divergence across jurisdictions reshape regional demand patterns.
United States
Multi-state health systems standardize transducer specifications across acute and outpatient sites through central supply committees. FDA cybersecurity guidance for connected monitoring devices extends premarket validation timelines. The Boston-Cambridge corridor anchors critical care technology development with specialized catheter-transducer integration capabilities.
Germany
Cardiac surgery suites specify strain-gauge architectures with ±1% full-scale accuracy for arterial waveform reproduction. EU MDR post-market surveillance mandates accelerate replacement cycles for legacy transducer inventories. The Baden-Württemberg medical technology cluster supports precision manufacturing for invasive disposable systems.
China
Domestic hospitals expand ICU bed capacity and upgrade hemodynamic monitoring infrastructure. NMPA medical device registration requirements tighten clinical evidence standards for imported transducer systems. The Yangtze River Delta region concentrates MEMS fabrication capacity for capacitive sensor miniaturization.
Japan
Aging demographics drive demand for continuous patient monitoring in acute care settings. PMDA quality management system inspections enforce rigorous device history record retention for disposable transducers. The Kansai region maintains specialized production of piezoelectric ceramic substrates for pressure sensing applications.
India
Private hospital chains invest in cardiac catheterization labs and critical care infrastructure. CDSCO medical device rules classify invasive transducers under higher-risk categories with strengthened import documentation. The Maharashtra-Gujarat pharmaceutical-medical device corridor attracts contract manufacturing for single-use monitoring accessories.
Blood Pressure Transducers Market Vendor Landscape
Player mix skews toward diversified medical technology conglomerates with critical care portfolios, creating a tiered structure where catheter-transducer integration capabilities separate premium positioning from commodity supply. Strategic archetypes include full-line monitoring suppliers defending enterprise contracts, specialized hemodynamic players leveraging clinical workflow expertise, and semiconductor entrants exploiting MEMS miniaturization for wireless formats. Competitive moves concentrate on portfolio diversification into telemetry platforms and strategic partnerships with integrated delivery networks for multi-year disposable supply agreements.
Among United States-based critical care specialists, Edwards Lifesciences Corporation and ICU Medical, Inc. occupy positions at the invasive hemodynamic monitoring tier, while Masimo Corporation exemplifies the non-invasive optical platform archetype with signal processing differentiation. These three anchors represent the divergence between catheter-integrated disposable systems and wireless telemetry alternatives reshaping competitive boundaries.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| ICU Medical, Inc |
| Medtronic plc |
| GE Healthcare, Inc. |
| Masimo Corporation |
| Smiths Group plc |
| Omron Healthcare |
| B. Braun SE |
| Utah Medical Products, Inc. |
| Others |
Supply Flow & Price Mechanics
FDA cybersecurity validation requirements and EU MDR clinical evidence standards simultaneously gate supplier qualification and stratify price tiers, forcing manufacturers to absorb compliance overhead into premium positioning or sacrifice margin in commoditized segments.
Pricing Analysis
Next-generation wireless capacitive platforms command substantial premiums over legacy strain-gauge assemblies, while prior-generation piezoelectric systems face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier, ISO 81060 validation status, and catheter integration depth. Pricing pressure stems from optical photoplethysmography substitution in moderate-acuity monitoring. Ambulatory surgical centers exhibit highest price sensitivity due to lean inventory models; cardiac catheterization labs show lowest sensitivity given procedural reimbursement structures.
Supply Chain Analysis
Extended lead times for piezoelectric ceramic substrates and MEMS-fabricated capacitive diaphragms strain just-in-time inventory models across transducer assembly lines. Manufacturing concentrates in Germany, the United States, and China, with raw material dependencies spanning East Asian ceramic substrate suppliers, European semiconductor foundries, and domestic sterilization packaging operations. Single-source vulnerability in specialty ceramic crystal sourcing creates input volatility. Distribution runs through integrated delivery network central supply committees and specialized critical care distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across care settings—acute hospitals, ambulatory surgical centers, and emerging homecare monitoring—creates multiple specialization niches where focused players can outmaneuver diversified conglomerates.
For Market Incumbents: Fortify catheter-transducer integration capabilities to defend against optical substitution in cardiac monitoring. Deepen backward integration into MEMS fabrication to secure capacitive sensor supply for wireless platform expansion. Prioritize FDA premarket submission resources toward connected device cybersecurity validation.
For New Entrants and Emerging Players: Anchor in ambulatory surgical center supply chains where standardized kit configurations reduce incumbent switching costs. Target United States outpatient migration corridors with pre-sterilized, procedure-matched disposable bundles. Pursue GPO contract qualification as the primary go-to-market pathway.
For Investors and Strategic Acquirers: EU MDR post-market surveillance mandates reshape the acquisition landscape toward targets with robust device history record infrastructure and European notified body relationships. Five-to-ten year viability favors specialized hemodynamic players with catheter integration expertise over commodity transducer suppliers. Monitor FDA cybersecurity guidance enforcement intensity as inflection indicator for connected monitoring platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Premarket validation timelines extend launch windows for connected transducer platforms. |
| CE Marking Pathway | EU MDR clinical evidence requirements favor manufacturers with European notified body relationships. |
| Hospital System Partnership | Integrated delivery network standardization creates multi-year disposable supply agreement opportunities. |
| Software Companion Development | EMR-integrated vital sign documentation differentiates digital transducer architectures. |
| Reimbursement Strategy | CPT code alignment for invasive hemodynamic monitoring sustains cardiac catheterization lab demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cardiac catheterization lab directors, hospital purchasing committee members, biomedical engineering specialists, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up unit demand modeling triangulated against top-down market sizing across technology generations and care settings.
Across the analysis window, forecasts incorporate product-type segmentation by invasive, wireless, non-invasive, and digital architectures; end-user stratification across hospitals, ambulatory surgical centers, clinics, and homecare; and technology differentiation among strain gauge, optical, piezoelectric, and capacitive sensing elements. CAGRs derive from replacement cycle analysis, ICU bed expansion trajectories, and outpatient migration patterns in United States integrated delivery networks.
Decision-makers should treat outputs as directional under assumptions of stable regulatory enforcement intensity and continued optical technology substitution rates; material deviation would warrant model refresh. Specific risk factors include FDA cybersecurity validation timeline extensions, EU MDR post-market surveillance cost escalation, and piezoelectric ceramic supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Global Vascular Embolization Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Infusion System Market