
 Cardiovascular Anastomosis Devices Market | 2026-2036
Cardiovascular Anastomosis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Anastomosis Devices Market Intelligence
CE-marked device tiers is reorganizing procurement criteria across European cardiac centers. Medtronic plc anchors its position through captive supply of suture-based anastomosis platforms. Johnson & Johnson Services Inc. differentiates via R&D intensity in mechanical coupler architectures. Abbott Laboratories leverages geographic dominance across North American hospital networks.
Cardiovascular anastomosis devices comprise implantable and instrument-based systems designed to create patent connections between blood vessels or grafts, typically fabricated from biocompatible polymers, ePTFE, or stainless steel alloys with burst-pressure ratings exceeding 300 mmHg. These devices serve to restore or redirect blood flow during revascularization procedures while minimizing thrombogenic risk and operative time. Mechanical couplers occupy the mature revenue core due to established coronary bypass protocols, whereas robotic-assisted technology segments capture accelerating preference as cardiac centers invest in da Vinci-compatible anastomosis modules. Vascular graft applications sustain premium positioning through saphenous vein and synthetic conduit demand in peripheral vascular surgery.
FDA 510(k) pathways and EU MDR conformity assessments govern device commercialization, with the latter extending technical documentation requirements for medium-risk cardiovascular implants. The EU AI Act introduces additional scrutiny for machine-learning-guided surgical planning tools paired with robotic anastomosis systems. Stakeholders must monitor reimbursement coding evolution for robotic-assisted cardiac procedures across CMS and national health technology assessment bodies.
Market Dynamics
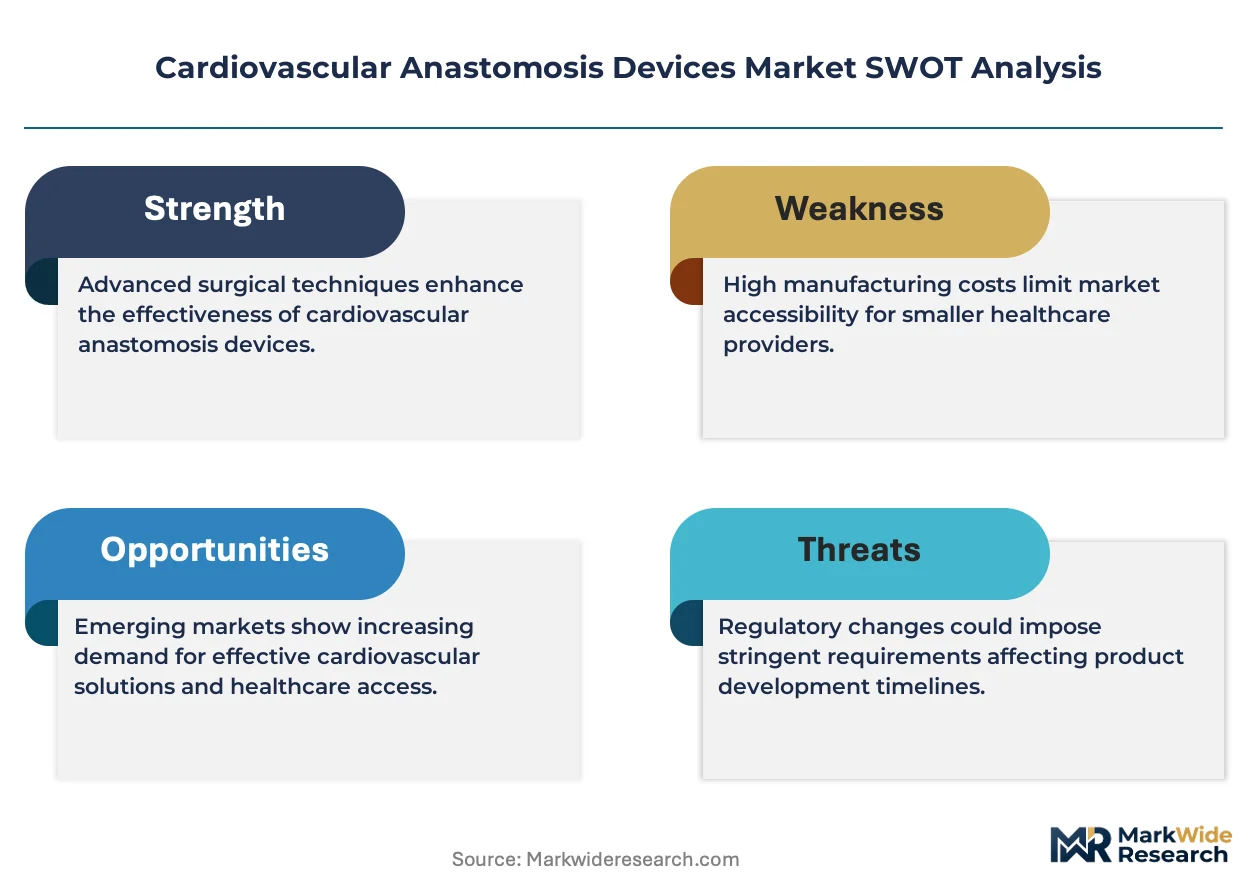
Robotic-assisted surgical platforms are compressing operative timelines for coronary revascularization while EU MDR conformity assessments extend technical documentation burdens for medium-risk cardiovascular implants.
Growth Catalysts
- EU MDR Transition:CE-marked device tiers are reorganizing procurement criteria across European cardiac centers, favoring suppliers with robust quality management systems.
- da Vinci-Compatible Modules:Cardiac centers are expanding their adoption of robotic-assisted anastomosis systems as surgical precision standards tighten.
- Japan's Aging Demographics:Established reimbursement frameworks in Tokyo and Osaka support complex cardiac procedure volumes for mechanical coupler deployment.
Market Restraints
- ePTFE Supply Concentration:Biocompatible polymer feedstock for vascular grafts concentrates among specialty chemical suppliers in Germany and Switzerland.
- FDA 510(k) Timeline Compression:Class II cardiovascular device clearances face extended review cycles as predicate device databases narrow.
- Suture-Based Protocol Persistence:Manual anastomosis techniques retain institutional preference in cost-constrained hospital systems.
Strategic Opportunities
- Peripheral Vascular Surgery:Saphenous vein and synthetic conduit applications sustain premium positioning outside coronary bypass protocols.
- EU AI Act Alignment:Machine-learning-guided surgical planning tools paired with robotic systems face additional scrutiny, creating first-mover advantage for compliant vendors.
- India's CDSCO Pathways:Domestic manufacturing incentives under PLI schemes attract suture-based anastomosis platform localization.
Industry Challenges
- Robotic Surgery Certification:Cardiac surgeons require extended training curves for autonomous anastomosis execution, delaying system utilization rates.
- EU MDR Technical Documentation:Medium-risk cardiovascular implants demand expanded clinical evidence portfolios, stretching R&D-to-commercialization intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Anastomosis Devices Market |
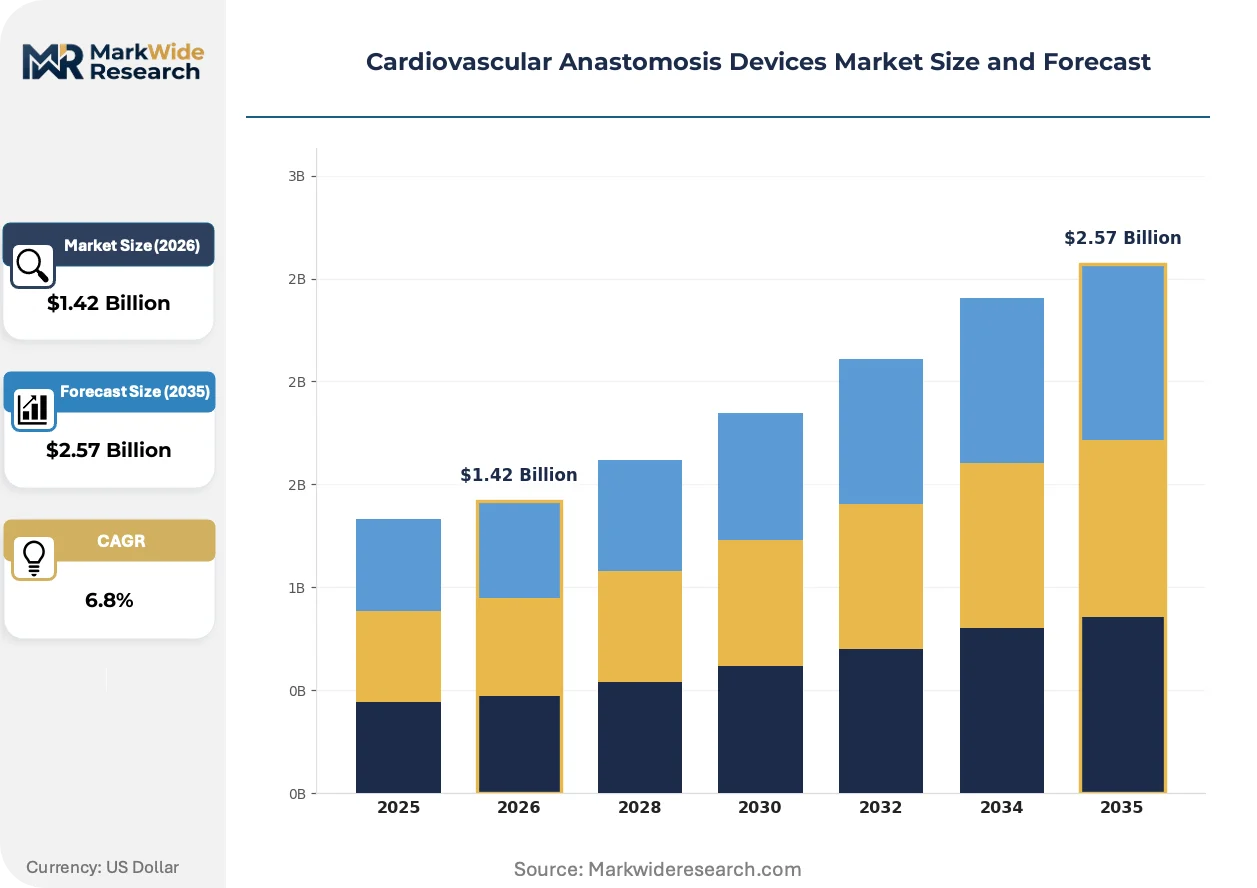
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Couplers, Vascular Grafts, Anastomosis Clips, Suture Devices End User: Hospitals, Cardiac Centers, Ambulatory Surgical Centers, Specialty Clinics Application: Coronary Bypass Surgery, Peripheral Vascular Surgery, Heart Valve Repair, Congenital Heart Surgery Technology: Laser-Assisted, Robotic-Assisted, Manual Techniques, Bioengineering Solutions |
| Companies Covered | Peters Surgical, Johnson & Johnson Services Inc., Medtronic plc, Intuitive Surgical Operations, Inc., Baxter, B. Braun Melsungen AG, Abbott Laboratories, Terumo Corporation, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Anastomosis Devices Market Strategic Shifts & Innovations
Convergence between mechanical coupler architectures and autonomous suturing algorithms is redefining competitive boundaries in coronary revascularization equipment.
Autonomous suturing algorithms are fragmenting the traditional mechanical coupler segment by enabling real-time tension adjustment during vessel approximation. Academic medical centers in the United States and Germany are piloting these systems for off-pump coronary artery bypass procedures. The technology is fragmenting established vendor relationships as hospitals evaluate hybrid procurement models combining capital equipment with per-procedure consumables.
EU MDR conformity assessments are extending technical documentation requirements for medium-risk cardiovascular implants beyond previous Medical Device Directive timelines. Manufacturers must submit expanded clinical evidence portfolios to notified bodies in Germany and the Netherlands. Medium-sized device firms are responding by consolidating regulatory affairs functions and outsourcing post-market surveillance to specialized consultancies.
Hospital procurement committees are bundling robotic-assisted anastomosis modules with comprehensive service agreements spanning maintenance, software updates, and surgeon training. Traditional capital equipment sales channels face displacement from multi-year performance contracts in United States integrated delivery networks. This restructuring is most visible in California and Texas health systems where procedure volume guarantees determine contract terms.
Cardiovascular Anastomosis Devices Market Segmentation
Segmentation in cardiovascular anastomosis devices reveals how procurement committees weight burst-pressure ratings against training overhead. Product type and technology choices determine contract structures across integrated delivery networks.
Product Type:
Margin pools concentrate in vascular grafts where biocompatible polymer specifications command premium positioning, while mechanical couplers defend volume through established coronary bypass protocols.
- Mechanical Couplers:Stainless steel and titanium architectures with burst-pressure ratings exceeding 300 mmHg anchor coronary revascularization workflows. Demand clusters in German cardiac centers where da Vinci-compatible modules compress operative timelines.
- Vascular Grafts:ePTFE and saphenous vein conduits sustain premium positioning through peripheral vascular surgery applications. Procurement in Tokyo and Osaka health systems favors synthetic options under established reimbursement frameworks.
- Anastomosis Clips:Polymer-based locking mechanisms reduce thrombogenic risk in off-pump procedures.
- Suture Devices:Manual and powered delivery systems retain institutional preference in cost-constrained hospital systems.
Mechanical couplers hold installed capacity. Vascular grafts are rotating up the share rankings.
End User:
Application complexity and capital equipment access determine where robotic-assisted systems displace manual techniques.
- Hospitals:Integrated delivery networks in California and Texas bundle anastomosis modules with multi-year service agreements spanning maintenance and surgeon training.
- Cardiac Centers:Academic medical centers in the United States and Germany pilot autonomous suturing algorithms for off-pump coronary artery bypass, fragmenting traditional vendor relationships.
- Ambulatory Surgical Centers:Procedure volume constraints limit adoption to mechanical coupler and clip-based systems.
- Specialty Clinics:Peripheral vascular focus drives demand for saphenous vein graft applications outside coronary protocols.
Cardiac centers absorb training overhead fastest. Ambulatory surgical centers lag on capital deployment.
Application:
Reimbursement coding evolution shapes where robotic-assisted procedures gain traction against manual alternatives.
- Coronary Bypass Surgery:Off-pump and on-pump revascularization protocols drive the steepest expansion trajectory for autonomous suturing systems as precision standards tighten.
- Peripheral Vascular Surgery:Synthetic conduit demand sustains premium positioning through saphenous vein and ePTFE graft deployment in limb salvage procedures.
- Heart Valve Repair:Minimally invasive approaches require specialized anastomosis clips for tissue approximation.
- Congenital Heart Surgery:Pediatric anatomical variation limits standardization, favoring manual suture techniques.
Coronary bypass holds procedure volume concentration. Peripheral vascular surgery is climbing the fastest on aging demographics.
Technology:
Regulatory scrutiny intensity separates capital-intensive platforms from consumable-heavy alternatives.
- Robotic-Assisted:da Vinci-compatible anastomosis modules face extended training curves for cardiac surgeons, delaying utilization rates in United States academic centers.
- Laser-Assisted:Tissue welding systems reduce operative time in microvascular applications. EU AI Act alignment creates first-mover advantage for machine-learning-guided surgical planning tools paired with these platforms.
- Manual Techniques:Suture-based protocols persist in cost-constrained systems and emerging markets.
- Bioengineering Solutions:Bioresorbable stents and tissue-engineered conduits remain pre-commercial.
Manual techniques defend installed base. Robotic-assisted systems are gaining share fastest on precision mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of ePTFE vascular grafts concentrate from German and Swiss specialty chemical suppliers toward cardiac centers in Japan and the United States, while robotic-assisted anastomosis modules move in the reverse direction from American manufacturers to European and Asian hospital networks.
United States
Integrated delivery networks in California and Texas bundle da Vinci-compatible anastomosis modules with multi-year service agreements covering maintenance and surgeon training. FDA 510(k) pathways for Class II cardiovascular devices face extended review cycles as predicate device databases narrow. Academic medical centers in Boston and New York pilot autonomous suturing algorithms for off-pump coronary artery bypass procedures.
Germany
Cardiac centers in Munich and Heidelberg anchor European demand for mechanical couplers with burst-pressure ratings exceeding 300 mmHg. EU MDR conformity assessments extend technical documentation requirements for medium-risk cardiovascular implants beyond previous Medical Device Directive timelines. Notified bodies in Berlin and Tübingen process expanded clinical evidence portfolios for CE-marked device tiers.
Japan
Tokyo and Osaka health systems sustain premium positioning for synthetic vascular grafts under established reimbursement frameworks. PMDA reviews compress approval timelines for robotic-assisted surgical platforms as precision standards tighten. The Kansai region concentrates procurement of saphenous vein conduit applications for peripheral vascular surgery.
India
Domestic manufacturing incentives under PLI schemes attract suture-based anastomosis platform localization in Maharashtra and Gujarat. CDSCO pathways for Class C and D cardiovascular devices require indigenous clinical trials, stretching commercialization intervals. Hyderabad and Bangalore clusters develop cost-constrained hospital system supply chains.
Switzerland
Specialty chemical suppliers in Basel and Zurich control ePTFE feedstock concentration for vascular graft biocompatible polymers. Swissmedic maintains alignment with EU MDR standards while preserving independent device authorization pathways. The country's precision manufacturing base exports to German and French cardiac centers.
Cardiovascular Anastomosis Devices Market Key Industry Players
Listed leaders compete with private specialists across capital equipment and consumable portfolios, creating a tiered structure where scale-driven multinationals face focused mid-cap innovators. The vendor base separates into three strategic archetypes: diversified medical technology conglomerates with captive cardiovascular divisions, pure-play surgical robotics specialists, and regional consumable manufacturers with cost-optimized suture platforms. Dominant competitive moves include M&A activity targeting robotic-assisted technology segments and strategic partnerships bundling capital equipment with per-procedure consumables.
Among diversified medical technology conglomerates, Medtronic plc and Johnson & Johnson Services Inc. exemplify scale-driven archetypes with broad cardiovascular portfolios, while Abbott Laboratories anchors North American geographic concentration. Within the surgical robotics tier, Intuitive Surgical Operations, Inc. represents platform-centric positioning. Specialists in mechanical coupler architectures include Peters Surgical and B. Braun Melsungen AG, with Terumo Corporation and Getinge AB occupying positions in vascular graft and perfusion technology segments respectively. Baxter sits within the diversified hospital supply tier with cross-category reach.
| Leading Market Players |
|---|
| Peters Surgical |
| Johnson & Johnson Services Inc. |
| Medtronic plc |
| Intuitive Surgical Operations, Inc. |
| Baxter |
| B. Braun Melsungen AG |
| Abbott Laboratories |
| Terumo Corporation |
| Getinge AB |
| Others |
Cost & Logistics Intelligence
ePTFE substitution for saphenous vein conduits is compressing procurement budgets across German and Japanese cardiac centers while simultaneously redrawing raw material sourcing maps from Swiss specialty chemical suppliers toward Asian polymer compounders.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium robotic-assisted modules, standard mechanical couplers, and economy suture platforms. Price differentiation hinges on FDA 510(k) clearance tier and bundled service agreement scope. Cost compression in the standard tier is intensifying because EU MDR technical documentation requirements are stretching R&D-to-commercialization intervals. Ambulatory surgical centers exhibit the highest price sensitivity, while academic medical centers in the United States absorb premium positioning for autonomous suturing systems.
Supply Chain Analysis
Germany and Switzerland anchor ePTFE biocompatible polymer production for vascular graft feedstock, with Japan and the United States serving as primary demand anchors. Manufacturing draws from stainless steel alloys, titanium architectures, and laser-welding components. Single-source vulnerability concentrates in German specialty chemical suppliers for burst-pressure-rated polymers. Distribution runs through integrated delivery networks in California and Texas that bundle capital equipment with multi-year consumable contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from surgeon training programs and software maintenance subscriptions is expanding faster than hardware sales as cardiac centers prioritize utilization guarantees over capital ownership.
For Market Incumbents: Consolidate regulatory affairs functions across EU MDR and FDA 510(k) pathways to compress clearance timelines. Deepen backward integration into ePTFE polymer feedstock to defend margin position against Swiss supplier concentration. Threat substitution from autonomous suturing algorithms demands preemptive R&D in da Vinci-compatible module architectures. For New Entrants and Emerging Players: Anchor in India's CDSCO Class C and D device pathways where domestic manufacturing incentives under PLI schemes offset indigenous clinical trial burdens. Target cost-constrained hospital systems in Maharashtra and Gujarat with suture-based platform localization. Go-to-market leverage rests on Hyderabad and Bangalore cluster partnerships for supply chain efficiency. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed surgical robotics specialists facing extended utilization rate delays from cardiac surgeon certification bottlenecks. Long-term viability across the analysis window favors platforms with demonstrated EU AI Act compliance for machine-learning-guided surgical planning. Signal to monitor: PMDA approval timeline compression for robotic-assisted platforms in Tokyo and Osaka health systems.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments in Berlin and Tübingen demand expanded clinical evidence portfolios. |
| Hospital System Partnership | California and Texas integrated delivery networks bundle anastomosis modules with procedure volume guarantees. |
| Software Companion Development | Autonomous suturing algorithms for off-pump coronary artery bypass fragment traditional vendor relationships. |
| Reimbursement Strategy | CMS coding evolution for robotic-assisted cardiac procedures determines adoption velocity in academic centers. |
| FDA Submission | Class II cardiovascular device clearances face extended review cycles as predicate device databases narrow. |
Research Approach
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with cardiac surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Primary fieldwork across United States academic medical centers, German notified bodies, and Japanese PMDA reviewers combined with secondary validation from SEC filings and customs trade data. Bottom-up procedure volume modeling and top-down market sizing triangulated segment-level outputs.
Variance decomposition across product type, technology tier, end-user category, and geographic regulatory cluster shaped analytical framework development over the projection horizon. CAGRs derived from surgeon training curve adoption rates, reimbursement coding evolution timelines, and ePTFE feedstock cost trajectories. Modeled inputs incorporated da Vinci-compatible module installation bases and autonomous suturing algorithm pilot program expansions.
Material uncertainties — EU AI Act implementation scope, PMDA robotic surgery approval acceleration, and ePTFE supplier consolidation — sit outside the modeled envelope. Forecasts reflect assumptions regarding cardiac center capital expenditure cycles and CMS reimbursement stability. Recalibration cycles align with material shifts in regulatory clearance timelines and robotic-assisted procedure volume thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Wearable Cardiac Devices Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
China Cardiovascular Devices Market