
 Sweden Cardiovascular Devices Market | 2026-2036
Sweden Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Cardiovascular Devices Market Analytics
Software-defined diagnostic capabilities embedded in imaging platforms is shifting how cardiovascular workflows are monetized beyond hardware sales. Medtronic leverages its integrated ecosystem of pacemakers and remote monitoring to sustain recurring revenue streams. Abbott Laboratories anchors its Swedish position through catheter-based coronary intervention portfolios. Siemens Healthineers AG differentiates via AI-augmented echocardiography systems that reduce operator dependency.
Cardiovascular devices encompass instruments, implants, and diagnostic equipment engineered to diagnose, monitor, or treat conditions of the heart and vasculature, typically manufactured from biocompatible alloys, polymers, or biological tissues under cleanroom conditions with surface finishes below 0.8 micrometers Ra to ensure hemocompatibility. Their primary commercial purpose is to restore or maintain circulatory function while minimizing procedural trauma and long-term adverse events. Drug-eluting stents command substantial margin pools due to sustained clinical preference in coronary artery disease revascularization, while transcatheter valve platforms represent the fastest-growing technology segment as Swedish centers expand structural heart programs. Bioresorbable scaffolds occupy a niche position constrained by mixed long-term trial data and selective reimbursement.
Sweden's Medical Products Agency applies the EU MDR and CE marking requirements, compelling manufacturers to maintain exhaustive clinical evidence and post-market surveillance systems. The EU F-Gas Regulation constrains sterilization process choices for device packaging, indirectly shaping supplier qualification criteria. Stakeholders must monitor how Sweden's regional health authorities reconcile centralized procurement frameworks with accelerated access to breakthrough device categories.
Market Dynamics
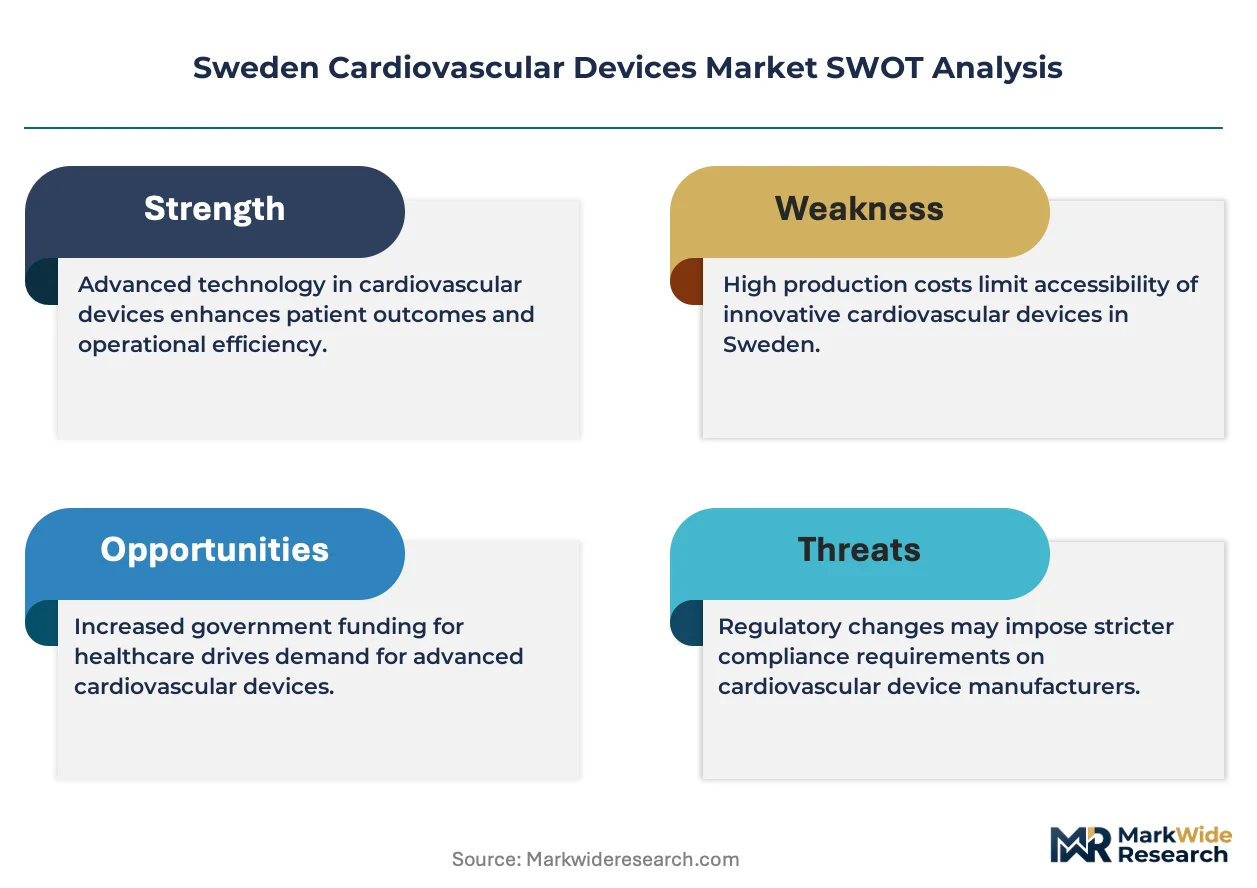
Sweden's cardiovascular device landscape is compressing around the EU MDR's expanded clinical evidence requirements, which is filtering sponsor portfolios and elevating compliance costs for market access.
Growth Catalysts
- Structural heart program expansion:Swedish university hospitals are scaling catheterization lab capacity to accommodate rising transcatheter aortic valve replacement volumes.
- EU MDR harmonization:The Medical Devices Regulation creates standardized pathways that reduce fragmentation for CE-marked device sponsors entering the Swedish market.
- Remote monitoring infrastructure:Digital health integration into cardiac implantable electronic devices is generating recurring revenue streams and patient adherence improvements.
Market Restraints
- Documentation burden escalation:The EU MDR's post-market surveillance requirements extend regulatory timelines and inflate sponsor operating costs.
- F-Gas sterilization constraints:The EU F-Gas Regulation limits packaging sterilization options, complicating supplier qualification for device manufacturers.
- Bioresorbable scaffold uncertainty:Mixed long-term trial data restricts clinical adoption and reimbursement coverage for this coronary intervention category.
Strategic Opportunities
- AI-augmented echocardiography:Machine learning integration into imaging platforms reduces operator dependency and expands diagnostic access beyond specialized centers.
- Centralized procurement leverage:Sweden's regional health authorities are consolidating purchasing power, creating volume incentives for device sponsors with integrated ecosystem offerings.
- Biocompatible polymer innovation:Advanced surface engineering below 0.8 micrometers Ra is enabling next-generation hemocompatibility for implantable devices.
Industry Challenges
- Specialized interventionalist scarcity:Structural heart procedure expansion outpaces training pipeline capacity for transcatheter valve operators.
- Legacy system integration friction:New digital diagnostic platforms face interoperability barriers with existing hospital information systems.
- CE marking timeline compression:Sponsors must synchronize clinical evidence generation with MDR transition deadlines to maintain market authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Cardiovascular Devices Market |
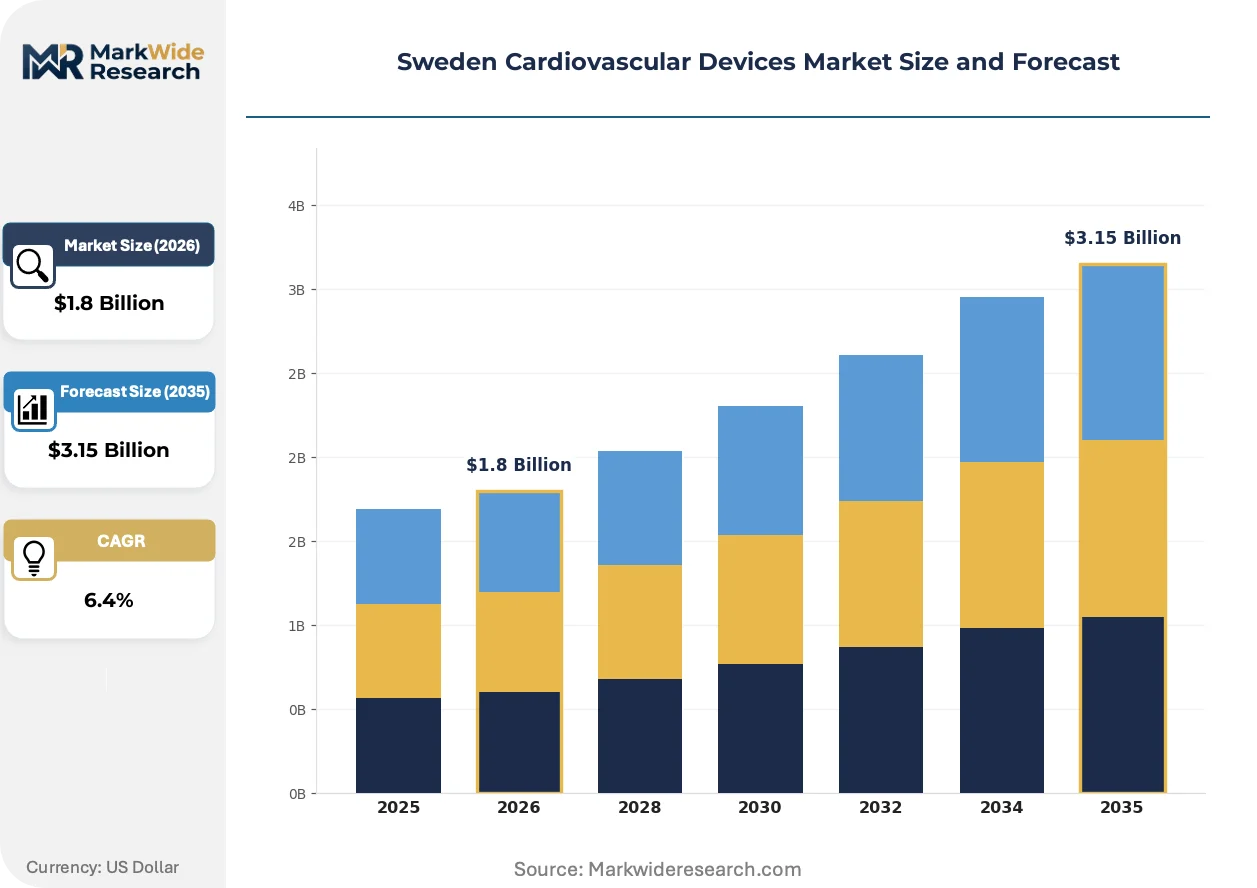
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Valves Technology: Minimally Invasive, Drug-Eluting, Bioresorbable, Transcatheter End User: Hospitals, Outpatient Clinics, Cardiology Centers, Research Institutions Application: Coronary Artery Disease, Arrhythmias, Heart Valve Disorders, Peripheral Vascular Disease |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Biotronik, Cardinal Health, Siemens Healthineers AG, GE Healthcare, Getinge AB, Occlutech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Cardiovascular Devices Market Evolving Landscape
Cardiovascular workflows in Sweden are digitizing through embedded software capabilities that monetize patient data and procedural analytics beyond hardware transactions.
Artificial intelligence is integrating into echocardiography systems to automate image acquisition and interpretation. Swedish university hospitals are deploying these platforms to reduce specialist bottlenecks in high-volume screening programs. The technology is integrating diagnostic expertise into general cardiology practice, compressing referral timelines and expanding service reach to regional centers.
The EU MDR's expanded clinical evidence requirements are reshaping sponsor investment priorities. Device manufacturers must maintain exhaustive post-market surveillance systems and periodic safety update reports. Swedish sponsors with legacy product portfolios face particular pressure to retrofit clinical documentation or withdraw non-viable registrations.
Swedish regional health authorities are consolidating procurement frameworks to extract volume discounts from device suppliers. Karolinska University Hospital's cluster purchasing power is compressing price points for coronary intervention categories while accelerating access negotiations for breakthrough structural heart technologies. This concentration is displacing fragmented hospital-level contracting across Stockholm, Skåne, and Västra Götaland regions.
Sweden Cardiovascular Devices Market Segmentation
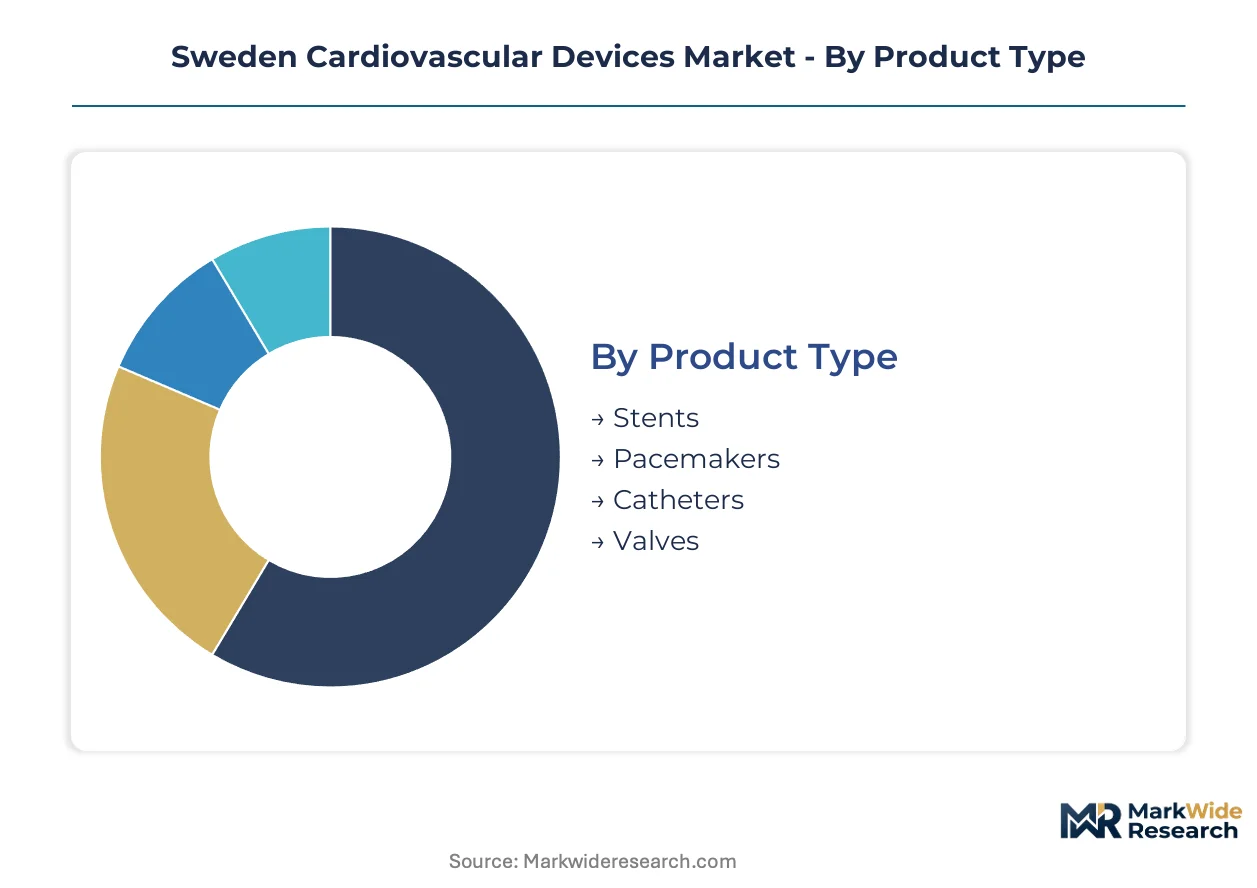
Device taxonomy in Sweden reflects how clinical workflows, reimbursement pathways, and regulatory evidence requirements intersect to shape purchasing decisions. Segmentation clarity enables sponsors to align R&D investment with the specific access barriers governing each commercial pocket.
Product Type:
Standardized implantable hardware dominates procurement volumes, while customized delivery systems command premium positioning through procedure-specific engineering.
- Stents:Metallic or polymeric scaffolds maintain vessel patency after percutaneous coronary intervention. Demand concentrates at Karolinska University Hospital and Sahlgrenska University Hospital, where high-volume PCI programs drive bulk purchasing negotiations under regional procurement frameworks.
- Pacemakers:Battery-powered pulse generators restore rhythm through transvenous or leadless configurations. Swedish cardiology centers prioritize remote monitoring integration, with Läkemedelsverket post-market surveillance requirements favoring sponsors with established digital infrastructure.
- Catheters:Flexible delivery conduits enable diagnostic and therapeutic access to cardiac and vascular structures. Stockholm's catheterization lab expansion programs absorb increasing volumes of guiding and balloon catheter systems.
- Valves:Mechanical and biological replacements address stenotic or regurgitant lesions. Transcatheter platforms are displacing surgical alternatives at university hospitals with structural heart specialization.
Leading the category by volume: Stents. Growing fastest: Valves.
Technology:
Cost tiers separate mature platforms with established reimbursement from emerging modalities requiring supplemental clinical evidence for coverage.
- Minimally Invasive:Percutaneous and transcatheter approaches reduce surgical trauma and recovery duration. Swedish regional health authorities favor these technologies for same-day discharge protocols that optimize bed utilization at university hospitals.
- Drug-Eluting:Polymer matrices release antiproliferative agents to inhibit neointimal hyperplasia. Clinical preference at Skåne University Hospital and Linköping University Hospital sustains margin pools despite generic competition.
- Bioresorbable:Temporary scaffolds dissolve after vessel remodeling, eliminating permanent foreign material. Mixed long-term trial data restricts adoption to selective indications within research-intensive centers.
- Transcatheter:Delivery systems enable valve replacement and repair without sternotomy. Structural heart program expansion across Västra Götaland and Stockholm regions is accelerating volume growth for this modality.
Commanding highest average selling prices: Transcatheter. Expanding most quickly: Minimally Invasive.
End User:
Customer type determines purchasing authority complexity, from centralized regional procurement to institutional research budgets with distinct compliance obligations.
- Hospitals:Acute care facilities perform emergency and scheduled cardiovascular procedures. Sweden's seven university hospitals anchor device consumption through high-complexity intervention volumes and training program requirements.
- Outpatient Clinics:Ambulatory settings manage stable patients and diagnostic workups. Diagnostic catheter and monitoring device demand is rising as regional authorities shift stable coronary disease management away from inpatient settings.
- Cardiology Centers:Specialized facilities focus on electrophysiology and interventional procedures. These centers drive pacemaker and implantable cardioverter-defibrillator volumes through dedicated device clinics.
- Research Institutions:Academic medical centers conduct clinical trials and technology assessments. Karolinska Institutet-affiliated hospitals generate first-adoption demand for breakthrough device categories requiring CE marking under EU MDR.
Capturing largest procurement volumes: Hospitals. Gaining share fastest: Outpatient Clinics.
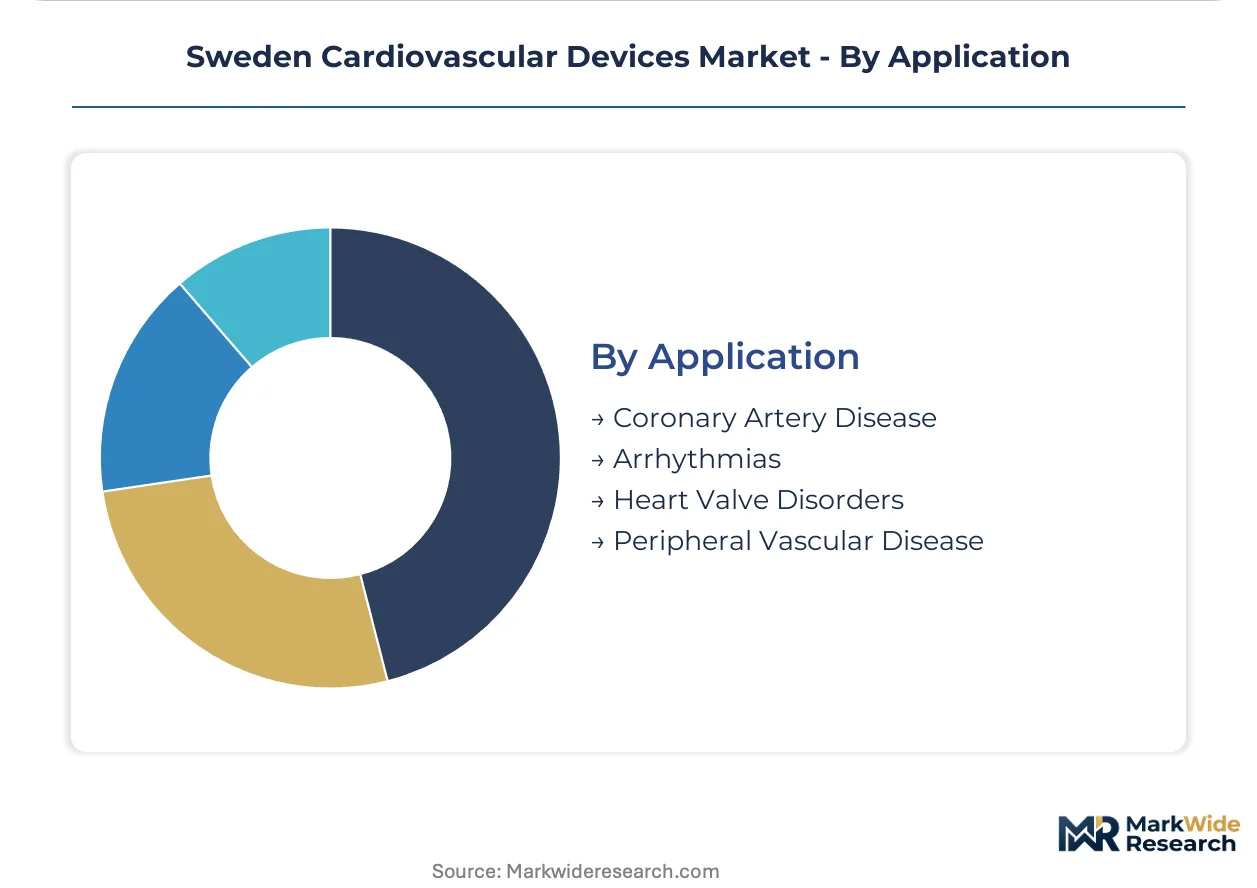
Application:
Maturity gradients separate well-established intervention pathways with standardized protocols from emerging indications requiring operator training infrastructure.
- Coronary Artery Disease:Atherosclerotic narrowing of epicardial vessels requiring revascularization. Stent and catheter demand remains concentrated at interventional cardiology hubs with 24/7 primary PCI capability.
- Arrhythmias:Electrical conduction disorders managed through ablation or device implantation. Electrophysiology procedure growth at Uppsala University Hospital and Lund University Hospital sustains pacemaker and mapping system consumption.
- Heart Valve Disorders:Structural abnormalities of native or prosthetic valves. Transcatheter aortic valve replacement volumes are climbing fastest at centers with multidisciplinary heart team structures.
- Peripheral Vascular Disease:Arterial insufficiency affecting non-coronary territories. Lower extremity intervention volumes are expanding as vascular surgery and interventional cardiology service lines merge at regional hospitals.
Generating highest procedure counts: Coronary Artery Disease. Climbing the fastest: Heart Valve Disorders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden imports the majority of its cardiovascular device consumption while domestic production concentrates in Gothenburg's medical technology corridor. Manufacturing capacity remains limited to specialized components and sterilization services rather than finished implantable systems.
Stockholm County
Karolinska University Hospital performs the highest per-capita volume of transcatheter aortic valve implantations in Sweden. The Medical Products Agency enforces EU MDR compliance through rigorous post-market surveillance audits. Solna's hospital cluster drives procurement negotiations that compress price points for coronary intervention devices across the entire region.
Västra Götaland
Sahlgrenska University Hospital anchors structural heart program expansion with dedicated catheterization lab capacity increases. The EU F-Gas Regulation constrains sterilization process choices for device packaging at Gothenburg-based suppliers. MedTech West innovation hub connects academic researchers with commercial sponsors seeking CE marking pathway optimization.
Skåne
Skåne University Hospital sustains substantial drug-eluting stent volumes through high-volume PCI programs. Regional health authorities apply centralized procurement frameworks that extract volume discounts from device manufacturers. Lund University Hospital's electrophysiology service generates pacemaker and ICD demand through specialized device clinics.
Uppsala
Uppsala University Hospital drives arrhythmia management procedure growth with expanded ablation capabilities. Läkemedelsverket maintains regional inspection offices that monitor compliance with periodic safety update report requirements. Akademiska Sjukhuset serves as a training pipeline for interventional cardiologists addressing specialized operator scarcity.
Sweden Cardiovascular Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Sweden's cardiovascular device procurement channels. The market structure consolidates around multinational sponsors with established CE marking portfolios and integrated digital ecosystems. Three archetypes dominate: diversified medical technology conglomerates with full cardiovascular portfolios, specialized interventional device manufacturers with catheter-based expertise, and diagnostic imaging platform vendors with AI-augmented capabilities. Strategic moves center on ecosystem integration to capture recurring revenue streams and regional procurement consolidation to defend volume positions.
Within the diversified conglomerate tier, Medtronic and Abbott Laboratories occupy positions defined by integrated hardware-software ecosystems spanning implantable devices through remote monitoring infrastructure. Boston Scientific Corporation exemplifies the interventional specialization archetype with catheter-based coronary and structural heart portfolios. Siemens Healthineers AG anchors the diagnostic imaging vector, representing AI-augmented echocardiography capabilities that reduce operator dependency in Swedish screening programs.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Biotronik |
| Cardinal Health |
| Siemens Healthineers AG |
| GE Healthcare |
| Getinge AB |
| Occlutech |
| Others |
Value Network & Pricing Analysis
Regional health authority consolidation across Stockholm, Skåne, and Västra Götaland concentrates purchasing power into a handful of procurement frameworks that enforce contract-based long-term offtake pricing with volume-scaled discounts.
Pricing Analysis
Margin tightening in coronary intervention categories reflects Karolinska University Hospital's cluster purchasing power compressing price points for drug-eluting stents and guiding catheters. Three-tier pricing structure across premium, standard, and economy levels separates transcatheter valve platforms with CE MDR full certification from legacy devices and research-only configurations. Cost-down pressure on implantable pulse generators accelerates because regional authorities bundle remote monitoring subscriptions into hardware negotiations. Academic medical centers show lowest price sensitivity due to research budget flexibility, while county hospitals face strict reimbursement ceilings.
Supply Chain Analysis
Biocompatible alloy supply rests on German specialty metallurgy producers and Swiss precision component manufacturers for surface finishes below 0.8 micrometers Ra. Nitinol wire, platinum-iridium electrodes, and medical-grade silicone elastomers constitute critical input dependencies. Single-source vulnerability concentrates in catheter shaft extrusion capabilities, where limited European qualified suppliers constrain alternative sourcing. Distribution runs through centralized regional warehouse networks before hospital-level consignment stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's cardiovascular device sector is consolidating around backward integration into sterilization services and captive supply of biocompatible polymers as sponsors seek margin defense against procurement compression.
For Market Incumbents: Deploy remote monitoring infrastructure as a recurring revenue lever to offset hardware price erosion from regional procurement frameworks. Deepen backward integration into packaging sterilization to circumvent EU F-Gas Regulation constraints on ethylene oxide alternatives. Anchor ecosystem stickiness through Läkemedelsverket-compliant post-market surveillance systems that raise switching costs for hospital customers. For New Entrants and Emerging Players: Launch via research institution partnerships targeting first-adoption demand at Karolinska Institutet-affiliated hospitals for breakthrough structural heart categories. Exploit specialized interventionalist scarcity by developing simplified delivery systems that reduce training burden for transcatheter valve operators. Position AI-augmented echocardiography platforms toward outpatient clinic expansion as regional authorities shift stable coronary disease management away from inpatient settings. For Investors and Strategic Acquirers: The window for entry favors device sponsors with established CE MDR technical documentation and periodic safety update report capabilities. Long-term viability hinges on capturing positions before EU MDR transition deadlines filter legacy product portfolios. Monitor Läkemedelsverket post-market surveillance audit frequency as an inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements filter sponsor portfolios and elevate market access barriers. |
| Hospital System Partnership | Karolinska University Hospital cluster purchasing power compresses price points across coronary intervention categories. |
| Software Companion Development | Remote monitoring integration generates recurring revenue streams beyond hardware transactions. |
| Reimbursement Strategy | Regional health authority consolidation demands value demonstration for breakthrough structural heart technologies. |
| Backward Integration | Captive sterilization capacity circumvents EU F-Gas Regulation constraints on packaging process choices. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with Läkemedelsverket device registrations, EU MDR notified body certificates, and regional procurement databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Data-stream reconciliation across implantable device registries, catheterization lab utilization reports, and reimbursement claim patterns informed the analytical framework. Segmentation dimensions modeled include product type, technology modality, end-user facility category, and clinical application across the projection horizon. CAGRs derived from trend extrapolation of structural heart program expansion rates and coronary intervention volume growth, with sensitivity testing against EU MDR transition timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for bioresorbable scaffolds would alter the outlook if long-term trial data shifts clinical preference. Forecasts reflect assumptions regarding regional procurement consolidation pace and specialized operator training pipeline capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market