
 Atherosclerotic Renovascular Treatment Market | 2026-2036
Atherosclerotic Renovascular Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Atherosclerotic Renovascular Treatment Market Analytics
European stent manufacturing is consolidating as producers scale precision laser-cutting capacity for renal artery platforms. Abbott leverages integrated catheter-stent workflows to sustain leadership in endovascular renal interventions. Medtronic anchors its position through chronic investment in balloon-expandable stent R&D. Boston Scientific differentiates via specialized drug-eluting platforms designed for small-vessel renal anatomy.
Atherosclerotic renovascular treatment encompasses endovascular and surgical interventions to restore perfusion in renal arteries narrowed by plaque accumulation, typically employing balloon angioplasty with metallic or drug-eluting stent placement to maintain luminal patency above 80 percent. The primary purpose is to preserve renal function, control resistant hypertension, and prevent ischemic nephropathy progression in patients with hemodynamically significant stenosis. Stent product lines command the dominant margin pool due to premium pricing on drug-eluting and bare-metal platforms, while balloon catheter segments experience faster volume expansion as predilation protocols standardize across interventional cardiology and nephrology departments. Endovascular delivery modes lead procedure volumes globally, though hybrid surgical-endovascular approaches capture complex anatomical cases with juxtarenal aortic involvement.
FDA maintains stringent premarket approval pathways for renal artery stents under cardiovascular device regulations, while EMA's Medical Device Regulation imposes enhanced clinical evidence requirements for Class III implantable devices. The EPA and OSHA frameworks govern sterilization facility emissions and worker exposure limits during nitinol stent manufacturing. Stakeholders must monitor evolving CMS national coverage determinations and parallel European HTA assessments that directly dictate hospital procurement budgets for renal revascularization programs.
Market Dynamics
Renal denervation catheter systems are converging with traditional stenting workflows, forcing interventionalists to retrain on dual-modality protocols while hospital administrators recalibrate capital equipment budgets. This technological overlay is compressing procedure times but expanding training overhead across cardiology and nephrology departments.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited review timelines for renal denervation systems compress regulatory lag, accelerating commercial availability of next-generation endovascular platforms.
- Medicare Coverage Determinations:National coverage decisions for renal artery stenting in the United States directly unlock hospital reimbursement pathways, shaping procurement priorities for interventional suites.
- Laser-Cutting Precision:Advances in femtosecond laser manufacturing enable thinner stent struts for tortuous renal anatomy, expanding treatable patient populations previously excluded from endovascular intervention.
Market Restraints
- Nitinol Price Volatility:Raw material cost swings for nickel-titanium alloys constrain margin predictability for bare-metal stent producers dependent on consistent feedstock pricing.
- EMA MDR Compliance Burden:Enhanced clinical evidence requirements for Class III implantable devices extend approval timelines and inflate trial costs for European market entry.
- Best Medical Therapy Substitution:Aggressive pharmaceutical management of renovascular hypertension with ACE inhibitors and ARBs delays or displaces interventional referrals in asymptomatic stenosis cases.
Strategic Opportunities
- Hybrid Surgical-Endovascular Protocols:Juxtarenal aortic cases requiring combined open and catheter-based approaches represent underserved territory for specialized training centers and device bundling.
- India Interventional Nephrology Expansion:Private hospital chains in Mumbai and Delhi are building dedicated renovascular programs, creating first-mover advantage for stent manufacturers establishing local clinical education infrastructure.
- AI-Enabled Fluoroscopy:Machine learning algorithms for real-time vessel sizing and stent positioning are converging with robotic catheter systems, enabling remote proctoring and standardized outcomes across low-volume centers.
Industry Challenges
- Interventional Nephrology Workforce Gap:Fellowship programs produce insufficient operators trained in both diagnostic angiography and endovascular intervention, creating bottlenecks for program expansion.
- Dual Certification Complexity:Stent systems require parallel FDA premarket approval and CMS national coverage determination processes, extending commercialization timelines and inflating regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atherosclerotic Renovascular Treatment Market |
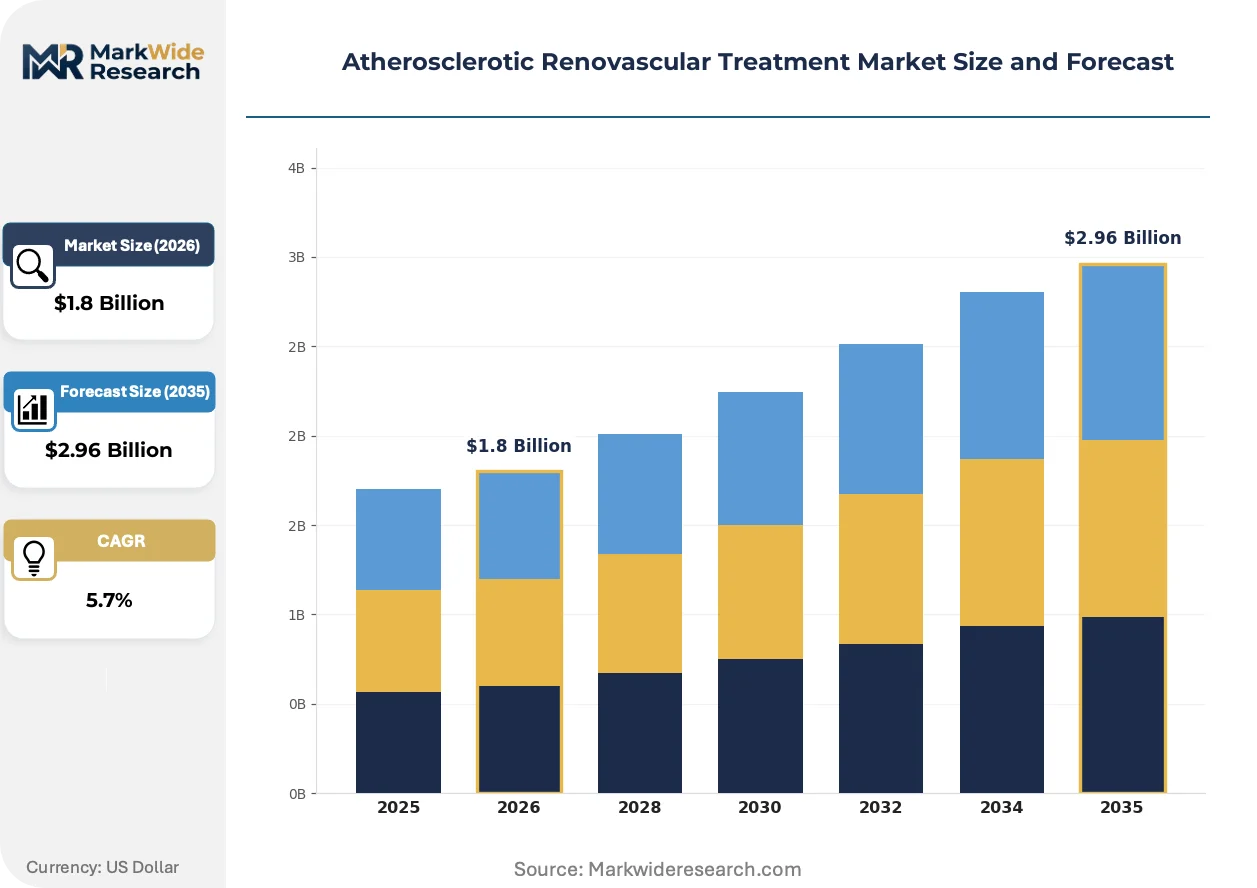
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Balloons, Catheters, Vascular Grafts Therapy Area: Cardiology, Nephrology, Interventional Radiology, Surgery End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Rehabilitation Centers Delivery Mode: Endovascular, Percutaneous, Surgical, Hybrid |
| Companies Covered | Abbott, Medtronic, Boston Scientific, Getinge, Artivion, LeMaitre Vascular, W. L. Gore & Associates, Terumo, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atherosclerotic Renovascular Treatment Market Evolving Landscape
Endovascular device architectures are fragmenting into procedure-specific platforms rather than universal systems, compelling manufacturers to optimize for renal artery tortuosity and calcification patterns distinct from coronary or peripheral anatomy.
Drug-eluting stent technology is converging with biodegradable polymer coatings to reduce late thrombotic events in small-vessel renal applications. Interventional cardiologists in high-volume United States centers are adopting these platforms faster than nephrologists, creating training asymmetries within hospital systems. This adoption gap is compressing market share for bare-metal alternatives while expanding specialist certification requirements.
EMA's Medical Device Regulation imposes post-market surveillance mandates that force stent manufacturers to maintain active implant registries tracking long-term patency outcomes. Industrial consequence includes mandatory investment in clinical affairs infrastructure and data analytics capabilities. European hospital procurement committees now weight registry participation heavily in tender evaluations, favoring established players with compliant traceability systems.
Hospital buying committees are consolidating vendor relationships through single-source contracts for renal intervention portfolios, displacing the previous multi-supplier model. Integrated catheter-stent-balloon bundles from dominant manufacturers are capturing preference over best-of-breed component selection. This concentration is most visible in United States health systems where GPO-negotiated pricing and standardization mandates reduce clinical autonomy in device selection.
Atherosclerotic Renovascular Treatment Market Segmentation
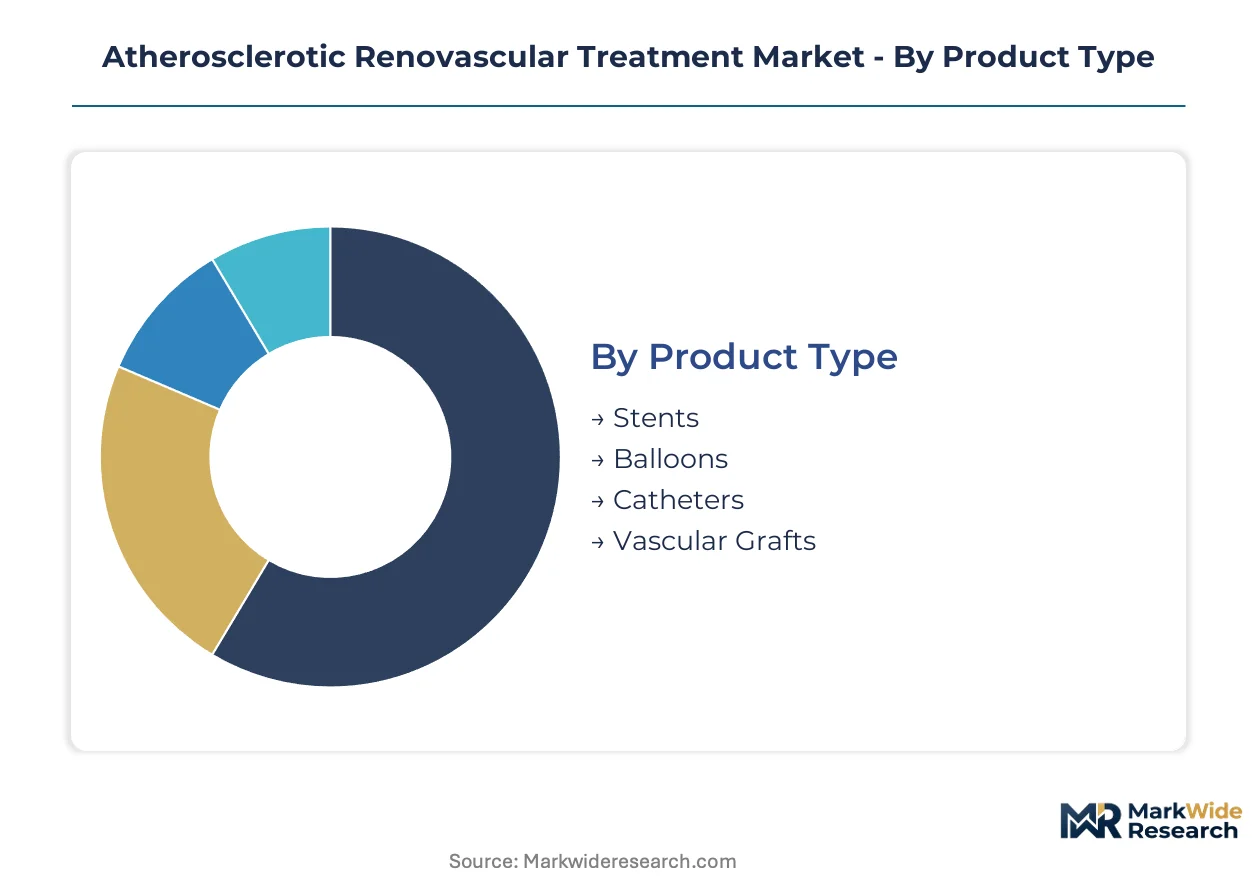
Renal revascularization markets fragment across intervention modality, physician specialty, and care setting, each dimension carrying distinct reimbursement codes and capital requirements that shape vendor portfolio strategy and hospital procurement decisions.
Product Type:
Integration depth varies sharply across implantable hardware, with standalone delivery systems commanding premium positioning versus consumable components embedded within broader procedure workflows.
- Stents:Metallic and drug-eluting platforms feature laser-cut nitinol or cobalt-chromium architectures optimized for renal artery tortuosity. United States hospital systems concentrate demand for drug-eluting variants as Medicare coverage determinations favor patency-proven technologies over bare-metal alternatives.
- Balloons:Semi-compliant and non-compliant dilatation catheters enable predilation protocols that standardize across interventional cardiology suites. Volume expansion accelerates in ambulatory surgery centers where cost containment pressures favor single-use balloon economics over permanent implant expenditures.
- Catheters:Guiding and diagnostic catheters with hydrophilic coatings navigate challenging renal artery takeoff angles.
- Vascular Grafts:Polyester and ePTFE conduits address complex juxtarenal reconstructions requiring open surgical exposure.
Stents lead volumes today; balloons are gaining share fastest.
Therapy Area:
Cost tier stratification emerges across specialties, with cardiology departments absorbing capital equipment burdens while nephrology programs rely on shared catheterization lab access.
- Cardiology:Interventional cardiologists perform the majority of renal artery stenting procedures in high-volume United States centers, leveraging existing coronary angiography infrastructure and established relationships with device manufacturers.
- Nephrology:Interventional nephrology represents an emerging specialty with dedicated fellowship training programs expanding across academic medical centers in the United States.
- Interventional Radiology:Radiologists historically dominated diagnostic angiography and maintain procedural presence in smaller community hospitals without dedicated interventional cardiology programs.
- Surgery:Vascular surgeons retain control over hybrid and open surgical cases involving aortic reconstruction or failed endovascular interventions.
Cardiology leads volumes today; nephrology is expanding most quickly.
End User:
Customer type determines purchasing authority structure, with integrated delivery networks centralizing procurement versus independent specialty clinics retaining physician-driven device selection.
- Hospitals:Academic medical centers and community hospitals house the majority of renal revascularization programs, with catheterization lab availability and on-site surgical backup determining case complexity thresholds.
- Ambulatory Surgery Centers:Freestanding endovascular facilities in the United States pursue selective renal artery stenting cases under streamlined reimbursement frameworks.
- Specialty Clinics:Nephrology-focused practices in urban United States markets develop dedicated renovascular hypertension management pathways.
- Rehabilitation Centers:Post-acute facilities manage blood pressure optimization following successful revascularization procedures.
Hospitals lead volumes today; ambulatory surgery centers are climbing the fastest.
Delivery Mode:
Maturity gradients separate established endovascular protocols from emerging hybrid techniques requiring cross-specialty coordination and combined capital investment.
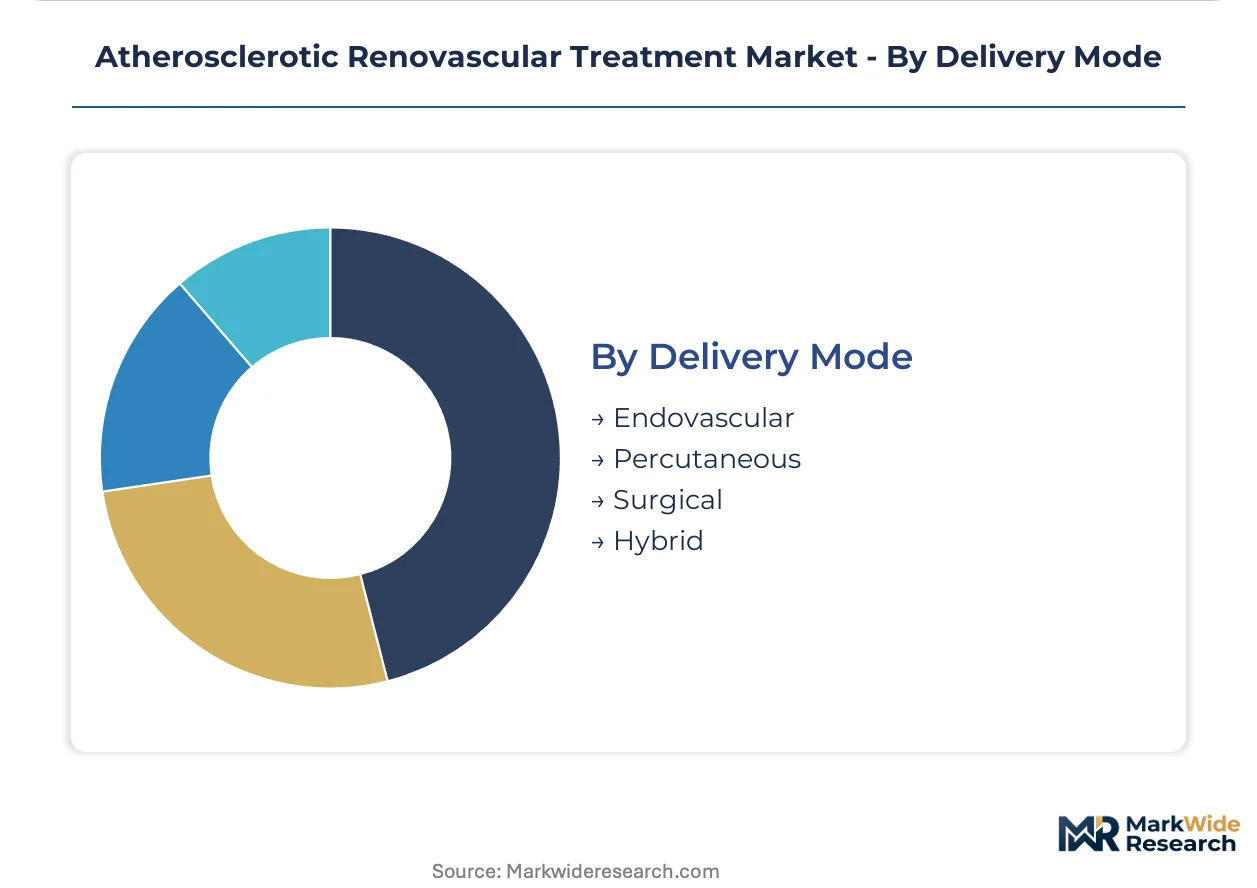
- Endovascular:Transfemoral and transradial catheter-based approaches constitute the dominant procedural methodology, with stent deployment completing balloon angioplasty in a single session.
- Percutaneous:Minimally invasive access techniques reduce recovery time compared to open surgical approaches.
- Surgical:Open renal artery bypass and endarterectomy persist for anatomically unfavorable lesions or endovascular failures.
- Hybrid:Combined open and endovascular protocols address juxtarenal aortic disease requiring simultaneous aortic and renal intervention.
Endovascular leads volumes today; hybrid approaches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers of renal intervention devices are migrating production toward jurisdictions with streamlined medical device approval pathways and favorable reimbursement frameworks. The United States maintains the highest procedure volumes but imposes stringent FDA premarket approval requirements that inflate compliance costs. European producers face elevated clinical evidence burdens under EMA's Medical Device Regulation, prompting some to relocate precision manufacturing to lower-cost regulatory environments.
United States
Hospital systems in Cleveland, Houston, and Minneapolis operate the highest-volume interventional nephrology programs, driving concentrated demand for drug-eluting renal stents. CMS national coverage determinations for renal artery stenting directly shape procurement budgets across integrated delivery networks. The FDA's breakthrough device pathway for renal denervation systems is accelerating commercial timelines for next-generation endovascular platforms in academic medical centers.
Germany
Baden-Württemberg hosts precision laser-cutting facilities supplying nitinol stent architectures to European and Asian markets. EMA MDR compliance requirements for Class III implantable devices extend approval timelines, favoring established manufacturers with existing clinical data portfolios. The country's statutory health insurance system maintains selective coverage for renal revascularization, restricting procedure growth to symptomatic hemodynamic stenosis cases.
Japan
PMDA approval pathways for renal artery devices emphasize long-term patency data, creating lag times versus US and European market entry. Tokyo and Osaka academic hospitals anchor the Asia-Pacific training infrastructure for interventional nephrology fellowship programs. METI industrial policy supports domestic stent manufacturing through targeted R&D subsidies for precision metalworking technologies.
India
Private hospital chains in Mumbai and Delhi are constructing dedicated renovascular hypertension management centers with imported catheterization equipment. CDSCO medical device regulations are converging toward international harmonization, reducing entry barriers for multinational stent manufacturers. Domestic producers in Gujarat and Karnataka are developing bare-metal stent capabilities to serve price-sensitive tier-two and tier-three city markets.
Switzerland
Swissmedic maintains accelerated review pathways for devices with prior FDA or EMA approval, positioning Basel and Zurich as European commercialization hubs. The country's precision engineering clusters supply femtosecond laser systems for stent strut manufacturing to global device producers. Swiss hospital procurement committees emphasize total cost-of-ownership metrics, favoring drug-eluting platforms with demonstrated patency durability over initial price considerations.
Atherosclerotic Renovascular Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue renal denervation and hybrid surgical platforms as differentiation vectors. The vendor structure concentrates around integrated catheter-stent-balloon portfolios, with hospital buying committees consolidating toward single-source contracts. Three archetypes dominate: diversified cardiovascular conglomerates with full renal intervention suites; specialized vascular device manufacturers with niche stent technologies; and emerging renal denervation specialists converging on hypertension management workflows. Competitive dynamics center on M&A activity to acquire laser-cutting manufacturing capabilities and strategic partnerships with academic medical centers for clinical trial infrastructure.
Among diversified cardiovascular conglomerates, Abbott, Medtronic, and Boston Scientific exemplify the integrated portfolio approach. Abbott occupies a position representing catheter-stent workflow integration. Medtronic anchors the scale-driven tier through chronic investment positioning in balloon-expandable platforms. Boston Scientific sits within the specialization vector for small-vessel renal anatomy applications. These three entities collectively represent the competitive archetype that hospital procurement committees favor under single-source contracting mandates.
| Leading Market Players |
|---|
| Abbott |
| Medtronic |
| Boston Scientific |
| Getinge |
| Artivion |
| LeMaitre Vascular |
| W. L. Gore & Associates |
| Terumo |
| Philips |
| Others |
Value Network & Pricing Analysis
Backward integration into nitinol feedstock production anchors pricing power for established stent manufacturers while insulating margins from nickel-titanium alloy spot market swings. Hospital procurement committees in the United States exploit this concentration by demanding bundled catheter-stent-balloon contracts that compress distributor margins.
Pricing Analysis
Distributor margin compression runs through the renal intervention supply chain as integrated manufacturers bypass wholesale channels to serve hospital GPOs directly. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy balloon-only tiers segments buyers by patency requirements and capital constraints. Pricing pressure stems from CMS national coverage determinations that restrict reimbursement to hemodynamically proven stenosis cases. Ambulatory surgery centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while academic medical centers prioritize patency-proven platforms regardless of premium.
Supply Chain Analysis
Nitinol wire supply rests on precision metallurgy facilities in Germany, Switzerland, and the United States that control femtosecond laser-cutting capacity for renal artery stent architectures. Cobalt-chromium alloy feedstock and hydrophilic polymer coatings constitute secondary input dependencies. Single-source vulnerability concentrates in European laser-system manufacturers subject to EMA MDR compliance delays. Distribution runs through manufacturer-direct hospital contracts and GPO-negotiated frameworks that displace independent medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atherosclerotic renovascular treatment market compounds steadily as aging demographics expand the addressable population with resistant hypertension and declining renal function.
For Market Incumbents: Anchor market position through captive nitinol feedstock arrangements and precision laser-cutting facility expansion in Baden-Württemberg or Swiss engineering clusters. Defend against renal denervation substitution by accelerating drug-eluting stent patency data generation for CMS coverage determinations. Prioritize interventional nephrology fellowship sponsorships to secure operator loyalty ahead of device selection standardization.
For New Entrants and Emerging Players: Capture white-space in hybrid surgical-endovascular protocols for juxtarenal aortic disease requiring combined open and catheter-based reconstruction. Target private hospital chains in Mumbai and Delhi building dedicated renovascular programs without established vendor relationships. Pursue CDSCO regulatory harmonization pathways to serve price-sensitive tier-two Indian cities with bare-metal stent platforms.
For Investors and Strategic Acquirers: Roll-up economics work for specialized vascular device manufacturers because hospital buying committees are consolidating toward single-source renal intervention portfolios. Five-to-ten year viability hinges on regulatory data moats and active implant registry participation under EMA post-market surveillance mandates. Watch FDA breakthrough device designations for renal denervation systems as the signal for endovascular therapy approval acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited renal denervation approvals compress commercialization timelines for next-generation platforms. |
| Hospital System Partnership | Single-source catheter-stent-balloon contracts secure preferred vendor status across integrated delivery networks. |
| CE Marking Pathway | EMA MDR compliance for Class III devices enables European market access amid heightened clinical evidence requirements. |
| Reimbursement Strategy | CMS national coverage determination alignment unlocks Medicare payment pathways for renal artery stenting procedures. |
| Software Companion Development | AI-enabled fluoroscopy integration with robotic catheter systems standardizes outcomes across low-volume centers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, interventional nephrologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers with secondary validation against FDA premarket approval filings, CMS national coverage determination records, EMA MDR submission databases, and hospital procurement contract repositories. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Segment-weighting across product type, therapy area, end user, and delivery mode dimensions shaped the analytical framework over the projection horizon. CAGRs derived from procedure volume trajectories and average selling price trends by segment. Forecast inputs incorporated Medicare coverage policy scenarios, EMA MDR implementation timelines, and interventional nephrology fellowship expansion rates.
Regulatory approval delays, reimbursement restriction expansions, and best medical therapy substitution advances are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions subject to these vectors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market