
 Cardiac Implantable Electronic Device Market | 2026-2036
Cardiac Implantable Electronic Device Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Implantable Electronic Device Market Analysis
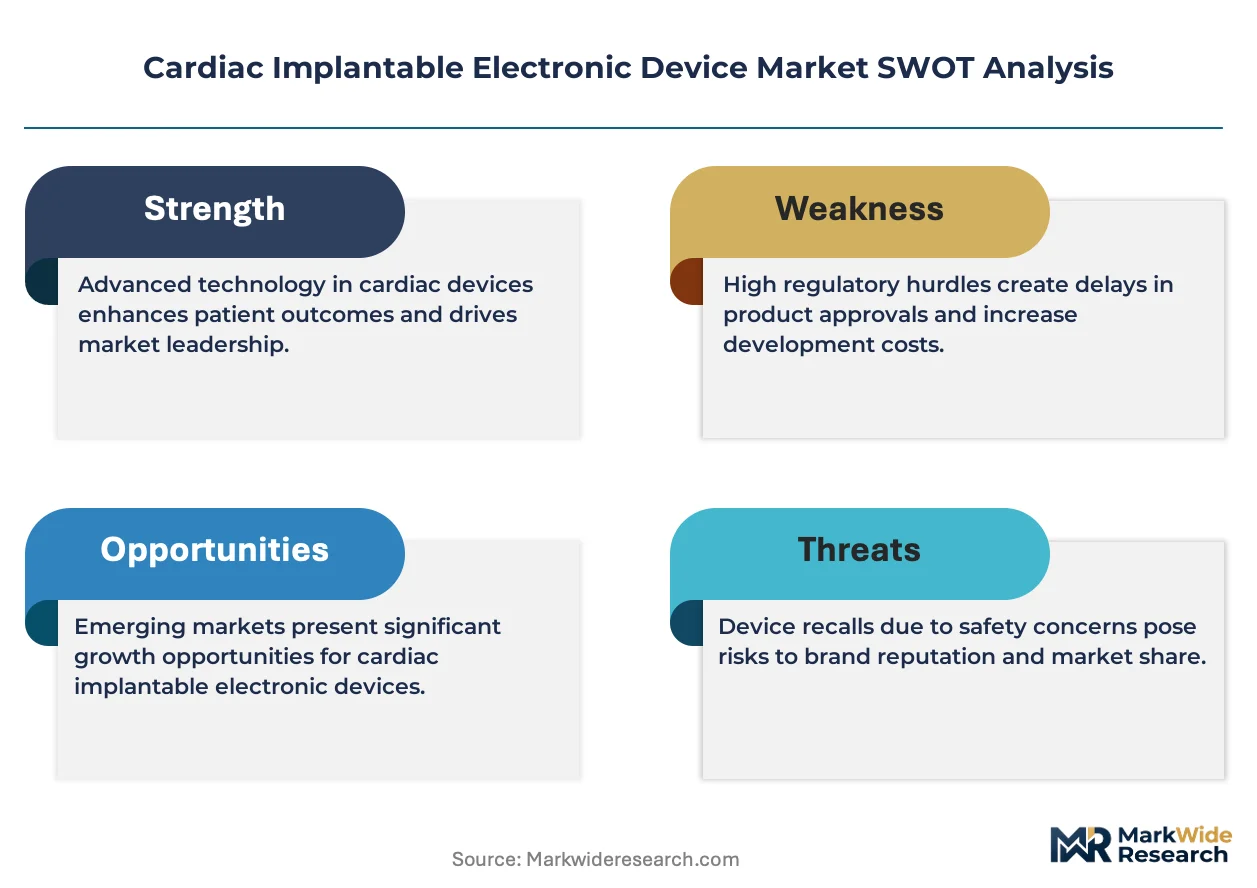
Biocompatible polymer coatings are broadening the performance envelope of cardiac implantable electronic devices by reducing fibrotic encapsulation and extending functional longevity. Medtronic plc leverages its integrated manufacturing infrastructure to sustain cost advantages across pacemaker and defibrillator portfolios. Abbott Laboratories anchors its competitive stance through specialization in leadless pacing systems, while Boston Scientific Corporation differentiates via wireless remote monitoring platforms that reduce in-clinic follow-up burdens.
Cardiac implantable electronic devices comprise battery-powered systems surgically placed to monitor, regulate, or restore cardiac rhythm through electrical impulse delivery, typically incorporating lithium-iodine cells with operational lifespans exceeding ten years and hermetic titanium enclosures rated for biocompatibility per ISO 14708. Their primary purpose is to reduce mortality and morbidity associated with bradyarrhythmias, tachyarrhythmias, and heart failure progression. Implantable cardioverter defibrillators command the largest revenue share among product types due to premium pricing and complex engineering requirements, whereas remote monitoring technology within the technology dimension is expanding fastest as healthcare systems prioritize post-implant surveillance efficiency and early complication detection. Heart rhythm disorders anchor application-side demand, though heart failure management is gaining procedural share with cardiac resynchronization therapy integration.
The FDA enforces Class III premarket approval standards that mandate extensive clinical trials for novel cardiac implantable electronic devices, while the EU MDR requires updated technical documentation and post-market clinical follow-up that extends time-to-certification. Japan's PMDA maintains distinct pharmaceutical and medical device agency review pathways that influence multinational launch sequencing. Stakeholders must monitor how evolving cybersecurity guidance from FDA and harmonized IEC 60601-1-2 electromagnetic compatibility standards reshape development priorities and geographic market entry timing.
Market Dynamics
Leadless pacing technology is compressing procedural complexity and redefing hospital resource allocation across cardiac rhythm management, while cybersecurity mandates from FDA and EU MDR are forcing hardware architecture redesigns that extend development timelines.
Growth Catalysts
- Aging demographics in Japan and Germany:Expanding patient pools eligible for implantable cardioverter defibrillators and cardiac resynchronization therapy devices drive procedural volume expansion in reimbursed healthcare systems.
- Remote monitoring infrastructure:Wireless telemetry integration enables real-time arrhythmia detection and reduces emergency department utilization, creating pull-through demand for device upgrades.
- EU MDR post-market clinical follow-up requirements:Stricter surveillance mandates accelerate replacement cycles for legacy devices lacking comprehensive longitudinal data portfolios.
Market Restraints
- Lithium-iodine cell supply concentration:Dependence on specialized battery chemistry from limited suppliers creates vulnerability to raw material price volatility and single-source risk.
- FDA Class III premarket approval timelines:Extensive clinical trial requirements for novel leadless systems extend capital lock-up periods and compress investor return horizons.
- Transcatheter pacing substitution:Minimally invasive catheter ablation techniques for atrial fibrillation reduce addressable patient populations for certain device categories.
Strategic Opportunities
- Underpenetrated Indian market:Low implantation rates relative to disease burden present expansion potential as CDSCO streamlines medical device registration pathways.
- Home-based monitoring convergence:Integration of implantable data streams with consumer wearable ecosystems creates new service revenue models beyond hardware sales.
- Japan PMDA Sakigake designation:Expedited review pathway for breakthrough devices accelerates time-to-market for AI-enabled diagnostic algorithms embedded in next-generation systems.
Industry Challenges
- Electrophysiologist training pipeline:Specialized procedural expertise required for leadless implantation creates bottlenecks that constrain volume scaling despite device availability.
- Legacy system interoperability:Proprietary communication protocols between manufacturer-specific devices and hospital IT infrastructure complicate multi-vendor environments.
- Hermetic sealing certification delays:ISO 14708 biocompatibility validation and titanium enclosure integrity testing extend quality assurance cycles before commercial release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Implantable Electronic Device Market |
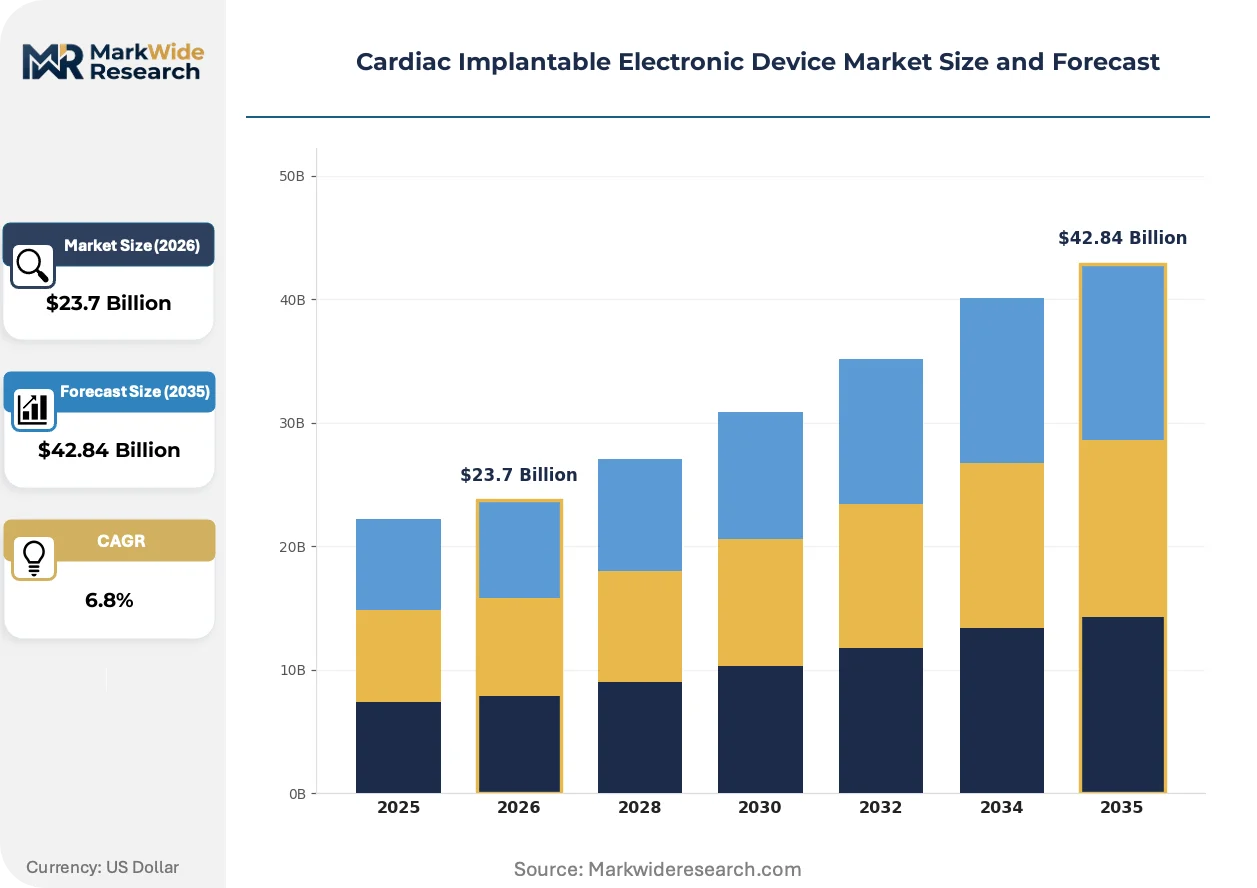
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Implantable Cardioverter Defibrillators, Cardiac Monitors, Lead Systems End User: Hospitals, Cardiac Clinics, Home Healthcare, Research Institutions Technology: Active Implantable Devices, Biocompatible Materials, Wireless Communication, Remote Monitoring Application: Heart Rhythm Disorders, Heart Failure Management, Post-MI Care, Preventive Cardiology |
| Companies Covered | BIOTRONIK SE & Co. KG, Lepu Medical Technology, Medtronic plc, Osypka AG, MicroPort Scientific Corporation, Abbott Laboratories, LivaNova PLC, Oscor Inc., Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Implantable Electronic Device Market Emerging Trajectories
Artificial intelligence integration is transforming how cardiac implantable electronic devices process rhythm data and deliver therapeutic responses. Three interconnected developments are reshaping competitive positioning and R&D investment allocation.
Machine learning algorithms embedded directly on device hardware are automating real-time arrhythmia classification and reducing false-positive shock delivery. Hospitals in the United States and Germany are prioritizing these systems to minimize inappropriate therapy and associated patient trauma. The technology is automating clinical decision support that previously required specialist interpretation, compressing response latency from minutes to milliseconds.
EU MDR cybersecurity annex requirements and FDA premarket guidance on device software assurance are mandating end-to-end encryption and secure boot architectures for all network-connected cardiac devices. Manufacturers must now embed hardware security modules and over-the-air patch capabilities that were previously optional features. Implantable cardioverter defibrillators with wireless connectivity face the steepest compliance burden, driving consolidation among smaller players lacking dedicated security engineering teams.
Hospital purchasing cooperatives are consolidating procurement authority and demanding standardized data interoperability across vendor platforms. This buyer concentration is displacing traditional single-source contracts and forcing manufacturers to adopt IEEE 11073 and HL7 FHIR communication standards. The shift is most visible in United States integrated delivery networks, where chief medical information officers now hold veto power over device selection based on EHR integration capabilities.
Cardiac Implantable Electronic Device Market Segmentation
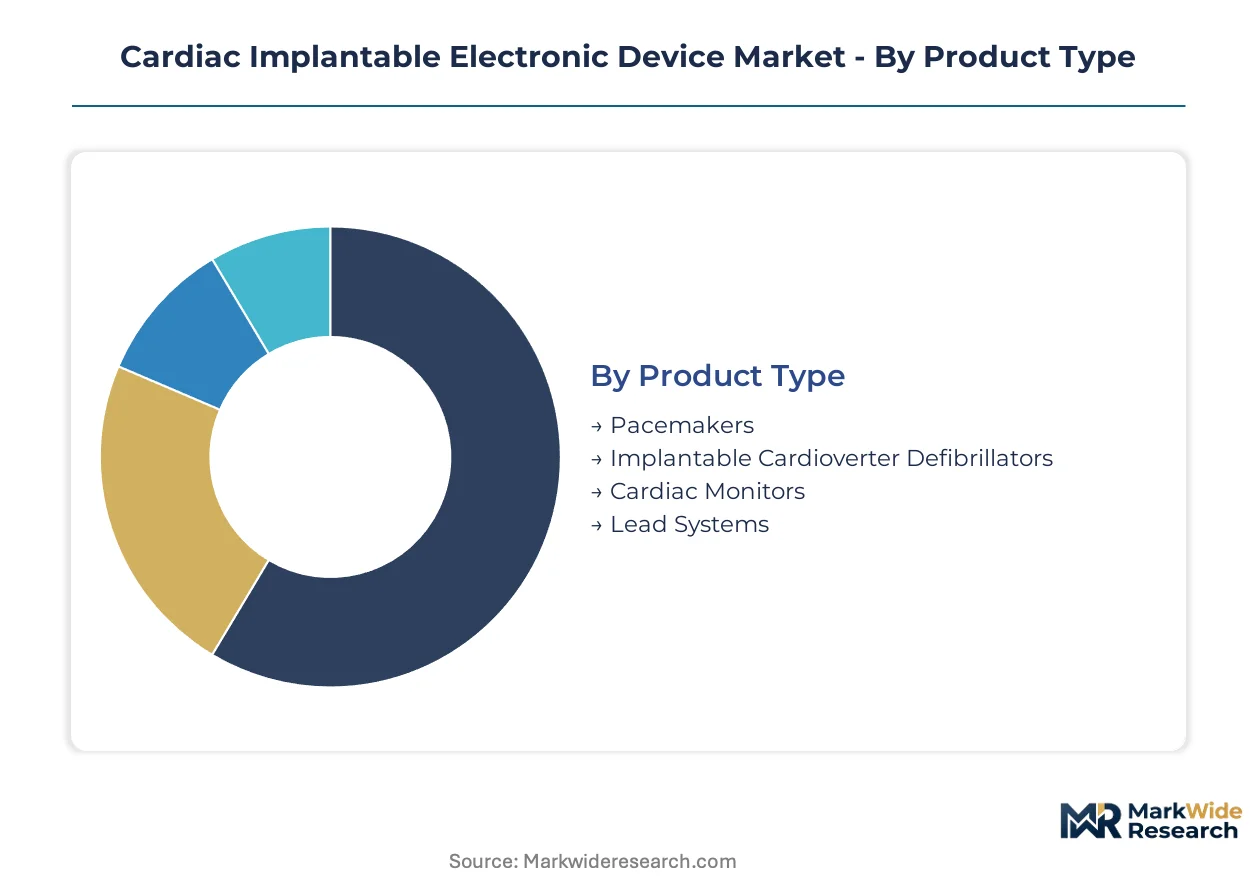
Segmentation in cardiac implantable electronic devices reveals how capital allocation, reimbursement pathways, and procedural expertise concentrate demand across distinct product configurations and care settings. Understanding these partitions illuminates where manufacturers must prioritize R&D investment and which customer segments warrant dedicated commercial resources.
Product Type:
Capital intensity varies sharply across this category, with implantable cardioverter defibrillators demanding the most substantial upfront manufacturing infrastructure due to high-voltage capacitor engineering and hermetic sealing requirements.
- Implantable Cardioverter Defibrillators:These devices incorporate high-energy capacitors delivering 25-40 joule shocks alongside bradycardia pacing functions. United States hospital systems absorb the majority of unit volume, driven by CMS reimbursement codes that cover device costs and implantation procedures under DRG 222.
- Pacemakers:Single-chamber, dual-chamber, and biventricular configurations regulate bradycardia through lithium-iodine cell-powered pulse generators. German statutory health insurance funds drive procedural volume through standardized G-DRG reimbursement frameworks that incentivize timely intervention.
- Cardiac Monitors:Insertable loop recorders capture subcutaneous ECG data for cryptogenic stroke evaluation.
- Lead Systems:Transvenous, epicardial, and leadless pacing conductors deliver electrical impulses to myocardial tissue.
Implantable cardioverter defibrillators absorb the bulk of installed capacity; lead systems are expanding most quickly as leadless pacing technology compresses procedural complexity.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks in the United States consolidating purchasing power for hospital-based implantation while cardiac clinics operate on more fragmented acquisition models.
- Hospitals:Tertiary cardiac centers maintain electrophysiology laboratories with fluoroscopy, mapping systems, and surgical backup for device implantation and extraction. Japan's university hospitals anchor procedural volume through PMDA-designated advanced medical care reimbursement tiers.
- Cardiac Clinics:Outpatient electrophysiology practices perform generator replacements and device interrogations with lower fixed-cost structures.
- Home Healthcare:Remote monitoring infrastructure enables post-implant surveillance without clinic visits.
- Research Institutions:Academic medical centers conduct pivotal clinical trials for FDA premarket approval submissions.
Hospitals command the dominant share of implantation volume; home healthcare is climbing the fastest as wireless telemetry reduces in-person follow-up requirements.
Technology:
Margin profiles diverge across technology layers, with wireless communication modules capturing premium pricing due to cybersecurity certification burdens and software validation requirements.
- Remote Monitoring:Cloud-connected platforms transmit device diagnostics and arrhythmia alerts to clinician dashboards, enabling early intervention before acute decompensation. United States integrated delivery networks prioritize these systems to reduce emergency department utilization and associated capitation penalties.
- Active Implantable Devices:Battery-powered pulse generators with hermetic titanium enclosures deliver therapeutic electrical impulses.
- Biocompatible Materials:Polymer coatings and steroid-eluting electrodes reduce fibrotic encapsulation and capture threshold elevation.
- Wireless Communication:Bluetooth Low Energy and proprietary radiofrequency protocols enable device-programmer connectivity.
Active implantable devices represent the largest installed base; remote monitoring is gaining share fastest as healthcare systems prioritize post-implant surveillance efficiency.
Application:
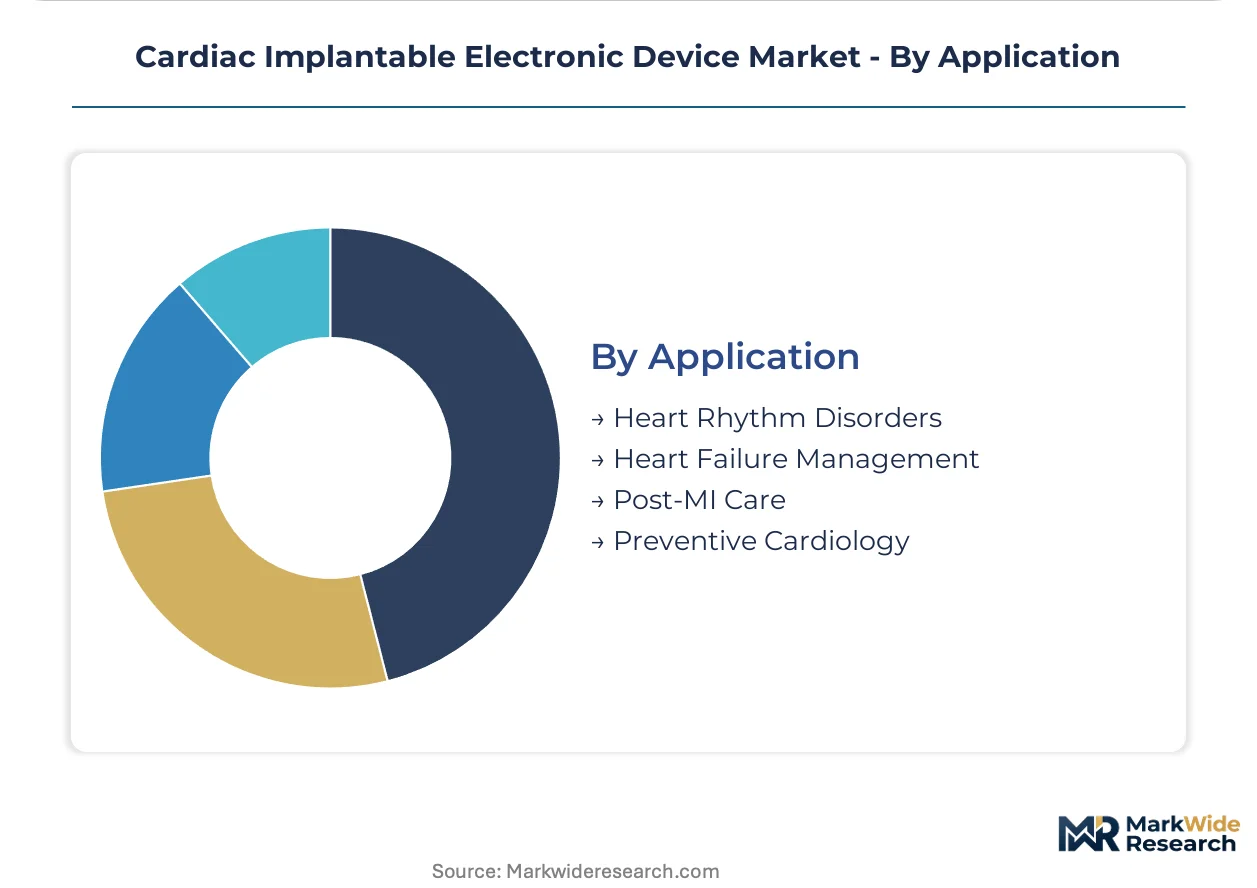
Patient risk stratification and reimbursement eligibility create distinct addressable populations across clinical indications, with heart failure management requiring the most complex device configurations.
- Heart Failure Management:Cardiac resynchronization therapy devices coordinate biventricular pacing to improve ejection fraction and reduce hospitalization frequency. German heart failure networks drive adoption through DMP (Disease Management Program) incentives that reward guideline-directed therapy implementation.
- Heart Rhythm Disorders:Bradyarrhythmia and tachyarrhythmia indications encompass the majority of implantable device procedures.
- Post-MI Care:Sudden cardiac death prevention drives prophylactic defibrillator implantation following myocardial infarction.
- Preventive Cardiology:Subcutaneous monitors and wearable patches detect subclinical arrhythmias in high-risk populations.
Heart rhythm disorders anchor the largest procedural volume; heart failure management is expanding most quickly as CRT-D penetration rises in systolic dysfunction populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cardiac implantable electronic devices concentrates in three major markets where aging demographics intersect with established reimbursement frameworks. Procedural volumes in these countries dwarf those in emerging economies, creating distinct competitive dynamics and regulatory entry barriers for manufacturers.
United States
CMS reimbursement codes covering device costs and implantation procedures under DRG 222 sustain procedural volume across tertiary cardiac centers. The FDA enforces Class III premarket approval standards that mandate extensive clinical trials for novel systems. Integrated delivery networks in the Northeast Corridor and California consolidate purchasing authority and demand standardized data interoperability across vendor platforms.
Germany
Statutory health insurance funds drive pacemaker procedural volume through standardized G-DRG reimbursement frameworks that incentivize timely intervention. The EU MDR requires updated technical documentation and post-market clinical follow-up that extends time-to-certification for manufacturers. Bavaria and Baden-Württemberg host university hospitals that anchor procedural volume through specialized electrophysiology laboratories.
Japan
University hospitals anchor device implantation volume through PMDA-designated advanced medical care reimbursement tiers. The PMDA maintains distinct pharmaceutical and medical device agency review pathways that influence multinational launch sequencing. The Kanto region surrounding Tokyo concentrates the majority of electrophysiologist training programs and high-volume implantation centers.
India
Low implantation rates relative to disease burden present expansion potential as CDSCO streamlines medical device registration pathways. The country's national pharmaceutical regulator is harmonizing standards with international norms to accelerate market entry for multinational manufacturers. Maharashtra and Karnataka host emerging cardiac care clusters where private hospital chains are investing in electrophysiology infrastructure.
Cardiac Implantable Electronic Device Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers expand across pacemaker, defibrillator, and cardiac monitor categories to capture comprehensive patient episodes. The vendor base organizes into three tiers: integrated multinationals with full rhythm management portfolios, mid-cap specialists concentrated in leadless pacing or remote monitoring, and regional manufacturers serving price-sensitive emerging markets. Two strategic archetypes define competitive positioning: vertically integrated players controlling battery cell supply and lithium-iodine chemistry, and software-centric firms prioritizing wireless telemetry and cybersecurity certification. M&A activity and technology licensing agreements represent the dominant competitive moves, with smaller players seeking access to security engineering capabilities and established manufacturers acquiring AI-enabled diagnostic algorithms.
Within the integrated multinational tier, Medtronic plc and Abbott Laboratories exemplify divergent strategic postures. Medtronic leverages integrated manufacturing infrastructure across its device portfolios, while Abbott anchors its position through specialization in leadless pacing systems. Boston Scientific Corporation occupies a distinct position emphasizing wireless remote monitoring platforms. Among European-based manufacturers, BIOTRONIK SE & Co. KG represents the specialist archetype with concentrated expertise in cardiac rhythm management.
| Leading Market Players |
|---|
| BIOTRONIK SE & Co. KG |
| Lepu Medical Technology |
| Medtronic plc |
| Osypka AG |
| MicroPort Scientific Corporation |
| Abbott Laboratories |
| LivaNova PLC |
| Oscor Inc. |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Leadless versus transvenous system divergence manifests in sharply divergent cost structures and supply chain footprints across cardiac implantable electronic devices. Premium leadless platforms command substantial markups due to concentrated manufacturing expertise and specialized lithium-iodine cell sourcing, while conventional transvenous systems compete on scale economies from established production lines.
Pricing Analysis
Volume concentrates in mid-tier dual-chamber pacemakers while margins pool in implantable cardioverter defibrillators and leadless pacing systems. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Class III certification burden and wireless telemetry integration depth. Pricing pressure stems from integrated delivery network procurement consolidation in the United States, with GPOs extracting volume discounts that compress manufacturer margins. Hospital systems exhibit lowest price sensitivity for cybersecurity-certified remote monitoring bundles, while emerging market distributors demonstrate acute sensitivity to generator unit costs.
Supply Chain Analysis
Electrophysiologist training bottlenecks in Germany and Japan constrain final assembly workforce availability despite robust component manufacturing. Lithium-iodine cell production centers on the United States and Switzerland, hermetic titanium enclosure forging concentrates in Germany, and final device assembly distributes across Ireland and Costa Rica. Raw material flows draw from tantalum capacitors, medical-grade titanium billet, and specialized polymer coatings. Single-source vulnerability in high-voltage capacitor supply creates exposure to semiconductor foundry allocation constraints. Distribution runs through hospital purchasing cooperatives and specialized cardiac device distributors with field clinical engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cybersecurity-certified platforms, with EU MDR and FDA software assurance mandates forcing subscale players toward exit or acquisition.
For Market Incumbents: Deepen backward integration into lithium-iodine cell chemistry to secure supply continuity against raw material volatility. Expand captive security engineering capabilities to meet FDA premarket guidance on device software assurance without external dependency. Leadless pacing substitution and transcatheter ablation advancement threaten procedural volume for conventional transvenous systems; defend through remote monitoring platform stickiness and EHR integration depth. For New Entrants and Emerging Players: Begin with cardiac monitor and insertable loop recorder segments where regulatory pathways compress time-to-revenue and capital requirements moderate. India's underpenetrated implantation market offers the most penetrable geography as CDSCO streamlines medical device registration. Partner with established distributors possessing field clinical engineering infrastructure rather than building direct sales organizations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated multinationals seeking AI-enabled diagnostic algorithms and cybersecurity engineering teams. Long-term viability favors platforms with demonstrated EU MDR certification and FDA premarket approval track records across multiple device generations. Watch for inflection in hospital purchasing cooperative contract consolidation velocity as signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Class III designation mandates extensive clinical trials that lock up capital and extend development timelines. |
| CE Marking Pathway | EU MDR technical documentation and post-market clinical follow-up requirements reshape certification economics. |
| Hospital System Partnership | Integrated delivery network procurement consolidation demands EHR interoperability and standardized data exchange. |
| Software Companion Development | AI-enabled diagnostic algorithms embedded on device hardware automate arrhythmia classification and reduce false-positive therapy. |
| Reimbursement Strategy | CMS DRG 222 coverage in the United States and G-DRG frameworks in Germany sustain procedural volume and device pull-through. |
Methodological Framework
Document review covered FDA premarket approval filings, EU MDR technical documentation databases, and hospital procurement contract records, complemented by interviews with electrophysiologists, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary sources included CMS Medicare claims data, PMDA review pathway documentation, and ISO 14708 certification registries. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue disclosures.
Segmentation-level outputs across product type, end user, technology, and application dimensions were generated through the projection horizon. CAGRs were derived from patient population epidemiology, reimbursement code valuation trends, and replacement cycle dynamics. Forecast inputs incorporated electrophysiologist training pipeline constraints, lithium-iodine cell supply concentration, and cybersecurity compliance burden evolution.
Underlying measurement precision varies by segment; implantable cardioverter defibrillator and pacemaker volumes carry tighter precision than emerging leadless pacing categories due to established reporting infrastructure. Forecasts reflect assumptions regarding regulatory pathway stability, reimbursement code maintenance, and raw material supply continuity. Material deviation in FDA cybersecurity guidance stringency or EU MDR post-market surveillance enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market