
 Global Aortic Valve Market | 2026-2036
Global Aortic Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aortic Valve Market Foresight
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape between established incumbents and emerging transcatheter specialists. Edwards Lifesciences dominates transcatheter valve innovation through sustained R&D intensity across its SAPIEN platform franchise. Medtronic anchors mechanical valve supply chains through backward integration into titanium forging and pyrolytic carbon coating operations. Abbott Laboratories differentiates via specialized annuloplasty repair technologies that complement its replacement portfolio.
An aortic valve is a semilunar cardiac structure comprising three leaflets that regulate unidirectional blood flow from the left ventricle into the systemic circulation, typically fabricated from bovine pericardium, porcine tissue, or pyrolytic carbon-coated mechanical alloys depending on replacement modality. Transcatheter valves capture the fastest expansion trajectory as minimally invasive delivery systems displace conventional sternotomy procedures in operable-risk patient cohorts. Bioprosthetic tissue valves command premium positioning in elderly populations where anticoagulation contraindications elevate demand for durable biological solutions. Mechanical valves retain cost-efficient penetration in younger patients with adequate warfarin monitoring access.
FDA premarket approval pathways and the EU MDR clinical evaluation requirements shape trial design burdens and market access timelines for novel valve platforms. Japan's PMDA maintains distinct pharmacovigilance reporting standards that extend post-approval surveillance obligations for transcatheter devices. Stakeholders must monitor evolving real-world evidence mandates from China's NMPA as that regulator expands its acceptance of overseas clinical data for imported cardiovascular implants.
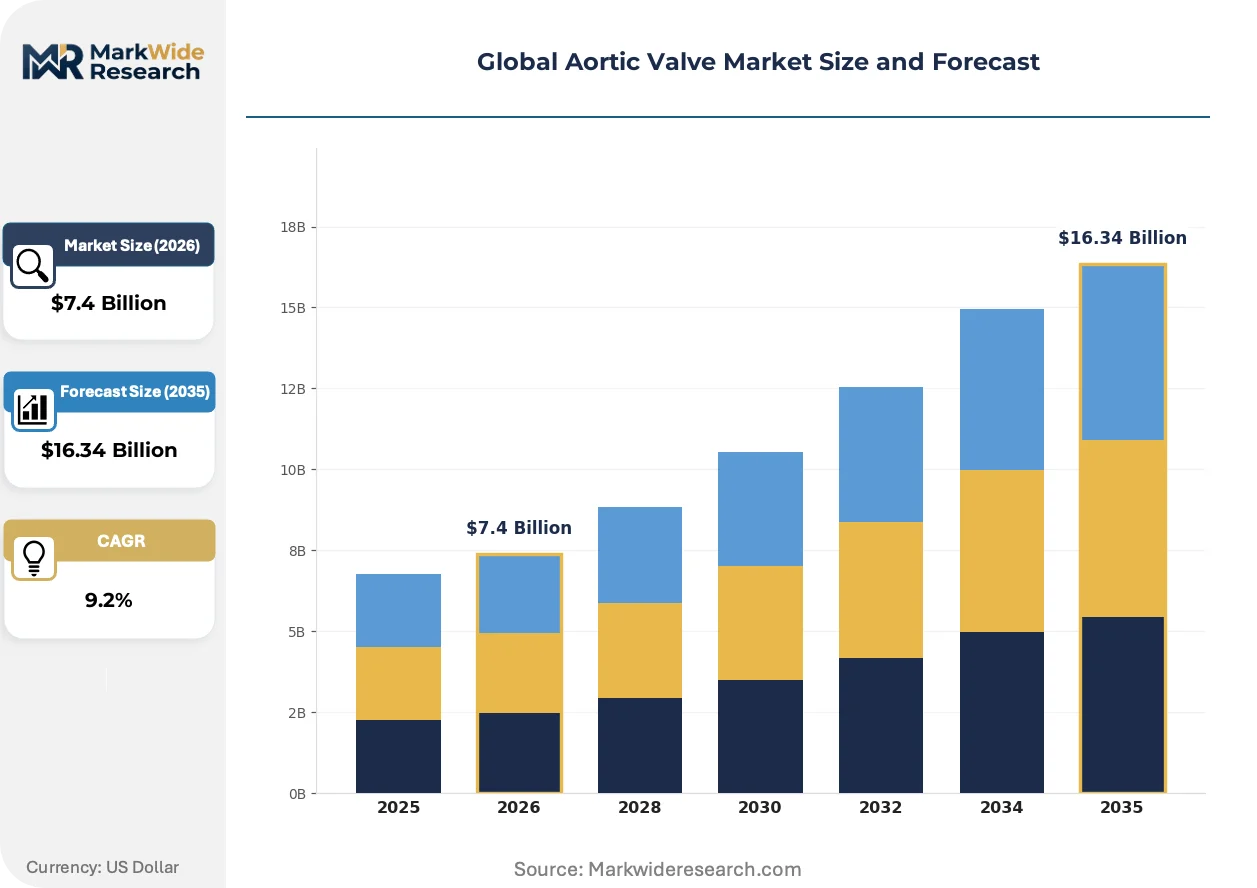
Market Dynamics
Transcatheter delivery systems are compressing procedural recovery timelines and redistributing surgical volume from specialized cardiac centers toward general interventional suites, fundamentally restructuring referral patterns and capital allocation across cardiovascular service lines.
Growth Catalysts
- Aging demographics in Japan and Germany:Populations over 75 years are expanding surgical candidacy for tissue valves while anticoagulation intolerance elevates bioprosthetic preference over mechanical alternatives.
- FDA breakthrough device designation:Accelerated review pathways for next-generation transcatheter platforms compress premarket timelines and reduce trial cost burdens for novel delivery mechanisms.
- Polymer leaflet materials:Synthetic tissue engineering eliminates xenograft sourcing constraints and enables standardized manufacturing scalability beyond bovine pericardium supply limitations.
Market Restraints
- Pyrolytic carbon supply concentration:Mechanical valve production depends on three specialized coating facilities in the United States and Germany, creating single-source vulnerability for hemocompatible surfaces.
- EU MDR clinical evaluation requirements:Extended post-market surveillance obligations and notified body capacity constraints delay CE marking timelines by 18-24 months versus prior Medical Device Directive pathways.
- Structural valve deterioration:Bioprosthetic tissue valves exhibit calcification and leaflet tearing within 10-15 years, forcing reintervention costs that mechanical alternatives avoid.
Strategic Opportunities
- China's NMPA overseas data acceptance:Regulator expansion of imported cardiovascular implant approvals using foreign clinical evidence reduces redundant trial requirements for established platforms.
- Convergence of imaging and robotics:Intra-procedural CT-fluoroscopy fusion with robotic catheter navigation enables precise valve positioning in anatomically complex cases previously excluded from transcatheter candidacy.
- Direct-to-hospital distribution:Manufacturers bypass distributor markups by establishing consignment inventory agreements with high-volume cardiac centers, capturing margin previously allocated to intermediaries.
Industry Challenges
- Interventional cardiologist training pipelines:Transcatheter procedure complexity requires 200+ supervised cases for competency certification, constraining deployable specialist supply against procedural demand expansion.
- Notified body MDR transition bottlenecks:Limited designated bodies under EU Medical Device Regulation extend technical documentation review queues, delaying market access for iterative product modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aortic Valve Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $16.34 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Valves, Bioprosthetic Valves, Transcatheter Valves, Homograft Valves Material: Titanium, Cobalt-Chromium, Porcine Tissue, Bovine Pericardium, Polymers Application: Severe Aortic Stenosis, Aortic Regurgitation, Congenital Valve Defects, Valve Replacements End User: Cardiovascular Surgery Centers, Specialty Heart Clinics, Multispecialty Hospitals, Ambulatory Surgical Centers |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic, Abbott Laboratories, Boston Scientific Corporation, LivaNova PLC, Artivion, CryoLife, JenaValve Technology, Venus MedTech HangZhou, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aortic Valve Market Shifts & Advancements
Device miniaturization and computational modeling are converging to enable transcatheter interventions in younger, lower-risk patient cohorts previously reserved for surgical valve replacement, compressing the addressable patient boundary between modalities.
Self-expanding nitinol frame technology is miniaturizing delivery system profiles from 14-French to sub-10-French sheaths, enabling transfemoral access in patients with peripheral vascular disease previously requiring transapical or transaortic approaches. Community hospitals without on-site cardiac surgery backup are adopting these lower-profile systems for standalone transcatheter programs. The structural consequence is miniaturizing the minimum facility infrastructure required for valve replacement, dispersing procedural volume from academic medical centers toward regional hospitals.
CE marking under EU Medical Device Regulation now mandates annual safety update reports and proactive post-market clinical follow-up studies for Class III implantable devices, elevating ongoing evidence generation costs beyond premarket trial expenditures. Manufacturers must maintain dedicated regulatory affairs teams for periodic safety reporting rather than episodic submission management. Transcatheter valve portfolios face the most acute compliance burden given their rapid iteration cycles and expanding indication claims.
Hospital purchasing committees are consolidating supplier contracts around full cardiovascular portfolio relationships rather than single-product negotiations, bundling valve procurement with structural heart imaging systems and catheter accessories. Device manufacturers respond by integrating annuloplasty rings, closure devices, and delivery systems under unified contract terms. This concentration is most visible in United States integrated delivery networks where procurement centralization across 10-50 hospital systems compresses vendor diversity to three-to-four strategic partnerships per network.
Global Aortic Valve Market Segmentation
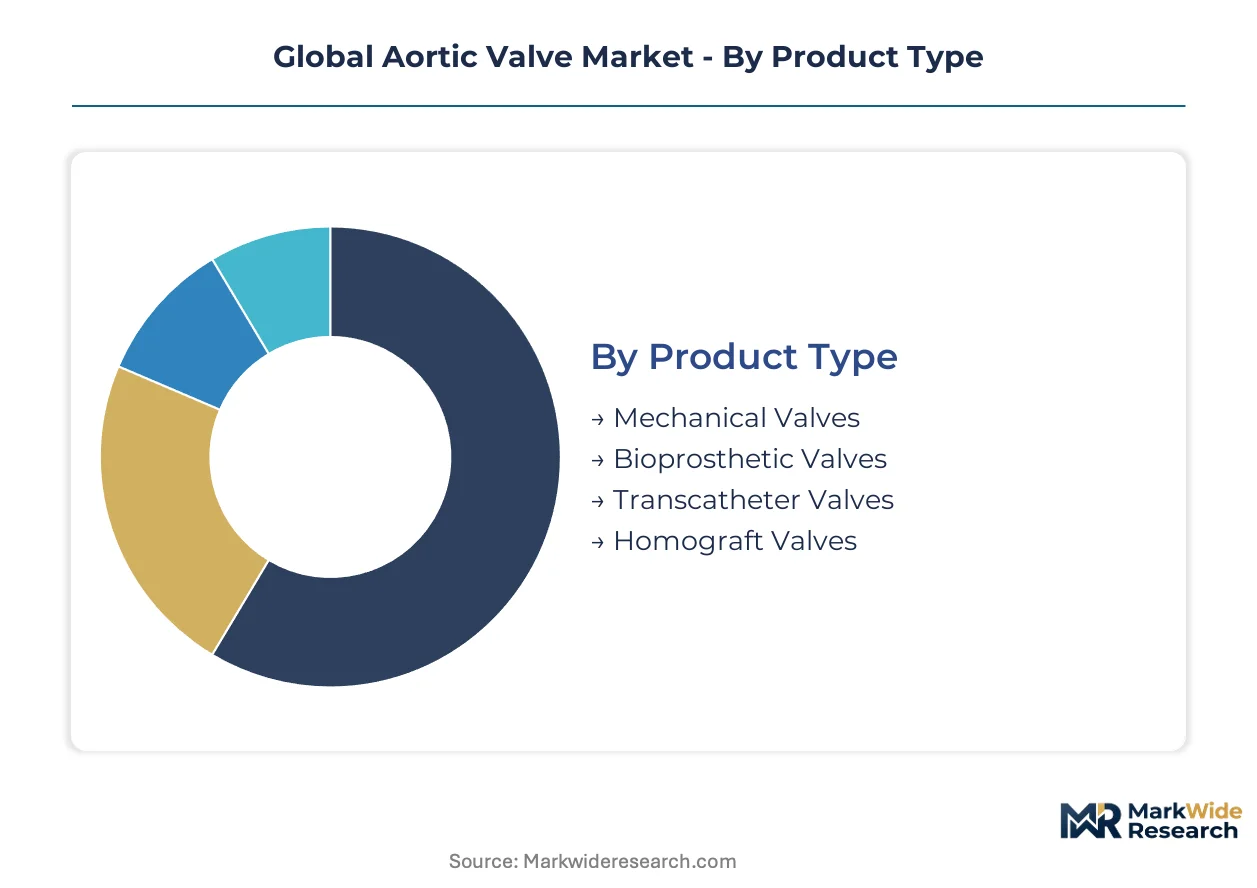
Aortic valve segmentation reveals divergent substitution pressures across modalities, with transcatheter platforms displacing surgical alternatives in operable-risk cohorts while mechanical valves defend cost-sensitive younger patients. Material sourcing constraints and end-user infrastructure requirements further stratify competitive positioning across the value chain.
Product Type:
Substitution pressure intensifies most acutely between transcatheter delivery systems and conventional surgical valves, as minimally invasive access redefines patient candidacy boundaries.
- Mechanical Valves:Pyrolytic carbon-coated tilting disc or bileaflet designs deliver lifetime durability exceeding 30 years. Demand concentrates in India and Brazil where younger patient demographics and limited anticoagulation monitoring infrastructure elevate cost efficiency over biocompatibility concerns.
- Bioprosthetic Valves:Chemically treated porcine aortic roots or bovine pericardial leaflets mounted on polymer or metal stents eliminate chronic anticoagulation requirements. German and Japanese cardiovascular surgery centers drive procurement volume as populations over 75 years expand surgical candidacy for tissue-based solutions.
- Transcatheter Valves:Self-expanding nitinol or balloon-expandable cobalt-chromium frames with tissue leaflets enable transfemoral deployment without sternotomy.
- Homograft Valves:Cryopreserved human donor aortic roots provide infection-resistant reconstruction for endocarditis cases.
Mechanical valves retain volume leadership in emerging markets; transcatheter platforms hold the steepest expansion curve.
Material:
Cost tier stratification separates premium biological tissues from standardized mechanical alloys, with synthetic polymers emerging as a manufacturing scalability bridge.
- Titanium:Biocompatible, non-ferromagnetic base metal for mechanical valve housings and sewing rings. Indian and Chinese orthopedic-forging suppliers are backward integrating into cardiovascular-grade titanium billet production.
- Cobalt-Chromium:High-strength alloy for balloon-expandable transcatheter frames requiring radial fatigue resistance. German precision metalworking clusters supply thin-walled tubing to Edwards Lifesciences and Medtronic stent platforms.
- Porcine Tissue:Aortic root xenografts from specific-pathogen-free herds provide native leaflet geometry. Brazilian and Argentine slaughterhouse supply chains face sustainability scrutiny from EU MDR sourcing documentation requirements.
- Bovine Pericardium:Cross-linked collagen sheets dominate bioprosthetic leaflet fabrication. Australian and New Zealand cattle herds supply over 60 percent of pharmaceutical-grade pericardium to global valve manufacturers.
- Polymers:Polyurethane and polycarbonate urethane leaflets enable synthetic valve platforms bypassing xenograft supply constraints.
Bovine pericardium commands premium positioning in tissue valves; polymer materials are climbing the fastest toward commercial scale.
Application:
Patient severity and anatomical complexity determine procedural modality selection, with congenital defects representing the most specialized surgical subset.
- Severe Aortic Stenosis:Calcific leaflet obstruction requiring flow restoration. United States integrated delivery networks now approve transcatheter intervention for low-risk patients, eroding the surgical boundary.
- Aortic Regurgitation:Incompetent leaflet coaptation permitting diastolic backflow. Transcatheter devices face technical limitations in non-calcified annuli, preserving surgical valve replacement volume in this indication.
- Congenital Valve Defects:Bicuspid aortic valve or other developmental anomalies requiring reconstruction. Pediatric cardiac centers in Boston, London, and Melbourne maintain specialized homograft and Ross procedure programs.
- Valve Replacements:Redo interventions following primary bioprosthetic failure. Japanese PMDA pharmacovigilance databases track structural valve deterioration patterns to inform reintervention timing.
Severe aortic stenosis anchors procedural volume; valve replacements for prior bioprosthetic failure show the steepest expansion trajectory.
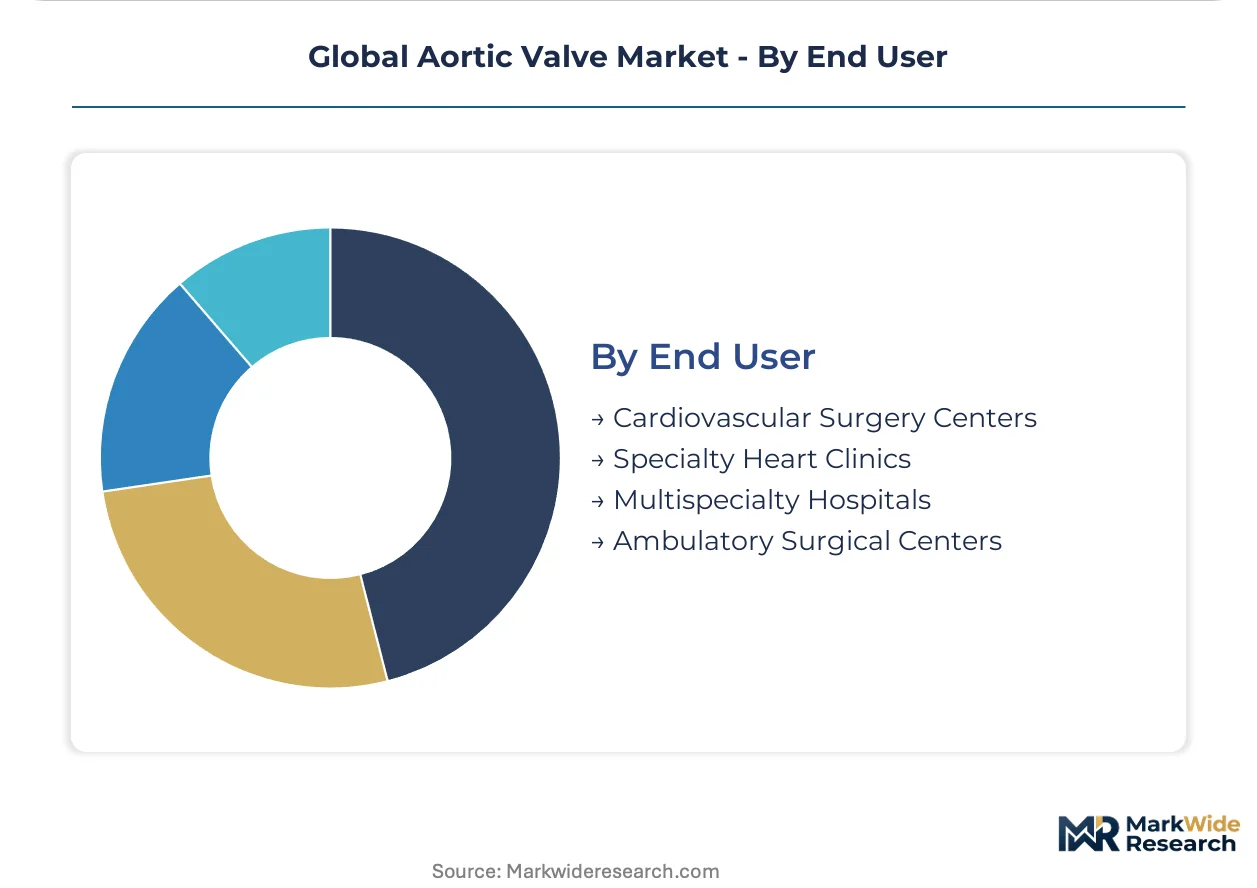
End User:
Facility infrastructure requirements stratify delivery capabilities, with ambulatory settings capturing only the lowest-complexity transcatheter cases.
- Cardiovascular Surgery Centers:Dedicated cardiac operating suites with cardiopulmonary bypass capability. Cleveland Clinic and Mayo Clinic campuses in the United States perform over 1,000 aortic valve procedures annually.
- Specialty Heart Clinics:Focused interventional cardiology practices with hybrid operating room infrastructure. German private cardiology groups in Munich and Hamburg have launched standalone transcatheter programs.
- Multispecialty Hospitals:General acute care facilities expanding structural heart service lines. Tier-2 cities in China's Jiangsu and Zhejiang provinces are adding transcatheter capabilities through provincial hospital upgrades.
- Ambulatory Surgical Centers:Limited-service facilities restricted to diagnostic catheterization and low-risk interventions. United States Medicare reimbursement constraints currently exclude valve replacement from ASC settings.
Multispecialty hospitals capture the broadest volume base; specialty heart clinics are expanding most quickly toward transcatheter specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement clarity and regulatory harmonization are accelerating procedural volume expansion across mature healthcare systems while emerging economies build structural heart infrastructure. The United States, Germany, Japan, China, and India concentrate demand through distinct demographic and policy pathways.
United States
Medicare coverage determinations for transcatheter aortic valve replacement now extend to low-risk patients, expanding addressable candidacy beyond the initial high-risk indication. FDA breakthrough device designations compress premarket review timelines for next-generation delivery systems. Cleveland Clinic and Mayo Clinic campuses perform over 1,000 aortic valve procedures annually, anchoring specialist training pipelines.
Germany
Statutory health insurance funds maintain comprehensive reimbursement for bioprosthetic tissue valves in patients over 75 years, aligning procurement with anticoagulation intolerance demographics. CE marking under EU MDR extends post-market surveillance obligations for Class III implantable devices. Munich and Hamburg private cardiology groups have launched standalone transcatheter programs outside traditional cardiac surgery centers.
Japan
PMDA maintains distinct pharmacovigilance reporting standards that extend post-approval surveillance obligations for transcatheter devices beyond FDA and EMA requirements. Aging demographics concentrate surgical candidacy in tissue valves for octogenarian populations. Tokyo and Osaka academic medical centers drive procedural volume through specialized structural heart programs.
China
NMPA expansion of overseas clinical data acceptance reduces redundant trial requirements for imported cardiovascular implants, accelerating market access for established transcatheter platforms. Provincial hospital upgrades in Jiangsu and Zhejiang provinces are adding transcatheter capabilities in tier-2 cities. Domestic manufacturers are backward integrating into nitinol frame fabrication and bovine pericardium processing.
India
Younger patient demographics and limited anticoagulation monitoring infrastructure elevate mechanical valve preference over bioprosthetic alternatives on cost efficiency grounds. CDSCO regulatory pathways for cardiovascular implants are converging toward international standards through increased reliance on overseas clinical evidence. Chennai and Hyderabad cardiac centers are developing regional transcatheter training hubs for South Asian specialists.
Global Aortic Valve Market Competitive Landscape
Player mix skews toward diversified cardiovascular conglomerates with integrated structural heart portfolios alongside specialized transcatheter innovators. Market structure exhibits tiered consolidation around three strategic archetypes: platform incumbents with iterative franchise extensions, mechanical valve specialists with captive materials capabilities, and emerging transcatheter challengers with regional regulatory footholds. Dominant competitive moves include backward integration into titanium forging and pyrolytic carbon coating operations, plus direct-to-hospital distribution agreements that bypass traditional distributor markups.
Among platform incumbents, Edwards Lifesciences Corporation and Medtronic occupy positions exemplifying sustained R&D intensity across delivery system generations and materials science integration. Abbott Laboratories represents the diversified conglomerate archetype, anchoring competitive positioning through portfolio breadth spanning repair technologies and replacement modalities. Boston Scientific Corporation sits within the transcatheter innovation tier, reflecting strategic emphasis on minimally invasive structural heart interventions.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| LivaNova PLC |
| Artivion |
| CryoLife |
| JenaValve Technology |
| Venus MedTech HangZhou |
| Others |
Supply & Pricing Matrix
CE marking under EU MDR gates both supplier qualification and price differentiation simultaneously, bifurcating the competitive landscape between premium-certified incumbents and price-challenged aspirants. Manufacturers must absorb elevated post-market surveillance costs that compress margins on economy-tier offerings while reinforcing premium positioning for Class III implantable devices.
Pricing Analysis
Certification level (ISO/FDA/CE-grade) creates the primary spread between premium transcatheter platforms and standard mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects material sourcing—bovine pericardium commands premium positioning against pyrolytic carbon mechanical valves. Price erosion runs through economy mechanical valves as Indian and Brazilian procurement prioritizes cost efficiency over biocompatibility. Hospital purchasing committees exhibit highest price sensitivity in mechanical valve tiers, while integrated delivery networks negotiate bundled premiums for transcatheter portfolios.
Supply Chain Analysis
Strategic stockpiling of bovine pericardium and pyrolytic carbon feedstocks dominates inventory strategy given xenograft sourcing constraints and coating facility concentration. Supply concentrates in the United States, Germany, and Australia—drawing from pharmaceutical-grade cattle herds and specialized carbon-coating operations. Raw material dependencies rest on titanium forging, nitinol tubing, and cross-linked collagen sheets. Single-source vulnerability in pyrolytic carbon coating creates supply chain risk. Distribution runs through direct-to-hospital consignment agreements that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global aortic valve market represents high-growth disruption as transcatheter delivery systems displace surgical sternotomy across expanding risk strata. FDA breakthrough device designation and EU MDR clinical evaluation requirements accelerate competitive separation between innovation-capable incumbents and compliance-burdened challengers.
For Market Incumbents: Shield market position by deepening backward integration into titanium forging and pyrolytic carbon coating operations, eliminating single-source vulnerability that emerging transcatheter specialists exploit. Fortify regulatory affairs capacity to manage annual safety update reports and proactive post-market clinical follow-up studies mandated under EU MDR, converting compliance burden into competitive moat against under-resourced entrants.
For New Entrants and Emerging Players: FDA breakthrough device designation offers accelerated review pathways that compress premarket timelines against established CE-marking bottlenecks. Target China's NMPA overseas data acceptance pathway for imported cardiovascular implants, leveraging foreign clinical evidence to bypass redundant trial requirements. Penetrate tier-2 Chinese provincial hospitals in Jiangsu and Zhejiang provinces through direct-to-hospital distribution agreements that capture margin from distributor intermediaries.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed transcatheter specialists holding regional regulatory footholds in China and Japan. Long-term viability hinges on manufacturing scalability beyond bovine pericardium constraints through polymer leaflet platforms. Watch polymer material durability data as inflection indicator for synthetic valve commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance obligations extend timelines 18-24 months versus prior directives. |
| Hospital System Partnership | Integrated delivery networks consolidate supplier contracts around full cardiovascular portfolio relationships. |
| Backward Integration | Captive titanium forging and pyrolytic carbon coating eliminates single-source supply vulnerability. |
| Reimbursement Strategy | Medicare coverage expansion to low-risk patients broadens transcatheter addressable candidacy. |
| Software Companion Development | CT-fluoroscopy fusion with robotic catheter navigation enables complex anatomical case expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA premarket approval databases, EU MDR notified body documentation, and hospital procurement records. Interviews with interventional cardiologists, cardiovascular surgeons, hospital purchasing committee members, and biomedical engineers informed procedural volume and technology adoption patterns. Secondary validation drew from CMS Medicare reimbursement data, PMDA pharmacovigilance reports, and NMPA overseas clinical evidence guidelines. Bottom-up procedure counts triangulate against top-down market sizing across transcatheter, surgical, and mechanical valve modalities.
Segmentation dimensions modeled include product type, material composition, application severity, and end-user facility infrastructure across the analysis window. CAGRs derive from procedural volume trajectories, reimbursement expansion patterns, and regulatory pathway velocity. Forecast inputs incorporate aging demographic projections in Japan and Germany, plus training pipeline constraints for interventional cardiologist certification.
Decision-makers should treat outputs as directional under assumptions of sustained reimbursement clarity and regulatory harmonization; material deviation would warrant model refresh. Revision becomes warranted when EU MDR notified body capacity constraints or polymer leaflet durability data cross thresholds that alter competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market