
 Transcatheter Heart Valve Replacement (THVR) Market | 2026-2036
Transcatheter Heart Valve Replacement (THVR) Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Heart Valve Replacement (THVR) Market Intelligence
A shortage of interventional cardiologists trained in transfemoral and transapical techniques is unwinding procedural volume growth across developed healthcare systems. Edwards Lifesciences leverages its SAPIEN platform franchise to sustain manufacturing scale in balloon-expandable systems. Medtronic anchors European market access through its CoreValve self-expanding portfolio and specialized physician training networks. Abbott differentiates via its diversified structural heart portfolio spanning aortic and mitral repair modalities.
Transcatheter heart valve replacement encompasses minimally invasive implantation of prosthetic valves via catheter-based delivery, typically employing nitinol or cobalt-chromium frames with bovine or porcine pericardial leaflets engineered to function at cardiac outputs exceeding five liters per minute. The procedure eliminates sternotomy and cardiopulmonary bypass, reducing recovery intervals from weeks to days for inoperable or high-risk surgical candidates. Self-expanding platforms now lead procedural volume in elderly populations with tortuous iliofemoral anatomy, while balloon-expandable systems retain preference in bicuspid aortic valve anatomy where radial force precision matters. Transcatheter mitral valve interventions represent the fastest-expanding application segment, though commercial penetration trails aortic stenosis treatment by nearly a decade due to anatomical complexity and recurrent regurgitation challenges.
FDA breakthrough device designation and CE marking under the EU Medical Device Regulation shape competitive timelines by compressing premarket review intervals for novel valve systems. Japan's PMDA and China's NMPA operate parallel approval tracks that condition market entry on localized clinical data generation, fragmenting go-to-market strategies. Stakeholders must monitor evolving CMS national coverage determinations and parallel private payer policies, as reimbursement parity between transcatheter and surgical valve replacement remains the decisive variable for hospital capital commitment to hybrid operating suites.
Market Dynamics
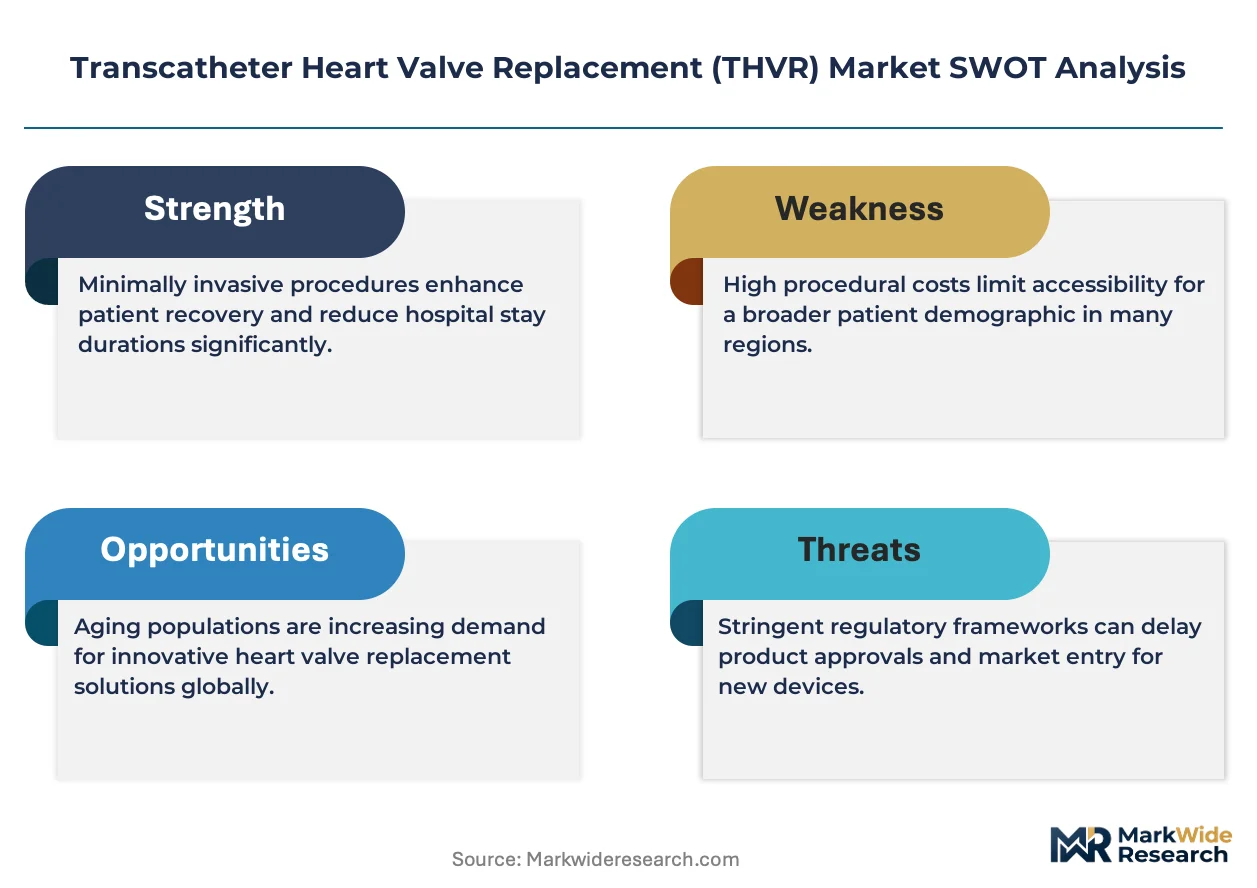
Hospital procurement committees now prioritize hybrid operating suite investments that accommodate both transcatheter and surgical valve workflows, compressing capital deployment timelines and reshaping vendor qualification criteria.
Growth Catalysts
- Medicare reimbursement parity:The Centers for Medicare & Medicaid Services maintains coverage determinations that reimburse transcatheter procedures at rates competitive with surgical alternatives, accelerating hospital adoption in the United States.
- CE marking under EU MDR:Streamlined conformity assessment pathways for breakthrough devices compress premarket review intervals, enabling faster European commercialization of novel valve platforms.
- Self-expanding nitinol frames:Advances in shape-memory alloy engineering enable delivery through tortuous iliofemoral anatomy, expanding treatable patient populations beyond surgical candidates.
Market Restraints
- Bovine pericardial tissue supply concentration:Reliance on single-source biological suppliers creates vulnerability to zoonotic disease outbreaks and tissue processing capacity constraints.
- PMDA localized clinical data mandates:Japan's pharmaceutical and medical device agency requires indigenous trial enrollment, fragmenting go-to-market economics and extending approval timelines.
- Surgical valve durability benchmarks:Established 15-20 year structural valve integrity data from tissue prostheses sets performance expectations that transcatheter platforms must match.
Strategic Opportunities
- Transcatheter mitral valve repair:Anatomical complexity has delayed commercial penetration relative to aortic applications, creating first-mover advantage for platforms solving recurrent regurgitation.
- India's PLI scheme for medical devices:Production-linked incentive structures attract manufacturing investment, enabling cost-competitive supply for price-sensitive Asian markets.
- Real-world evidence integration:FDA breakthrough device pathways now incorporate post-market surveillance data, compressing total evidence generation timelines for iterative platform improvements.
Industry Challenges
- Interventional cardiologist training pipelines:Procedural volume growth outpaces fellowship program output for transfemoral and transapical technique certification, constraining hospital capacity expansion.
- Hybrid suite capital intensity:Fixed imaging infrastructure, anesthesia integration, and sterile processing requirements demand $3-5 million per installation, straining community hospital balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Heart Valve Replacement (THVR) Market |
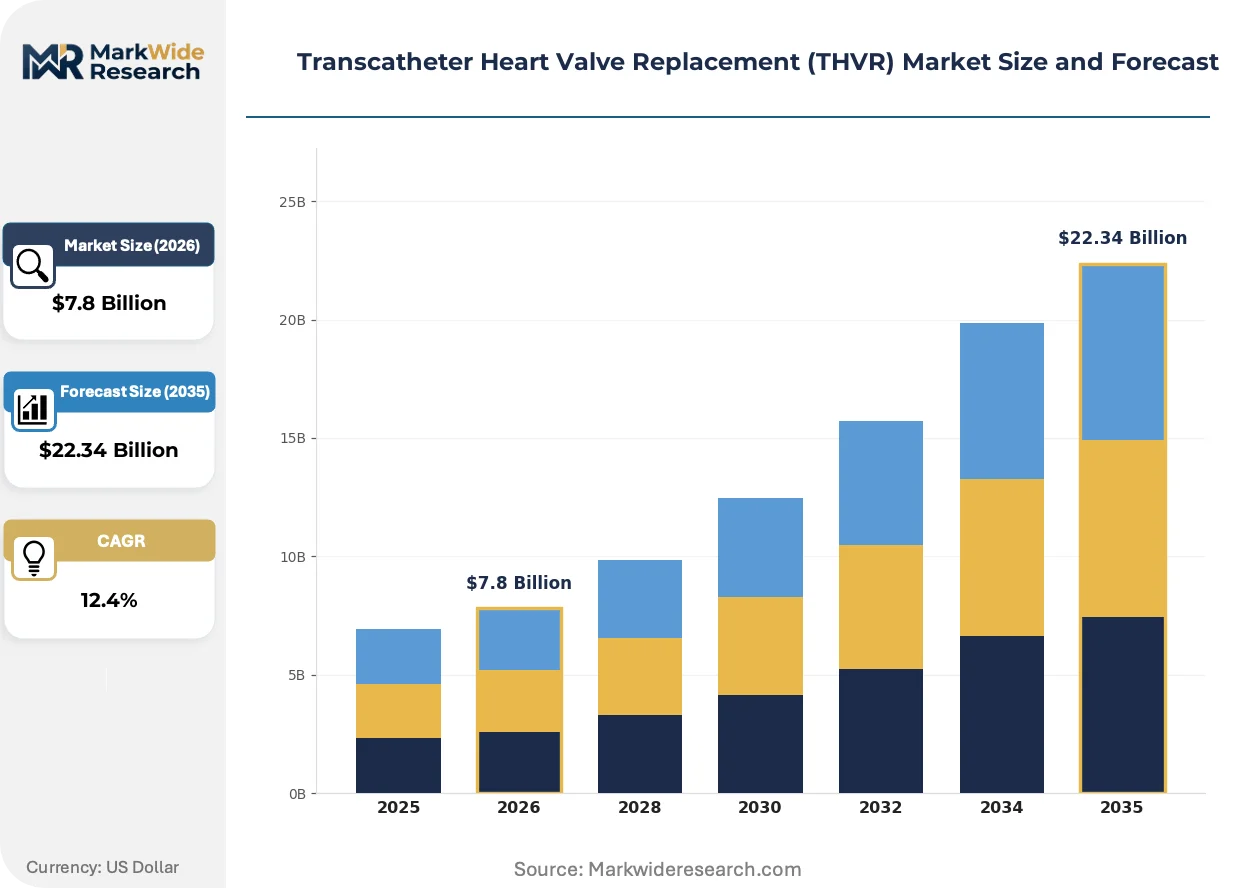
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $22.34 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon-Expandable, Self-Expanding, Transcatheter Aortic Valve, Transcatheter Mitral Valve End User: Hospitals, Cardiology Clinics, Surgical Centers, Research Institutions Delivery Mode: Transfemoral, Transapical, Subclavian, Transaortic Application: Aortic Stenosis, Mitral Regurgitation, Pulmonary Valve Replacement, Others |
| Companies Covered | Edwards Lifesciences, Medtronic, Boston Scientific Corporation, Abbott, LivaNova, JenaValve Technologies, Venus Medtech, Meril Lifesciences, Peijia Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Heart Valve Replacement (THVR) Market Strategic Shifts & Innovations
Technology convergence between cardiac imaging, robotic delivery systems, and computational modeling is compressing procedural learning curves and enabling operator-agnostic outcomes.
Next-generation valve frame metallurgy is bifurcating between cobalt-chromium alloys optimized for radial force precision in bicuspid anatomy and low-profile nitinol systems designed for minimalistic delivery sheaths. Academic medical centers in Germany and the United States are adopting both platforms in parallel, stratifying inventory by patient anatomical classification. This material divergence is bifurcating procurement strategies and forcing manufacturers to maintain dual manufacturing lines.
EU Medical Device Regulation's enhanced clinical evidence requirements are extending notified body review timelines for class III implantable devices, particularly affecting novel transcatheter mitral platforms. Manufacturers are responding by front-loading European pivotal trials and establishing quality management systems that exceed previous Medical Device Directive standards. Small-cap innovators without legacy MDR infrastructure face disproportionate compliance burdens.
Hospital value analysis committees now mandate lifetime cost-of-care modeling that incorporates reintervention probability, valve-in-valve feasibility, and complication management expenses. This analytical rigor favors platforms with durable hemodynamic performance and modular repairability. The United States exhibits the most advanced procurement sophistication, with integrated delivery networks standardizing these evaluation frameworks across multi-hospital systems.
Transcatheter Heart Valve Replacement (THVR) Market Segmentation
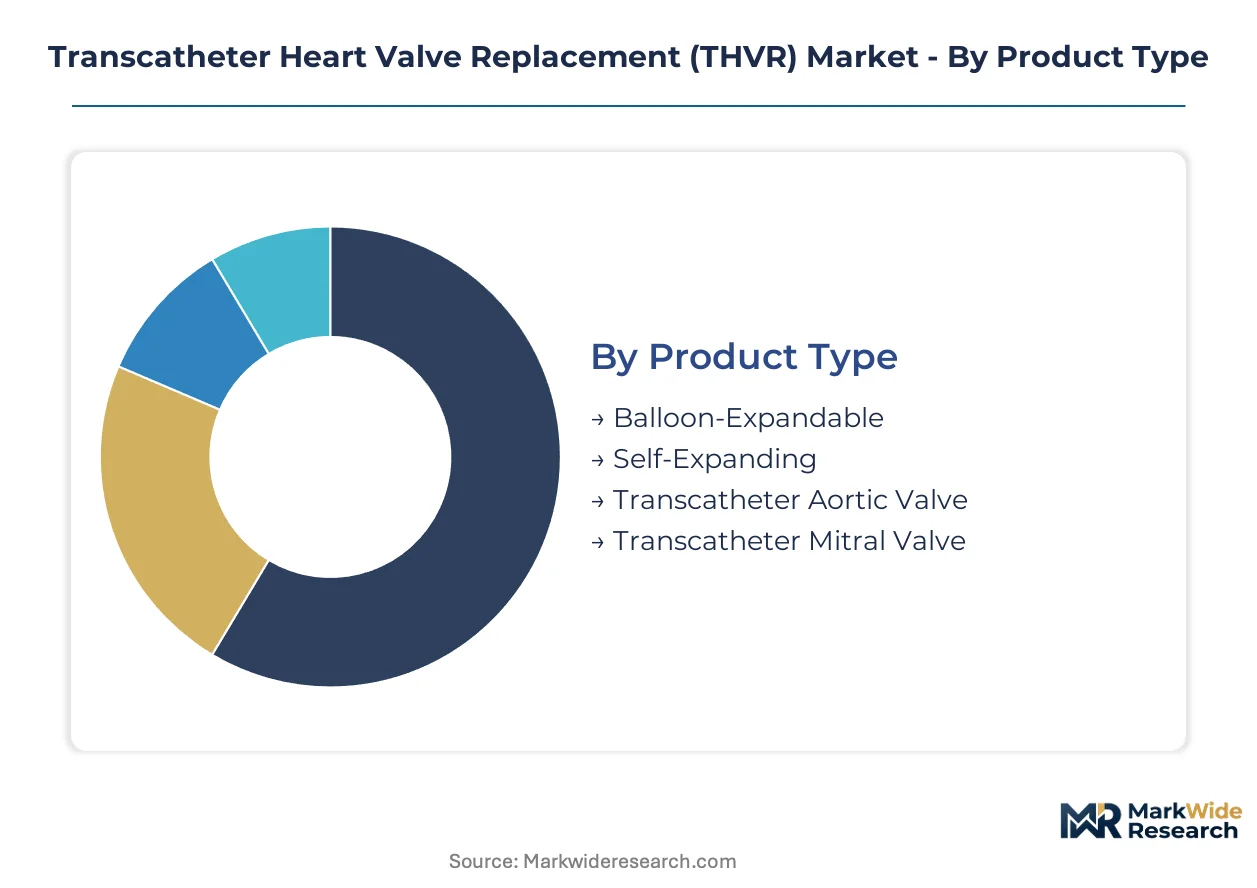
Segmentation in the THVR market reveals how procedural complexity, anatomical variation, and site-of-care economics fragment commercial pathways. Hospital procurement committees stratify inventory by delivery approach and valve platform, while reimbursement structures condition adoption across patient risk categories.
Product Type:
Balloon-expandable and self-expanding platforms flow through distinct hospital procurement channels, with inventory decisions stratified by patient anatomical classification and operator training networks.
- Balloon-Expandable:Cobalt-chromium frames deliver precise radial force deployment for bicuspid aortic valve anatomy. Demand concentrates in academic medical centers across the United States where operators prioritize hemodynamic precision over delivery flexibility.
- Self-Expanding:Nitinol shape-memory alloys enable navigation through tortuous iliofemoral vessels without pre-dilation. German hospital systems favor this platform for elderly populations with peripheral vascular disease, expanding treatable candidate pools beyond surgical thresholds.
- Transcatheter Aortic Valve:The established commercial segment with mature reimbursement pathways and standardized training curricula.
- Transcatheter Mitral Valve:Emerging platforms addressing anatomical complexity through novel anchoring mechanisms and leaflet repair approaches.
By volume, transcatheter aortic valves lead. By growth pace, transcatheter mitral platforms are expanding most quickly.
End User:
Site-of-care economics create tiered procurement patterns, with capital intensity and case volume requirements filtering platform access across facility types.
- Hospitals:Hybrid operating suites demand $3-5 million capital deployment for fixed imaging and anesthesia integration. United States integrated delivery networks concentrate procedural volume in high-throughput centers, achieving economies that community hospitals cannot replicate.
- Cardiology Clinics:Outpatient diagnostic and follow-up services without implant capability. Japanese clinic networks manage post-procedural anticoagulation monitoring, extending hospital episode value through longitudinal care.
- Surgical Centers:Limited to diagnostic catheterization and low-risk interventions.
- Research Institutions:Pivotal trial enrollment and real-world evidence generation sites shaping regulatory precedents.
By installed base, hospitals dominate. By expansion trajectory, cardiology clinics are gaining share fastest as post-acute care networks deepen.
Delivery Mode:
Vascular access strategy determines device profile requirements, anesthesia protocols, and recovery pathway design across patient anatomies.
- Transfemoral:The preferred percutaneous approach through femoral artery access enabling same-day mobilization. United States Medicare reimbursement parity with surgical alternatives has cemented this as the default pathway for eligible candidates.
- Transapical:Direct left ventricular apex access for patients with prohibitive iliofemoral disease. European centers retain higher utilization due to aging populations with extensive peripheral vascular calcification.
- Subclavian:Alternative access through axillary or subclavian arteries when femoral vessels are occluded.
- Transaortic:Direct aortic access via mini-thoracotomy for complex anatomical configurations.
By procedural count, transfemoral access leads. By residual need fulfillment, transapical approaches show the steepest expansion trajectory in elderly populations.
Application:
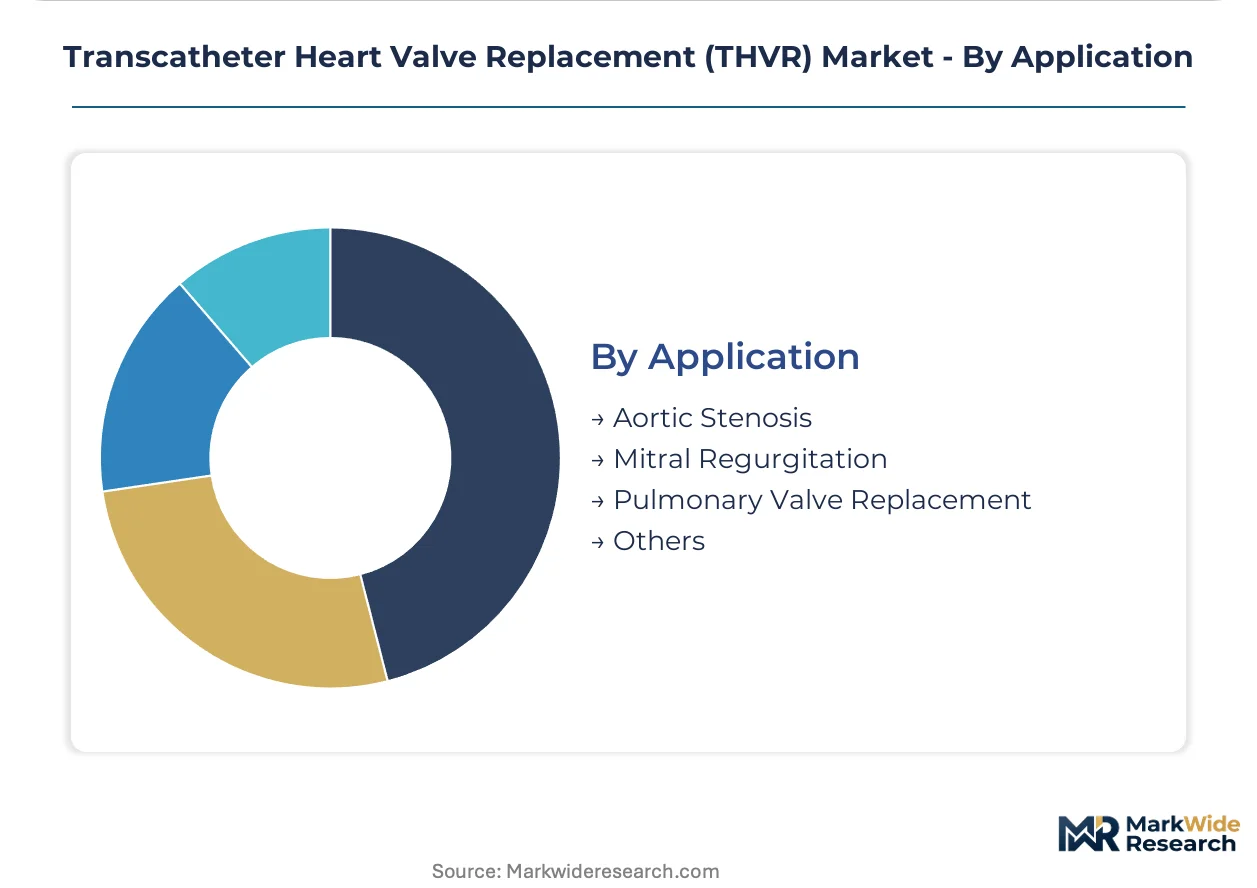
Indication-specific platforms address distinct hemodynamic pathologies, with anatomical complexity and recurrence risk fragmenting commercial maturity timelines.
- Aortic Stenosis:Calcific valve degeneration in elderly patients represents the validated commercial application with established durability data. German and United States hospital systems have standardized workflows, compressing door-to-procedure intervals.
- Mitral Regurgitation:Functional and degenerative etiologies present recurrent regurgitation challenges that aortic platforms do not face. CE marking under EU MDR has accelerated European commercialization ahead of FDA breakthrough device timelines.
- Pulmonary Valve Replacement:Congenital heart disease applications with smaller addressable populations.
- Others:Tricuspid regurgitation and valve-in-valve procedures in surgical prosthesis failure.
By current revenue concentration, aortic stenosis treatment leads. By platform investment intensity, mitral regurgitation solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates transcatheter procedures in integrated delivery networks with Medicare reimbursement parity, while Germany and Japan fragment volume across dispersed academic medical centers with divergent training pipelines and regulatory data mandates.
United States
Hospital systems in Cleveland, Houston, and New York Metro operate hybrid suites with $3-5 million capital deployments. FDA breakthrough device pathways compress premarket review for novel valve platforms. Medicare national coverage determinations reimburse transcatheter procedures at surgical parity, anchoring demand concentration in high-throughput centers.
Germany
University hospitals in Munich, Heidelberg, and Berlin standardize self-expanding platform workflows for elderly populations with tortuous iliofemoral anatomy. CE marking under EU MDR extends notified body review timelines for class III implantable devices. The Baden-Württemberg medical technology cluster concentrates manufacturing engineering expertise for nitinol frame production.
Japan
Academic medical centers in Tokyo and Osaka manage post-procedural anticoagulation through extended clinic networks. PMDA mandates indigenous clinical trial enrollment, fragmenting go-to-market economics for foreign manufacturers. The Kanto region concentrates interventional cardiology training capacity, constraining procedural volume growth relative to eligible patient pools.
China
Class III medical device registration through NMPA requires localized manufacturing partnerships for market access. Shanghai and Beijing medical centers pioneer transcatheter mitral platforms ahead of commercial scale. Domestic manufacturers leverage cost structures to supply price-sensitive provincial hospital systems.
India
Production-linked incentive schemes attract catheterization lab equipment manufacturing to Gujarat and Karnataka. CDSCO regulatory pathways condition import approvals on local clinical data generation. Mumbai and Delhi private hospital chains expand transfemoral capacity for medical tourism segments.
Transcatheter Heart Valve Replacement (THVR) Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in transcatheter valve manufacturing. Balloon-expandable and self-expanding platform divergence has stratified procurement relationships, with hospital systems maintaining dual inventory lines. Three archetypes dominate: diversified cardiovascular conglomerates with structural heart divisions, pure-play transcatheter specialists, and emerging Asia-Pacific manufacturers leveraging cost-advantaged production. Competitive moves concentrate on physician training network expansion and M&A for complementary mitral repair technologies.
Within the diversified cardiovascular tier, Edwards Lifesciences and Medtronic occupy positions reflecting distinct platform philosophies, while Abbott exemplifies portfolio breadth spanning aortic and mitral modalities. These entities anchor procurement relationships through specialized training networks and hybrid suite co-development programs. Boston Scientific Corporation represents the integrated device manufacturer archetype with structural heart diversification. The specialist tier includes JenaValve Technologies and Venus Medtech, which sit within narrower technology licensing and regional market access strategies respectively. LivaNova, Meril Lifesciences, and Peijia Medical exemplify geographic concentration patterns in European and Asia-Pacific manufacturing clusters.
| Leading Market Players |
|---|
| Edwards Lifesciences |
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| LivaNova |
| JenaValve Technologies |
| Venus Medtech |
| Meril Lifesciences |
| Peijia Medical |
| Others |
Cost & Logistics Intelligence
Manufacturing scale economies in nitinol frame production concentrate cost advantages among producers operating multi-platform lines across Germany and the United States, compressing price floors for balloon-expandable systems while elevating entry barriers for single-product specialists. This scale dynamic feeds into procurement negotiations where hospital systems leverage volume commitments against dual-source inventory requirements.
Pricing Analysis
Long-term offtake agreements anchor pricing for cobalt-chromium and nitinol raw materials, with balloon-expandable platforms commanding premium positioning over self-expanding alternatives due to radial force precision requirements. Price differentiation hinges on CE marking tier under EU MDR and FDA breakthrough device status, with academic medical centers exhibiting lowest price sensitivity and provincial hospital systems in Asia-Pacific showing highest. Pricing pressure stems from India's PLI scheme enabling cost-competitive domestic manufacturing, compressing margins for imported platforms.
Supply Chain Analysis
Inventory lead times for bovine pericardial tissue extend procurement planning cycles, with suppliers in Australia and New Zealand anchoring biological material sourcing alongside processing facilities in Ireland and Switzerland. The supply chain draws from cobalt-chromium alloy producers in Germany and nitinol wire manufacturers in the United States, creating single-source vulnerability for shape-memory alloy specifications. Distribution runs through specialized cardiac device distributors with cold-chain capabilities, bypassing general medical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States, where three hospital systems now control over half of transcatheter procedural volume and extract co-development terms from manufacturers.
For Market Incumbents: Consolidate manufacturing scale across dual-platform lines to defend against emerging Asia-Pacific cost competitors, prioritizing backward integration into nitinol wire production to secure shape-memory alloy supply. Lock in hospital system partnerships through hybrid suite co-investment programs before procurement committees standardize on single-vendor frameworks. For New Entrants and Emerging Players: Post-procedural monitoring services represent an under-served layer where incumbents lack dedicated infrastructure, enabling white-space entry through clinic-based anticoagulation management and remote hemodynamic surveillance. Target cardiology clinic networks in Japan and Germany with software companion platforms that extend episode value beyond implant, bypassing capital-intensive manufacturing requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play transcatheter mitral specialists with CE marking progress but pre-FDA submission status, offering acquisition windows before breakthrough device designation compresses valuation multiples. Watch PMDA approval timelines for indigenous trial data as inflection signal for Asia-Pacific market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment accelerates European commercialization ahead of FDA timelines for mitral platforms. |
| Hospital System Partnership | Co-investment in hybrid suites locks in procurement preference and blocks competitor access to high-volume centers. |
| Reimbursement Strategy | CMS national coverage determination alignment secures Medicare parity essential for United States hospital adoption. |
| Software Companion Development | Computational modeling tools reduce procedural learning curves and enable operator-agnostic outcomes across training networks. |
| Physician Training Network Expansion | Fellowship program partnerships address interventional cardiologist shortages constraining procedural volume growth. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CE marking databases under EU MDR, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue disclosures to anchor market sizing.
Across the projection horizon, the analytical framework modeled segmentation by valve platform type, delivery approach, anatomical application, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, reimbursement expansion schedules, and training pipeline output projections. Forecast inputs incorporated PMDA trial enrollment mandates, hybrid suite capital deployment cycles, and biological tissue processing capacity constraints.
Underlying assumptions cover reimbursement parity maintenance, interventionalist training expansion, and nitinol supply stability, with deviation risk concentrated in zoonotic disease impacts on pericardial tissue sourcing and EU MDR notified body review delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market