
 Transesophageal Echocardiography (TEE) Market | 2026-2036
Transesophageal Echocardiography (TEE) Market Size, Share, and Industry Trends Forecast 2026-2036
Transesophageal Echocardiography (TEE) Market Analytics
Buyer concentration among cardiac centers and large hospital networks is rebalancing as ambulatory surgical centers gain purchasing autonomy for outpatient procedures. GE Healthcare leverages its installed base of cardiovascular imaging platforms to sustain service revenue streams. Philips Healthcare differentiates through integrated ultrasound ecosystems that combine hardware with workflow software. Siemens Healthineers anchors its position in European markets through direct hospital contracting.
Transesophageal echocardiography employs a multiplane transducer mounted on a flexible endoscope to generate real-time ultrasound images from the esophagus, operating at frequencies between 3.5 and 7.5 megahertz for cardiac structural assessment. The technology enables visualization of posterior cardiac structures without intervening bone or lung tissue, serving critical functions in intraoperative monitoring and interventional guidance. Three-dimensional imaging systems command premium positioning due to superior spatial resolution for valve repair planning, while Doppler imaging maintains broad utilization across hemodynamic evaluation protocols. Software segments attract recurring revenue models as vendors deploy automated measurement tools and cloud-based archiving.
FDA 510(k) pathways govern device clearance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for TEE probe reprocessing and biocompatibility. Japan's PMDA maintains distinct standards for ultrasonic diagnostic equipment that influence product development cycles for manufacturers seeking market access. Stakeholders must monitor evolving cybersecurity guidance for networked imaging systems and prepare for interoperability mandates that will reshape procurement criteria.
Market Dynamics
Three-dimensional imaging capability is modularizing across TEE system architectures, compressing hardware upgrade cycles as cardiac centers demand interoperable software layers without full device replacement.
Growth Catalysts
- EU MDR compliance deadlines:Strengthened clinical evidence requirements for probe reprocessing are accelerating hospital capital expenditure on certified single-use sheaths and validated sterilization protocols.
- Ambulatory surgical center expansion:United States outpatient cardiac procedure volumes are pulling TEE systems into freestanding facilities previously dependent on hospital-based imaging departments.
- AI-enhanced measurement algorithms:Automated ejection fraction calculations and valve quantification tools are reducing operator-dependent variability in interventional cardiology suites.
Market Restraints
- Transducer manufacturing concentration:Precision piezoelectric crystal supply chains cluster in East Asian component foundries, exposing OEMs to input volatility and geopolitical logistics friction.
- Specialized operator training requirements:TEE probe insertion and image acquisition demand certified echocardiographer presence, constraining deployment in smaller cardiac centers without fellowship-trained staff.
- Reimbursement compression:United States CMS physician fee schedule adjustments for intraoperative TEE monitoring are narrowing margin contribution per procedure.
Strategic Opportunities
- Japan's tertiary hospital infrastructure refresh:PMDA ultrasonic diagnostic equipment standards are driving replacement demand as aging 2D systems reach end-of-service life in university-affiliated cardiac centers.
- Cloud-native image archiving:Vendor-neutral PACS integration and remote diagnostic consultation platforms are opening recurring SaaS revenue streams independent of hardware sales cycles.
- Hybrid operating room expansion:Convergence of surgical robotics and real-time TEE guidance is creating integrated visualization workstation demand in Germany's leading cardiovascular institutes.
Industry Challenges
- Probe reprocessing validation complexity:High-level disinfection protocols for reusable TEE transducers face intensified scrutiny from infection control committees, extending equipment downtime and compliance documentation burdens.
- Legacy system interoperability gaps:Pre-2015 imaging platforms lack DICOM-RTV compatibility with contemporary 3D rendering software, forcing costly middleware investments or premature retirement of functional hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transesophageal Echocardiography (TEE) Market |
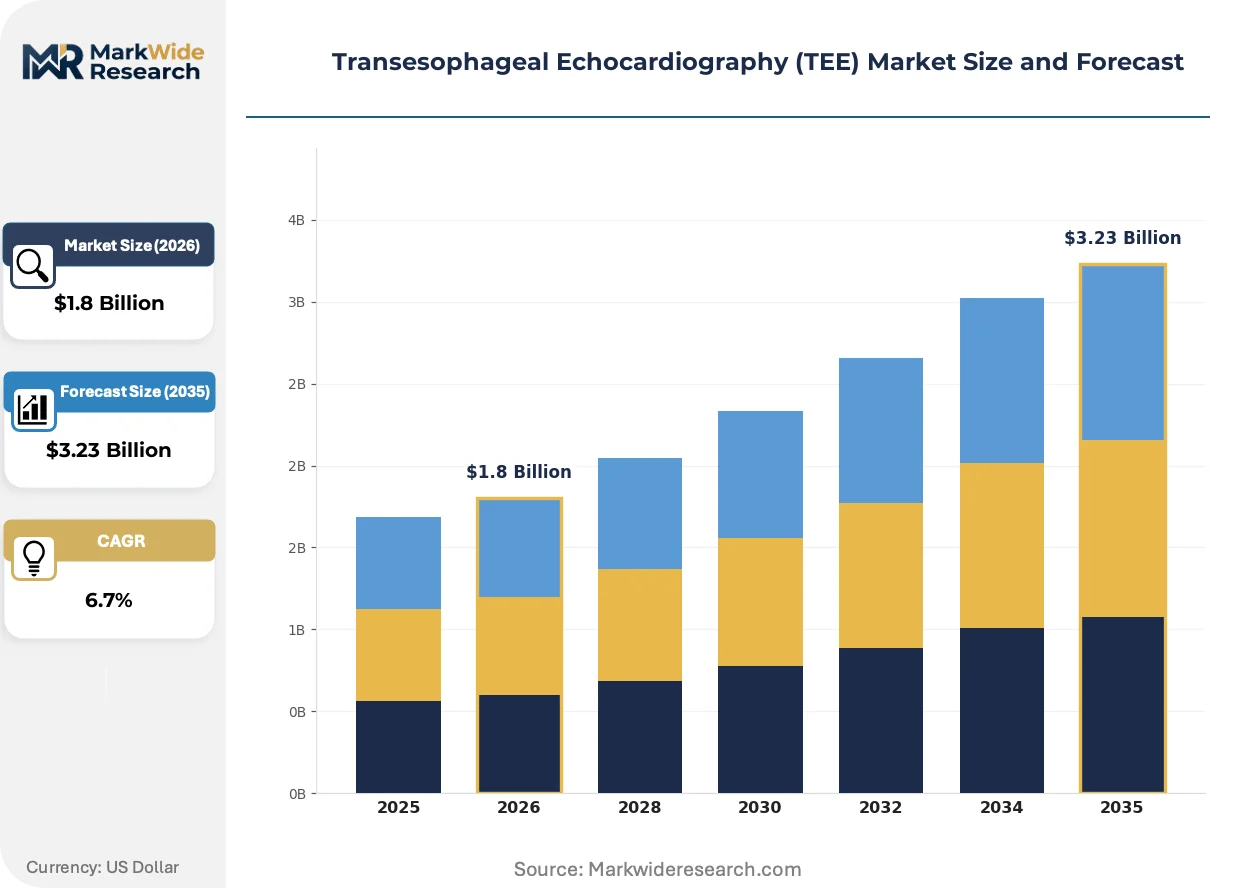
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transducer, Monitor, Software, Imaging System End User: Cardiac Center, Hospital, Ambulatory Surgical Center, Imaging Center Technology: 2D Imaging, 3D Imaging, Doppler Imaging, Contrast Imaging Application: Cardiac Valve Assessment, Congenital Heart Disease, Atrial Fibrillation, Myocardial Infarction |
| Companies Covered | Canon Medical Systems Corporation, Mindray Bio-Medical Electronics Co., Ltd., GE Healthcare, Hitachi Medical Systems, Samsung Medison Co., Ltd., Philips Healthcare, Fujifilm Holdings Corporation, Esaote SpA, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transesophageal Echocardiography (TEE) Market Evolving Landscape
Computational imaging pipelines are displacing hardware-centric differentiation, enabling software-defined feature upgrades that decouple clinical capability from capital equipment refresh cycles.
Matrix-array transducer technology is modularizing TEE system architectures, allowing cardiac centers to field-upgrade from 2D to real-time 3D imaging through probe swaps rather than console replacement. Leading United States academic medical centers are standardizing on this upgrade path to preserve capital budgets. The approach is compressing OEM replacement revenue while expanding service contract attach rates for software maintenance.
Japan's PMDA has tightened electromagnetic compatibility standards for ultrasonic diagnostic equipment, forcing manufacturers to redesign shielding architectures and retest existing product lines. The regulatory friction is delaying product introductions by 8-14 months for non-domestic suppliers. European OEMs with established Tokyo regulatory affairs teams are capturing accelerated approval timelines relative to newer market entrants.
After-sales service unbundling is fragmenting traditional procurement relationships as cardiac centers negotiate separate contracts for probe repair, software licensing, and clinical training. Independent service organizations are capturing probe refurbishment volumes previously captive to OEM service divisions. This pattern is most pronounced in Germany's hospital purchasing cooperatives, where multi-year total cost of ownership models now dominate capital committee evaluations.
Transesophageal Echocardiography (TEE) Market Segmentation
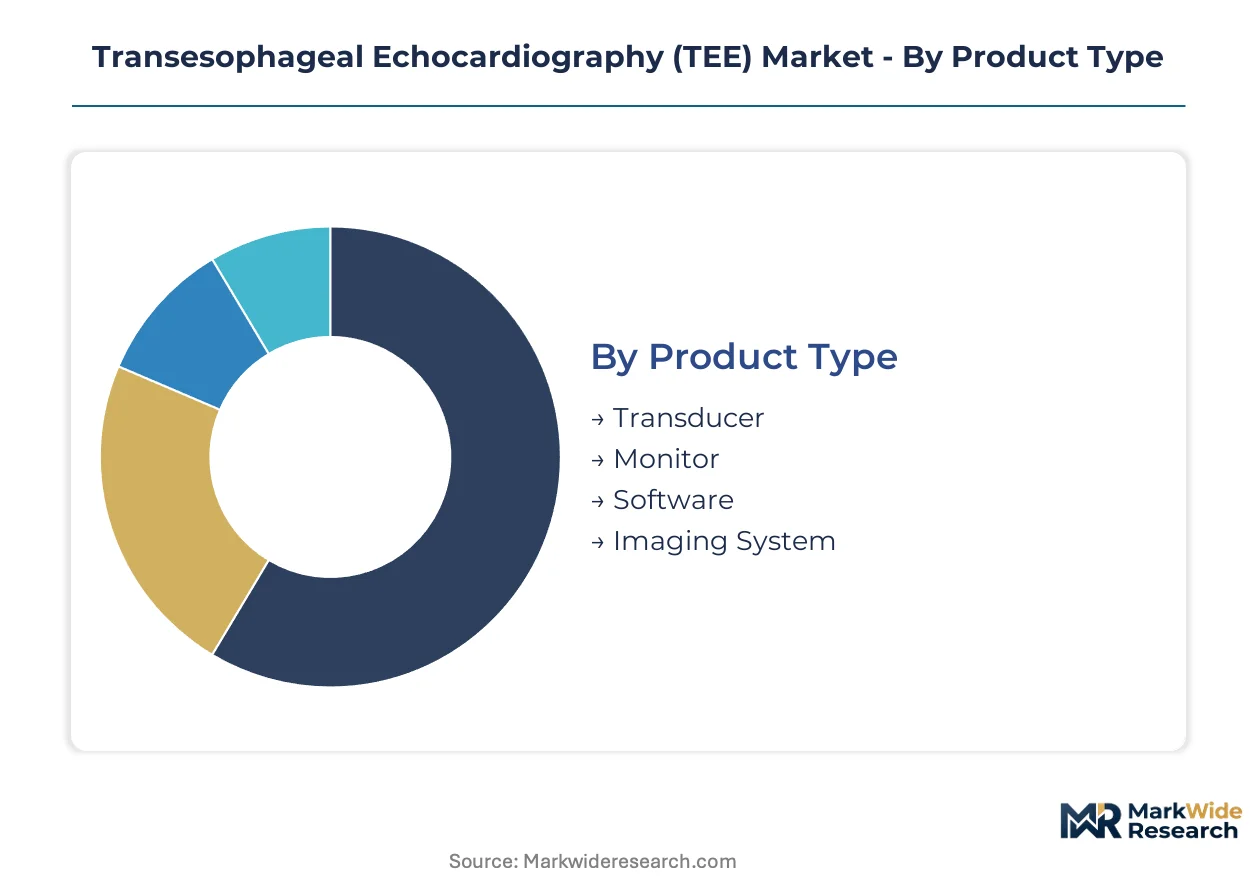
TEE market segmentation reveals how hardware, software, and service components generate distinct revenue rhythms. Product architecture choices determine capital expenditure cycles, while end-user channel shifts reshape distribution economics.
Product Type:
Transducer engineering specifications define system performance ceilings and replacement cadences across cardiac imaging workflows.
- Transducer:Multiplane probe assemblies with 3.5-7.5 MHz frequency ranges constitute the highest-margin hardware segment. Demand clusters in United States academic medical centers pursuing 2D-to-3D field upgrades without console replacement. Piezoelectric crystal supply concentration in East Asian foundries constrains OEM production flexibility.
- Software:Automated measurement algorithms and AI-enhanced quantification tools command recurring SaaS revenue models. Cardiac centers in Germany negotiate separate licensing contracts from hardware procurement, fragmenting traditional bundled purchasing relationships. Cloud-native archiving capabilities are expanding addressable market beyond installed base constraints.
- Monitor:Display workstations for real-time visualization support hybrid operating room integration with surgical robotics platforms. Procurement concentrates in Japan's tertiary hospital infrastructure refresh cycles.
- Imaging System:Integrated console-probe combinations remain the reference standard for de novo installations. Ambulatory surgical centers in the United States favor compact configurations for space-constrained outpatient cardiac suites.
Mature deployment sits with Imaging System. Newer deployment is concentrated in Software.
End User:
Channel structure is rebalancing as outpatient cardiac procedure volumes shift care settings and purchasing authority.
- Cardiac Center:Dedicated cardiovascular institutes generate the densest TEE utilization per bed, with intraoperative monitoring protocols requiring 24/7 echocardiographer coverage. United States centers lead 3D imaging adoption for transcatheter valve repair guidance. Fellowship-trained staffing requirements constrain expansion in smaller markets.
- Hospital:General acute care facilities with cardiac surgery programs represent the largest installed base volume. Germany's hospital purchasing cooperatives dominate procurement through multi-year total cost of ownership evaluations. Legacy DICOM interoperability gaps force middleware investments or premature hardware retirement.
- Ambulatory Surgical Center:Freestanding outpatient facilities are gaining autonomous purchasing authority for diagnostic and interventional cardiac procedures previously dependent on hospital-based imaging departments. United States CMS reimbursement adjustments influence capital committee prioritization.
- Imaging Center:Dedicated diagnostic facilities concentrate on non-invasive echocardiography, with TEE deployment limited to pre-procedural planning contracts with referring cardiac practices.
Procurement consolidation is strongest in Hospital. Procurement autonomy is expanding fastest in Ambulatory Surgical Center.
Technology:
Imaging modality selection determines diagnostic yield, operator workflow efficiency, and hardware upgrade pathways.
- 3D Imaging:Real-time volumetric rendering enables superior spatial resolution for valve repair planning and interventional guidance. Matrix-array transducer modularization allows field upgrades from 2D systems in United States academic centers. Premium positioning reflects procedural time savings and reduced reintervention rates.
- Doppler Imaging:Hemodynamic evaluation protocols across all cardiac centers maintain broad utilization for pressure gradient quantification and regurgitant flow assessment. Standard-of-care status limits pricing power despite commodity hardware characteristics.
- 2D Imaging:Conventional multiplane imaging remains sufficient for basic structural assessment in resource-constrained settings. Japan's aging installed base is approaching end-of-service life under tightened PMDA electromagnetic compatibility standards.
- Contrast Imaging:Microbubble-enhanced perfusion imaging expands diagnostic capability in suboptimal acoustic windows. Adoption concentrates in specialized centers with advanced heart failure and cardiomyopathy referral patterns.
Installed base dominance rests with Doppler Imaging. Capability expansion is climbing the fastest in 3D Imaging.
Application:
Clinical indication targeting shapes probe utilization rates, reimbursement coding, and specialist training requirements.
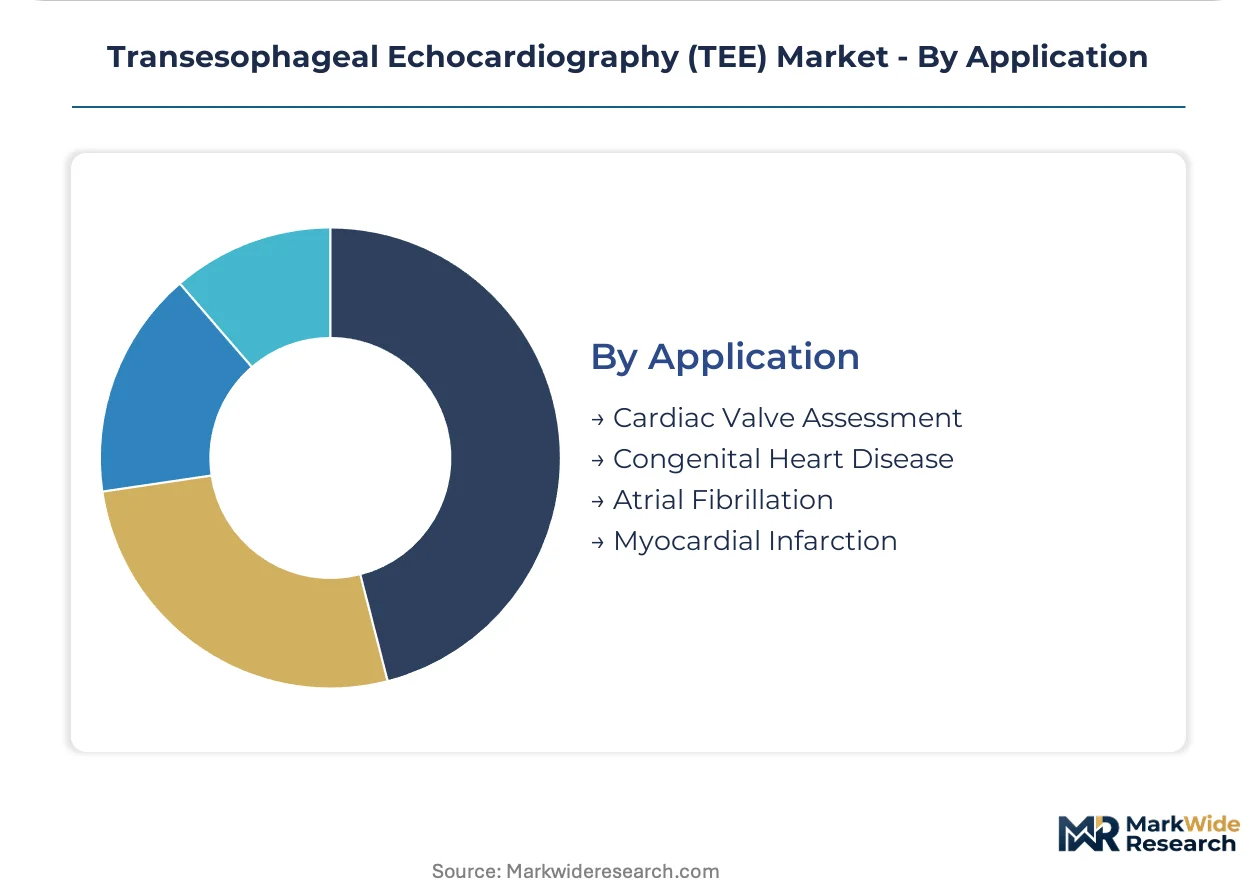
- Cardiac Valve Assessment:Structural evaluation for repair-versus-replace decisions drives the highest TEE probe utilization per procedure. United States transcatheter aortic valve replacement volume expansion sustains demand for real-time 3D guidance. Hybrid operating room integration with surgical robotics creates workstation demand in Germany's leading cardiovascular institutes.
- Atrial Fibrillation:Left atrial appendage exclusion and pulmonary vein isolation procedures require precise anatomical mapping. Electrophysiology lab TEE adoption is accelerating as catheter ablation volumes expand in tertiary cardiac centers.
- Congenital Heart Disease:Pediatric and adult congenital specialist centers deploy TEE for pre-surgical planning and post-repair hemodynamic verification. Case volume concentrates in university-affiliated children's hospitals with fellowship training programs.
- Myocardial Infarction:Mechanical complication assessment and ventricular function quantification support acute coronary syndrome management. Emergency deployment is limited by echocardiographer availability outside standard hours.
Procedure volume leadership belongs to Cardiac Valve Assessment. Volume expansion is steepest in Atrial Fibrillation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac centers in the United States, Germany, and Japan concentrate TEE demand through tertiary hospital infrastructure investment and intraoperative monitoring protocol expansion.
United States
FDA 510(k) clearance pathways for 3D imaging systems and AI-enhanced software accelerate product introductions for academic medical centers. Ambulatory surgical centers gain autonomous purchasing authority as outpatient cardiac procedure volumes expand beyond hospital-based imaging departments. Greater Boston and the Pacific Northwest host dense clusters of hybrid operating room installations integrating TEE guidance with surgical robotics platforms.
Germany
Hospital purchasing cooperatives dominate procurement through multi-year total cost of ownership evaluations that fragment traditional bundled vendor relationships. EU MDR compliance deadlines for probe reprocessing strengthen clinical evidence requirements and accelerate capital expenditure on certified sterilization protocols. Bavaria and North Rhine-Westphalia anchor European demand as cardiovascular institutes replace aging 2D systems with matrix-array upgrade paths.
Japan
PMDA electromagnetic compatibility standards for ultrasonic diagnostic equipment force shielding architecture redesigns that delay product introductions by 8-14 months for non-domestic suppliers. University-affiliated cardiac centers in Kanto and Kansai regions drive replacement demand as aging 2D systems reach end-of-service life under tightened regulatory timelines.
China
Domestic manufacturers expand production capacity for multiplane transducer assemblies serving price-sensitive hospital procurement tenders. NMPA regulatory pathways for imported ultrasonic diagnostic equipment impose additional testing requirements that extend market access timelines. Yangtze River Delta medical device clusters concentrate regional distribution networks for cardiac imaging equipment.
United Kingdom
NHS England procurement frameworks prioritize interoperability mandates that reshape capital committee evaluation criteria for networked imaging systems. London and Southeast cardiac centers lead 3D imaging adoption for transcatheter valve repair guidance while Midlands facilities face legacy DICOM compatibility gaps requiring middleware investments.
Transesophageal Echocardiography (TEE) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined feature differentiation and cloud-native service models. The vendor base organizes around three archetypes: diversified imaging conglomerates with cardiovascular platform breadth, specialized ultrasound manufacturers with probe engineering depth, and emerging Asian electronics firms with cost-optimized hardware. Competitive positioning hinges on service contract attach rates for software maintenance and probe refurbishment capabilities.
Among diversified imaging conglomerates, GE Healthcare, Philips Healthcare, and Siemens Healthineers occupy positions anchored by installed base scale and direct hospital contracting relationships. Canon Medical Systems Corporation and Hitachi Medical Systems represent Japanese-origin competitors navigating PMDA regulatory friction. Mindray Bio-Medical Electronics Co., Ltd. exemplifies Chinese-scale manufacturing positioning in emerging markets.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Mindray Bio-Medical Electronics Co., Ltd. |
| GE Healthcare |
| Hitachi Medical Systems |
| Samsung Medison Co., Ltd. |
| Philips Healthcare |
| Fujifilm Holdings Corporation |
| Esaote SpA |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
Matrix-array transducer certification tiers bifurcate TEE system economics between FDA-cleared premium configurations and CE-marked standard platforms, concentrating margin capture in United States academic medical centers while compressing pricing power in European hospital purchasing cooperatives negotiating total cost of ownership models. This tier divergence feeds directly into supply chain configurations: premium-tier OEMs source piezoelectric crystals through captive East Asian foundry relationships, whereas standard-tier assemblers draw from open-market component distributors exposed to input volatility.
Pricing Analysis
Volume-margin splits separate high-throughput cardiac centers pursuing 3D imaging upgrades from ambulatory surgical centers selecting compact 2D configurations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance status, probe frequency range, and software bundling depth. Pricing pressure stems from CMS reimbursement compression for intraoperative monitoring codes, narrowing per-procedure margin contribution. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, while university-affiliated cardiac centers prioritize capability over unit cost.
Supply Chain Analysis
Japan's PMDA electromagnetic compatibility standards and China's NMPA import testing requirements are reshaping sourcing strategies toward domestic-content partnerships with local shielding manufacturers and regional assembly facilities. Piezoelectric crystal supply concentrates in South Korea, Taiwan, and Japan, with precision ceramic substrate dependencies tethered to East Asian specialty materials producers. Single-source vulnerability runs through multiplane transducer foundries concentrated in the Yangtze River Delta. Distribution runs through hospital purchasing cooperatives in Germany, GPO contracts in the United States, and regional medical device clusters in Japan's Kanto region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
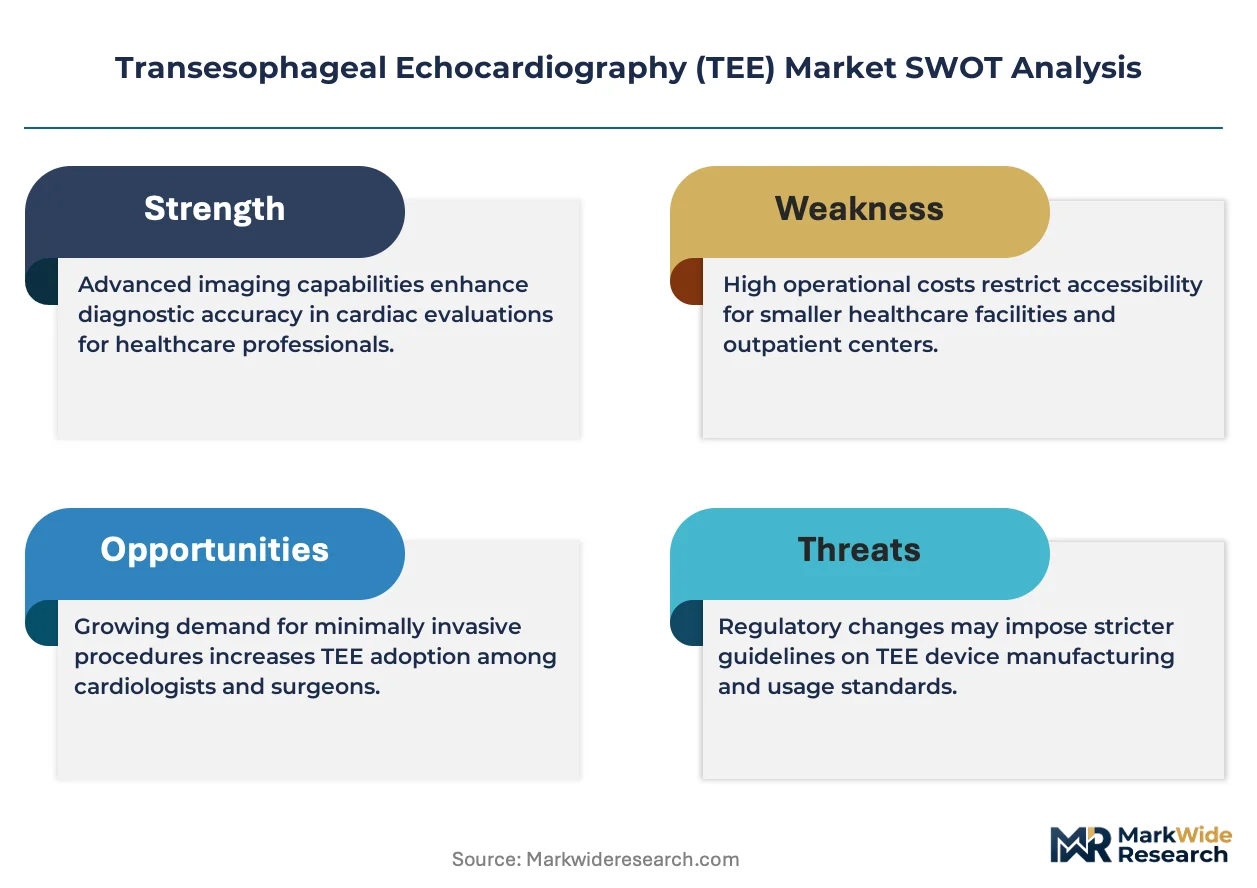
EU MDR probe reprocessing mandates have erected a cost-of-compliance moat that favors incumbents with validated sterilization protocols and clinical evidence portfolios, raising capital barriers for new entrants lacking regulatory affairs infrastructure.
For Market Incumbents: Cement service contract attach rates through predictive maintenance platforms and probe refurbishment capabilities that capture volumes fleeing OEM service divisions. Independent service organizations threaten aftermarket revenue streams; vertical integration into cloud-native archiving software preserves recurring revenue independent of hardware refresh cycles.
For New Entrants and Emerging Players: Ambulatory surgical center procurement autonomy in the United States represents the most penetrable channel, bypassing hospital-based imaging department gatekeepers. Target compact TEE configurations for space-constrained outpatient cardiac suites, leveraging direct contracting relationships with freestanding facility administrators rather than multi-hospital system committees.
For Investors and Strategic Acquirers: Re-rating potential sits with software-defined ultrasound specialists given AI-enhanced quantification algorithm adoption in interventional cardiology suites. Long-term viability over a multi-year horizon favors targets with FDA-cleared automated measurement tools and hospital system pilot contracts. Watch for PMDA accelerated approval timelines as inflection signal for non-domestic suppliers overcoming electromagnetic compatibility redesign friction.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates hospital capital expenditure on certified single-use sheaths. |
| Hospital System Partnership | Direct contracting with Germany's purchasing cooperatives fragments traditional bundled vendor relationships. |
| Software Companion Development | AI-enhanced ejection fraction tools reduce operator-dependent variability in interventional suites. |
| FDA Submission | 510(k) clearance pathways accelerate 3D imaging introductions for academic medical centers. |
| Reimbursement Strategy | CMS fee schedule navigation preserves margin contribution for intraoperative monitoring protocols. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare reimbursement data underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, echocardiography lab directors, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, PMDA approval records, and EU MDR technical documentation databases. Bottom-up installed base enumeration and top-down cardiac procedure volume estimates triangulate market sizing.
Rate-of-change decomposition across technology adoption curves, regulatory compliance timelines, and channel structure evolution shapes the analytical framework throughout the forecast period. Segmentation dimensions modeled include product architecture, end-user channel, imaging modality, and clinical application, with regional regulatory clusters capturing FDA, PMDA, and EU MDR pathway divergence. CAGRs derive from procedure volume trajectories, replacement cycle compression, and software attach rate expansion in cardiac imaging workflows.
Caveats apply where PMDA electromagnetic compatibility standard revisions or CMS reimbursement code restructuring could materially shift the outlook for non-domestic suppliers and capital equipment procurement priorities. Forecasts reflect assumptions regarding probe reprocessing validation complexity and AI algorithm regulatory clearance timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Global Computer Vision in Healthcare Market