
 Disposable Blood Pressure Cuffs Market | 2026-2036
Disposable Blood Pressure Cuffs Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Blood Pressure Cuffs Market Intelligence
Preventive maintenance and calibration subscription services is consolidating how acute-care facilities manage disposable cuff inventories, shifting capital toward operational expenditure models. Cardinal Health leverages its distribution density to sustain hospital-system contracts across North America. Philips Healthcare anchors its position through integrated vital-signs platforms that bundle disposable cuffs with monitoring hardware. SunTech Medical specializes in OEM partnerships, competing on blood-pressure algorithm compatibility rather than cuff commoditization.
Disposable blood pressure cuffs are single-patient-use inflatable bladders encased in fabric or synthetic sleeves, designed to occlude arterial flow for non-invasive sphygmomanometry and eliminate cross-contamination between clinical encounters. Adult Cuffs generate the largest revenue pool due to procedural volume in general medicine and surgical wards, though Neonatal Cuffs command premium unit economics from intensive-care precision requirements. Homecare channels represent the fastest-growing end-user segment as remote patient monitoring programs expand cuff dispensing through durable medical equipment suppliers.
FDA 510(k) clearance requirements and EMA Medical Device Regulation (MDR) conformity assessments govern material biocompatibility and sterility validation for disposable cuffs entering clinical use. The EPA and REACH frameworks additionally constrain latex and PVC formulations, pushing manufacturers toward non-woven fabric and foam alternatives with lower environmental persistence. Stakeholders must monitor how reimbursement policy for remote patient monitoring reshapes volume allocation between institutional and homecare channels.
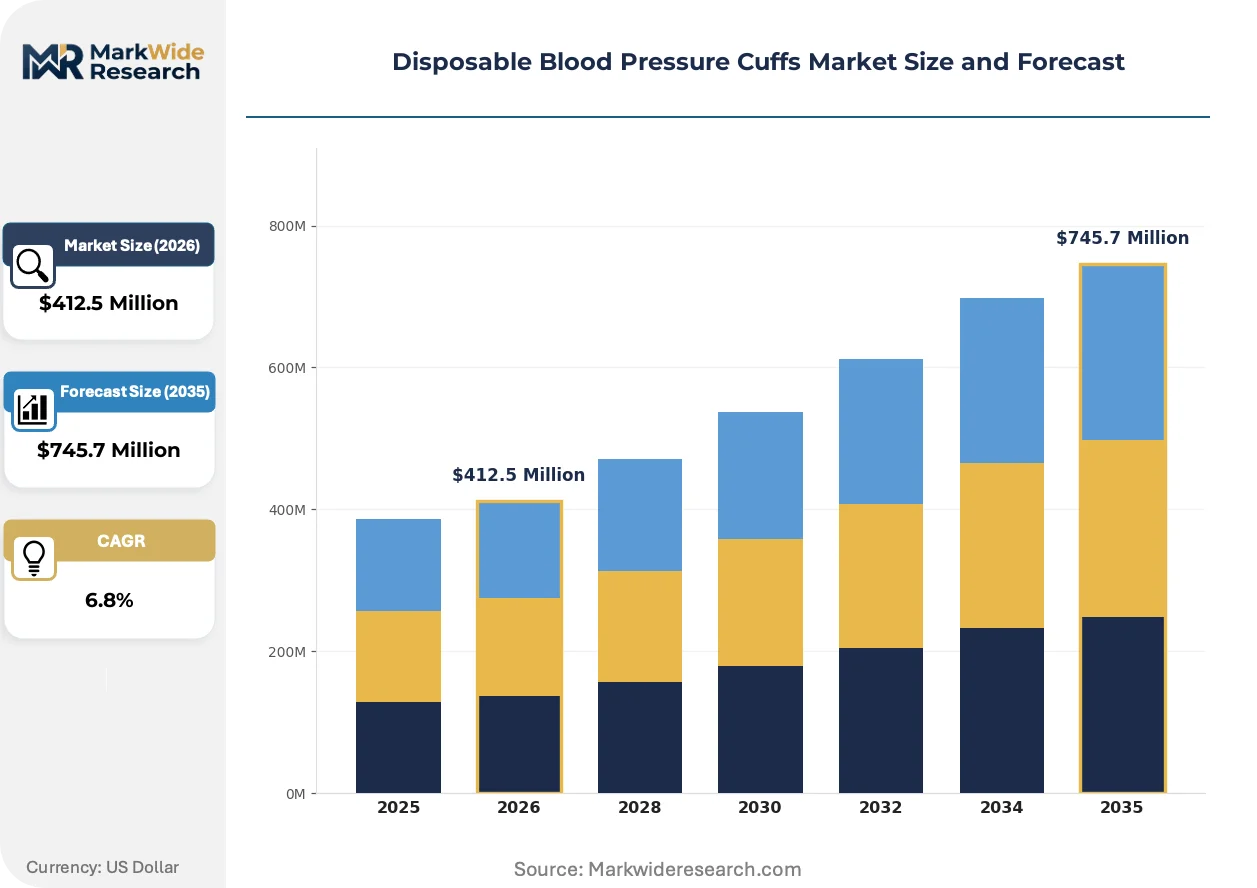
Market Dynamics
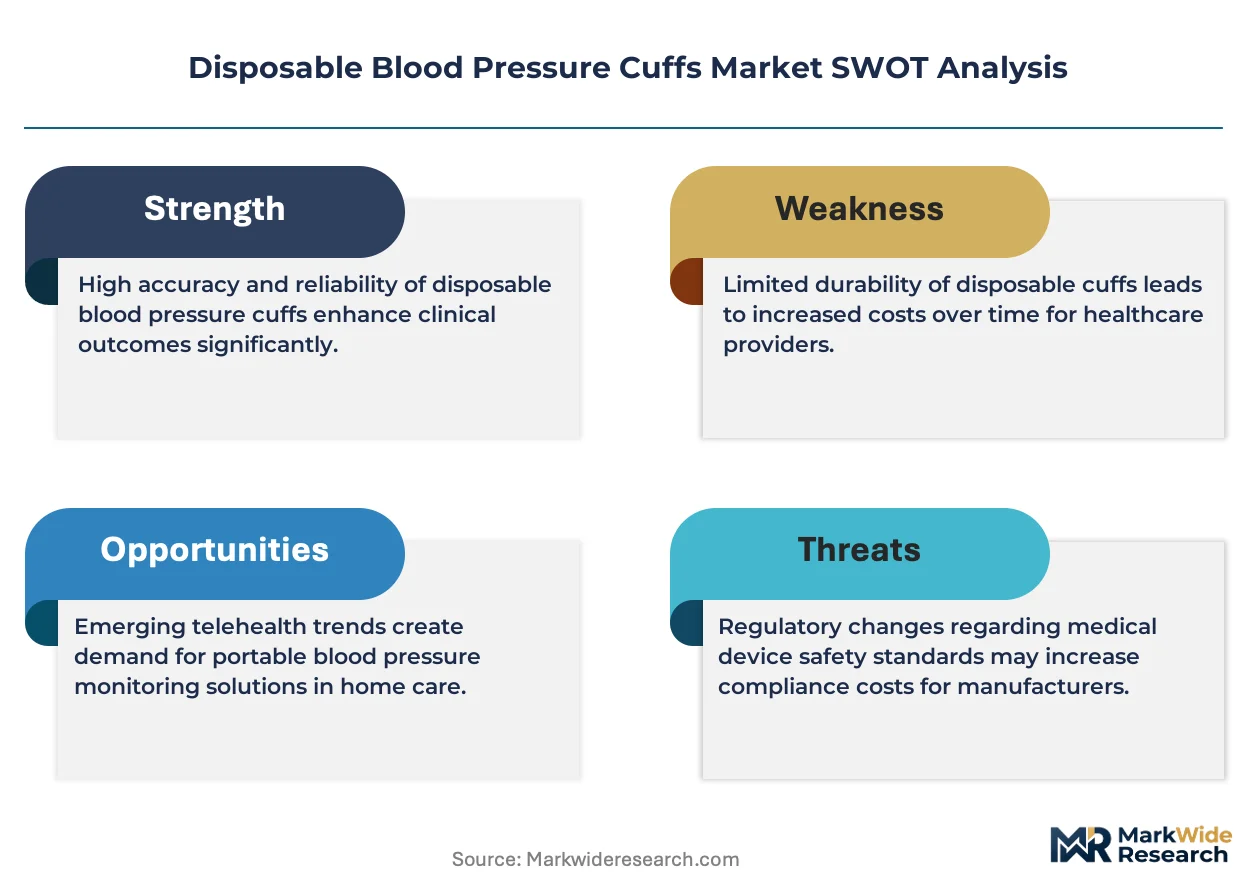
Hospital procurement departments are consolidating vendor relationships around subscription-based cuff supply programs, converting capital equipment purchases into recurring operational expenditures while embedding infection-control compliance into contract terms.
Growth Catalysts
- FDA 510(k) Infection-Control Mandates:Stricter sterility validation requirements for non-invasive blood pressure devices are compelling acute-care facilities to replace reusable cuff inventories with single-patient-use alternatives.
- Neonatal Intensive Care Precision:Specialized cuff designs for low-birth-weight infants command premium positioning as perinatal units prioritize hemodynamic accuracy over commodity cost.
- Japan's Acute-Care Bed Density:Sustained investment in geriatric surgical capacity sustains procedural volumes requiring disposable sphygmomanometry accessories.
Market Restraints
- Petrochemical Input Volatility:PVC and synthetic rubber price swings compress margin stability for manufacturers dependent on petroleum-derived bladder materials.
- Single-Source Bladder Fabrication:Concentrated supply of medical-grade non-woven laminates in Southeast Asian contract manufacturers creates geographic vulnerability.
- Reusable Cuff Durability:Extended service life of silicone-based multi-patient cuffs in dialysis and psychiatric settings limits addressable market expansion.
Strategic Opportunities
- German Ambulatory Surgery Expansion:Same-day procedure volume growth in outpatient clinics creates demand for compact, pre-sterilized cuff dispensers.
- Remote Patient Monitoring Reimbursement:United States CMS coverage expansion for home blood pressure telehealth enables durable medical equipment channel penetration.
- Wearable Sensor Convergence:Integration of oscillometric cuffs with Bluetooth-enabled vital signs monitors opens telemetry-enabled post-acute care applications.
Industry Challenges
- Biocompatibility Certification Timelines:EMA MDR conformity assessment backlogs delay market entry for novel hypoallergenic sleeve materials.
- Legacy Monitor Protocol Integration:Proprietary pneumatic connectors from incumbent vital signs manufacturers complicate universal cuff compatibility engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Blood Pressure Cuffs Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Cuffs, Pediatric Cuffs, Neonatal Cuffs, Large Adult Cuffs End User: Hospitals, Clinics, Homecare, Emergency Services Functionality: Single-Use, Multi-Use, Digital, Analog Material: Latex, Non-Woven Fabric, PVC, Foam |
| Companies Covered | Welch Allyn (Hillrom), GE Healthcare, Philips Healthcare, Cardinal Health, Omron Healthcare, Medline Industries, SunTech Medical, Baxter International, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Blood Pressure Cuffs Market Strategic Shifts & Innovations
Material science advances and regulatory stringency are compressing product lifecycles while elevating performance specifications for single-patient-use hemodynamic accessories.
Non-woven fabric bladders with thermoplastic polyurethane coatings are overtaking traditional PVC constructions in acute-care procurement specifications. Surgical wards in tertiary hospitals across Germany and Japan now specify fabric-based cuffs for 80% of new monitor deployments. This transition is compressing commodity pricing power while rewarding manufacturers with in-house polymer lamination capabilities.
REACH restrictions on phthalate plasticizers are forcing reformulation of legacy sleeve compounds across European supply chains. ECHA substance-of-very-high-concern listings for DEHP and DBP have triggered 18-month material qualification cycles for cuff suppliers serving EU member states. Pediatric and neonatal segments are responding fastest, with hospitals preemptively removing PVC-containing inventory ahead of 2025 enforcement deadlines.
Subscription inventory management is displacing spot purchasing for high-volume hospital systems. Cardinal Health and regional distributors in the United States are bundling cuff replenishment with calibration services and usage analytics. This model is most visible in integrated delivery networks consolidating purchasing across 15-plus facility footprints, where standardization reduces SKU complexity and nurse training burden.
Disposable Blood Pressure Cuffs Market Segmentation
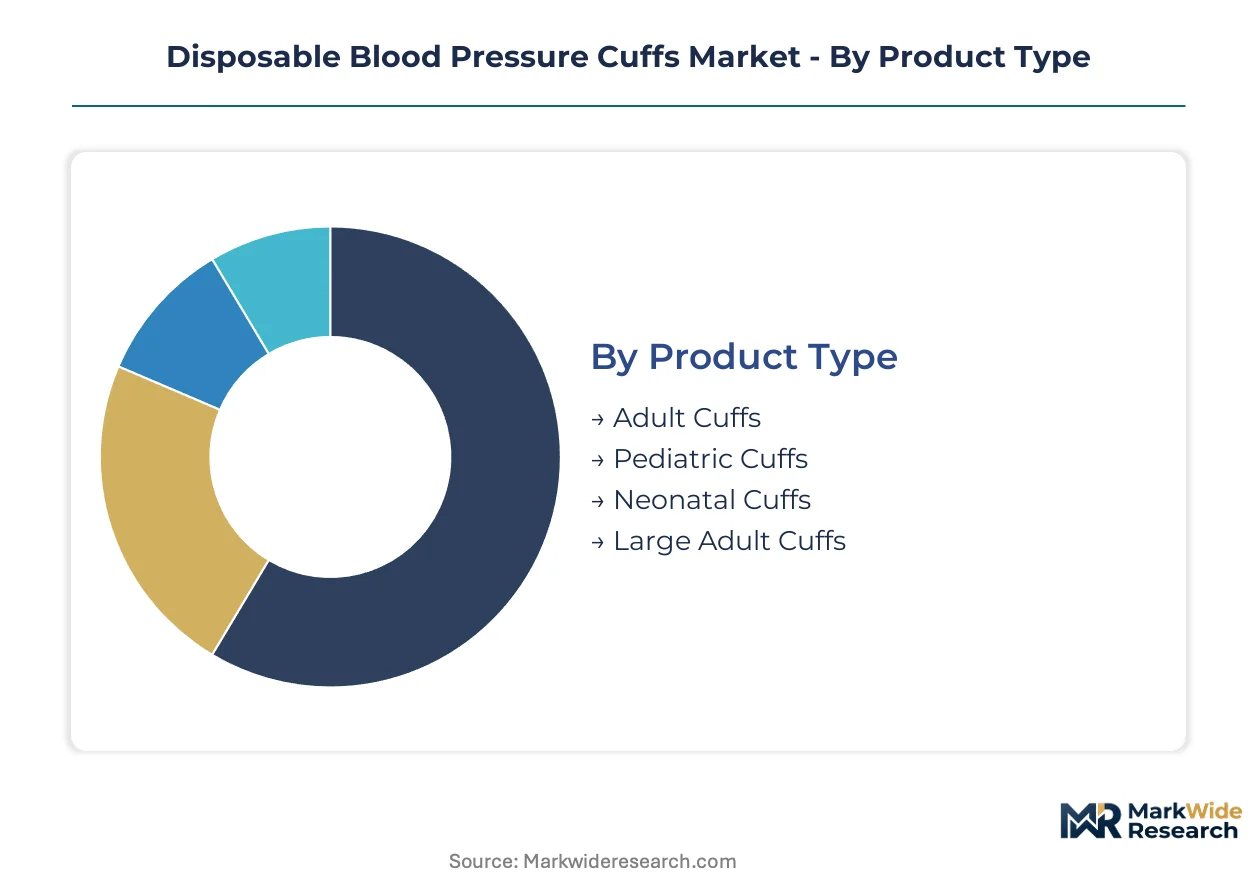
Disposable blood pressure cuff segmentation reveals how procurement priorities diverge between infection-control compliance and cost containment. Material specifications and patient-size precision determine contract winners across acute-care and ambulatory channels.
Product Type:
Standardization dominates high-volume adult applications while neonatal and bariatric segments demand engineered customization for anatomical precision.
- Adult Cuffs:Nylon-reinforced TPU bladders with hook-and-loop closures serve general medicine and surgical wards. Hospital procurement in the United States concentrates volume here for standardized monitor compatibility.
- Pediatric Cuffs:Smaller circumference ranges with color-coded sizing prevent misapplication in pediatric emergency departments. German outpatient clinics specify these for school-age vaccination programs.
- Neonatal Cuffs:Micro-bladder designs with ±2 mmHg accuracy tolerance address low-birth-weight hemodynamic monitoring. Japanese perinatal centers drive premium positioning through precision requirements.
- Large Adult Cuffs:Extended-length sleeves accommodate bariatric populations with reinforced bladder construction. Demand concentrates in US metabolic surgery units.
Most installed capacity flows through Adult Cuffs. Expansion is steepest in Neonatal Cuffs.
End User:
Channel economics separate capital-intensive institutional buyers from distributed homecare dispensing models.
- Hospitals:Integrated delivery networks negotiate subscription replenishment tied to monitor fleet size. Infection-control mandates from FDA 510(k) drive single-use conversion.
- Clinics:Ambulatory surgery centers prioritize pre-sterilized compact dispensers for same-day procedure throughput. German outpatient expansion sustains volume.
- Homecare:Remote patient monitoring reimbursement enables durable medical equipment channel penetration. CMS coverage expansion reshapes volume allocation fastest here.
- Emergency Services:Field-deployed compact packaging with rapid-application designs serves pre-hospital triage. Stock rotation requirements limit inventory depth.
Hospital procurement maintains the largest revenue pool. Homecare channels are expanding most quickly.
Functionality:
Single-patient-use protocols are displacing multi-use alternatives as regulatory sterility requirements tighten.
- Single-Use:Pre-sterilized individually packaged cuffs eliminate cross-contamination between encounters. FDA infection-control mandates compel acute-care conversion.
- Multi-Use:Silicone-based construction with disinfection protocols persists in dialysis and psychiatric settings where patient contact duration extends. Reusable durability limits addressable expansion.
- Digital:Bluetooth-enabled oscillometric integration supports telemetry for post-acute monitoring. Wearable sensor convergence opens new applications.
- Analog:Pneumatic manual inflation with mercury-free gauges serves resource-constrained settings and backup power scenarios. Legacy protocol compatibility requirements sustain niche demand.
Single-Use functionality captures dominant procurement share. Digital integration shows the steepest expansion trajectory.
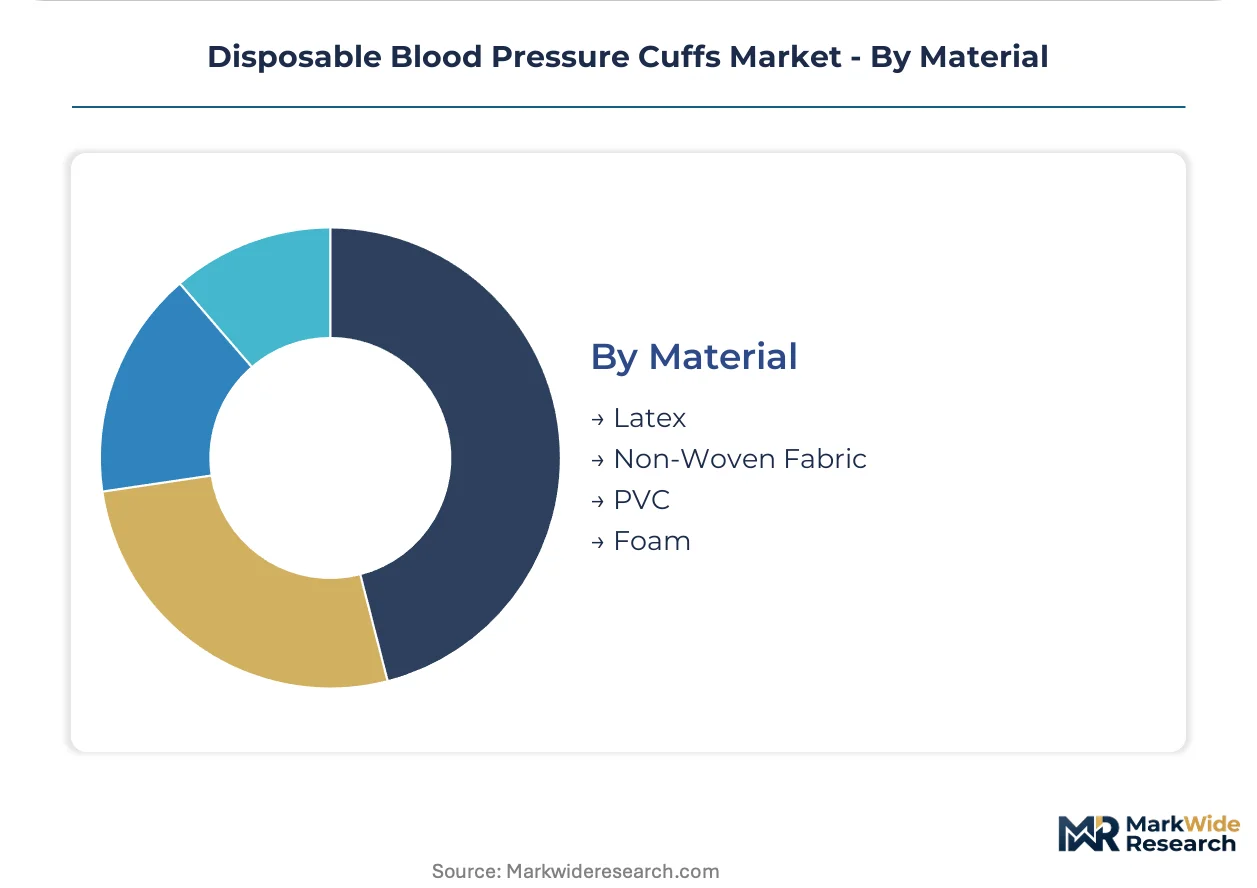
Material:
Environmental and biocompatibility regulations are forcing substitution away from petroleum-derived formulations.
- Non-Woven Fabric:Thermoplastic polyurethane-coated laminates now specify for 80% of new German and Japanese monitor deployments. REACH phthalate restrictions accelerate conversion.
- PVC:Legacy DEHP-plasticized constructions face ECHA substance-of-very-high-concern enforcement deadlines. Pediatric segments are removing inventory preemptively.
- Latex:Natural rubber bladders with protein-level certification address cost-sensitive markets. Allergy prevalence restricts penetration in developed markets.
- Foam:Polyethylene and polyurethane foam sleeves provide patient comfort in extended monitoring. Homecare channel growth sustains demand.
Non-Woven Fabric dominates new procurement specifications. Foam applications are gaining share fastest in comfort-focused segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's acute-care bed density sustains higher per-capita cuff consumption than the United States, where ambulatory surgery volumes drive outpatient channel expansion. Procurement patterns diverge sharply between institutional subscription models and distributed homecare dispensing.
United States
Hospital procurement departments consolidate vendor relationships around subscription-based cuff supply programs, converting capital equipment purchases into recurring operational expenditures. CMS coverage expansion for remote patient monitoring reshapes volume allocation toward durable medical equipment channels. Integrated delivery networks in Texas and Florida standardize purchasing across 15-plus facility footprints.
Germany
Same-day procedure volume growth in outpatient clinics creates demand for compact, pre-sterilized cuff dispensers. REACH restrictions on phthalate plasticizers force reformulation of legacy sleeve compounds across European supply chains. Medical technology clusters in Baden-Württemberg and Bavaria drive specification standards for fabric-based cuff deployments.
Japan
Sustained investment in geriatric surgical capacity sustains procedural volumes requiring disposable sphygmomanometry accessories. METI guidelines on medical device quality management tighten material traceability requirements. Perinatal centers in Tokyo and Osaka drive premium positioning for neonatal cuff precision requirements.
United Kingdom
NHS procurement frameworks emphasize infection-control compliance in non-invasive blood pressure device specifications. MHRA conformity assessments govern material biocompatibility validation for disposable cuffs entering clinical use. Hospital trusts in Greater London and the Midlands pilot subscription inventory management models.
China
Domestic manufacturing capacity expansion targets cost-sensitive hospital procurement in tier-two and tier-three cities. NMPA medical device registration requirements strengthen sterility validation protocols for single-patient-use accessories. Yangtze River Delta medical device clusters scale non-woven fabric lamination capabilities.
Disposable Blood Pressure Cuffs Market Key Industry Players
Top-tier vendors anchor hospital-system contracts through distribution density and integrated vital-signs platforms, while mid-tier specialists compete on algorithm compatibility and OEM partnerships. The vendor base stratifies across three functional tiers: diversified health technology conglomerates, regional distribution-focused suppliers, and precision-focused niche manufacturers. Two dominant competitive moves are subscription-based inventory management embedding compliance into contract terms, and material science differentiation toward non-woven fabric and thermoplastic polyurethane constructions.
Among diversified health technology conglomerates, Cardinal Health and Philips Healthcare occupy positions exemplifying scale-driven distribution and integrated platform bundling respectively. SunTech Medical represents the specialist archetype competing on blood-pressure algorithm compatibility rather than cuff commoditization. These three entities anchor the competitive structure without exhausting the vendor ecosystem.
| Leading Market Players |
|---|
| Welch Allyn (Hillrom) |
| GE Healthcare |
| Philips Healthcare |
| Cardinal Health |
| Omron Healthcare |
| Medline Industries |
| SunTech Medical |
| Baxter International |
| 3M |
| Others |
Cost & Logistics Intelligence
REACH phthalate restrictions on DEHP and DBP plasticizers gate qualified supply for European hospital procurement, reserving premium-tier pricing access to manufacturers with completed ECHA substance-of-very-high-concern compliance cycles. This regulatory filtration compresses margin stability for PVC-dependent suppliers while elevating pricing power for fabric-based cuff producers with in-house polymer lamination capabilities.
Pricing Analysis
Capacity additions in China's Yangtze River Delta medical device clusters are reshaping price floors for standard adult cuffs, intensifying cost compression in commodity segments. Three-tier pricing structure across premium, standard, and economy levels separates neonatal precision cuffs with ±2 mmHg accuracy tolerance from general medicine disposables and unbranded latex alternatives. Pricing pressure stems from petrochemical input volatility in thermoplastic polyurethane and synthetic rubber feedstocks. Ambulatory surgery centers in Germany exhibit highest price sensitivity due to same-day procedure volume economics, while Japanese perinatal centers absorb premium positioning for hemodynamic accuracy.
Supply Chain Analysis
Workforce availability constraints in Vietnam and Malaysia contract manufacturing zones are tightening throughput for medical-grade non-woven laminate production. Supply concentrates in China, Malaysia, and Germany, with raw material dependencies spanning petroleum-derived TPU resins, synthetic rubber bladders, and hypoallergenic fabric substrates. Single-source vulnerability in Southeast Asian laminate fabrication creates geographic concentration risk. Distribution runs through integrated delivery networks in the United States, regional hospital supply consortia in Germany, and durable medical equipment channels for homecare expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA 510(k) infection-control mandates and EMA MDR conformity assessments continuously refresh demand for compliant single-patient-use alternatives.
For Market Incumbents: Anticipate margin compression from REACH-driven material reformulation costs by accelerating backward integration into thermoplastic polyurethane lamination capabilities. Defend hospital-system contract tenure through embedded calibration subscription services that convert spot purchasing into recurring operational expenditure relationships. Prioritize certification investment for Bluetooth-enabled oscillometric integration ahead of wearable sensor convergence in post-acute telemetry applications. For New Entrants and Emerging Players: Durable medical equipment distributors represent the most accessible channel partner type for bypassing entrenched hospital procurement relationships. Target homecare segments where CMS reimbursement expansion for remote patient monitoring creates white-space volume allocation fastest. Exploit German ambulatory surgery clinic expansion with compact pre-sterilized cuff dispensers designed for same-day procedure throughput. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier OEM partnership specialists with blood-pressure algorithm compatibility expertise rather than commoditized cuff manufacturing. Long-term viability over the projection horizon hinges on material science differentiation toward non-woven fabric constructions with regulatory clearance runway. Watch EMA MDR conformity assessment backlog resolution as inflection indicator for novel hypoallergenic sleeve material market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Conformity Assessment Completion | Accelerates European market entry for fabric-based cuff constructions ahead of PVC enforcement deadlines. |
| Hospital System Subscription Partnership | Converts capital equipment purchases into recurring operational expenditures with embedded compliance analytics. |
| Bluetooth-Enabled Oscillometric Integration | Opens telemetry-enabled post-acute care applications through wearable sensor convergence with vital signs monitors. |
| Backward Integration into TPU Lamination | Captures margin compression from REACH-driven material reformulation by controlling polymer coating supply. |
| CMS Reimbursement Strategy Development | Enables durable medical equipment channel penetration for homecare expansion under remote patient monitoring coverage. |
Research Approach
Coverage spans the United States, Germany, Japan, and China, with primary inputs from each market's acute-care procurement ecosystem. The research combines structured interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and durable medical equipment distributors with secondary validation from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up volume modeling triangulates against top-down expenditure estimates from integrated delivery network financial disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include patient size category, end-user channel, functionality protocol, and material composition, with regional regulatory cluster as the cross-cutting analytical layer. CAGRs derive from fitted trend extrapolation adjusted for policy inflection points, with specific inputs from ambulatory surgery volume trajectories and remote patient monitoring reimbursement expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA MDR assessment backlog duration and petrochemical input price volatility. Projections reflect documented assumptions regarding infection-control mandate enforcement timing and homecare channel reimbursement stability. Material deviation in FDA sterility validation requirements or REACH substance-of-very-high-concern enforcement deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Endovascular Stent Market