
 Touch Screen Controllers Market | 2026-2036
Touch Screen Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Touch Screen Controllers Market Intelligence
Software-defined touch calibration and over-the-air sensitivity tuning is broadening what suppliers deliver beyond hardware die. Texas Instruments Incorporated leverages its analog front-end portfolio to anchor premium industrial automation contracts requiring noise immunity. Synaptics Incorporated specializes in automotive-grade controllers that sustain qualification cycles spanning multiple vehicle platform generations.
A touch screen controller is an integrated circuit that converts analog touch stimuli into digital positional data, typically operating with scan frequencies above 100 Hz and supporting multi-point coordinate reporting through I2C or SPI interfaces; its core purpose is to enable human-machine interaction in sealed, high-ambient-light environments where mechanical switches fail. Capacitive controllers dominate consumer electronics volume, while projected capacitive technology captures the margin pool in automotive infotainment where electromagnetic compliance requirements add certification overhead. Resistive controllers retain niche dominance in medical instruments and industrial automation where gloved-input reliability outweighs optical clarity demands.
FCC Part 15 emissions rules in the US, CE marking under the EU Electromagnetic Compatibility Directive, and China's GB/T 17618 standard collectively shape controller shielding architectures and testing budgets for cross-regional product families. REACH substance restrictions and RoHS substance limits in Europe are forcing die-level material declarations that extend compliance liability upstream to wafer foundries. Stakeholders must monitor how automotive OEMs reconcile ISO 26262 functional-safety grades with consumer-grade controller cost structures as cockpit display consolidation accelerates.
Market Dynamics
Automotive cockpit consolidation is forcing controller suppliers to reconcile ISO 26262 functional-safety grades with consumer-grade cost structures as single-display architectures replace distributed switch panels.
Growth Catalysts
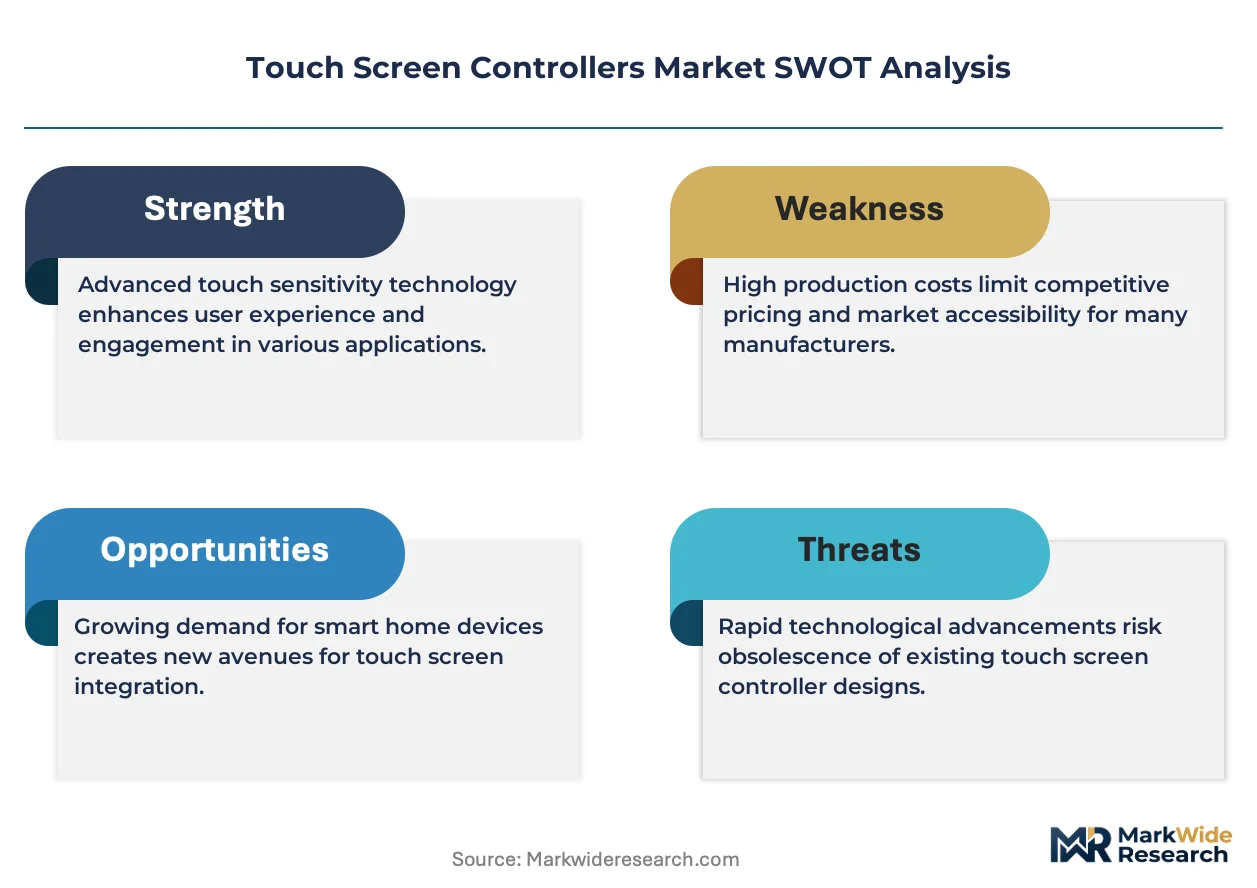
- EU Green Deal material mandates:RoHS substance limits and REACH restrictions are accelerating lead-free die architectures across European supply chains, creating upgrade cycles for legacy controller inventories.
- Curved display penetration:Automotive OEMs are integrating non-planar touch surfaces that demand flexible scan-matrix controllers with adaptive calibration algorithms.
- China captive sourcing:Domestic panel producers in Shenzhen and Hefei are scaling in-house controller design teams to reduce import dependency on Taiwanese and Korean suppliers.
Market Restraints
- Wafer foundry concentration:Advanced-node controller production concentrates at TSMC and Samsung Foundry, creating allocation risk during semiconductor demand surges.
- Indium tin oxide volatility:Transparent conductor supply constraints in projected capacitive stacks expose controller margins to rare earth price swings.
- Automotive qualification timelines:AEC-Q100 stress testing and PPAP documentation extend design-in cycles to 24-36 months, freezing supplier switches across vehicle platform generations.
Strategic Opportunities
- Haptic feedback convergence:Piezoelectric actuator integration with force-sensing controllers is opening premium automotive tier-one contracts previously held by discrete module suppliers.
- Medical device underpenetration:Sterilizable resistive controllers in surgical robotics remain underserved by capacitive-focused semiconductor portfolios.
- India PLI scheme:Domestic manufacturing incentives for electronics assembly are attracting controller packaging investments to Noida and Sriperumbudur clusters.
Industry Challenges
- EMC engineering scarcity:Automotive OEMs face shortages of engineers capable of reconciling CISPR 25 radiated emissions limits with high-scan-rate capacitive architectures.
- Legacy I2C integration friction:Industrial automation retrofit projects struggle to bridge SPI-only modern controllers with existing PLC backplanes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touch Screen Controllers Market |
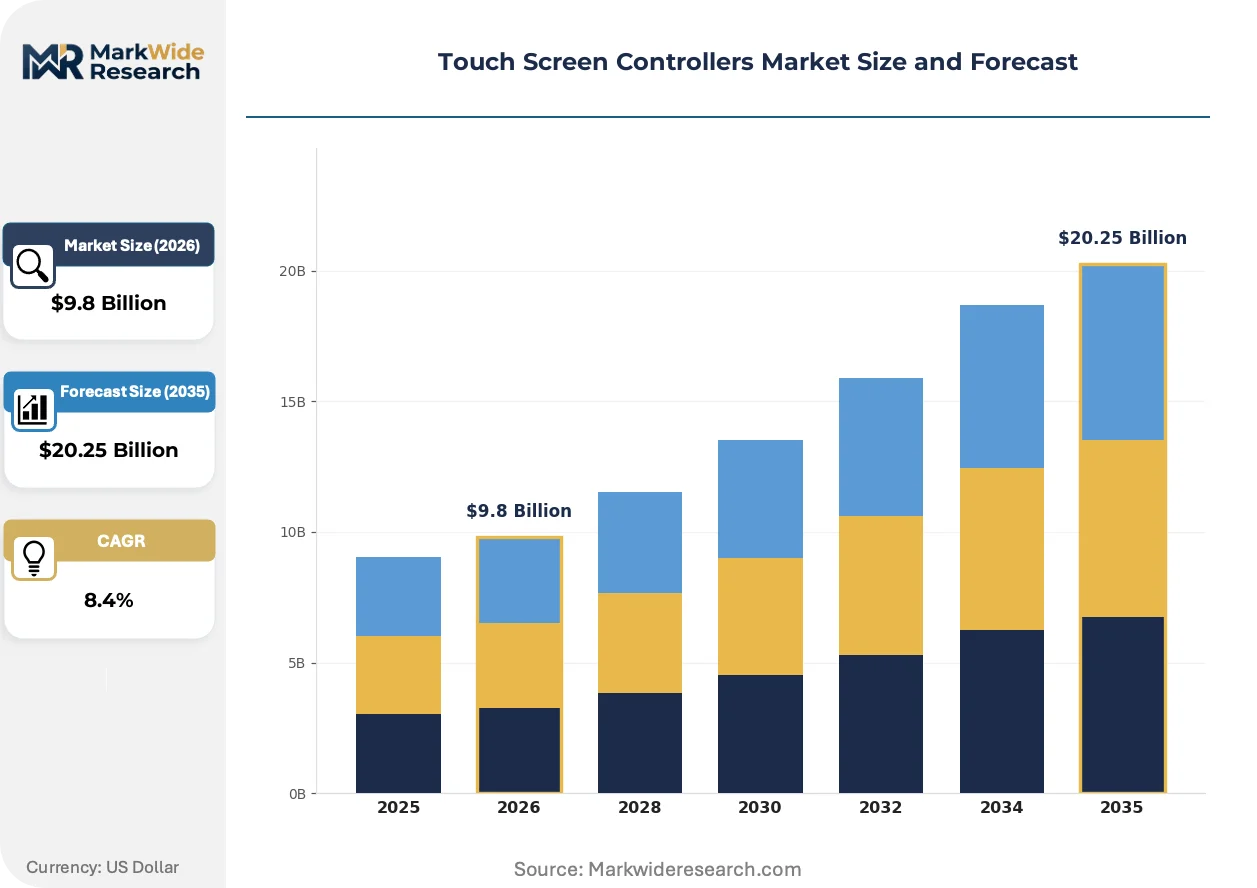
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Infrared, Surface Acoustic Wave, Optical, Dispersive Signal Technology Technology: Projected Capacitive, Mutual Capacitive, Self Capacitive, Resistive Film, Multi-Touch, Single Touch Application: Consumer Electronics, Industrial Automation, Gaming Devices, Automotive Infotainment, Medical Instruments, Aerospace Systems End User: OEMs, Aftermarket Suppliers, System Integrators, Electronic Manufacturing Services, Device Assemblers, Panel Producers |
| Companies Covered | Analog Devices Inc., Samsung Electronics Co. Ltd, NXP Semiconductors, Broadcom Limited, Synaptics Incorporated, STMicroelectronics, Microchip Technology Inc., Cypress Semiconductor Corporation, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touch Screen Controllers Market Strategic Shifts & Innovations
Touch controller architecture is bifurcating between software-defined sensitivity stacks for consumer flexibility and hardened deterministic pipelines for automotive safety integrity.
Ultrasonic force sensing is converging with traditional capacitive position detection to enable pressure-aware input recognition without dedicated mechanical buttons. Tier-one automotive suppliers in Germany and Japan are sampling fused-stack controllers for 2027 model year center consoles. This convergence is compressing the addressable market for standalone haptic module suppliers into controller-integrated solutions.
REACH substance restrictions are forcing die-level material declarations that extend compliance liability upstream to wafer foundries across European supply chains. Controller vendors must now document brominated flame retardant absence and conflict mineral status at the mask layer. Automotive infotainment programs face the highest documentation burden as they bridge consumer electronics sourcing practices with automotive quality systems.
After-sales calibration unbundling is separating sensitivity tuning from hardware shipments as automotive OEMs demand over-the-air parameter updates across fleet lifecycles. Tier-one integrators in Stuttgart and Detroit are rewriting supplier contracts to retain controller firmware ownership. This pattern is most visible in premium electric vehicle platforms where display replacement costs justify remote diagnostic investment.
Touch Screen Controllers Market Segmentation
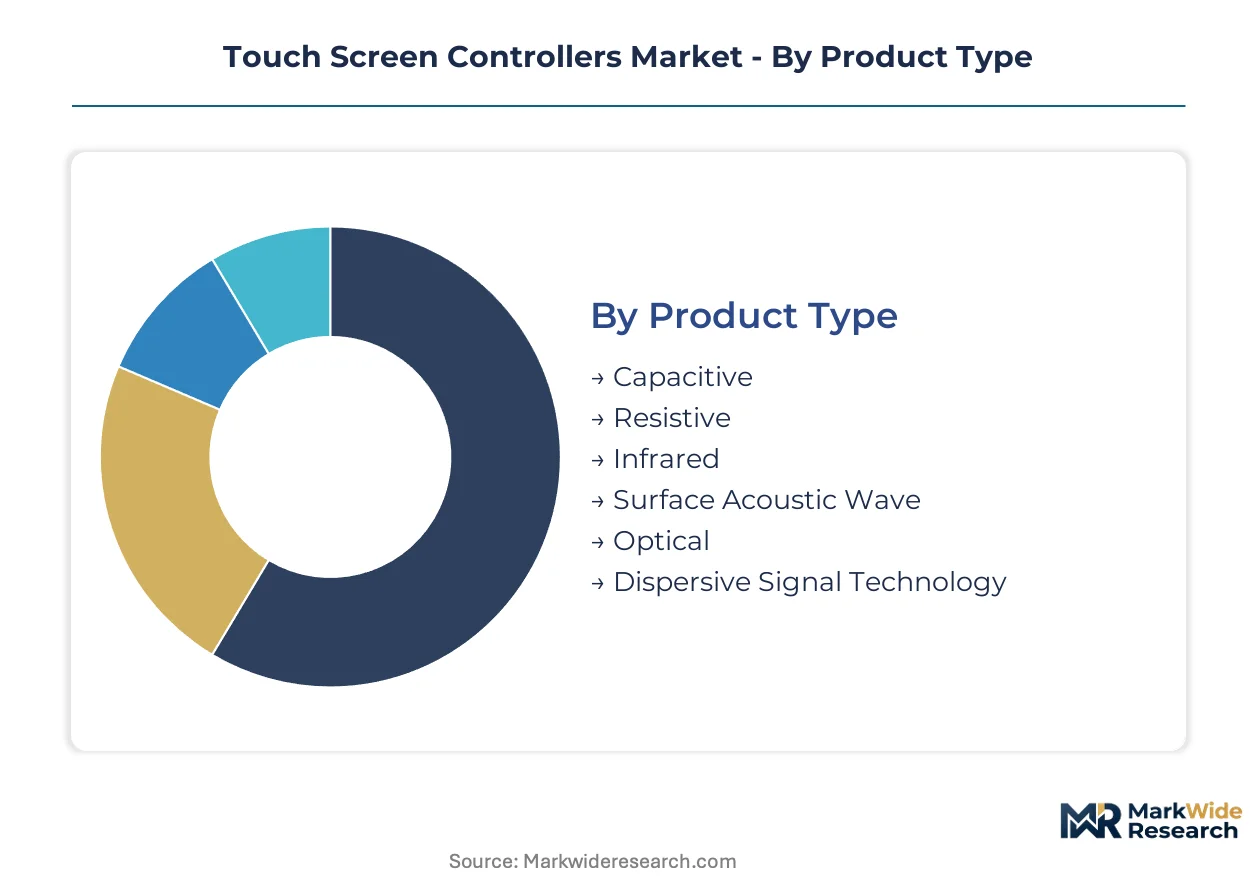
Touch screen controller segmentation reveals stark divergence between high-volume consumer applications and margin-rich automotive certification tiers. Suppliers must architect separate product lines—one chasing smartphone ASP erosion, the other capturing infotainment platform consolidation cycles.
Product Type:
Capacitive controllers dominate unit shipments while resistive variants capture margin pools in regulated environments where gloved-input reliability outweighs optical clarity.
- Capacitive:Projected capacitive architectures scan at frequencies above 100 Hz through I2C or SPI interfaces. Demand concentrates in smartphone and tablet production clusters in Shenzhen and Hefei where domestic panel producers scale captive controller sourcing to reduce import dependency on Taiwanese suppliers.
- Resistive:Four-wire and five-wire film constructions convert mechanical pressure into positional voltage divides. Medical instruments and industrial automation in Germany and Japan sustain procurement volumes where sterilization compatibility and electromagnetic immunity certification add supplier stickiness.
- Infrared:LED-phototransistor arrays detect touch interruptions without surface overlay degradation. Large-format interactive whiteboards in corporate and education deployments drive replacement cycles.
- Surface Acoustic Wave:Piezoelectric transducers launch ultrasonic waves across glass substrates with superior optical clarity. High-end retail kiosks and casino gaming terminals in Las Vegas and Macau sustain niche demand.
- Optical:Camera-based triangulation tracks touch coordinates through infrared backlighting. Interactive digital signage networks in South Korea and UAE shopping districts require controller integration with image processing pipelines.
- Dispersive Signal Technology:Bending-wave detection through piezoelectric sensors mounted at screen corners enables very-large-format touch surfaces. Museum installations and command-and-control centers in Washington DC and Brussels deploy these for durability in high-traffic environments.
Today's leader: Capacitive. Tomorrow's challenger: Resistive in surgical robotics and hazardous-area automation.
Technology:
Controller architectures bifurcate between software-defined sensitivity stacks for consumer flexibility and hardened deterministic pipelines for automotive functional safety.
- Projected Capacitive:XY electrode matrices enable multi-point coordinate reporting with mutual capacitance measurement between transmit and receive lines. Automotive infotainment systems in Stuttgart and Detroit demand these controllers for curved display integration, though AEC-Q100 qualification timelines extend design-in cycles to 24-36 months.
- Mutual Capacitive:Scan sequences measure capacitance changes at electrode intersections for robust water and glove rejection. Industrial automation panels in Japan and Germany specify these for factory-floor reliability where ISO 26262 grades intersect with consumer-grade cost constraints.
- Self Capacitive:Single-electrode measurement simplifies controller die size at the expense of multi-touch fidelity. Low-cost wearable devices and basic appliance interfaces in India and Vietnam sustain volume demand.
- Resistive Film:Pressure-activated conductive layers bridge voltage gradients through flexible substrates. Surgical robotics OEMs in Switzerland and the United States specify sterilizable variants where capacitive solutions fail autoclave compatibility.
- Multi-Touch:Controller firmware tracks ten or more simultaneous contact points with gesture recognition pipelines. Premium smartphone and tablet platforms require these for pinch-zoom and rotation input.
- Single Touch:Simplified coordinate reporting reduces die cost and power consumption for basic human-machine interfaces. Point-of-sale terminals and elevator control panels in Brazil and Mexico deploy these for cost-constrained retrofit projects.
Projected capacitive commands automotive premium pricing. Mutual capacitive gains fastest in industrial automation substitution cycles.
Application:
End-use demand fragments across consumer velocity, industrial longevity, and automotive certification intensity.
- Consumer Electronics:Smartphone, tablet, and wearable integration demands scan frequencies above 120 Hz for scrolling responsiveness. Panel producers in China concentrate procurement through captive design teams to reduce dependency on Korean and Taiwanese controller suppliers.
- Automotive Infotainment:Center console and cluster displays require electromagnetic compliance under CISPR 25 radiated emissions limits. OEMs in Germany and Japan sample fused-stack controllers combining capacitive position with ultrasonic force sensing for 2027 model year platforms.
- Industrial Automation:Programmable logic controller interfaces and machine tool panels prioritize gloved-input reliability over optical clarity. Resistive controllers retain dominance where legacy I2C integration friction complicates SPI-only modern controller adoption.
- Medical Instruments:Surgical robotics and diagnostic equipment demand sterilizable touch surfaces with ISO 13485 quality system documentation. Capacitive-focused semiconductor portfolios underpenetrate this segment.
- Gaming Devices:Arcade cabinets and casino terminals deploy surface acoustic wave and infrared technologies for vandal resistance. Macao and Las Vegas replacement cycles sustain aftermarket controller demand.
- Aerospace Systems:Cockpit display and cabin management interfaces require DO-178C software assurance and extended temperature operation. Boeing and Airbus tier-one suppliers in France and the United States qualify controllers through multi-year platform cycles.
Consumer electronics generates unit volume. Automotive infotainment captures margin expansion from display consolidation.
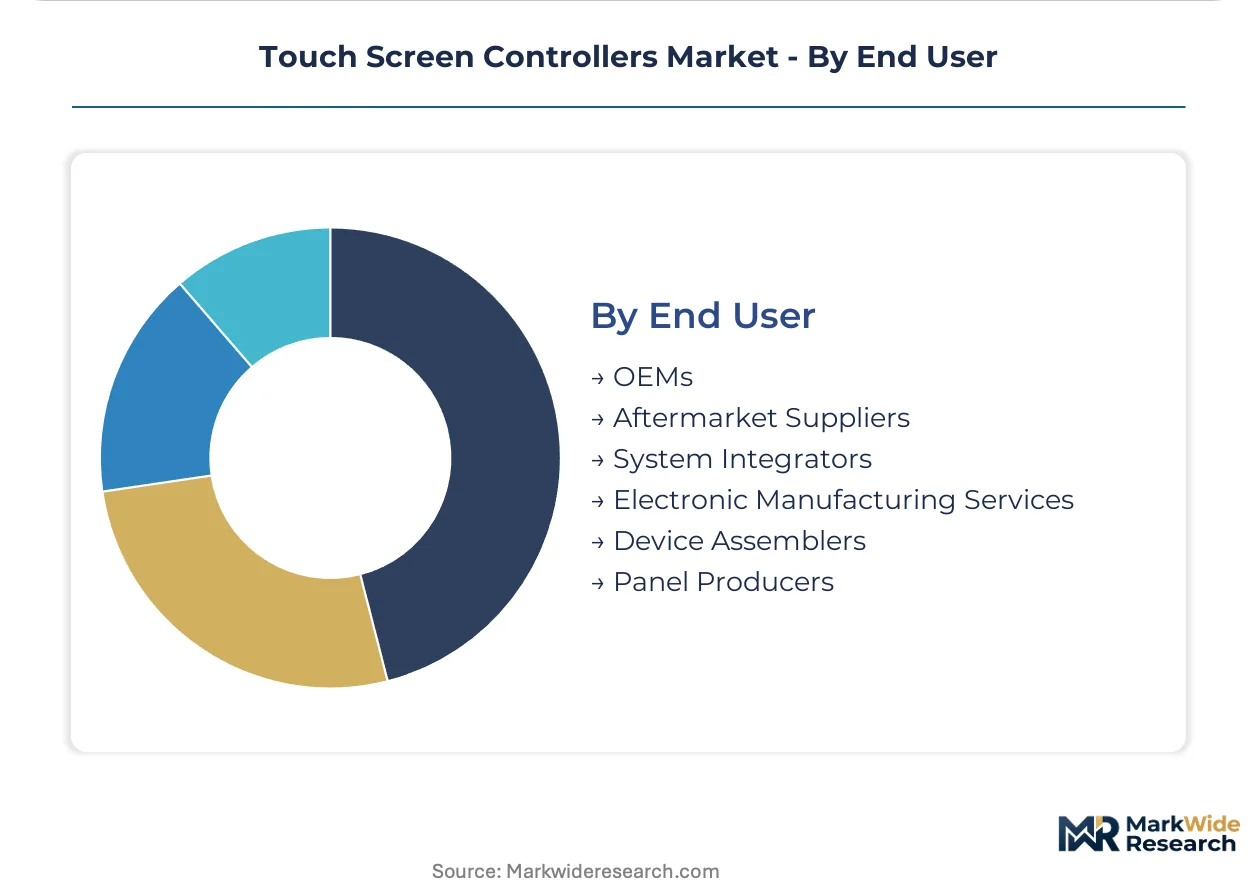
End User:
Procurement authority concentrates with panel producers and automotive tier-ones while electronic manufacturing services capture consumer electronics assembly.
- OEMs:Original equipment manufacturers in automotive and aerospace verticals retain firmware ownership and demand over-the-air calibration capability across fleet lifecycles. Stuttgart and Detroit integrators rewrite supplier contracts to unbundle sensitivity tuning from hardware shipments.
- Panel Producers:Display manufacturers in Shenzhen and Hefei scale in-house controller design teams for captive sourcing. BOE and CSOT vertical integration strategies reduce wafer foundry allocation risk during semiconductor demand surges.
- Electronic Manufacturing Services:Foxconn and Pegatron assembly operations procure controllers through consolidated component sourcing agreements. India PLI scheme incentives attract packaging investments to Noida and Sriperumbudur clusters.
- System Integrators:Industrial automation and medical device specialists configure controller sensitivity parameters for specific operating environments. German and Japanese integrators maintain engineering relationships spanning multiple hardware generations.
- Device Assemblers:Smartphone and tablet contract manufacturers match controller specifications to panel supplier roadmaps. Vietnamese and Indonesian facilities face compressed qualification timelines compared to automotive counterparts.
- Aftermarket Suppliers:Replacement display and retrofit kit distributors source controllers through secondary component markets. Repair networks in Brazil and Mexico sustain demand for legacy resistive architectures.
Panel producers control sourcing evolution. OEMs capture firmware value migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates panel production and captive controller design while Germany anchors automotive qualification standards, creating divergent sourcing logics across the two largest demand centers.
China
Domestic display manufacturers in Shenzhen and Hefei scale in-house controller teams to reduce import dependency on Taiwanese suppliers. GB/T 17618 electromagnetic compatibility standards shape shielding architectures for products bound for both domestic consumption and export markets. BOE and CSOT vertical integration strategies in the Yangtze River Delta and Pearl River Delta now extend to die-level design partnerships with local wafer foundries.
United States
Automotive OEMs in Detroit and Austin demand over-the-air calibration capabilities across fleet lifecycles, rewriting supplier contracts to retain firmware ownership. FCC Part 15 emissions rules govern controller shielding designs for cross-regional product families. Tier-one integrators in the Midwest and Texas are sampling fused-stack controllers combining position and force sensing for 2027 model year platforms.
Germany
Stuttgart-based automotive suppliers reconcile ISO 26262 functional-safety grades with consumer-grade cost structures as cockpit display consolidation accelerates. REACH substance restrictions and RoHS limits force die-level material declarations extending compliance liability upstream to wafer foundries. Bavarian and Baden-Württemberg industrial clusters sustain procurement of resistive controllers where gloved-input reliability outweighs optical clarity demands.
Japan
Industrial automation OEMs in Nagoya and Osaka specify mutual capacitive controllers for factory-floor reliability where electromagnetic immunity certification adds supplier stickiness. METI industrial standards influence scan-frequency requirements for machine tool interfaces. Precision manufacturing clusters in the Chubu region maintain engineering relationships spanning multiple hardware generations for medical instrument applications.
India
Electronics manufacturing services in Noida and Sriperumbudur expand controller packaging investments under PLI scheme incentives for domestic assembly. BIS certification requirements create localization pressure for products serving the consumer electronics and automotive aftermarket. Device assemblers in Tamil Nadu and Uttar Pradesh face compressed qualification timelines compared to automotive counterparts in Germany or Japan.
Touch Screen Controllers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with semiconductor incumbents capturing automotive certification premiums and captive design teams eroding merchant controller volumes in consumer electronics. The vendor base concentrates around three strategic archetypes: analog-front-end diversifieds, touch-focused specialists, and vertically integrated panel producers. M&A activity targets haptic feedback convergence capabilities, while capacity expansion concentrates at TSMC and Samsung Foundry for advanced-node controller production.
Within the diversified semiconductor tier, Texas Instruments Incorporated and Analog Devices Inc. anchor positions leveraging broad analog portfolios to secure industrial automation contracts. Synaptics Incorporated exemplifies the touch-specialist archetype, occupying a position shaped by automotive-grade qualification cycles spanning multiple vehicle platform generations. Samsung Electronics Co. Ltd represents the captive-integrated model, where backward control over wafer foundry capacity insulates against allocation risk during demand surges.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Samsung Electronics Co. Ltd |
| NXP Semiconductors |
| Broadcom Limited |
| Synaptics Incorporated |
| STMicroelectronics |
| Microchip Technology Inc. |
| Cypress Semiconductor Corporation |
| Texas Instruments Incorporated |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap controller specialists in Taiwan and Korea anchor pricing discipline through captive foundry relationships, while their private-equity-rolled counterparts in Europe chase volume through aggressive die-cost amortization. This ownership bifurcation shapes how supply responds to automotive OEM contract terms versus consumer electronics spot purchasing.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for capacitive controllers as BOE and CSOT in-house design teams bypass merchant vendor premiums. Pricing stratifies across automotive-grade AEC-Q100 certified tiers, industrial ISO 26262 compliant tiers, and consumer economy tiers. Cost compression in smartphone-bound controllers is intensifying because domestic Chinese panel producers substitute captive sourcing for Taiwanese imports. Device assemblers in Vietnam and Indonesia exhibit the highest price sensitivity, while Stuttgart and Detroit automotive OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Hsinchu, and Seoul operate hub-and-spoke patterns for controller die shipments to panel integration facilities. Wafer fabrication concentrates in Taiwan, South Korea, and mainland China, with advanced-node production drawing from TSMC and Samsung Foundry capacity. Indium tin oxide for projected capacitive stacks, ABF substrate for high-pin-count packages, and rare earth elements for piezoelectric haptic integration constitute critical input dependencies. Single-source vulnerability at foundry level exposes allocation risk during semiconductor demand surges. Distribution runs through tier-one automotive integrators in Germany and Japan, EMS consolidators Foxconn and Pegatron, and direct OEM contracts for aerospace applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Automotive cockpit consolidation shifts procurement authority toward OEMs demanding ISO 26262 functional-safety grades that resist commodity pricing.
For Market Incumbents: Anticipate margin compression from Chinese captive sourcing by accelerating AEC-Q100 qualification pipelines for curved display architectures. Defensive consolidation through haptic feedback module acquisition addresses the threat of piezoelectric actuator suppliers encroaching on controller-integrated solutions. Certification investment in REACH-compliant material declarations extends compliance liability protection upstream to wafer foundries. For New Entrants and Emerging Players: Surgical robotics OEMs in Switzerland and the United States represent an underserved buyer archetype where sterilizable resistive controllers face capacitive-focused incumbent neglect. White-space targets include hazardous-area automation panels requiring gloved-input reliability and medical device ISO 13485 quality system documentation. A go-to-market angle pairing force-sensing firmware with autoclave-compatible hardware packages bypasses established automotive qualification barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among touch-focused specialists lacking automotive platform generation spans. Long-term viability over a multi-decade window hinges on software-defined calibration ownership as OEMs rewrite contracts for over-the-air fleet updates. Acquisition target archetypes include haptic feedback convergence capabilities and ultrasonic force-sensing IP. The signal to watch is Tier-one automotive sampling volumes for fused-stack controllers combining position and pressure detection.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Qualification Pipeline | Automotive OEMs in Stuttgart extend design-in cycles across multiple vehicle platform generations. |
| Haptic Feedback Module Acquisition | Piezoelectric actuator integration compresses addressable market for standalone module suppliers. |
| REACH-Compliant Material Declaration | Die-level documentation extends compliance liability upstream to European wafer foundries. |
| Over-the-Air Calibration Platform | Firmware ownership migration rewrites supplier contract structures for fleet lifecycle revenue. |
| Surgical Robotics Controller Development | Sterilizable resistive architectures address ISO 13485 quality system gaps in capacitive portfolios. |
Research Approach
Multiple input streams — controller procurement managers at panel producers, automotive Tier 1 supplier engineering directors, EMS component sourcing leads, and industrial automation system integrators — were reconciled against customs records, SEC semiconductor segment disclosures, AEC-Q100 qualification databases, and GB/T electromagnetic compatibility filings. Bottom-up unit shipment estimates from Shenzhen and Hefei production clusters were triangulated against top-down wafer foundry capacity allocation data.
Data-stream reconciliation across the projection horizon applied segmentation by controller architecture type, end-use certification tier, and regional sourcing pattern. Automotive content-per-vehicle trajectories and smartphone panel shipment forecasts supplied industry-specific volume anchors. CAGRs were derived from fitted growth curves calibrated to historical qualification cycle durations and foundry capacity expansion announcements.
Underlying measurement precision varies by segment; consumer electronics procurement through consolidated EMS agreements carries tighter precision than aerospace DO-178C qualification programs with extended platform cycles. Forecasts reflect documented assumptions regarding wafer foundry allocation continuity and automotive cockpit consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio Power Amplifier Market
Electronic Components
Distribution Components Market
Electronic Components
Americas MPU Market
Electronic Components
Touchless Tubes Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Braking Resistors Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Breadboards Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Electronic Wipe Market
Electronic Components
Gigabit Interface Converter Market