
 Touchless Tubes Market | 2026-2036
Touchless Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Touchless Tubes Market Analytics
Pharmaceutical-grade barrier specifications is rotating through the touchless tubes landscape as hygiene protocols harden across end-use sectors. AptarGroup leverages its sensor-integrated dispensing portfolio to anchor North American supply relationships with institutional buyers. Albea Group sustains European manufacturing density through specialized cosmetic and pharmaceutical tube lines. Berry Global competes on polymer formulation breadth, extending its position in antimicrobial surface technologies for high-touch environments.
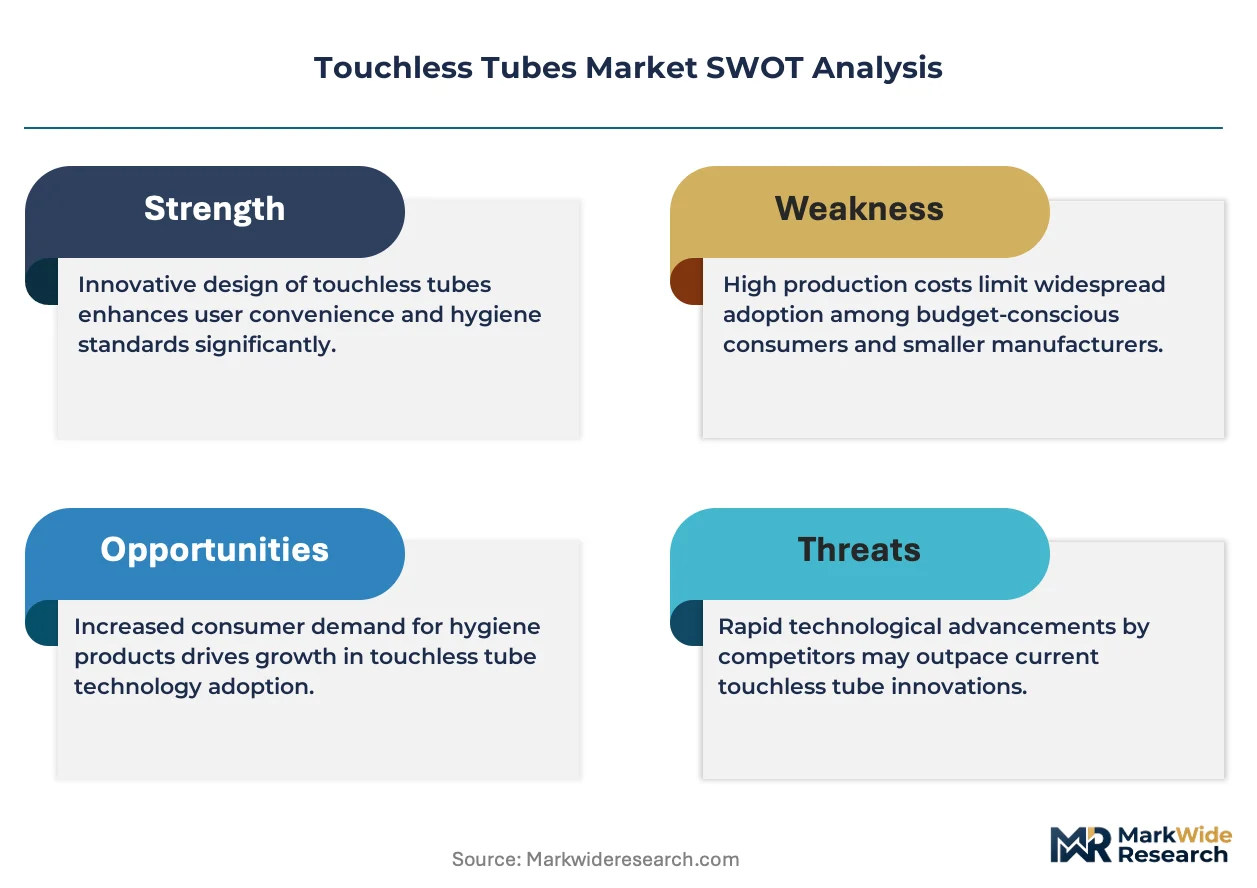
Touchless tubes are sealed cylindrical containers equipped with proximity-activated dispensing mechanisms, typically incorporating infrared or capacitive sensors, silicone valve actuators, and multilayer polymer barriers to prevent back-contamination. These systems deliver measured product doses without direct hand contact, serving infection prevention protocols in healthcare, food service, and personal care settings. The technology dimension shows infrared and capacitive variants capturing margin pools due to their reliability in moisture-heavy environments, while ultrasonic configurations remain nascent but gain traction in premium automotive applications. Among end users, hospitals and airports represent the most structurally concentrated demand segments, with procurement decisions increasingly bundling touchless infrastructure into broader hygiene system contracts.
FDA medical device sanitation standards and EPA antimicrobial claims regulations shape product validation requirements for US-market touchless tube systems, while REACH compliance in Europe constrains polymer and coating chemistries available to manufacturers. ISO 22196 antimicrobial surface testing provides a cross-border benchmark that buyers increasingly specify in tenders. Stakeholders must monitor how fragmented national hygiene codes evolve toward harmonized technical standards, as this convergence will determine which sensor-platform and material combinations achieve scalable certification.
Market Dynamics
Ultrasonic sensor miniaturization is compressing unit economics for premium touchless dispensing systems, enabling mass-market penetration beyond healthcare into food service and automotive interiors.
Growth Catalysts
- FDA Sanitary Device Guidelines:Post-pandemic enforcement of medical device interface standards in the United States is mandating proximity-activated dispensing in hospital procurement contracts.
- Silicone Valve Actuation:Advances in elastomer precision molding are eliminating mechanical wear points, extending product lifecycle in high-frequency healthcare deployments.
- Germany:Federal hospital modernization programs are bundling touchless infrastructure into hygiene-critical ward renovations, concentrating demand among institutional buyers.
Market Restraints
- Polymer Feedstock Volatility:Multilayer barrier films depend on specialty polyethylene and EVOH resins subject to petrochemical price swings.
- East Asian Sensor Concentration:Infrared and capacitive sensor module production clusters in Taiwan and South Korea, creating single-source vulnerability for Western assemblers.
- REACH Chemical Restrictions:European coating and antimicrobial additive formulations face recurring substance authorization delays, compressing available material palettes.
Strategic Opportunities
- India:Hospital accreditation standards under the National Accreditation Board for Hospitals are newly mandating touchless dispensing in tertiary care facilities, opening greenfield installation demand.
- Automotive Cabin Hygiene:Premium vehicle interiors are integrating touchless sanitizer tubes into center console modules, creating a specification channel distinct from institutional procurement.
- ISO 22196 Harmonization:Cross-border antimicrobial surface testing standards are enabling certificate portability, reducing re-certification costs for multi-market product lines.
Industry Challenges
- Embedded Firmware Talent Scarcity:Proximity sensor calibration and power-optimization engineering skills concentrate in consumer electronics hubs, creating hiring friction for industrial tube manufacturers.
- Legacy Dispenser Retrofit Complexity:Mechanical pump infrastructure in existing healthcare and food service installations requires custom mounting adapters, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touchless Tubes Market |
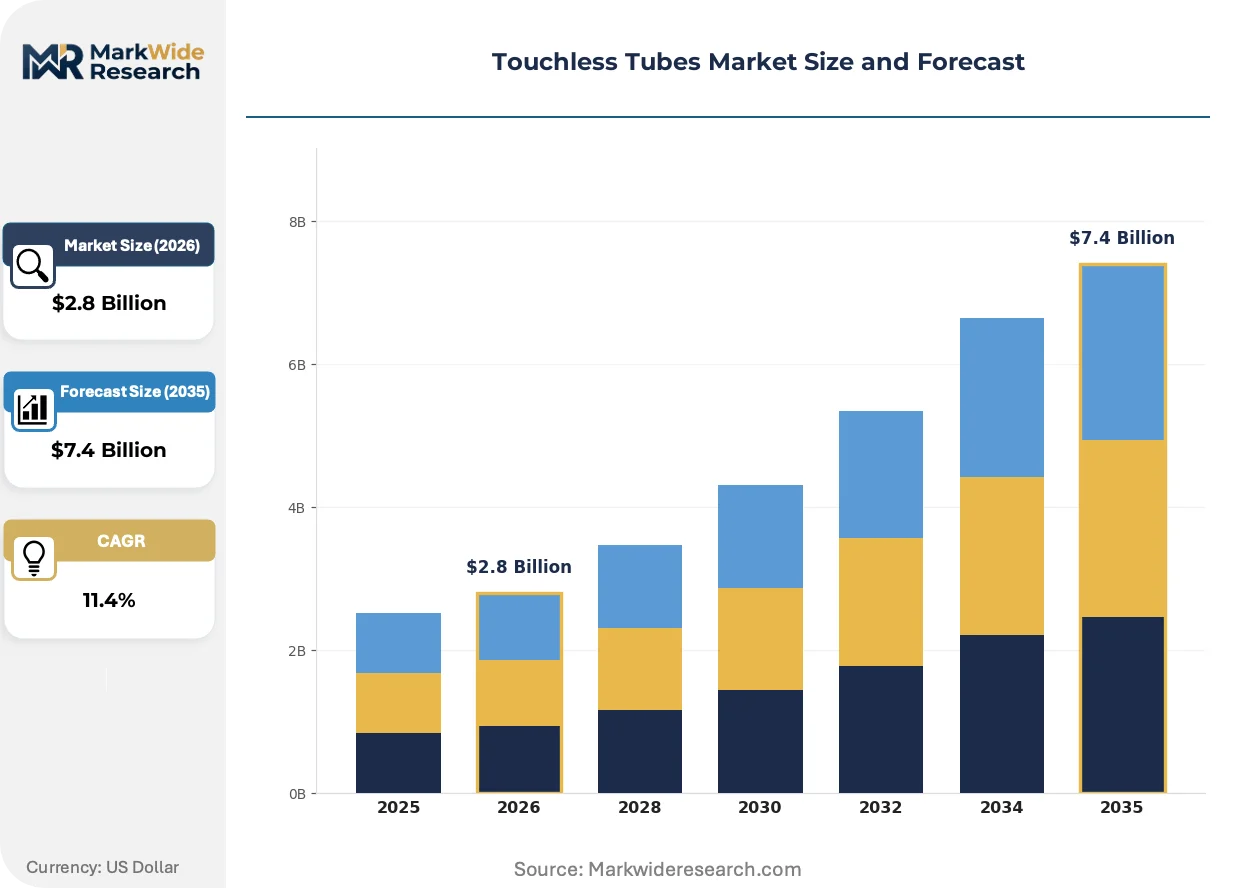
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Actuators, Connectors, Components Technology: Ultrasonic, Infrared, Capacitive, Optical Application: Healthcare Facilities, Public Restrooms, Automotive, Home Automation End User: Hospitals, Airports, Restaurants, Retail Stores |
| Companies Covered | AptarGroup, Albea Group, Berry Global, Silgan Holdings, CCL Industries, Amcor, WWP Beauty, Raepak Limited, Alltub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touchless Tubes Market Evolving Landscape
Capacitive sensing architectures are overtaking infrared in moisture-heavy environments, while regulatory pressure on antimicrobial claims is forcing material science investment. Procurement patterns are consolidating around hygiene system integrators rather than component vendors.
Ultrasonic proximity detection is displacing legacy infrared arrays in premium dispensing applications. German automotive suppliers are specifying millimeter-wave sensors for cabin sanitizer modules to eliminate false triggers from temperature fluctuations. This displacement is compressing the addressable market for conventional photoelectric components in high-reliability segments.
REACH substance authorization timelines are extending from eighteen to thirty-six months for novel antimicrobial coatings. European tube manufacturers are retreating to established silver-ion formulations rather than risking pipeline delays with experimental chemistries. Personal care brands with pan-European distribution are most affected, accelerating reformulation cycles to maintain shelf access.
Integrated hygiene system contracts are consolidating sensor, dispenser, and consumable procurement under single-source agreements. Airport authorities and hospital networks are bypassing component vendors to negotiate directly with full-stack providers. This pattern is most visible in the United States, where GPOs are rewriting supplier qualification criteria around bundled service capabilities.
Touchless Tubes Market Segmentation
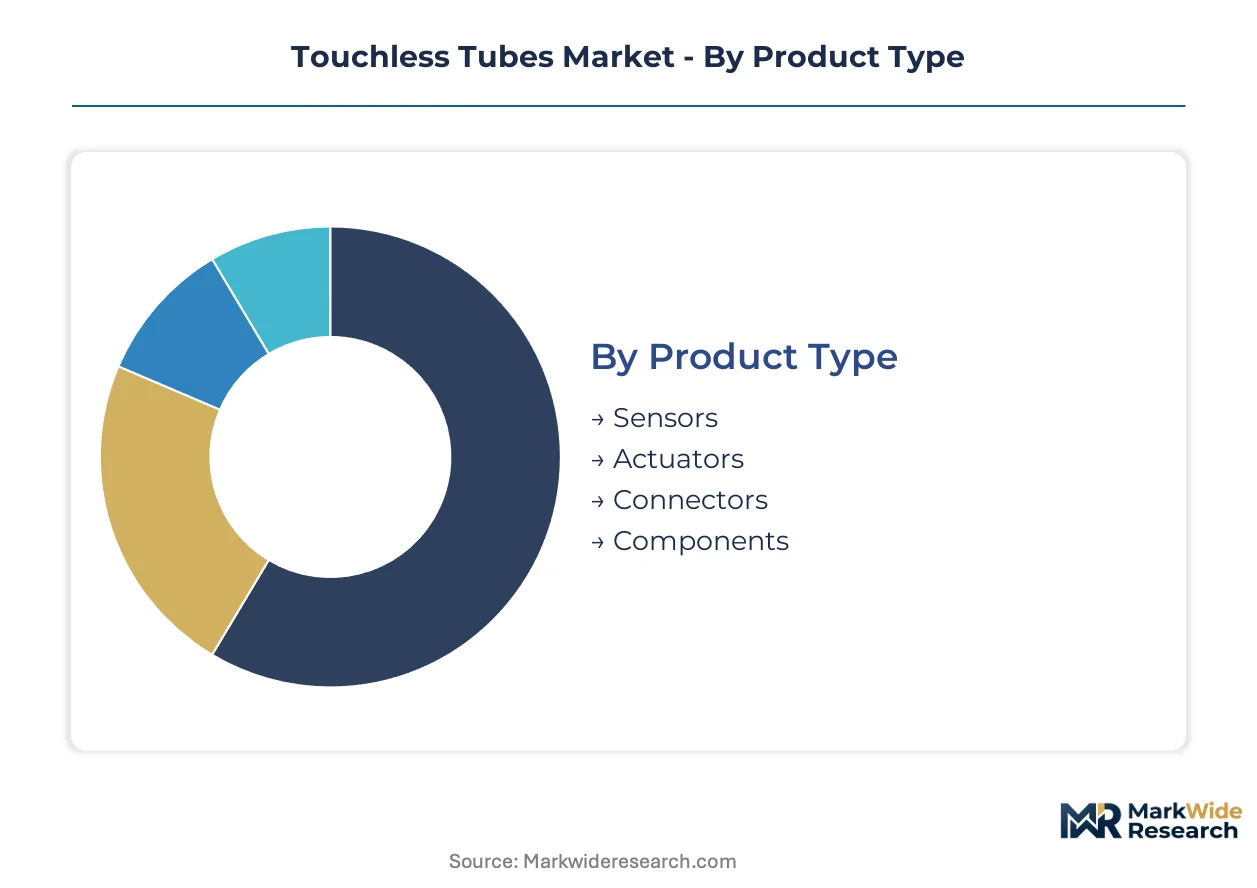
Touchless tube systems fragment across four distinct segmentation axes, each governing different procurement logics and margin structures. Component-level specifications determine technical performance, while application context dictates regulatory compliance burdens and volume economics.
Product Type:
Margin pools concentrate in precision-engineered subassemblies where sensor integration complexity creates defensible supplier positions.
- Sensors:Infrared and capacitive proximity detectors form the core activation layer, with multilayer PCB architectures and moisture-sealed housings commanding premium positioning. Demand clusters in German hospital modernization programs, where federal procurement mandates specify minimum IP67 ingress protection for ward installations.
- Actuators:Silicone valve mechanisms with precision-molded elastomer geometries enable measured dose delivery without mechanical wear. FDA sanitary device guidelines in the United States are mandating platinum-cured silicone grades for medical deployments, narrowing qualified supplier bases.
- Connectors:Quick-disconnect fluidic couplings with antimicrobial surface treatments.
- Components:Multilayer polymer barrier films and housing assemblies.
The dominant share belongs to Sensors, while Actuators is closing the gap fastest.
Technology:
Technology selection maps directly to environmental reliability requirements and false-trigger tolerance thresholds.
- Ultrasonic:Millimeter-wave proximity detection eliminates temperature drift vulnerabilities that plague infrared arrays. German automotive suppliers specify these for cabin sanitizer modules, creating a specification channel distinct from institutional procurement with higher engineering service attach rates.
- Infrared:Legacy photoelectric arrays with established supply chains and compressed unit economics dominate high-volume healthcare deployments. Taiwan and South Korean manufacturing clusters control module production, creating single-source vulnerability for Western assemblers.
- Capacitive:Field-effect architectures with moisture-compensated algorithms.
- Optical:Structured-light and time-of-flight variants for precision dispensing.
Infrared retains volume leadership, though Ultrasonic expands most quickly in premium segments.
Application:
Application context determines certification burden and procurement decision-maker identity.
- Healthcare Facilities:Infection control protocols in United States acute care settings mandate proximity-activated dispensing under Joint Commission accreditation standards. Bundled hygiene system contracts consolidate sensor, dispenser, and consumable procurement under single-source agreements, favoring full-stack providers over component vendors.
- Public Restrooms:High-frequency commercial installations with standardized form factors and compressed replacement cycles.
- Automotive:Premium vehicle interiors integrate touchless sanitizer tubes into center console modules, with millimeter-wave specifications creating technology differentiation.
- Home Automation:Consumer electronics integration with voice-assistant connectivity and aesthetic design priorities.
Healthcare Facilities command the dominant position, while Automotive climbs fastest on specification value.
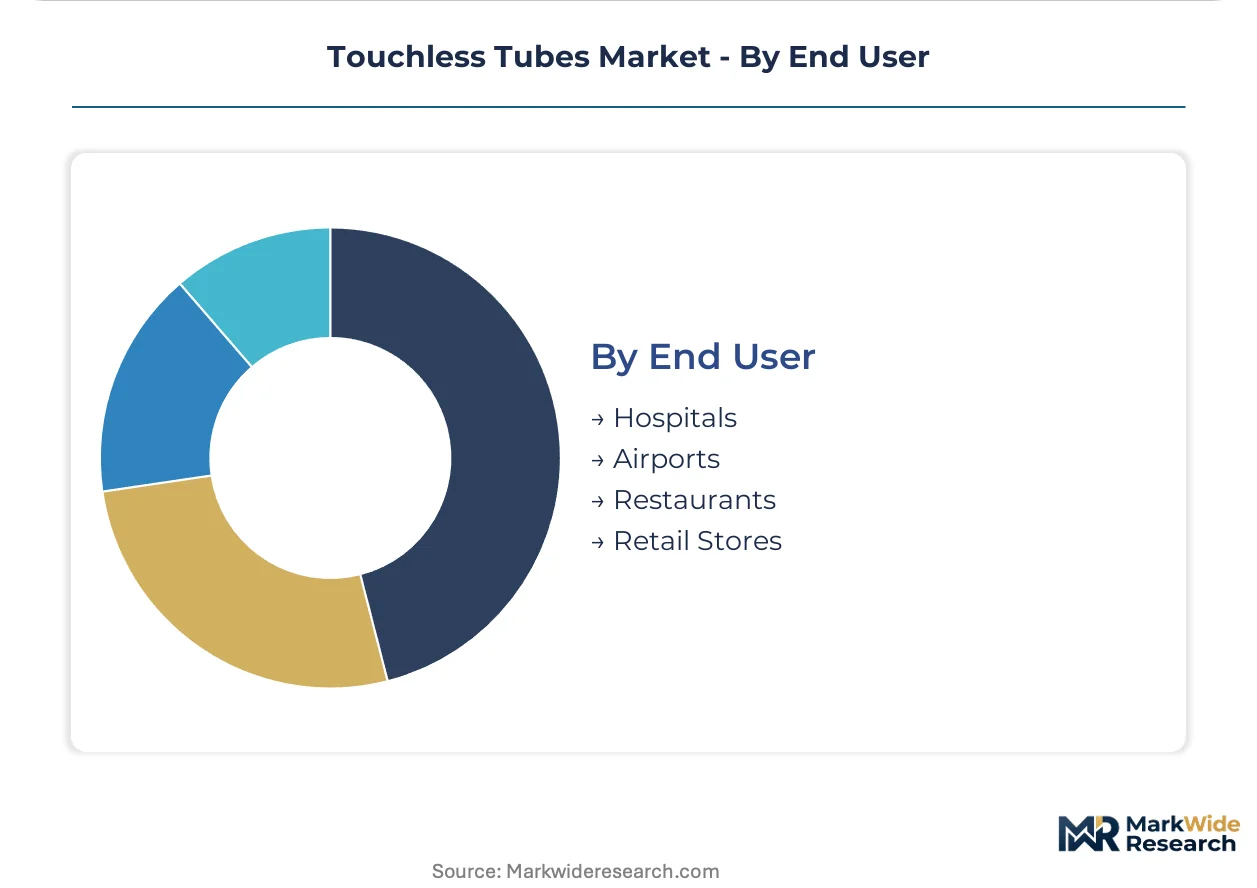
End User:
End-user concentration shapes channel strategy and service model requirements.
- Hospitals:Tertiary care facilities under India's National Accreditation Board for Hospitals face newly mandated touchless dispensing requirements, opening greenfield installation demand. Group purchasing organizations in the United States rewrite supplier qualification criteria around bundled service capabilities.
- Airports:Authority-level procurement with integrated hygiene system contracts bypassing component vendors.
- Restaurants:Food service chains with high-frequency usage patterns and standardized maintenance protocols.
- Retail Stores:Customer-facing installations with brand experience and aesthetic priorities.
Hospitals anchor the largest share, while Airports gains ground fastest on infrastructure bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty polymer compounding and sensor module assembly concentrate in Taiwan, South Korea, and Germany, creating distinct supply corridors for touchless tube manufacturers serving institutional buyers across three continents.
United States
FDA sanitary device guidelines and Joint Commission accreditation standards mandate proximity-activated dispensing in acute care facilities. Hospital group purchasing organizations bundle touchless infrastructure into hygiene system contracts, consolidating procurement under full-stack providers. Greater Boston and the Pacific Northwest host sensor calibration engineering clusters serving medical device OEMs.
Germany
Federal hospital modernization programs prioritize hygiene-critical ward renovations, concentrating institutional demand for IP67-rated sensor housings. REACH chemical restrictions constrain coating formulations, pushing manufacturers toward established silver-ion antimicrobials. Baden-Württemberg's automotive supplier ecosystem specifies millimeter-wave sensors for premium cabin sanitizer modules.
China
Domestic hospital accreditation standards under NMPA guidance increasingly specify touchless dispensing in tertiary care construction. Dual carbon goals accelerate polymer lightweighting investments for barrier film production. The Yangtze River Delta hosts multilayer extrusion equipment clusters supplying regional tube converters.
India
National Accreditation Board for Hospitals mandates touchless dispensing in new tertiary care facilities, opening greenfield installation demand. CDSCO medical device regulations align with ISO 22196 antimicrobial surface testing for certificate portability. Maharashtra and Karnataka concentrate pharmaceutical packaging converters upgrading to sensor-integrated lines.
South Korea
MFDS medical device standards and MFDS GMP requirements shape validation protocols for healthcare-deployed dispensing systems. Capacitive sensor module production clusters in Gyeonggi Province supply Western assemblers, creating single-source vulnerability exposure. Seoul-based electronics houses provide firmware engineering services for proximity calibration algorithms.
Touchless Tubes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision sensor integrators commanding premium positioning while polymer specialists compete on formulation breadth. The vendor base spans multinational packaging conglomerates, regional tube converters, and specialized sensor-assembly houses. Three archetypes dominate: full-stack hygiene system providers, component-focused material suppliers, and automotive-tier electronics integrators. Capacity expansion in multilayer barrier films and strategic partnerships between sensor houses and tube manufacturers represent the dominant competitive moves.
Within the multinational packaging tier, AptarGroup, Albea Group, and Berry Global exemplify divergent strategic positions. AptarGroup anchors North American institutional supply relationships through sensor-integrated dispensing portfolios. Albea Group sustains European manufacturing density via specialized pharmaceutical and cosmetic tube lines. Berry Global occupies the polymer formulation breadth position, extending into antimicrobial surface technologies for high-touch environments. These three players represent how scale, geography, and technical specialization segment competitive space without any single archetype commanding unified leadership.
| Leading Market Players |
|---|
| AptarGroup |
| Albea Group |
| Berry Global |
| Silgan Holdings |
| CCL Industries |
| Amcor |
| WWP Beauty |
| Raepak Limited |
| Alltub |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Taiwanese sensor module foundries shapes both supply concentration and price floors for touchless tube systems, compressing margins for Western assemblers while elevating procurement leverage for volume buyers in United States hospital networks.
Pricing Analysis
FDA sanitary device guidelines dictate the pricing tier structure for touchless tube systems, separating platinum-cured silicone actuators for medical deployments from standard elastomer grades for commercial installations. Price differentiation rests on certification tier and volume scale, with GPO-negotiated contracts commanding 40% discounts over spot procurement. Cost compression in infrared sensor modules is intensifying because East Asian manufacturing clusters are expanding die-level output. Food service chains exhibit the highest price sensitivity, while German automotive cabin hygiene specifications tolerate premium engineering service attach rates.
Supply Chain Analysis
Inventory buffers for multilayer EVOH barrier films currently stretch to sixteen weeks, exposing converters to petrochemical price volatility. Component sourcing draws from Taiwan and South Korea for infrared sensor modules, Germany for precision-molded silicone actuators, and China for polymer housing extrusion. Single-source vulnerability concentrates in capacitive sensor firmware calibration, where Seoul-based engineering houses control algorithm development. Distribution runs through hygiene system integrators rather than component vendors, with airport authorities and hospital networks negotiating directly with full-stack providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement decision-makers—hospital GPOs, automotive Tier 1s, and airport authorities—creates niche entry points for specialists who can bundle sensor calibration with consumable supply contracts.
For Market Incumbents: Consolidate sensor-assembly capacity in Baden-Württemberg to capture German automotive cabin hygiene specifications before millimeter-wave ultrasonic modules displace legacy infrared arrays. Backward integration into platinum-cured silicone compounding will defend margin position against polymer feedstock volatility and narrow qualified supplier bases under FDA guidelines. For New Entrants and Emerging Players: ISO 22196 certificate portability offers a regulatory fast-track for antimicrobial surface testing, enabling single-certification entry into both United States and Indian hospital procurement channels. Target India's newly mandated tertiary care installations, where National Accreditation Board for Hospitals standards are greenfield requirements without incumbent lock-in. Lead with firmware engineering partnerships from Gyeonggi Province sensor clusters to differentiate on proximity calibration precision. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision sensor integrators with captive silicone actuator supply over commodity polymer converters facing REACH authorization delays. Five-to-ten year viability hinges on bundled hygiene system contract capture rather than component vendor relationships. Watch for GPO qualification criteria rewrites in United States acute care as the inflection signal for full-stack provider consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Actuator Integration Partnership | Combines Gyeonggi Province firmware expertise with German silicone molding for automotive cabin specifications. |
| ISO 22196 Harmonization Investment | Enables certificate portability across FDA and CDSCO jurisdictions, reducing re-certification overhead for multi-market lines. |
| Platinum-Cured Silicone Backward Integration | Captures qualified supplier base narrowing under FDA sanitary device guidelines for medical deployments. |
| Millimeter-Wave Ultrasonic R&D Expansion | Addresses German automotive specifications for temperature-stable cabin sanitizer modules. |
| GPO Bundled Service Qualification | Aligns vendor positioning with United States hospital procurement consolidation under hygiene system contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, GPO contracts managers, automotive Tier 1 procurement leads, and sensor module firmware developers. Secondary validation drew from FDA 510(k) filings for sanitary device interfaces, EPA antimicrobial claim registrations, REACH substance authorization databases, and ISO 22196 test report repositories. Bottom-up unit economics for sensor-actuator subassemblies were triangulated against top-down market sizing from hygiene system contract values.
Across the analysis window, forecasts were constructed by modeling technology adoption curves for infrared, capacitive, and ultrasonic sensor platforms alongside application segmentation across healthcare facilities, automotive interiors, and public infrastructure. CAGRs were derived from installed base replacement cycles and greenfield construction pipelines in United States, Germany, and India. Polymer feedstock price indices and sensor module die output from Taiwanese foundries provided industry-specific forecast inputs.
Underlying assumptions cover stable REACH authorization timelines for silver-ion antimicrobials and continued GPO bundling trends in United States acute care, with deviation risk concentrated in East Asian sensor module export restrictions and petrochemical price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Cordless Phone Battery Market
Electronic Components
Audio Capacitor Market
Electronic Components
Digital Audio Processor Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Lowpass Filters Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Industrial Relays Market
Electronic Components
Buffered Encoders and Decoders Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Amplifier Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
RAID Controller Card Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Chip Shield Market