
 Japan Logic Integrated Circuit (IC) Market | 2026-2036
Japan Logic Integrated Circuit (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Logic Integrated Circuit (IC) Market Insights
JIS C 1010 qualification for industrial semiconductor reliability is rotating supplier eligibility toward firms with sustained testing infrastructure. Renesas Electronics leverages its vertically integrated fabrication network to dominate automotive-grade logic production. Sony Semiconductor Solutions anchors its position through specialized imaging-sensor companion logic. Toshiba competes in industrial automation segments with legacy bipolar expertise.
Logic integrated circuits are semiconductor devices that execute Boolean operations to process binary signals, typically fabricated on silicon wafers using photolithography with feature nodes ranging from mature 40nm processes to advanced sub-10nm FinFET architectures for high-speed switching. Their primary purpose is to control data flow, timing, and computation in electronic systems from smartphones to factory robots. High-performance logic commands premium positioning in telecommunications infrastructure and AI accelerators, while low-power logic extends battery life in portable consumer devices. Specialized logic designs for automotive safety systems represent the fastest-expanding margin pool as functional safety requirements intensify.
METI's semiconductor strategy, JIS standards for electronic component quality, and PMDA medical-device regulations collectively shape design verification cycles and qualification timelines for Japanese logic IC suppliers. METI subsidies for domestic 2nm pilot lines are redirecting R&D budgets toward sovereign manufacturing capacity. Stakeholders must monitor how METI's next funding tranches allocate between logic foundry scale-up and advanced packaging integration.
Market Dynamics
Automotive electrification and autonomous driving architectures are compressing design cycles for Japanese logic IC suppliers, forcing simultaneous investment in mature-node capacity for powertrain controllers and advanced-node pilot lines for AI inference accelerators.
Growth Catalysts
- EV Powertrain Digitization:Electric vehicle inverters and battery management systems require high-reliability logic ICs with ASIL-D functional safety ratings, pulling demand from hybrid and full-electric platforms across domestic OEM supply chains.
- METI Subsidy Tranches:Japan's Ministry of Economy, Trade and Industry is directing capital toward domestic 2nm pilot fabrication facilities, reducing reliance on Taiwan and South Korea for leading-edge logic production.
- Kyushu Foundry Cluster Density:Concentrated material suppliers, equipment vendors, and specialized engineering talent in Fukuoka and Kumamoto prefectures are shortening procurement lead times for logic wafer starts.
Market Restraints
- EUV Lithography Equipment Access:Single-sourced extreme ultraviolet scanners from ASML create bottlenecks for Japanese firms attempting sub-7nm logic migration, with delivery backlogs extending equipment procurement timelines.
- Silicon Wafer Input Volatility:300mm prime-grade silicon wafer pricing fluctuates with polysilicon spot markets and energy costs, compressing gross margins for logic foundries operating on fixed-price automotive supply agreements.
- Legacy Node Demand Persistence:Mature 40nm-90nm processes for industrial automation and automotive body electronics resist volume migration to advanced nodes, stranding capital in depreciated fabrication lines.
Strategic Opportunities
- Chiplets and 3D Integration:Advanced packaging technologies enabling heterogeneous integration of logic dies from different process nodes are opening architectural flexibility for cost-optimized automotive SoC designs.
- Medical Device Logic:PMDA regulatory pathways for implantable and diagnostic equipment are creating certified-supplier status premiums for Japanese logic IC vendors with established quality management systems.
- Industrial Edge AI:Factory automation systems in Aichi and Osaka manufacturing corridors are embedding inference accelerators for predictive maintenance, generating demand for low-latency logic at the network edge.
Industry Challenges
- Functional Safety Engineering Talent:ISO 26262 certified design engineers and verification specialists command premium compensation, with domestic universities producing insufficient graduates to match automotive sector hiring velocity.
- Legacy System Integration Friction:Brownfield industrial facilities in the Chubu region require logic ICs with extended temperature ranges and pin-compatible drop-in replacements, constraining architectural innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Logic Integrated Circuit (IC) Market |
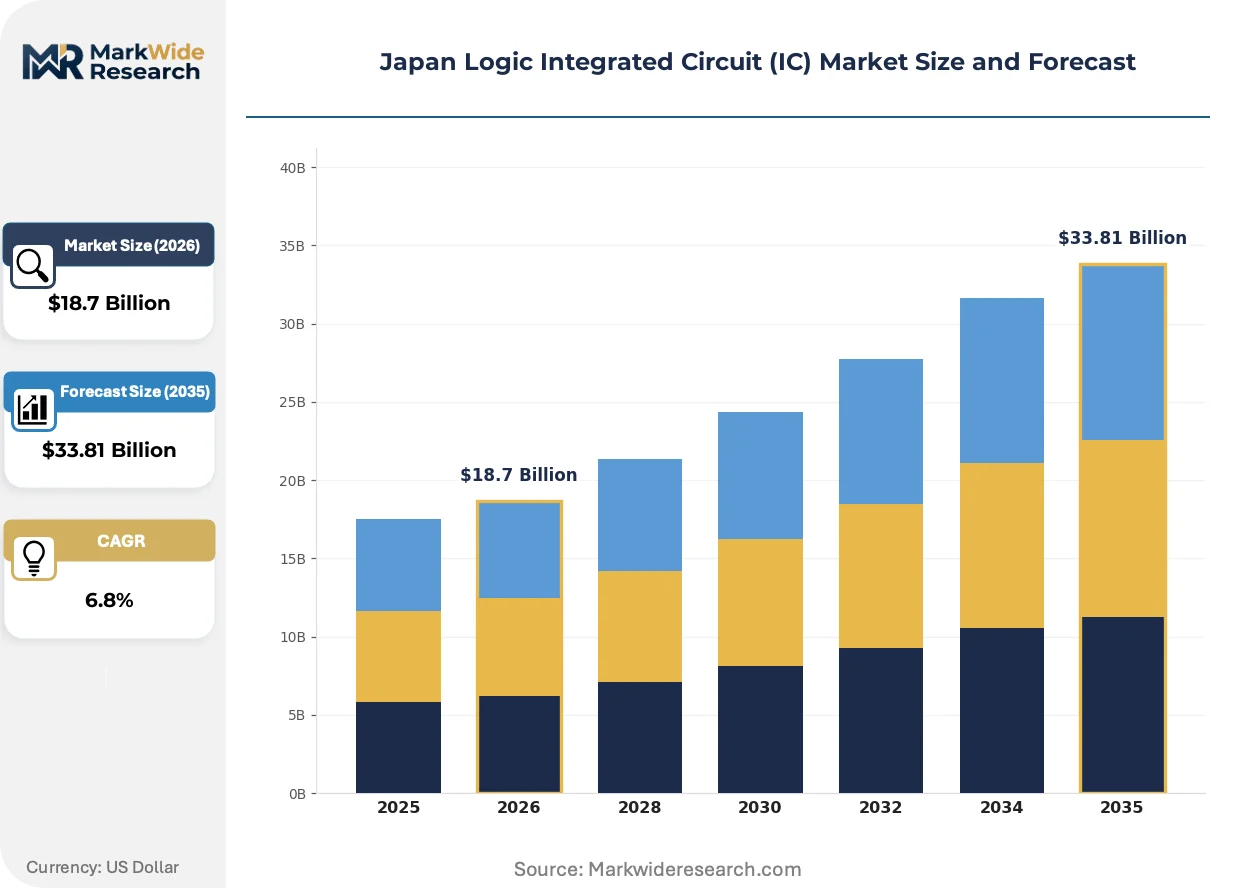
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Logic, High-Performance Logic, Low-Power Logic, Specialized Logic Technology: CMOS, BiCMOS, Bipolar, SiGe Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators |
| Companies Covered | Renesas Electronics Corporation, Sony Semiconductor Solutions Corporation, ROHM Semiconductor, Toshiba Corporation, Fujitsu Limited, Mitsubishi Electric Corporation, Panasonic Corporation, Kioxia Holdings Corporation, Socionext, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Logic Integrated Circuit (IC) Market Trends and Innovations
Silicon carbide power electronics and gallium nitride RF components are reshaping thermal and switching specifications for logic IC companion chips, forcing co-design methodologies that merge power and signal processing architectures.
FinFET transistors with gate-all-around geometry are displacing planar MOSFET structures in high-performance computing accelerators. Domestic telecommunications equipment manufacturers are qualifying these devices for 5G baseband processing. The shift is compressing competitive differentiation around leakage current control and dynamic voltage scaling precision.
METI's semiconductor ecosystem revitalization framework is mandating domestic content ratios for logic ICs deployed in critical infrastructure and defense applications. Industrial automation OEMs are requalifying supplier bases to meet these procurement guidelines. The policy is redirecting R&D investment toward sovereign manufacturing capacity rather than pure fabless design.
Automotive tier-one suppliers are consolidating logic IC vendor lists from fifteen-plus qualified sources to four-to-six strategic partners with captive foundry relationships. Procurement teams in Toyota City and Hiroshima are negotiating multi-year volume commitments with guaranteed capacity allocations. The concentration is visible most acutely in powertrain controller modules where single-source qualification timelines exceed thirty-six months.
Japan Logic Integrated Circuit (IC) Market Segmentation
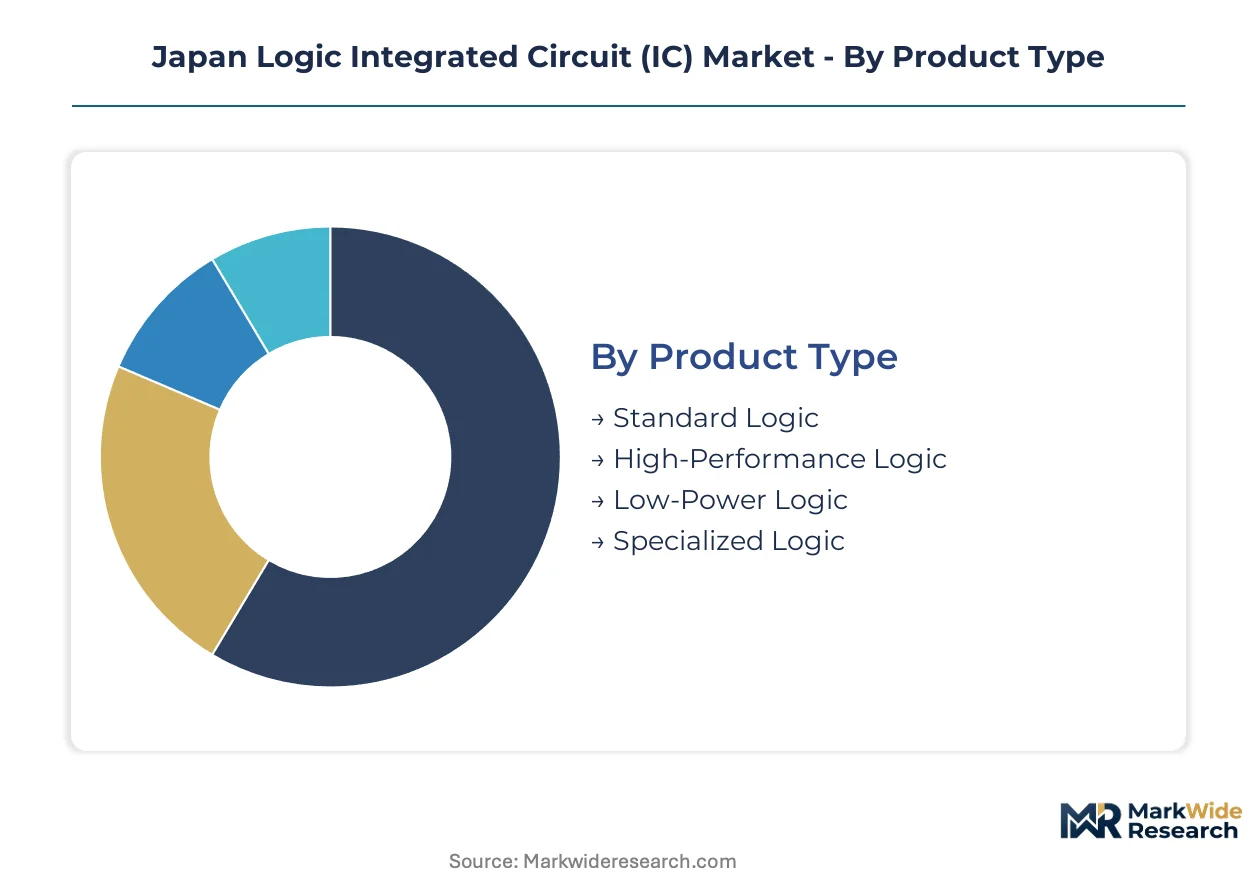
Logic IC procurement patterns in Japan diverge sharply across product tiers and customer types. Automotive and industrial buyers prioritize JIS-qualified reliability over cost, while consumer electronics OEMs drive volume through foundry partnerships in Kyushu.
Product Type:
Domestic demand concentrates in automotive-grade and industrial-grade categories where Japanese suppliers maintain captive fabrication, while standard logic faces price pressure from import competition.
- Standard Logic:Basic gate arrays and flip-flops fabricated on mature 40nm-90nm nodes serve industrial control boards and legacy automotive body electronics. Procurement teams at Nagoya-based tier-one suppliers favor domestic sources for supply security despite 15-20% cost premiums over Taiwanese imports.
- High-Performance Logic:Sub-10nm FinFET devices power AI accelerators and 5G baseband processors. METI subsidy tranches for 2nm pilot lines target this category, with foundry investments clustering in Kumamoto prefecture to serve domestic telecommunications equipment manufacturers.
- Low-Power Logic:Optimized for battery-operated portable devices through aggressive voltage scaling and clock gating. Smartwatch and hearing-aid manufacturers in Osaka drive modest domestic volumes.
- Specialized Logic:ASICs with ASIL-D functional safety certification for electric vehicle powertrain controllers. Renesas Electronics dominates this segment through vertically integrated production in Naka and Saijo facilities.
Specialized logic commands the established base. The steepest expansion runs through high-performance logic.
Technology:
Process selection correlates directly with end-use reliability requirements and thermal operating envelopes, with automotive applications mandating proven node maturity.
- CMOS:Dominant fabrication platform spanning 90nm to 5nm nodes for general-purpose logic. Kyushu foundry clusters achieve 85% domestic wafer starts for this technology, with Shin-Etsu Chemical supplying 300mm silicon substrates from Uenohara.
- BiCMOS:Merged bipolar-CMOS processes deliver high-speed switching with analog precision for automotive radar signal chains. Limited to two qualified domestic sources due to process complexity and qualification costs.
- Bipolar:Legacy TTL and ECL families persist in industrial automation retrofit markets. Toshiba maintains production lines at Oita for pin-compatible replacements in brownfield Chubu manufacturing facilities.
- SiGe:Silicon-germanium heterojunction transistors enable millimeter-wave logic for 5G beamforming arrays. NTT Docomo base station deployments in Tokyo and Osaka anchor domestic demand.
Bipolar retains the installed base. The most aggressive capacity additions target CMOS.
Application:
End-use segmentation reveals divergent margin structures, with automotive and industrial applications commanding qualification premiums while consumer electronics operates on foundry-determined cost curves.
- Consumer Electronics:Smartphones, tablets, and wearables requiring annual node migrations for performance gains. Domestic OEMs source primarily from TSMC and Samsung, limiting Japanese foundry participation to mature-node peripheral controllers.
- Automotive Electronics:Powertrain controllers, ADAS processors, and battery management systems with ISO 26262 functional safety mandates. Toyota and Honda procurement teams enforce 15-year supply continuity agreements, favoring Renesas and domestic captive sources.
- Industrial Automation:Programmable logic controllers and servo motor drives operating across -40°C to +125°C temperature ranges. Fanuc and Yaskawa factories in Yamanashi and Fukuoka prefectures specify extended-temperature logic from qualified Japanese vendors.
- Telecommunications:5G baseband processors and network switching fabric for NTT and Rakuten Mobile infrastructure. METI domestic content ratios redirect procurement toward Japan-sourced dies even at 30-40% cost premiums.
Industrial automation commands the established base. The steepest expansion runs through automotive electronics.
End User:
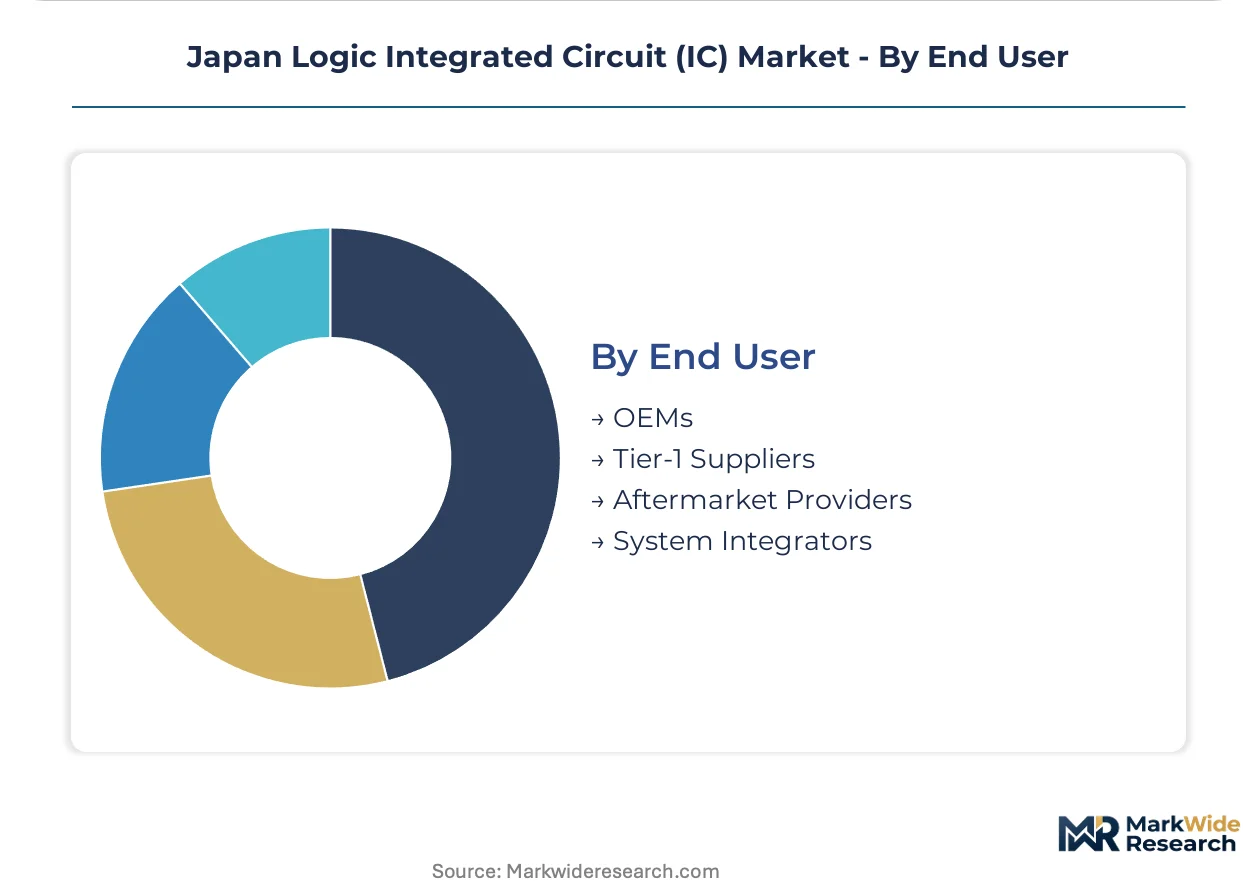
Customer type determines contract structures, with OEMs and tier-one suppliers locking in multi-year capacity while aftermarket and integrator channels absorb spot-market volatility.
- OEMs:Toyota, Sony, and Panasonic operate direct procurement teams with dedicated foundry capacity allocations. These customers negotiate 36-month rolling forecasts with take-or-pay provisions, securing wafer starts at TSMC Japan and domestic Rapidus pilot lines.
- Tier-1 Suppliers:Denso, Aisin, and Panasonic Automotive Systems consolidate vendor lists to four-to-six strategic partners. Functional safety certification timelines exceeding 30 months create switching costs that stabilize supplier relationships.
- Aftermarket Providers:Replacement logic ICs for repair and refurbishment channels. Distribution runs through Tokyo-based electronics trading houses with 8-12 week inventory cycles.
- System Integrators:Custom industrial control panel builders in Osaka and Nagoya purchasing small-lot logic through distributor networks. These customers absorb spot-market pricing volatility without volume leverage.
OEMs command the established base. The steepest expansion runs through tier-1 suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's semiconductor subsidies are redirecting capital toward domestic fabrication capacity, concentrating investment in Kyushu foundry clusters while Kanto maintains design engineering density. Regional specialization patterns reflect legacy industrial infrastructure and targeted policy incentives.
Kyushu
Foundry investments in Kumamoto and Fukuoka prefectures anchor Japan's logic wafer production, with Rapidus pilot lines and TSMC Japan facilities absorbing METI subsidy tranches. Local material suppliers including Shin-Etsu Chemical and Tokyo Electron shorten procurement lead times for 300mm silicon substrates. Kyushu Economic Federation coordinates workforce training programs to address equipment technician shortages.
Kanto
Tokyo and Kanagawa prefectures concentrate fabless design houses and system-level engineering for automotive and telecommunications applications. NTT Docomo and Rakuten Mobile headquarters drive demand for 5G baseband logic verification. University of Tokyo and Tokyo Institute of Technology feed graduate talent into functional safety engineering pipelines.
Chubu
Toyota City and Nagoya manufacturing corridors generate concentrated demand for ASIL-D certified powertrain controllers. Denso and Aisin procurement teams enforce 15-year supply continuity agreements with qualified logic vendors. Legacy industrial automation facilities in Yamanashi require extended-temperature logic with pin-compatible drop-in replacements.
Kansai
Osaka and Kyoto prefectures host medical device OEMs navigating PMDA regulatory pathways for implantable equipment logic. Sharp and Panasonic consumer electronics divisions source mature-node peripheral controllers from domestic foundries. Osaka University semiconductor research programs focus on low-power design methodologies for battery-operated devices.
Tohoku
Sendai and Fukushima prefectures supply silicon wafer inputs from Shin-Etsu Chemical Uenohara and SUMCO facilities. Earthquake-resistant fabrication infrastructure developed post-2011 attracts disaster-conscious supply chain planning. Tohoku University anchors materials science research supporting next-generation substrate development.
Japan Logic Integrated Circuit (IC) Market Competitive Landscape
Listed leaders compete with private specialists across fabrication and design capabilities, creating a tiered structure where scale advantages concentrate in vertically integrated incumbents while fabless specialists capture niche functional safety segments. Three archetypes dominate: captive foundry operators with in-house wafer production, fabless design houses targeting automotive qualification premiums, and diversified conglomerates leveraging cross-divisional technology transfer. Competitive moves center on METI subsidy alignment for domestic capacity expansion and multi-year procurement lock-ins with tier-one automotive suppliers.
Among Japan-based fabricators, Renesas Electronics Corporation and Sony Semiconductor Solutions Corporation exemplify divergent strategic positions. Renesas anchors the automotive-grade logic segment through vertically integrated production facilities. Sony Semiconductor Solutions occupies a specialized tier focused on imaging-sensor companion logic. Toshiba Corporation represents the legacy industrial automation incumbent with sustained bipolar process expertise. These three entities collectively illustrate how domestic market structure rewards either deep vertical integration or narrow technological specialization.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| Sony Semiconductor Solutions Corporation |
| ROHM Semiconductor |
| Toshiba Corporation |
| Fujitsu Limited |
| Mitsubishi Electric Corporation |
| Panasonic Corporation |
| Kioxia Holdings Corporation |
| Socionext |
| Others |
Pricing and Supply Chain Analysis
300mm wafer fab utilization rates above 85 percent in Kyushu foundry clusters compress cost curves for domestic logic IC production while simultaneously elevating price floors for automotive-grade qualified supply. METI subsidy absorption and JIS certification overhead create bifurcated margin structures where captive fabrication commands persistent premiums over fabless alternatives.
Pricing Analysis
Certification level creates the primary spread across Japanese logic IC procurement, with ASIL-D functional safety tiers commanding 40-60 percent premiums over industrial-grade equivalents. Contract-based long-term offtake agreements dominate automotive supply relationships, locking in volume commitments across 36-month horizons. Cost compression in standard logic tiers intensifies as Taiwanese import competition erodes domestic share. Tier-one automotive suppliers exhibit lowest price sensitivity due to qualification switching costs, while system integrators in Osaka and Nagoya absorb spot-market volatility without volume leverage.
Supply Chain Analysis
Inbound logistics costs through Yokohama and Hakata ports fluctuate with container availability on Asia-Japan trade lanes, compressing margin buffers for just-in-time wafer delivery schedules. Japanese logic IC production draws from concentrated equipment and material inputs originating in Taiwan, South Korea, and the United States. EUV lithography scanner dependence on ASML single-sourcing creates structural vulnerability for sub-7nm migration timelines. Distribution runs through Tokyo-based electronics trading houses with tier-one suppliers securing direct foundry allocations bypassing distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's logic IC market sits in early-cycle expansion as EV powertrain digitization and METI sovereign manufacturing subsidies accelerate domestic capacity commitments ahead of demand inflection.
For Market Incumbents: Secure multi-year procurement lock-ins with Toyota and Honda procurement teams before Rapidus pilot lines achieve commercial scale, eroding captive foundry differentiation. Defend automotive-grade margin pools through accelerated ASIL-D certification pipelines and backward integration into 300mm silicon substrate supply through Shin-Etsu Chemical partnerships. METI subsidy allocation shifts toward advanced packaging integration represent the primary regulatory threat requiring strategic repositioning. For New Entrants and Emerging Players: Anchor in medical device logic segments where PMDA regulatory pathways create certified-supplier status premiums and incumbent concentration remains lowest. Industrial edge AI inference accelerators for predictive maintenance in Aichi and Osaka manufacturing corridors offer the most penetrable white-space target. Pursue fabless design partnerships with Kyushu foundry clusters to bypass capital-intensive fabrication barriers while capturing functional safety engineering premiums. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive-tier-one suppliers with 15-year supply continuity agreements and captive foundry relationships, positioning these archetypes for durable cash flow generation across the next decade. Acquisition targets should prioritize firms with ISO 26262 certified design teams and existing JIS qualification infrastructure. Monitor METI's next subsidy tranche allocation between logic foundry scale-up and advanced packaging integration as the critical inflection signal for sovereign manufacturing viability.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic 2nm Pilot Line Investment | METI subsidy absorption reduces reliance on Taiwan and South Korea for leading-edge logic production. |
| ASIL-D Functional Safety Certification | ISO 26262 compliance locks in automotive powertrain controller supply relationships exceeding 36 months. |
| Advanced Packaging Integration | Chiplet and 3D integration capabilities open architectural flexibility for cost-optimized automotive SoC designs. |
| Kyushu Foundry Cluster Expansion | Concentrated material suppliers and equipment vendors in Fukuoka and Kumamoto shorten procurement lead times. |
| Medical Device Logic Certification | PMDA regulatory pathways for implantable equipment create certified-supplier status premiums in Kansai region. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with semiconductor fabrication executives, automotive procurement directors, and METI policy officials; and secondary validation through METI subsidy disclosure filings, JIS certification registries, and SEC 10-K filings from listed Japanese semiconductor firms. Bottom-up demand modeling across consumer electronics, automotive, industrial automation, and telecommunications applications was triangulated against top-down wafer start capacity data from Kyushu foundry clusters.
Across the projection horizon, the analytical framework modeled demand segmentation by product type, technology node, application vertical, and end-user procurement structure. CAGRs were derived from regression analysis of historical wafer pricing, capacity utilization trends, and OEM production forecasts. Industry-specific inputs included EUV equipment delivery timelines from ASML, polysilicon spot market volatility, and functional safety engineering talent pipeline data from University of Tokyo and Tokyo Institute of Technology.
Decision-makers should treat outputs as directional under assumptions of sustained METI subsidy commitment and stable Taiwan Strait logistics corridors; material deviation would warrant model refresh. Specific risks include ASML equipment delivery delays, polysilicon price spikes compressing foundry margins, and automotive OEM demand destruction from macroeconomic contraction. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market