
 Semiconductor Device in Aerospace and Defense Industry Market | 2026-2036
Semiconductor Device in Aerospace and Defense Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Device in Aerospace and Defense Industry Market Insights
Modular packaging of mixed-signal chipsets with integrated RF front-ends is rebalancing procurement decisions across prime contractors and tier-one suppliers. Infineon Technologies leverages its power semiconductor expertise to anchor European defense electrification programs. Texas Instruments sustains broad catalog dominance in precision analog for avionics sensor networks. BAE Systems differentiates through captive foundry access and sovereign supply-chain control for UK military platforms.
Semiconductor devices for aerospace and defense comprise discrete components and integrated circuits engineered to withstand extreme temperature swings, radiation exposure, and mechanical shock across operational lifetimes exceeding fifteen years. These devices employ silicon-on-insulator substrates, triple-module redundancy architectures, and hermetic ceramic packaging to ensure signal integrity in orbital and combat environments. Integrated circuits command the largest value share within product-type segmentation, while RF technology is expanding fastest as phased-array radar and software-defined radio architectures proliferate across military and satellite applications. Surveillance applications concentrate margin pools where custom ASIC development contracts carry multi-year exclusivity terms and security-cleared engineering access.
FAA airworthiness certification requirements, DoD MIL-STD-883 test methods, and ESA SCC qualification standards collectively govern component acceptance for flight-critical systems. These frameworks mandate traceable manufacturing origins, extended burn-in protocols, and radiation lot-acceptance testing that filter out commercial-grade suppliers. Stakeholders must monitor how export-control expansions under ITAR and emerging allied consortium agreements reshape eligible vendor pools for cross-border defense programs.
Market Dynamics
Radiation-hardened component procurement is bifurcating between sovereign foundry mandates and commercial foundry partnerships, forcing prime contractors to dual-source across trusted and non-trusted supply tiers while maintaining MIL-STD-883 qualification traceability.
Growth Catalysts
- Trusted Foundry Program mandates:The U.S. Department of Defense's sourcing requirements are redirecting defense procurement toward domestic fabrication facilities with security-cleared personnel and controlled design environments.
- Phased-array radar proliferation:Military platforms are replacing mechanically scanned arrays with active electronically scanned arrays, multiplying RF semiconductor content per platform by an order of magnitude.
- Silicon-on-insulator substrates:SOI process nodes now deliver radiation tolerance without full custom foundry runs, compressing development cycles for satellite payload processors.
Market Restraints
- Specialized substrate costs:Silicon-on-sapphire and SOI wafers command 8-15x pricing premiums over commercial-grade silicon, constraining program budgets for volume satellite constellations.
- Foundry concentration:Radiation-hardened qualified fabrication capacity clusters in three U.S. facilities and one European site, creating single-point-of-failure exposure for allied defense programs.
- Extended qualification timelines:ESA SCC and MIL-STD-883 test sequences require 18-36 months for new device introduction, freezing out iterative design approaches common in commercial semiconductor markets.
Strategic Opportunities
- Software-defined radio convergence:Multi-band, multi-mission RF platforms are consolidating discrete components into reconfigurable chipsets, opening ASIC development contracts with decade-long exclusivity terms.
- European defense electrification:NATO member states are funding domestic packaging and test capabilities to reduce dependency on U.S. trusted foundries for tactical vehicle power electronics.
- LEO satellite manufacturing scale:Constellation operators are accepting radiation-tolerant commercial-grade devices with selective hardening, creating hybrid qualification pathways outside traditional military specifications.
Industry Challenges
- Cleared engineering talent scarcity:Security-cleared IC designers and radiation effects specialists command compensation premiums exceeding 40% above commercial analogs, constraining program staffing.
- Legacy system integration friction:New semiconductor architectures must interface with 30-year-old avionics buses and proprietary military data protocols, forcing costly interface ASIC development.
- Supply chain reconfiguration costs:ITAR-controlled component transitions between qualified suppliers trigger re-qualification cycles that suspend production lines for 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Device in Aerospace and Defense Industry Market |
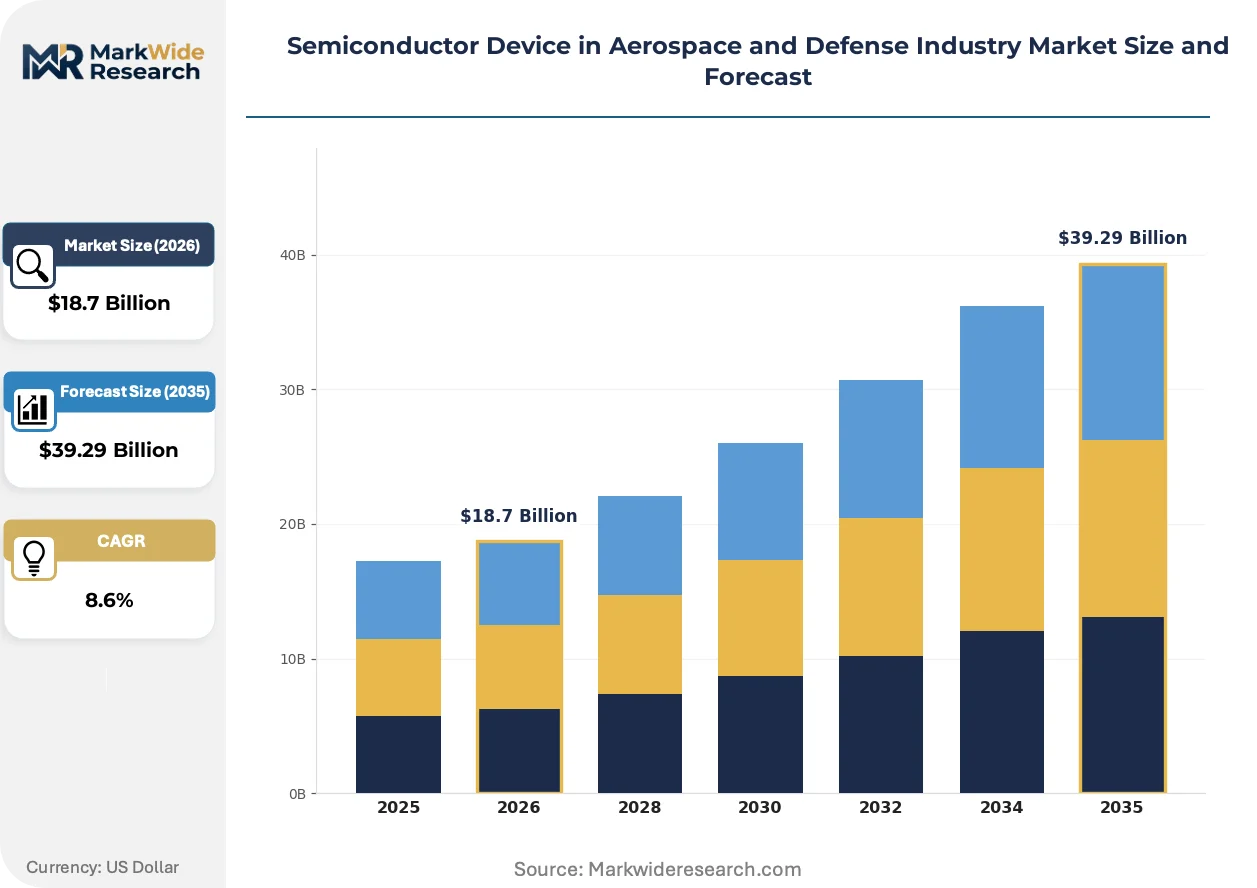
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diodes, Transistors, Integrated Circuits, Sensors Technology: Analog, Digital, Mixed Signal, RF Application: Satellite Systems, Avionics, Communication, Surveillance End User: Military, Commercial Aviation, Space Exploration, Defense Contractors |
| Companies Covered | Infineon Technologies, onsemi, Texas Instruments, Broadcom, BAE Systems, Analog Devices, NXP Semiconductors, Northrop Grumman, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Device in Aerospace and Defense Industry Market Trends and Innovations
Modular packaging architectures and heterogeneous integration are compressing subsystem footprints while complicating thermal management and radiation shielding strategies across orbital and airborne platforms.
Chiplets with standardized die-to-die interconnects are decentralizing monolithic radiation-hardened processor development. Satellite prime contractors now assemble mission-specific compute tiles from qualified die libraries rather than commissioning full-custom SoCs. This approach is decentralizing design authority from captive semiconductor divisions toward fabless defense contractors with packaging expertise.
The U.S. Department of Commerce's export control expansions under ITAR Category XV are restricting gallium nitride and silicon carbide power device transfers to specific allied nations. Defense contractors must now segment product roadmaps between unrestricted commercial-aerospace grades and restricted military grades. Satellite communications vendors serving dual-use markets face the greatest compliance burden as customer eligibility determinations delay contract execution.
Defense procurement officers are consolidating vendor relationships around suppliers offering bundled qualification documentation and lifetime traceability databases. Tier-one contractors now select component vendors based on pedigree file completeness rather than unit cost alone. This preference shift is most visible in U.S. Navy surface ship programs where supply chain resilience ratings factor into source selection criteria alongside technical performance.
Semiconductor Device in Aerospace and Defense Industry Market Segmentation
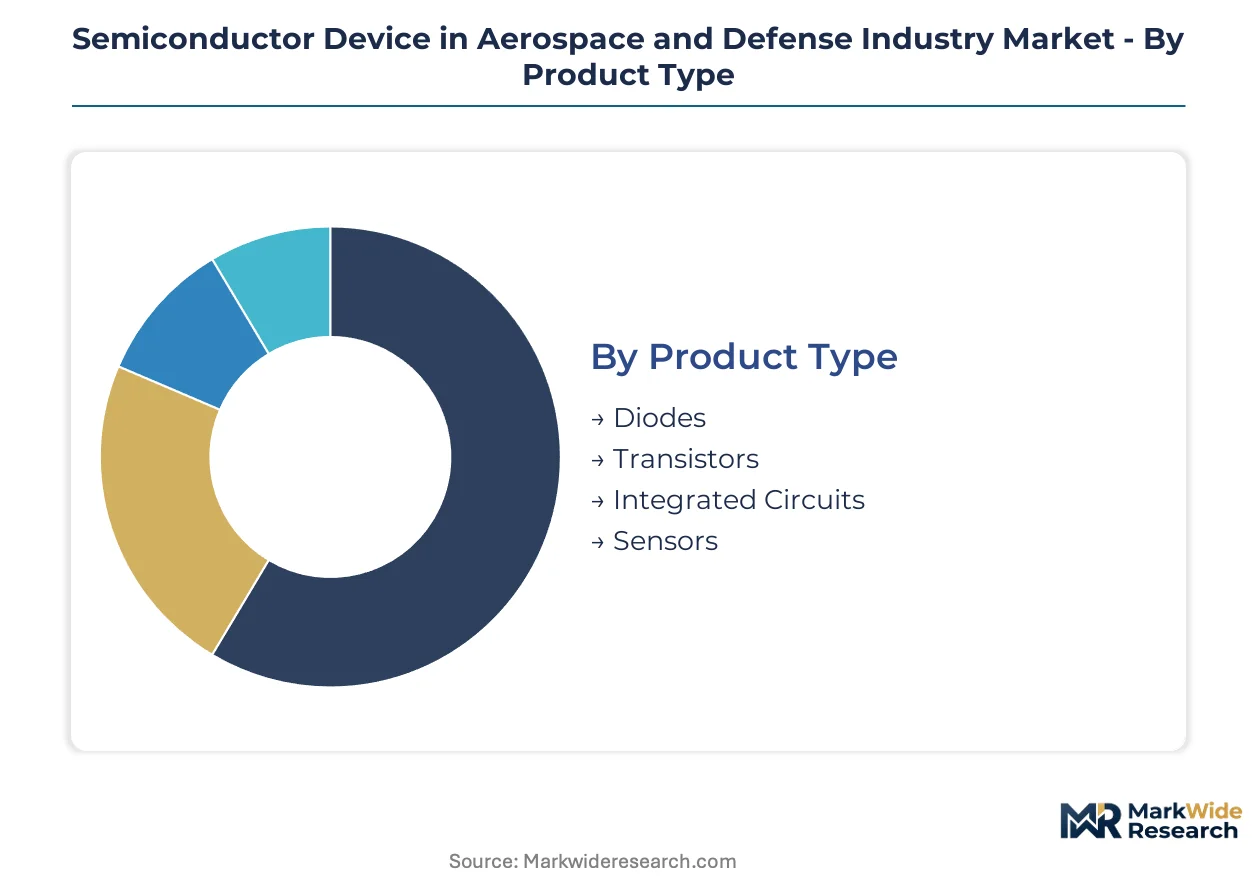
Segmentation in aerospace and defense semiconductors reveals how certification requirements fragment procurement strategies. MIL-STD-883, ESA SCC, and FAA airworthiness standards create divergent qualification pathways that reshape vendor selection across each product category.
Product Type:
Certification burden varies sharply across device complexity, with integrated circuits demanding the most extensive radiation lot-acceptance testing and hermetic packaging validation under DoD and ESA frameworks.
- Integrated Circuits:Complex silicon-on-insulator and silicon-on-sapphire devices incorporating triple-module redundancy for orbital processors. Demand concentrates in U.S. satellite payload programs where Trusted Foundry Program mandates restrict sourcing to domestic qualified fabrication. Foundry concentration in three U.S. facilities and one European site creates supply vulnerability for allied defense programs.
- Sensors:Precision analog devices for avionics networks measuring pressure, temperature, and inertial parameters. Texas Instruments maintains catalog dominance here, with procurement gravitating toward suppliers offering complete pedigree documentation for FAA certification.
- Diodes:Discrete power rectifiers and protection devices with simpler qualification pathways than complex ICs.
- Transistors:Power switching and amplification components, including gallium nitride and silicon carbide variants now restricted under ITAR Category XV export controls.
Leading the category by volume: Integrated Circuits. Growing fastest: Sensors.
Technology:
Cost tiers separate legacy qualification approaches from emerging commercial-radiation-tolerant alternatives, with RF commanding premium pricing for phased-array radar content.
- RF:Gallium nitride and silicon germanium devices for active electronically scanned arrays and software-defined radios. Military platforms replacing mechanically scanned arrays multiply RF semiconductor content per platform substantially. ITAR restrictions now segment product roadmaps between commercial-aerospace and restricted military grades.
- Mixed Signal:Chipsets combining analog front-ends with digital processing for software-defined radio convergence. Modular packaging of these devices is rebalancing procurement decisions across prime contractors and tier-one suppliers.
- Analog:Precision voltage references, amplifiers, and data converters for sensor signal conditioning.
- Digital:Logic devices and processors, increasingly deployed via chiplet architectures that decentralize monolithic radiation-hardened development.
Highest margin tier: RF. Steepest expansion trajectory: Mixed Signal.
Application:
Customer type determines whether devices follow military specification pathways or hybrid commercial-radiation-tolerant qualification.
- Surveillance:Custom ASIC development for signals intelligence and electronic warfare platforms. Multi-year exclusivity terms and security-cleared engineering access concentrate margin pools here. BAE Systems leverages captive foundry access for UK sovereign supply-chain control in this segment.
- Satellite Systems:LEO constellation operators are accepting radiation-tolerant commercial-grade devices with selective hardening, creating hybrid qualification pathways outside traditional military specifications. Silicon-on-insulator process nodes now deliver radiation tolerance without full custom foundry runs.
- Avionics:Flight-critical systems governed by FAA airworthiness certification and extended burn-in protocols.
- Communication:Tactical and satellite communications equipment facing dual-use market compliance burdens.
Dominant revenue concentration: Surveillance. Gaining share fastest: Satellite Systems.
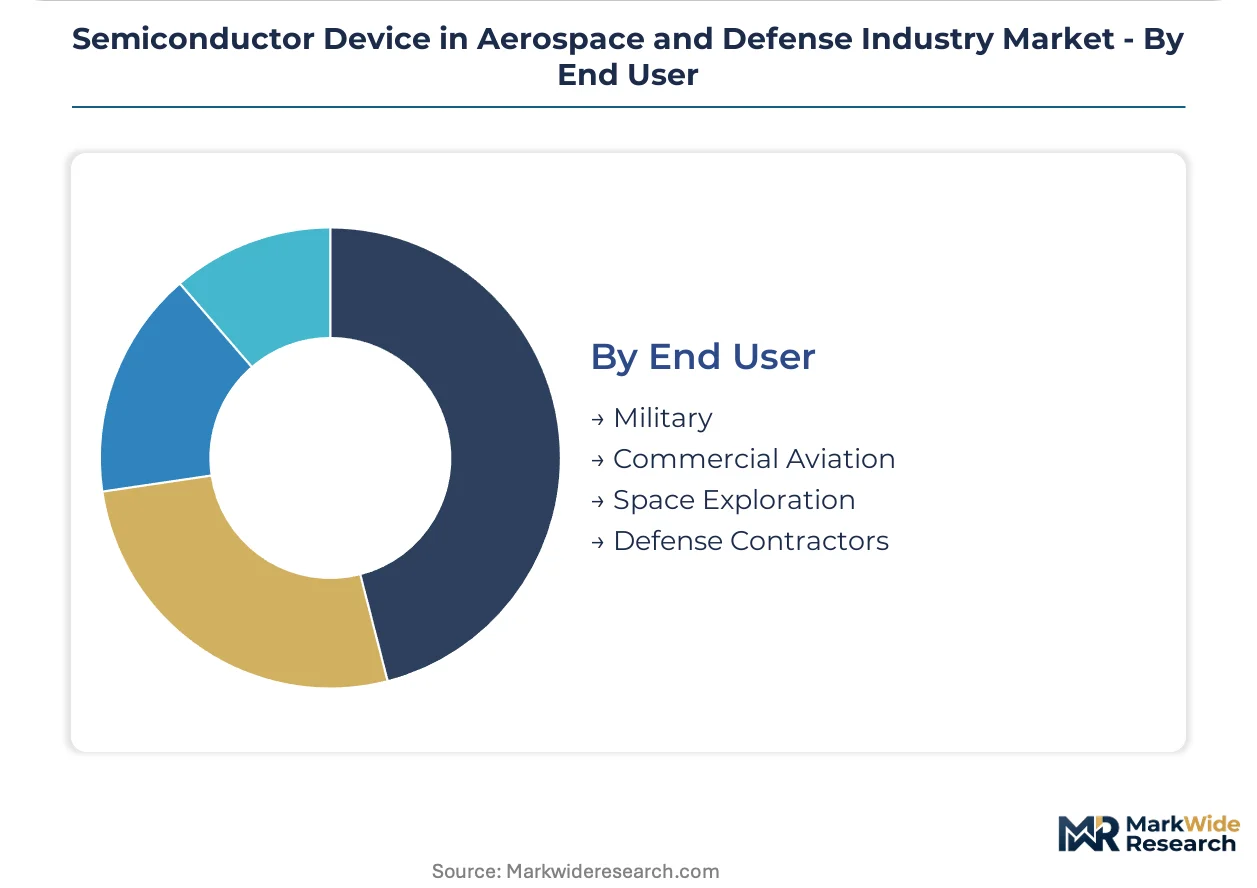
End User:
Supply concentration aligns with defense modernization budgets and domestic fabrication incentives across major procurement authorities.
- Military:U.S. Department of Defense programs driving Trusted Foundry Program compliance and security-cleared personnel requirements. Defense procurement officers now consolidate vendor relationships around bundled qualification documentation and lifetime traceability databases.
- Defense Contractors:Prime contractors and tier-one suppliers managing dual-sourcing across trusted and non-trusted supply tiers while maintaining MIL-STD-883 qualification traceability. Supply chain resilience ratings now factor into U.S. Navy surface ship source selection.
- Commercial Aviation:FAA-governed systems with distinct certification timelines from military specifications.
- Space Exploration:NASA and ESA science missions with extended operational lifetime requirements exceeding fifteen years.
Largest procurement volume: Military. Fastest budget growth: Defense Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CHIPS and Science Act incentive zones in Arizona, Texas, and New York are concentrating domestic fabrication capacity for radiation-hardened components. Defense procurement mandates now require traceable supply chains through these designated facilities.
United States
Defense modernization budgets and Trusted Foundry Program compliance redirect procurement toward domestic qualified fabrication. The Department of Defense mandates security-cleared personnel and controlled design environments for all flight-critical semiconductor sourcing. Arizona's Phoenix-Tempe corridor hosts expanding SOI processing capacity for satellite payload processors.
Germany
European defense electrification programs fund domestic packaging and test capabilities for tactical vehicle power electronics. The EU Chips Act subsidizes sovereign semiconductor infrastructure to reduce dependency on external trusted foundries. Bavaria's Munich-Ingolstadt cluster anchors Infineon Technologies' power semiconductor operations for NATO platform integration.
United Kingdom
BAE Systems leverages captive foundry access for sovereign supply-chain control across UK military platforms. National security regulations mandate domestic traceability for surveillance and electronic warfare component procurement. South Wales hosts specialized packaging facilities serving the UK's space and defense prime contractor ecosystem.
Japan
METI coordinates public-private partnerships to secure gallium nitride and silicon carbide supply chains for radar and communications systems. Export control alignment with allied frameworks restricts dual-use semiconductor transfers to vetted nations. Tokyo-Yokohama's precision manufacturing corridor concentrates analog and mixed-signal device production for avionics networks.
Israel
Domestic defense R&D expenditure sustains captive ASIC development for signals intelligence and electronic warfare platforms. National security classification requirements limit foreign vendor access to military semiconductor programs. Haifa's technology cluster houses specialized design centers focusing on phased-array radar and software-defined radio chipsets.
Semiconductor Device in Aerospace and Defense Industry Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across qualification-intensive procurement channels. The vendor base stratifies between captive defense divisions with foundry control and fabless contractors with packaging expertise. Three archetypes dominate: integrated primes with semiconductor divisions, European power semiconductor specialists, and broad-catalog analog suppliers. Competitive moves center on dual-sourcing partnerships and sovereign packaging investments.
Among integrated defense primes, BAE Systems exemplifies the captive-foundry archetype through UK sovereign supply-chain control. Texas Instruments and Infineon Technologies occupy distinct positions in the analog and power semiconductor tiers respectively, with the former sustaining broad catalog dominance and the latter anchoring European defense electrification programs. These three entities represent the spectrum from vertical integration to specialized component supply.
| Leading Market Players |
|---|
| Infineon Technologies |
| onsemi |
| Texas Instruments |
| Broadcom |
| BAE Systems |
| Analog Devices |
| NXP Semiconductors |
| Northrop Grumman |
| Microchip Technology |
| Others |
Pricing and Supply Chain Analysis
U.S. Department of Defense prime contractors concentrate procurement authority, locking in contract-based long-term offtake pricing with radiation-hardened foundries. This buyer concentration feeds back into supply choices, forcing dual-sourcing mandates that fragment volume across qualified facilities.
Pricing Analysis
Lead-time premiums command substantial markups for MIL-STD-883 qualified devices with sub-twelve-month delivery windows. Three-tier pricing structure across Trusted Foundry Program, allied sovereign, and commercial-radiation-tolerant grades differentiates by certification pedigree and security clearance requirements. Cost compression in commercial-radiation-tolerant tiers intensifies as LEO constellation operators scale procurement. Satellite prime contractors exhibit highest price sensitivity, while surveillance platform integrators prioritize pedigree completeness over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with specialized SOI substrate suppliers clustered in the United States, Germany, and Japan. Raw material dependencies include silicon-on-insulator wafers, hermetic ceramic packaging materials, and gallium arsenide substrates. Tariff exposure under ITAR Category XV expansion threatens cross-border component flows for GaN and SiC power devices. Distribution runs through defense-authorized distributors with security-cleared warehousing and traceability database systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-on-insulator process nodes are displacing silicon-on-sapphire for satellite payload processors, compressing development cycles and reshaping foundry relationships.
For Market Incumbents: Extend qualification documentation bundling to capture U.S. Navy supply chain resilience ratings in source selection criteria. Secure captive packaging capacity in CHIPS Act incentive zones to defend against fabless competitors with heterogeneous integration expertise. Vertical integration into SOI substrate sourcing mitigates pricing volatility from specialized wafer suppliers. For New Entrants and Emerging Players: Defense contractors with packaging expertise represent the most penetrable channel partner type for chiplet-based mission-specific compute tiles. Target European defense electrification programs funding domestic test capabilities for tactical vehicle power electronics. Pursue ASIC development contracts with decade-long exclusivity terms in software-defined radio convergence segments. For Investors and Strategic Acquirers: The window for entry favors fabless defense contractors with security-cleared engineering teams and packaging specialization. Long-term viability hinges on sovereign supply-chain mandates tightening across NATO member states. Watch for ITAR Category XV expansion announcements as inflection indicators for GaN and SiC device market access restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Qualification | DoD sourcing mandates redirect procurement toward security-cleared domestic fabrication facilities. |
| Chiplet Architecture Adoption | Satellite prime contractors assemble mission-specific compute tiles from qualified die libraries. |
| Sovereign Packaging Investment | EU Chips Act subsidizes test capabilities reducing dependency on external trusted foundries. |
| Software-Defined Radio Convergence | Multi-band RF platforms consolidate discrete components into reconfigurable chipsets with exclusivity terms. |
| ITAR Compliance Segmentation | Export control expansions force product roadmaps splitting commercial-aerospace from restricted military grades. |
Research Methodology
Multi-period observation of defense procurement budgets, foundry qualification timelines, and satellite constellation deployment rates anchored the trend analysis, supplemented by interviews with radiation effects specialists, security-cleared IC designers, defense procurement officers, and satellite payload engineering directors. Secondary validation drew from DoD budget justification documents, ESA SCC qualification databases, FAA airworthiness certification records, and customs trade data for semiconductor imports. Bottom-up build of device-level demand and top-down reconciliation against prime contractor revenue disclosures provided cross-check triangulation.
Segment-weighting across product type, technology node, application mission profile, and end-user procurement authority shaped the analytical framework over the projection horizon. Modeled dimensions included integrated circuit complexity tiers, RF versus mixed-signal versus analog technology splits, and military versus commercial-space end-use distinctions. CAGRs derived from fitting historical qualification cycle data to projected deployment schedules for phased-array radar and LEO constellation programs. Industry-specific inputs incorporated Trusted Foundry Program mandate expansion timelines and ITAR Category XV restriction coverage.
Caveats apply where defense budget sequestration, foundry qualification delays, or allied consortium agreement restructuring could materially shift the outlook. Forecasts reflect assumptions about security clearance processing throughput and substrate supply continuity that carry execution risk. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
AMD Motherboards Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Europe Power Transistor Market