
 Battery Shunt Resistor Market | 2026-2036
Battery Shunt Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Shunt Resistor Market Insights
Manganese-copper alloy is shifting toward bulk metal foil in high-precision battery shunt designs, improving temperature stability and reducing drift under thermal cycling. Vishay Intertechnology leverages its foil technology heritage to dominate aerospace-grade segments that now migrate into EV applications. Isabellenhütte Heusler anchors European automotive supply chains with proprietary ZERANIN alloys processed in-house.
A battery shunt resistor is a low-ohm precision component inserted in series with a battery pack to measure current flow via voltage drop, typically manufactured from temperature-stable alloys such as manganin or constantan and calibrated to micro-ohm tolerances for coulomb counting in battery management systems. Wirewound technology retains cost advantages in high-current industrial settings, while thin film captures premium EV and energy storage margins where miniaturization and thermal precision command price premiums. Automotive Systems application demand outpaces Industrial Equipment as OEMs integrate shunts directly into cell monitoring units rather than external measurement racks.
EPA tailpipe rules and the EU Green Deal's battery passport requirements force resistor manufacturers to certify traceability and recyclability across supply chains. China's MIIT mandates domestic EV battery testing standards that specify current measurement accuracy thresholds, creating technical barriers for non-compliant imports. Stakeholders must monitor alloy supply concentration and regulatory divergence between jurisdictions to avoid stranded inventory or certification gaps.
Market Dynamics
Precision current sensing requirements from EV battery management systems are compressing tolerance specifications and forcing alloy suppliers to certify thermal drift performance under automotive qualification protocols.
Growth Catalysts
- EPA tailpipe regulations:US vehicle efficiency mandates push OEMs toward higher-precision coulomb counting for range certification, directly expanding demand for micro-ohm shunt resistors in traction battery packs.
- Cell-to-pack architectures:Elimination of module housings integrates current sensors directly into cell monitoring units, creating embedded shunt opportunities that wirewound alternatives cannot miniaturize.
- China's MIIT testing standards:Domestic EV battery certification protocols specify current measurement accuracy thresholds, creating technical compliance requirements that favor precision alloy suppliers with in-house calibration capabilities.
Market Restraints
- Manganese-copper alloy supply concentration:Specialized manganin and constantan feedstock production clusters in German and Japanese metallurgical facilities, exposing buyers to single-source disruption risks.
- Thin film capex intensity:Vacuum deposition equipment for bulk metal foil processing requires multi-year capital recovery timelines that deter mid-tier entrants from competing on precision specifications.
- RoHS substance restrictions:European hazardous substance limits constrain traditional alloy compositions, forcing reformulation cycles that delay product qualification with automotive OEMs.
Strategic Opportunities
- Stationary energy storage systems:Grid-scale battery installations in Germany and California adopt automotive-grade sensing for warranty validation, opening a parallel demand channel with less stringent automotive qualification timelines.
- EU Green Deal battery passport:Traceability mandates create premium positioning for suppliers with vertically integrated alloy sourcing and documented recyclability credentials.
- Silicon carbide inverter pairing:Wide-bandgap power electronics operate at switching frequencies that demand faster current feedback loops, converging shunt resistor specifications with high-bandwidth sensing architectures.
Industry Challenges
- Automotive AEC-Q200 qualification timelines:Extended temperature cycling and humidity bias testing protocols stretch new product introduction cycles beyond 18 months, compressing effective revenue windows within technology generations.
- Calibration technician scarcity:Micro-ohm measurement accuracy requires specialized metrology expertise that competes with semiconductor and aerospace sectors for limited talent pools in precision electronics manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Shunt Resistor Market |
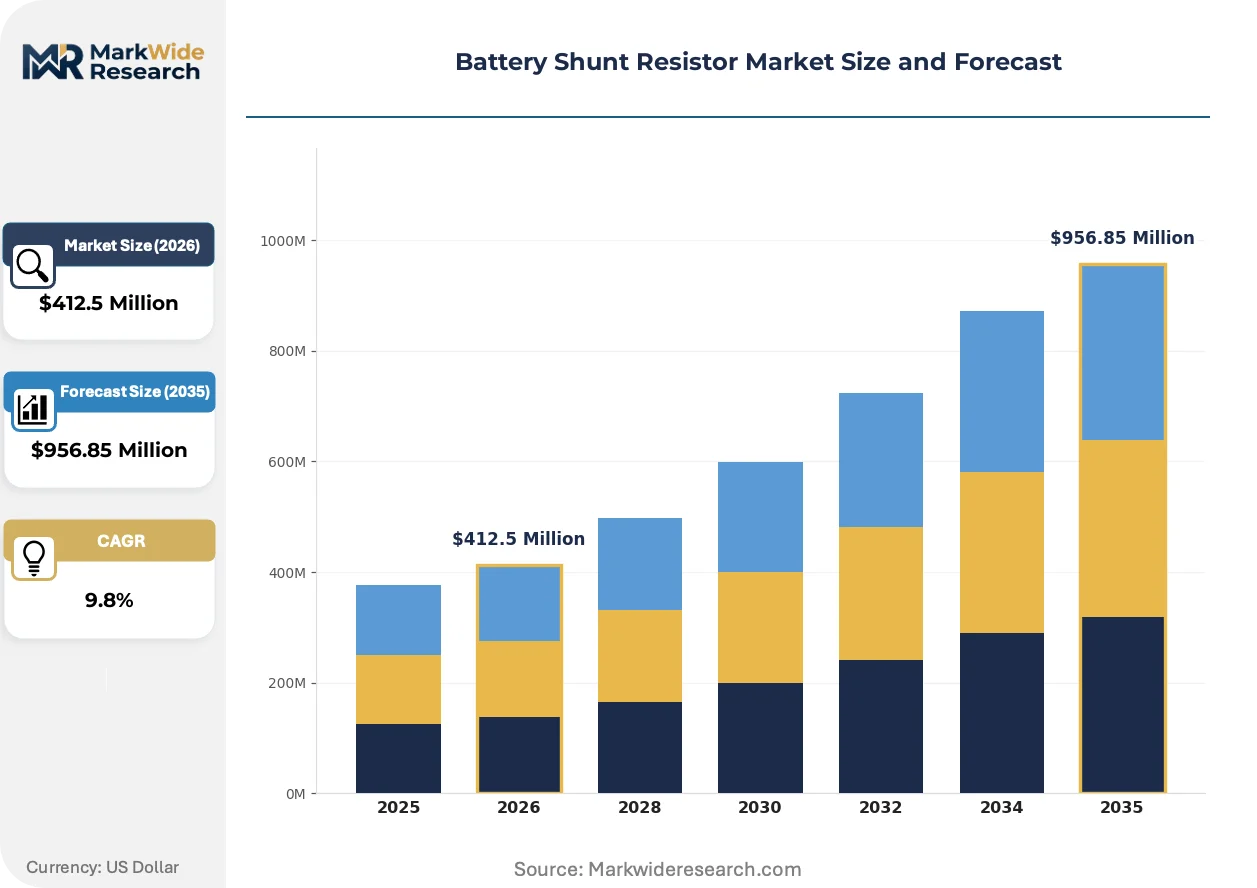
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $956.85 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Resistors, Adjustable Resistors, Power Resistors, High Precision Resistors Application: Automotive Systems, Renewable Energy Systems, Industrial Equipment, Consumer Electronics Technology: Wirewound, Thick Film, Thin Film, Metal Foil End User: OEMs, Aftermarket Providers, Research Institutions, Commercial Users |
| Companies Covered | Yageo Corporation, Panasonic Corporation, Vishay Intertechnology, Inc., Susumu Co., Ltd., KOA Corporation, Rohm Semiconductor, Ohmite Manufacturing Company, Isabellenhütte Heusler GmbH & Co. KG, TT Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Shunt Resistor Market Trends and Innovations
Bulk metal foil fabrication techniques are migrating from aerospace heritage applications into automotive battery systems, compressing thermal coefficient specifications while enabling direct cell-level integration.
Foil-based manganin shunts is converging with laser-trimmed resistance calibration to achieve sub-50 ppm temperature coefficients. Tier 1 battery pack integrators in Stuttgart and Shanghai are specifying these components for next-generation 800V architectures. The technology is converging with solid-state battery prototyping cycles, embedding current sensing into cell formats that eliminate external measurement harnesses.
China's MIIT mandates domestic content verification for EV battery testing equipment, creating certification friction for imported precision resistors. The regulation forces foreign suppliers to establish localized calibration laboratories or partner with licensed domestic distributors. European automotive OEMs are responding by dual-sourcing from MIIT-approved facilities while maintaining ISO 17025 traceability for export markets.
Direct procurement from resistor manufacturers is displacing traditional electronics distributor channels for high-volume battery programs. Tier 1 suppliers in Germany negotiate multi-year alloy supply agreements that bypass regional distribution markups. This pattern concentrates most visibly in automotive clusters around Munich and Wolfsburg, where cell monitoring unit integrators consolidate vendor bases to secure allocation priority during raw material constraints.
Battery Shunt Resistor Market Segmentation
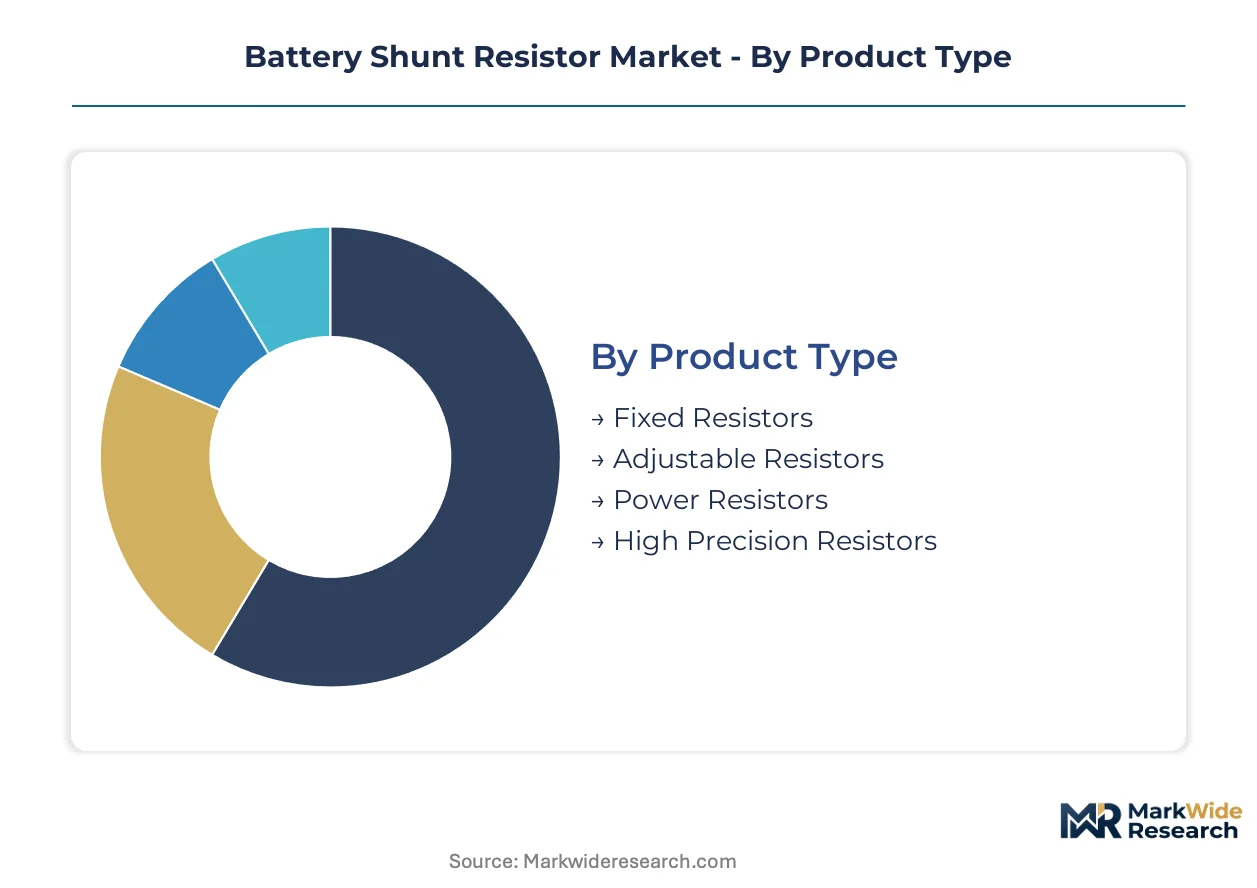
Precision requirements diverge sharply across battery shunt resistor applications. Cell-to-pack architectures and 800V traction systems fragment demand into specialized performance tiers that resist commoditization.
Product Type:
Standardization dominates low-current consumer applications while automotive battery management systems force custom micro-ohm specifications with certified thermal drift performance.
- Fixed Resistors:Manganin and constantan alloys calibrated to micro-ohm tolerances serve as the workhorse for embedded cell monitoring units. Demand concentrates in Stuttgart automotive clusters where Tier 1 integrators specify AEC-Q200 qualified components for 800V architectures.
- High Precision Resistors:Bulk metal foil construction achieves sub-50 ppm temperature coefficients through laser-trimmed resistance calibration. German OEMs source these for EPA range certification protocols requiring accurate coulomb counting across thermal cycling extremes.
- Power Resistors:Wirewound designs retain cost advantages in grid-scale energy storage current sensing.
- Adjustable Resistors:Laboratory and prototyping applications require manual calibration capability for battery test benches.
Leading the category by volume: Fixed Resistors. Growing fastest: High Precision Resistors.
Application:
Automotive qualification timelines stretch 18-plus months while industrial buyers prioritize cost over certified traceability.
- Automotive Systems:Direct integration into cell monitoring units replaces external measurement racks. Munich and Wolfsburg battery pack integrators negotiate multi-year supply agreements that bypass distribution channels.
- Industrial Equipment:Wirewound shunts dominate high-current motor drives and uninterruptible power supplies where miniaturization carries less premium than thermal robustness.
- Renewable Energy Systems:Grid-scale installations in California adopt automotive-grade sensing for warranty validation with compressed qualification timelines.
- Consumer Electronics:Power tool and e-bike battery packs drive volume demand for standard tolerance shunts.
Automotive Systems commands the revenue concentration. Renewable Energy Systems shows the steepest expansion trajectory as grid storage deployment accelerates.
Technology:
Capital intensity separates thin film precision from wirewound commodity production.
- Thin Film:Vacuum-deposited resistive elements on ceramic substrates enable miniaturization for cell-level integration. Shanghai battery pack designers specify these for MIIT-compliant domestic content verification.
- Metal Foil:Bulk metal foil heritage from aerospace applications migrates into EV systems with unmatched temperature stability. Isabellenhütte's ZERANIN alloys anchor European automotive supply chains.
- Wirewound:Precision alloy wire wound on ceramic cores retains cost advantages in high-current industrial settings.
- Thick Film:Screen-printed resistive pastes serve cost-sensitive applications with moderate precision requirements.
Metal Foil leads on margin per unit. Thin Film gains share fastest as 800V architectures proliferate.
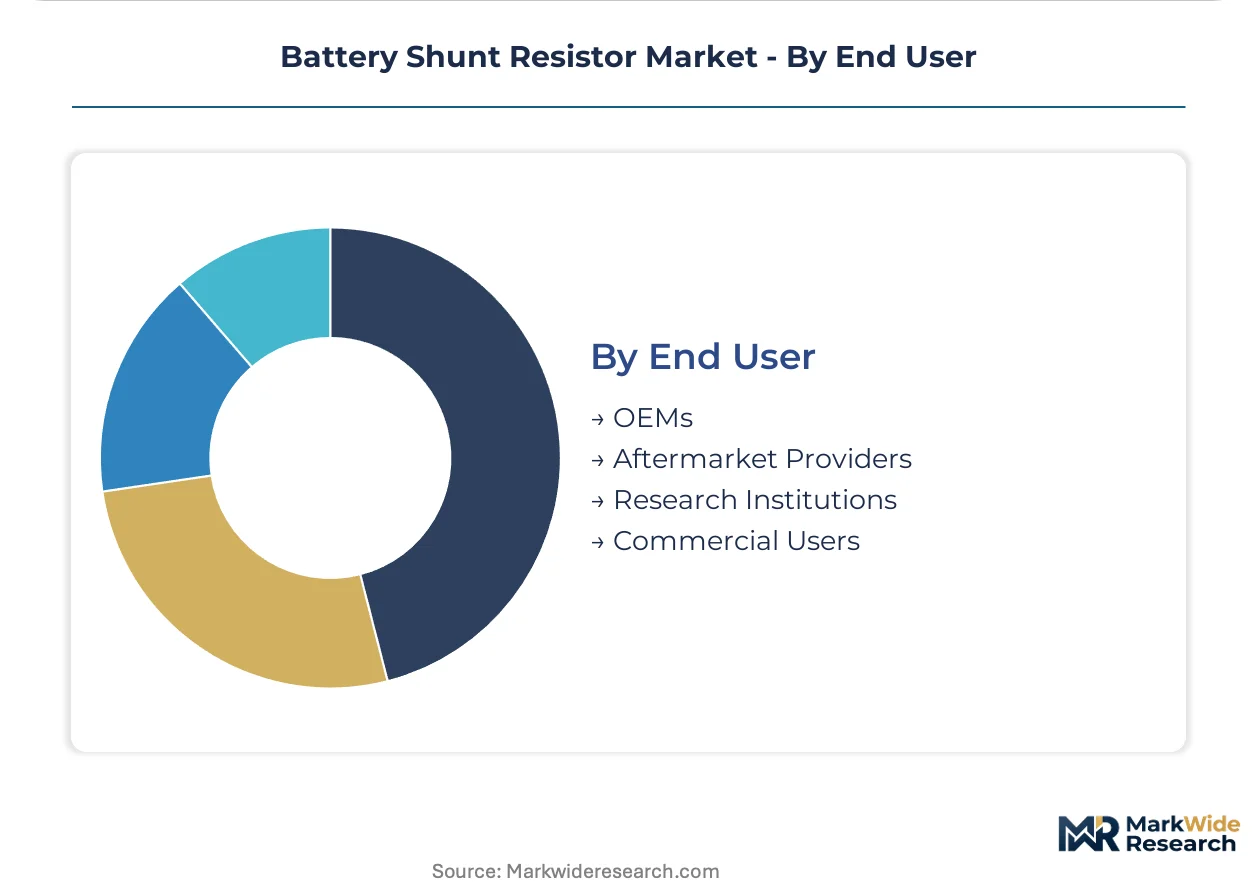
End User:
Procurement centralization distinguishes direct OEM engagement from fragmented aftermarket distribution.
- OEMs:Battery pack integrators in Germany and China consolidate vendor bases to secure allocation priority during raw material constraints. Dual-sourcing from MIIT-approved facilities maintains ISO 17025 traceability.
- Aftermarket Providers:Independent battery service networks source replacement shunts through traditional electronics distributors with longer lead times.
- Research Institutions:Solid-state battery prototyping cycles demand custom sensing formats for experimental cell designs.
- Commercial Users:Fleet operators and energy storage developers specify shunts for warranty validation in stationary applications.
OEMs dominate procurement volume. Research Institutions expand most quickly as next-generation battery chemistry development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive battery pack production concentrates in Germany, China, and the United States, with precision resistor demand tracking OEM assembly locations and domestic content regulations. Each geography imposes distinct certification protocols that reshape supplier qualification requirements.
Germany
Stuttgart and Wolfsburg battery integrators specify AEC-Q200 qualified shunts for 800V traction systems. The EU Green Deal's battery passport mandates traceable alloy sourcing through 2030. Isabellenhütte's Dillenburg facility processes proprietary ZERANIN alloys for Munich-based cell monitoring unit suppliers.
China
MIIT domestic content verification rules force foreign resistor suppliers to establish localized calibration laboratories. Shanghai battery pack designers specify thin film shunts for compliance with GB/T testing standards. Yangtze River Delta cell manufacturers consolidate vendor bases to secure allocation priority during raw material constraints.
United States
EPA tailpipe efficiency mandates push Detroit-area OEMs toward higher-precision coulomb counting for range certification. Michigan battery pack assembly plants source micro-ohm shunts directly from manufacturers, bypassing traditional distribution channels. California grid-scale storage installations adopt automotive-grade sensing for warranty validation.
Japan
METI-funded solid-state battery prototyping creates demand for custom sensing formats in experimental cell designs. Nagoya-area automotive electronics suppliers qualify foil-based manganin shunts for next-generation traction systems. Osaka precision alloy producers face competition from German and Chinese metallurgical facilities.
South Korea
Seoul Capital Area battery manufacturers integrate shunts directly into cell monitoring units for domestic EV platforms. Busan-Ulsan industrial corridors host wirewound resistor production for high-current energy storage applications. KSA battery testing standards align with MIIT accuracy thresholds, easing export qualification to China.
Battery Shunt Resistor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision automotive applications favoring in-house alloy processing while industrial buyers accept distributor-sourced alternatives. The vendor base organizes around three archetypes: vertically integrated metallurgical houses with captive alloy production, thin film deposition specialists leveraging semiconductor equipment, and wirewound commodity producers serving cost-sensitive industrial channels. Capacity expansion and strategic partnerships dominate competitive moves as OEMs consolidate vendor bases to secure allocation priority.
Within the precision alloy tier, Isabellenhütte Heusler GmbH & Co. KG exemplifies the European vertically integrated model, while Vishay Intertechnology, Inc. represents North American foil technology heritage migrating from aerospace into automotive applications. Susumu Co., Ltd. occupies a position among Japanese thin film specialists serving high-frequency sensing architectures. These anchors illustrate how geographic concentration of metallurgical expertise and deposition technology shapes competitive positioning across regulatory jurisdictions.
| Leading Market Players |
|---|
| Yageo Corporation |
| Panasonic Corporation |
| Vishay Intertechnology, Inc. |
| Susumu Co., Ltd. |
| KOA Corporation |
| Rohm Semiconductor |
| Ohmite Manufacturing Company |
| Isabellenhütte Heusler GmbH & Co. KG |
| TT Electronics |
| Others |
Pricing and Supply Chain Analysis
Manganese-copper alloy feedstock originating from German and Japanese metallurgical facilities flows through three distinct pricing tiers before reaching battery pack integrators, with AEC-Q200 certification premiums separating automotive-grade precision from industrial commodity grades.
Pricing Analysis
High-volume wirewound shunts for industrial motor drives trade on thin margins while bulk metal foil precision resistors command substantial premiums from Stuttgart OEMs. Price differentiation rests on thermal coefficient certification and MIIT compliance verification, with automotive buyers showing minimal sensitivity compared to cost-optimized grid storage developers. Pricing pressure stems from thin film capex intensity as vacuum deposition equipment stretches capital recovery timelines, compressing returns for mid-tier entrants attempting precision specifications.
Supply Chain Analysis
Freight costs for precision alloy shipments from Dillenburg to Shanghai battery pack designers have risen as MIIT domestic content rules force localization of calibration capacity. Supply concentrates in Germany, Japan, and China, with proprietary ZERANIN and manganin formulations drawing from concentrated manganese and copper smelting capacity. Single-source vulnerability pervades specialized alloy feedstock, while distribution runs through direct manufacturer procurement that bypasses traditional electronics distributors for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery shunt resistor market sits in a technology-transition phase as bulk metal foil architectures displace legacy wirewound designs in 800V traction systems, forcing incumbents and entrants to recalibrate around thermal precision rather than current capacity.
For Market Incumbents: Acquire captive alloy processing capabilities to secure manganin and constantan supply chains against German and Japanese feedstock concentration. Isabellenhütte's vertically integrated Dillenburg model demonstrates defensibility against thin film specialists lacking metallurgical heritage. Invest in AEC-Q200 qualification pipelines to compress 18-month automotive certification cycles before solid-state battery prototyping accelerates. For New Entrants and Emerging Players: Laser-trimmed resistance calibration technology offers entry into the precision tier without legacy wirewound infrastructure. Stationary energy storage systems in California and Germany present the most penetrable white space, with warranty validation requirements less stringent than automotive qualification timelines. Partner with Yangtze River Delta cell manufacturers seeking MIIT-compliant domestic content verification. For Investors and Strategic Acquirers: EPA tailpipe rule tightening is the leading indicator that coulomb counting precision will command sustained premium pricing across the analysis window. Target metallurgical houses with in-house alloy formulation and ISO 17025 calibration laboratories as acquisition archetypes. Watch for MIIT expanding domestic content verification beyond testing equipment into component sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Smelting | Captive manganese-copper processing insulates margins from German and Japanese feedstock concentration. |
| MIIT Calibration Laboratory Localization | Shanghai-certified facilities unlock access to domestic EV battery testing equipment procurement. |
| AEC-Q200 Qualification Pipeline Investment | Compressed 18-month certification cycles align revenue windows with 800V architecture adoption. |
| Solid-State Battery Sensing Partnership | Embedded current sensing for experimental cell formats eliminates external measurement harnesses. |
| EU Battery Passport Traceability Program | Documented recyclability credentials command premium positioning under Green Deal mandates. |
Research Methodology
Multi-period observation of alloy pricing spreads, AEC-Q200 qualification timelines, and MIIT regulatory filings anchored the trend analysis, supplemented by interviews with Tier 1 battery pack procurement officers, precision resistor manufacturing engineers, automotive platform electrification leads, and calibration laboratory managers. Secondary validation drew from EPA tailpipe rulemaking dockets, EU Green Deal battery passport implementation guidance, China GB/T standard revision notices, and customs trade data for manganin and constantan alloy shipments. Bottom-up unit demand modeling triangulated against top-down OEM production forecasts.
The input-output matrix structured demand across product type, application, technology, and end-user dimensions, with value outputs derived from pricing tier segmentation throughout the projection horizon. CAGRs emerged from fitted growth curves applied to EV battery pack production trajectories, stationary energy storage deployment pipelines, and semiconductor deposition equipment capacity expansion. Alloy supply concentration indices and automotive qualification backlog durations fed industry-specific sensitivity parameters.
Several conditions sit outside the modeled scope, including unannounced solid-state battery chemistry transitions, abrupt RoHS substance restriction expansions, and geopolitical disruptions to German-Japanese metallurgical supply corridors. Forecasts reflect documented assumptions around EPA rule stability and MIIT enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Intel Motherboards Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Touchless Tubes Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Amplifier Market
Electronic Components
Pneumatic Components Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Electric Fuse Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
Braking Resistors Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Switch Diode Market