
 Class D Audio Amplifier Market | 2026-2036
Class D Audio Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Class D Audio Amplifier Market Intelligence
The shift from consumer electronics to automotive applications is reorganizing the competitive landscape. Original equipment manufacturers in the automotive sector now command significant volume, influencing product roadmaps. Texas Instruments leverages its broad portfolio to serve both high-volume consumer and stringent automotive clients. STMicroelectronics specializes in automotive-grade solutions, while Infineon Technologies competes on power efficiency and thermal performance for professional audio systems.
A Class D audio amplifier is a switching amplifier that uses pulse-width modulation (PWM) to achieve very high efficiency, often exceeding 90%. This design minimizes heat dissipation, making it ideal for compact and battery-powered devices. Multichannel amplifiers represent the fastest-growing product type, driven by demand from automotive sound systems. The portable speaker systems application also relies heavily on Class D technology for its combination of audio power and extended battery life.
Compliance with electromagnetic interference (EMI) standards, such as those set by the US Federal Communications Commission (FCC), is a critical design constraint. In Europe, CE marking and RoHS directives govern product safety and material composition, influencing component selection. These regulations create a complex environment for semiconductor suppliers. Success hinges on developing architectures that balance audio fidelity, thermal management, and adherence to evolving international energy efficiency mandates.
Market Dynamics
The central dynamic shaping the Class D audio amplifier market is the escalating demand for high-fidelity audio performance clashing with stringent global energy efficiency mandates. This creates a technical and commercial tension that semiconductor suppliers must resolve through architectural innovation.
Growth Catalysts
- Automotive Systems Expansion:The proliferation of multi-channel premium sound systems in vehicles, from luxury sedans to mainstream SUVs, creates substantial volume demand for compact, efficient, and powerful multichannel amplifiers.
- EU Ecodesign Directive:European energy efficiency regulations, particularly the Ecodesign Directive, mandate lower standby and operational power consumption for consumer electronics, directly favoring the inherent high-efficiency characteristics of Class D amplifier architectures.
- Portable Audio Devices:The portable speaker and personal audio systems segment depends on Class D technology to deliver high acoustic output and extended battery life, a combination unattainable with less efficient amplifier classes.
Market Restraints
- EMI Compliance Complexity:The high-frequency switching nature of Class D amplifiers generates significant electromagnetic interference, requiring complex and costly filtering and shielding solutions to meet standards like the FCC Part 15 regulations in the United States.
- Advanced Semiconductor Costs:High-performance designs increasingly use Gallium Nitride (GaN) transistors to improve efficiency and power density, but the higher cost of GaN wafers compared to traditional silicon limits adoption in price-sensitive consumer applications.
- Fidelity Perception:Despite technical advances, a persistent audiophile community perception holds that Class D amplifiers are sonically inferior to traditional Class A/B designs, restraining adoption in the high-end, two-channel audio market.
Strategic Opportunities
- Smart Home Integration:The growth of voice-activated smart speakers and integrated home audio systems from manufacturers in the United States and China presents a significant volume opportunity for highly integrated, low-cost Class D amplifier SoCs.
- GaN-on-Silicon (GaN-on-Si):The maturation of GaN-on-Si process technology offers a path to lower the cost of Gallium Nitride devices, potentially unlocking their performance benefits for mainstream automotive and consumer electronics applications.
- Professional Audio Systems:Power-intensive professional applications, including concert sound reinforcement and public address systems, offer a high-margin opportunity for robust, high-power Class D modules that can displace heavy and inefficient legacy amplifiers.
Industry Challenges
- Fragmented Regulatory Environment:Manufacturers face a complex web of compliance requirements, including Europe's CE marking and RoHS directives for safety and materials, alongside China's distinct GB standards, complicating global product development and certification.
- Specialized Design Talent:A scarcity of engineers with combined expertise in high-frequency power electronics, analog signal processing, and thermal management creates a bottleneck in developing next-generation, highly optimized Class D amplifier designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Class D Audio Amplifier Market |
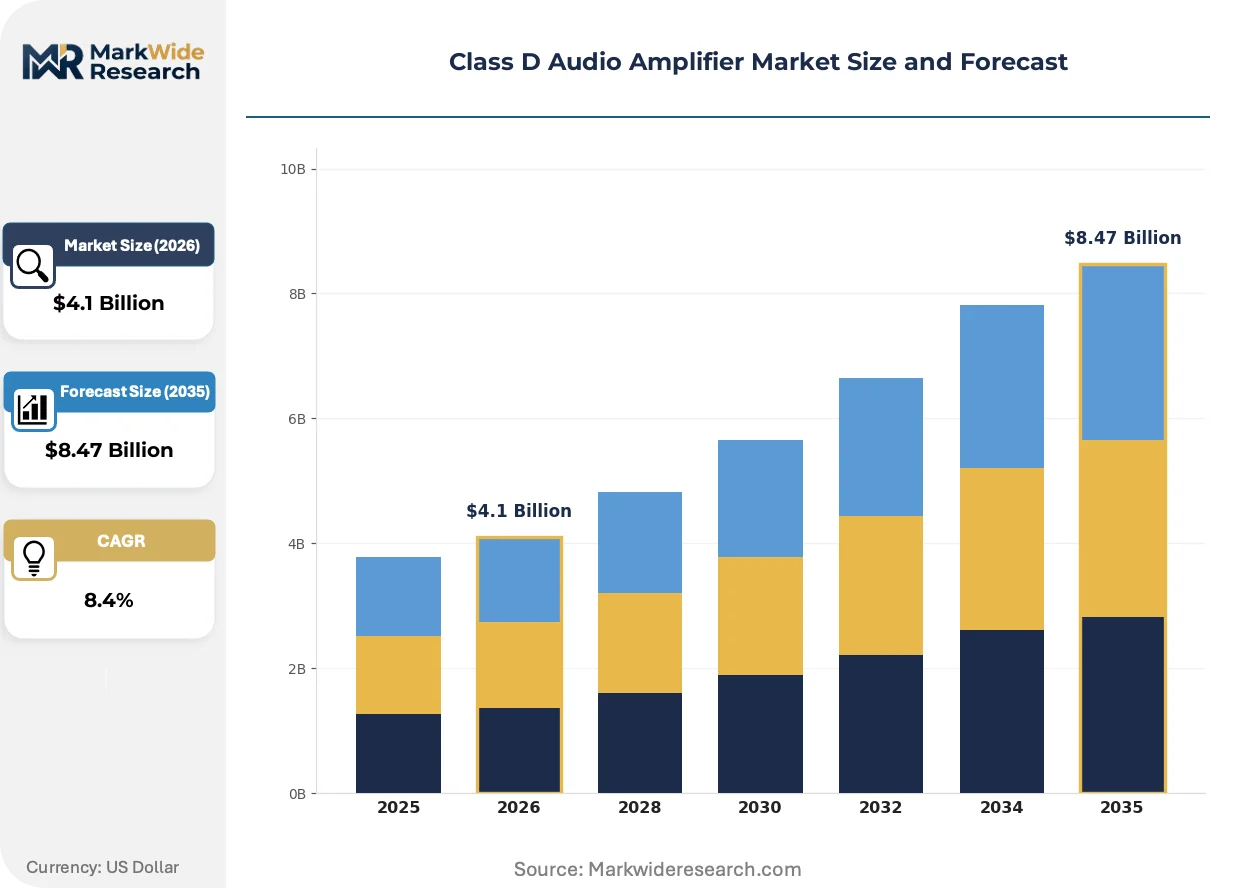
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono Amplifiers, Stereo Amplifiers, Multichannel Amplifiers, Subwoofer Amplifiers Technology: PWM Modulation, Sigma-Delta Modulation, Self-Oscillating Modulation, Hybrid Modulation Application: Consumer Electronics, Professional Audio, Automotive Sound Systems, Portable Speaker Systems End User: Original Equipment Manufacturers, Audio Equipment Retailers, Event Management Companies, Electronic Product Distributors |
| Companies Covered | NXP Semiconductors, ROHM Semiconductors, Texas Instruments, Qualcomm Technologies, STMicroelectronics, Infineon Technologies, ON Semiconductor, Cirrus Logic, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Class D Audio Amplifier Market Strategic Shifts & Innovations
Technological advancement is focused on greater system-level integration, embedding more intelligence and control alongside the core amplification function. This evolution is transforming the amplifier from a simple power block into a sophisticated, software-defined audio processing node.
GaN Transistor Adoption
Gallium Nitride (GaN) semiconductor technology enables significantly higher switching frequencies and lower switching losses compared to traditional silicon MOSFETs. High-end automotive audio and professional sound system manufacturers are progressively adopting GaN-based designs. This advancement is decomposing the historical trade-off between power efficiency, physical size, and audio fidelity, enabling compact designs with superior performance.
Software-Defined Audio Processing
New amplifier integrated circuits incorporate powerful Digital Signal Processors (DSPs), allowing for real-time software-based audio correction, equalization, and speaker protection. This shift gives automotive and consumer electronics brands immense flexibility to tune audio characteristics and differentiate their products without hardware changes. The most significant impact is in automotive cabins, where DSPs correct for complex interior acoustics.
Procurement Model Evolution
Automotive original equipment manufacturers are changing how they source audio systems, moving from buying individual amplifier chips to procuring complete, pre-validated audio subsystems from Tier 1 suppliers. This disrupts direct sales channels for semiconductor firms, forcing them to establish deeper partnerships with system integrators like Harman or Bose. This trend is most visible in the electric vehicle sector, where audio systems are a key element of the user experience.
Class D Audio Amplifier Market Segmentation
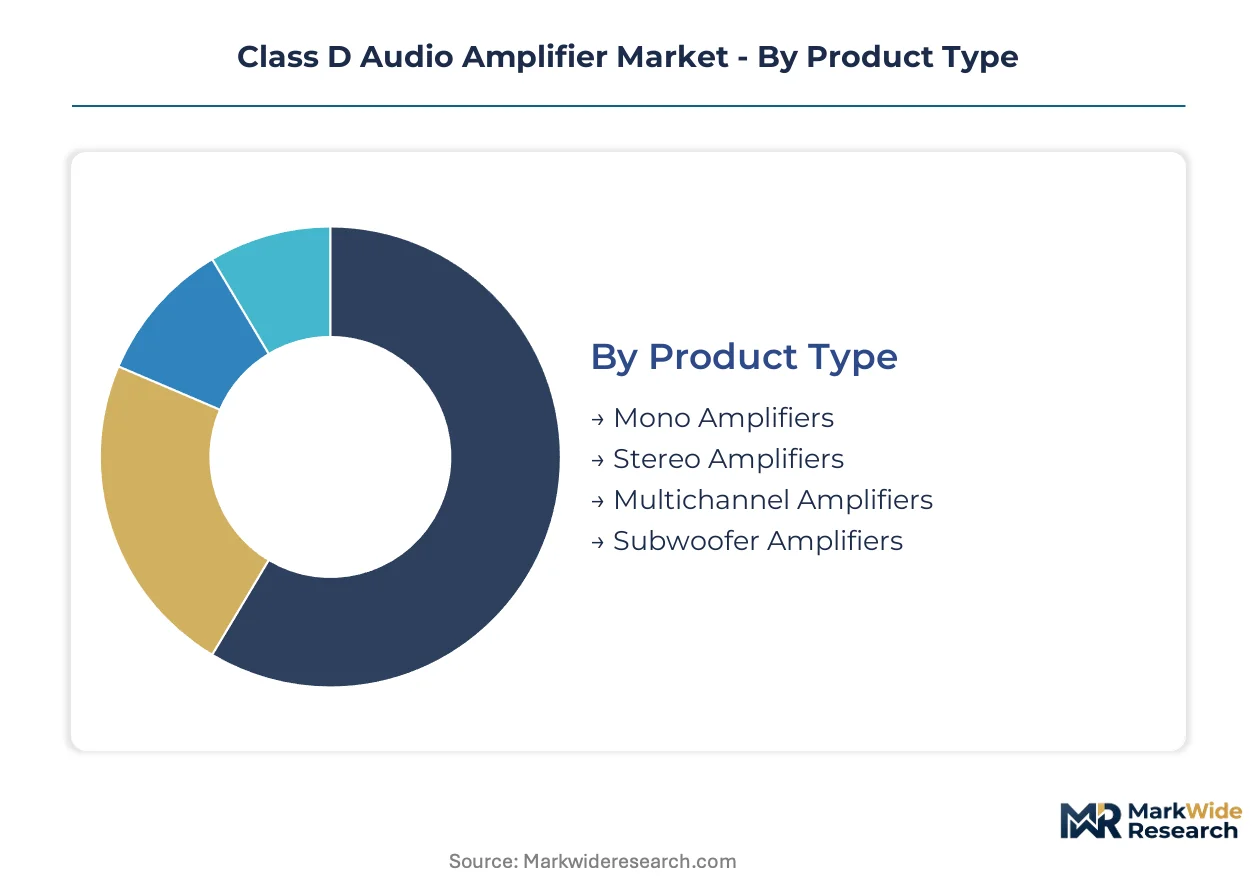
The Class D audio amplifier market segments across diverse dimensions, reflecting specialized design requirements and varied end-user demands. Understanding these distinctions helps semiconductor suppliers and system integrators align product development with specific market needs. This granular view reveals where innovation is most impactful and where commercial opportunities are concentrating.
Product Type:
This product type segmentation highlights amplifier configurations tailored for specific audio channel requirements, with certain types demonstrating strong export-led demand from manufacturing hubs in China.
- Multichannel Amplifiers:These designs integrate multiple amplification channels, enabling complex sound staging and surround sound experiences. Demand concentrates within the automotive sector, where premium sound systems and higher channel counts are standard for new vehicle models.
- Stereo Amplifiers:These amplifiers provide two discrete channels for left and right audio signals, forming the backbone of traditional two-channel audio systems. This product type sees significant demand in consumer electronics for home audio setups globally.
- Mono Amplifiers:These units deliver a single channel of amplified audio, primarily used for driving subwoofers or simple, single-speaker applications.
- Subwoofer Amplifiers:Specifically designed to power subwoofers, these optimize for low-frequency reproduction and often include dedicated crossover circuits.
Multichannel Amplifiers hold the largest share; momentum sits with Multichannel Amplifiers.
Technology:
Technology segmentation differentiates Class D amplifiers based on their modulation schemes, directly impacting efficiency, output fidelity, and component cost tiers.
- PWM Modulation:Pulse-width modulation is the most common Class D switching technique, converting analog audio into varying width pulses. This approach underpins most Class D designs, providing high efficiency for consumer electronics and automotive applications.
- Hybrid Modulation:This advanced approach combines different modulation techniques to optimize performance, balancing efficiency with reduced electromagnetic interference. Hybrid modulation finds increasing favor in high-fidelity professional audio systems.
- Sigma-Delta Modulation:Utilizing oversampling and noise shaping, this offers high linearity and reduced distortion, beneficial for high-resolution audio.
- Self-Oscillating Modulation:This simpler method employs a feedback loop to generate the switching frequency, offering cost-effective solutions for portable devices.
PWM Modulation accounts for the highest volume of units shipped; Hybrid Modulation exhibits the steepest expansion trajectory.
Application:
Application segments reveal how Class D amplifiers are deployed across various end-use environments, each presenting unique demands for power output, thermal management, and integration complexity.
- Automotive Sound Systems:This application integrates amplifiers into vehicle audio architectures, requiring robustness against temperature extremes, vibration, and stringent electromagnetic compatibility. Proliferation of multi-channel premium sound systems drives substantial volume demand.
- Portable Speaker Systems:Class D technology is crucial here, enabling high acoustic output from compact form factors while maximizing battery life. Consumer demand for extended playback from manufacturers in the United States and China influences amplifier design.
- Consumer Electronics:This broad category includes home theater systems, soundbars, and smart speakers, where efficiency and compact size are critical for mass-market appeal.
- Professional Audio:High-power applications like concert sound reinforcement and public address systems leverage Class D for its efficiency and reduced weight.
Automotive Sound Systems represent the largest segment; Portable Speaker Systems are gaining share fastest.
End User:
End-user segmentation identifies the primary purchasers and integrators of Class D amplifier components and modules, reflecting distinct procurement models and supply chain relationships.
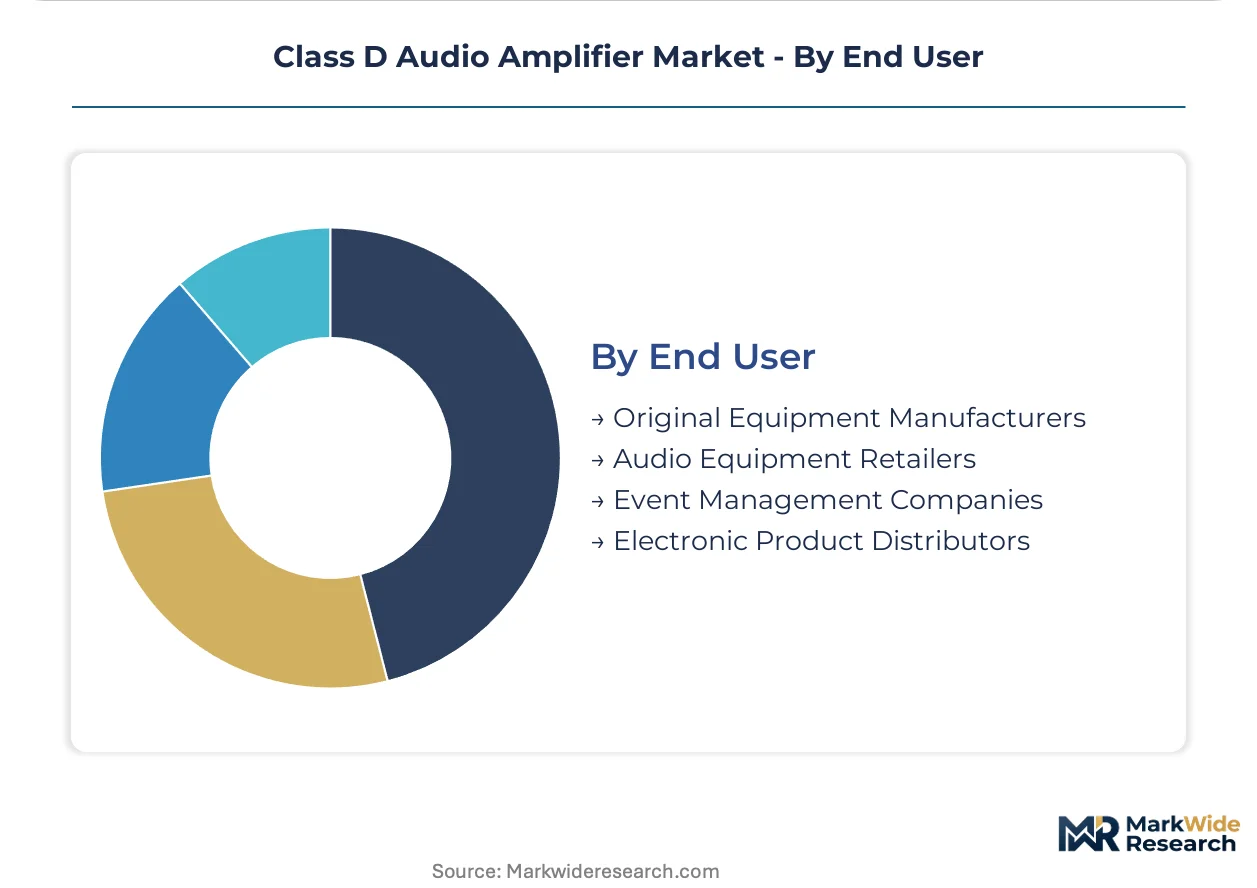
- Original Equipment Manufacturers:OEMs in automotive and consumer electronics integrate Class D amplifier chips directly into their products. These entities command significant volume, influencing product roadmaps and demanding customized solutions.
- Electronic Product Distributors:These companies act as intermediaries, supplying amplifier components to smaller manufacturers, system integrators, and design houses. Distributors play a critical role in reaching fragmented markets.
- Audio Equipment Retailers:These outlets sell finished audio products containing Class D amplifiers directly to consumers, including home theater systems.
- Event Management Companies:These firms utilize high-power Class D amplifier systems for live sound reinforcement, concerts, and public address at large-scale events.
Original Equipment Manufacturers drive the most significant volume; Event Management Companies are climbing the fastest in specialized demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast electronics manufacturing ecosystem supplies global markets, including high-volume consumer and automotive segments. This robust supply chain supports the expanding Class D audio amplifier market through efficient component production and assembly. High efficiency and compact size remain critical for widespread global adoption across diverse applications.
China
Domestic and export markets for consumer and automotive audio systems drive substantial demand for Class D amplifiers. China's GB standards influence product safety and material composition for electronic components, including audio devices. The Pearl River Delta region concentrates major electronics assembly operations, facilitating high-volume amplifier integration into finished goods.
United States
A strong consumer electronics market, particularly for portable speaker systems, and a growing automotive sound system sector fuel amplifier demand. FCC Part 15 regulations govern electromagnetic interference, posing a critical design constraint for Class D amplifier manufacturers. Silicon Valley houses significant analog and mixed-signal semiconductor design firms, innovating advanced amplifier architectures.
Germany
The premium automotive sound systems segment and professional audio applications represent significant demand drivers in Germany. The EU Ecodesign Directive mandates energy efficiency for electronic products, directly favoring highly efficient Class D technology. Munich and Stuttgart host major automotive OEMs and Tier 1 suppliers, influencing amplifier procurement models for luxury vehicles.
Japan
Advanced automotive audio systems, high-end consumer electronics, and professional sound equipment contribute to amplifier market growth. JIS standards ensure quality and performance for audio components used in both domestic and international products. Tokyo's electronics industry and automotive R&D centers drive innovation in compact, high-fidelity audio solutions.
South Korea
Global leadership in consumer electronics manufacturing and a substantial automotive production base create consistent demand for Class D amplifiers. The country's national regulatory bodies ensure compliance for electronic devices, including advanced audio systems. Seoul's technology parks foster semiconductor design and advanced audio system integration for global brands.
Class D Audio Amplifier Market Key Industry Players
Player mix skews toward established semiconductor manufacturers with broad product portfolios. The market is characterized by a blend of large, diversified players and specialized component providers focused on specific application niches. Diversified semiconductor giants, specialized automotive solution providers, and emerging GaN technology innovators represent key strategic archetypes. Strategic partnerships with Tier 1 automotive suppliers and continuous portfolio diversification are common competitive moves.
Diversified semiconductor firms like Texas Instruments represent companies with broad portfolios serving both high-volume consumer and stringent automotive clients. STMicroelectronics exemplifies a specialized approach by focusing on automotive-grade solutions for vehicle audio systems. Infineon Technologies occupies a position emphasizing power efficiency and thermal performance, particularly for professional audio systems.
| Leading Market Players |
|---|
| NXP Semiconductors |
| ROHM Semiconductors |
| Texas Instruments |
| Qualcomm Technologies |
| STMicroelectronics |
| Infineon Technologies |
| ON Semiconductor |
| Cirrus Logic |
| Analog Devices |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts, particularly with major automotive original equipment manufacturers, lock in both stable supply access and predictable pricing visibility for semiconductor suppliers. This structure mitigates volatility for high-volume components, allowing for longer-term planning.
Pricing Analysis
The pricing gap between current-generation silicon-based Class D amplifiers and advanced GaN-based designs reflects a significant performance-cost trade-off. Per-unit transactional pricing dominates in high-volume consumer electronics, while contract-based long-term agreements secure automotive-grade solutions. Price differentiation stems from automotive-grade certification levels and the integration of advanced DSP capabilities. Pricing softness across the mass-market consumer segment intensifies due to fierce competition from Chinese manufacturers. Consumer electronics OEMs exhibit the highest price sensitivity, contrasting with premium automotive and professional audio clients.
Supply Chain Analysis
Current inventory levels for standard Class D amplifier components reflect stable lead times, but specialized GaN wafers face more constrained availability. Geographic supply concentration centers on semiconductor manufacturing hubs in Taiwan, South Korea, and China. Raw material dependencies include high-purity silicon wafers, gallium nitride substrates, and various passive components. Single-source vulnerability for advanced GaN transistors represents a structural supply chain risk. Distribution typically runs through direct sales channels to large OEMs and electronic product distributors serving smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents an early-cycle expansion story, with the proliferation of multi-channel premium sound systems in vehicles serving as a primary tailwind for adoption.
For Market Incumbents: Consolidate core competencies in established silicon-based architectures while strategically acquiring GaN technology specialists. This defensive move mitigates the threat from emerging GaN innovators and ensures a competitive offering across all performance tiers. Invest heavily in R&D for advanced GaN-on-silicon processes to reduce manufacturing costs and broaden market applicability.
For New Entrants and Emerging Players: Differentiate on power density and efficiency, targeting niches underserved by broad-portfolio incumbents. Professional audio systems and smart home integration represent penetrable segments for highly integrated, cost-optimized solutions. Focus go-to-market efforts on delivering software-defined audio processing capabilities as a key value proposition.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-centric firms specializing in advanced GaN solutions or integrated DSP capabilities. These targets offer long-term viability, driven by sustained demand for high-efficiency, high-fidelity audio. Watch for the maturation of GaN-on-Si process technology as a signal for broader market disruption and acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in GaN-on-Si R&D | Lowers cost of Gallium Nitride devices, unlocking mainstream automotive and consumer applications. |
| Deepen Automotive OEM Partnerships | Secures high-volume design wins and influences product roadmaps for next-generation vehicles. |
| Expand DSP Software Integration | Enables flexible audio tuning and product differentiation for consumer electronics brands. |
| Acquire Professional Audio Specialists | Captures high-margin opportunities in concert sound reinforcement and public address systems. |
| Strengthen EMI Compliance Expertise | Ensures adherence to FCC Part 15 regulations and CE marking for global market access. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Primary research involved discussions with automotive OEM engineers, semiconductor R&D leads, Tier 1 audio system integrators, and electronics distributors. Secondary sources included company financial reports, patent databases, regulatory filings from FCC and CE marking authorities, and industry association publications. A comprehensive bottom-up and top-down triangulation process validated all data points.
The forecasting boundary for this study encompassed a comprehensive analytical framework, projecting market evolution across the analysis window. This framework modeled segmentation dimensions including product type, technology, application, and end-user, alongside regional regulatory frameworks. Compound annual growth rates were derived through a robust statistical analysis, incorporating industry-specific inputs like vehicle production forecasts and smart speaker shipment volumes.
Forecasts assume regulatory continuity in key regimes like the EU Ecodesign Directive and FCC Part 15; material policy shifts would require re-modeling. The analysis accounts for potential risk factors such as rapid technological disruption or unforeseen component shortages. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Coaxial Attenuators Market
Electronic Components
Battery Holders Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Resonators Market
Electronic Components
Impulse Relays Market
Electronic Components
Global Circuit Protection Market
Electronic Components
2D Electronics Market
Electronic Components
Metal Oxide Varistor (MOV) Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Passive Attenuator Market
Electronic Components
Touch Screen Controllers Market
Electronic Components
Motherboard Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
United States MLCC Market
Electronic Components
Circuit Protection Kits Market