
 Audio Power Amplifier Market | 2026-2036
Audio Power Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Power Amplifier Market Analysis
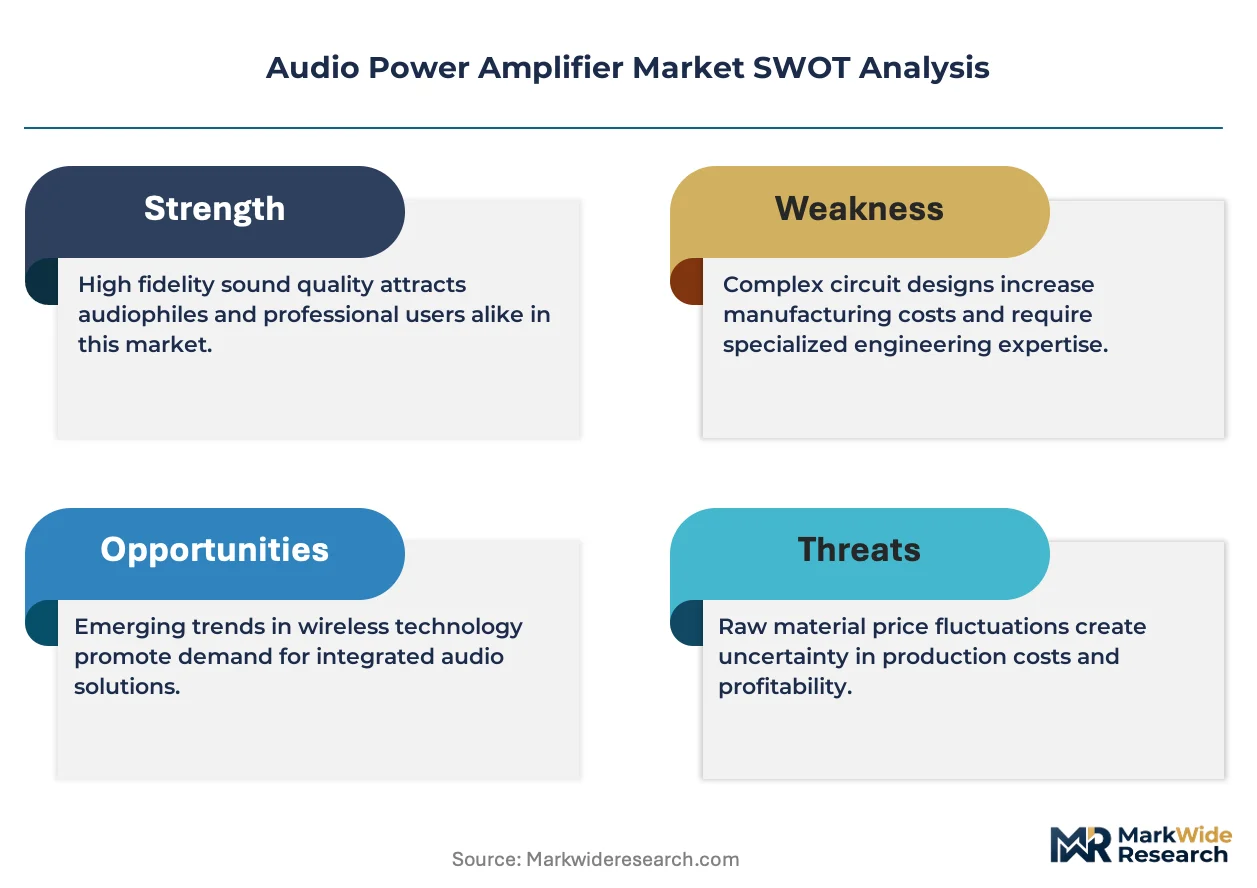
Gallium nitride is broadening the performance envelope for Class D amplifiers by enabling higher switching frequencies at reduced thermal loads. Texas Instruments Incorporated leverages its integrated manufacturing footprint to control die supply for automotive-grade amplifiers. Infineon Technologies AG anchors its position through proprietary GaN-on-Si process technology for premium audio segments. STMicroelectronics competes across the full Class AB-to-Class D spectrum with foundry partnerships in Europe and Asia.
An audio power amplifier is an electronic circuit that increases the amplitude of low-power audio signals to levels sufficient to drive loudspeakers, typically operating across frequency ranges of 20 Hz to 20 kHz with total harmonic distortion below 1 percent. Its primary commercial purpose is to deliver clean, high-current output for consumer, professional, and vehicular sound reproduction systems. Class D technology leads volume shipments due to efficiency advantages in battery-powered and thermally constrained environments, while integrated amplifiers capture margin pools in compact home audio systems where space and cost optimization dominate design priorities. Professional audio applications sustain premium pricing through demanding specifications for transient response and channel separation.
The EU Ecodesign Directive and REACH framework shape product development by mandating standby power limits and restricting hazardous substances in amplifier assemblies. The FCC in the United States governs electromagnetic emissions from switching amplifiers, particularly affecting Class D designs with high-frequency noise signatures. Japan's METI energy-labeling program drives efficiency benchmarking for consumer audio equipment sold in that market. Stakeholders must monitor how evolving GaN supply constraints and automotive functional-safety certifications under ISO 26262 reshape sourcing strategies and qualification timelines.
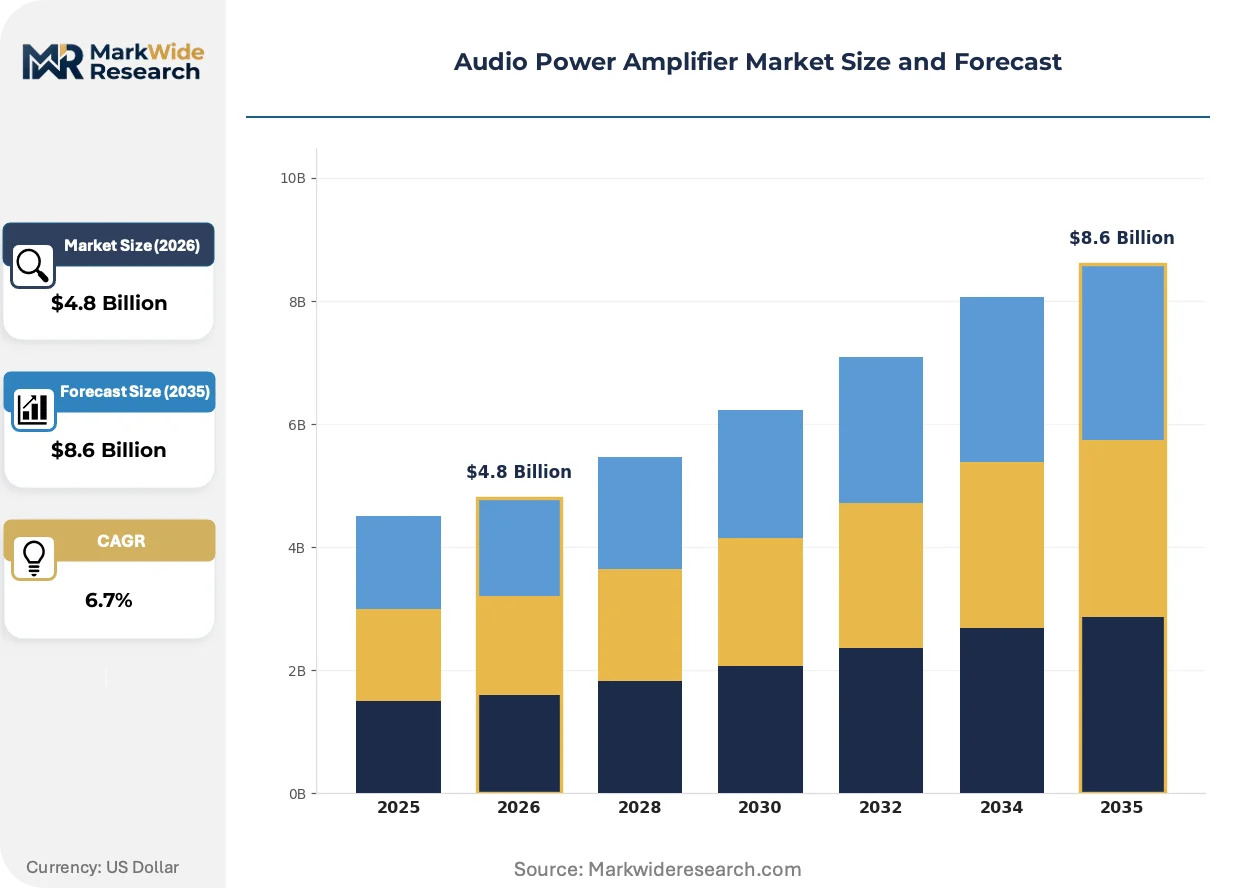
Market Dynamics
Gallium nitride power semiconductors are compressing thermal management costs for Class D architectures while EU standby-power mandates force redesign cycles across consumer and automotive product lines.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby power limits below 0.5 watts force manufacturers toward Class D topologies with inherently lower quiescent losses.
- Electric vehicle audio systems:Stuttgart and Munich automotive electronics clusters drive demand for efficient amplification in battery-constrained cabin environments.
- GaN-on-Si process maturation:Foundry scaling in Asia-Pacific reduces die costs for high-frequency switching applications previously dominated by silicon MOSFETs.
Market Restraints
- GaN substrate supply concentration:Epitaxial wafer production clusters in East Asian foundries create single-source vulnerability for premium amplifier tiers.
- ISO 26262 functional-safety certification:Automotive qualification timelines extend 18-24 months, freezing design wins for non-automotive-grade suppliers.
- Electromagnetic compatibility testing:FCC Part 15 emissions limits for Class D switching noise add $50,000-$150,000 per SKU in pre-compliance engineering.
Strategic Opportunities
- India BIS energy-labeling expansion:Mandatory efficiency grades for imported audio equipment create first-mover advantage for Class D suppliers with existing certification.
- Professional live-sound rental:Tour-grade amplifier fleets require modular, flight-case-compatible designs with networked monitoring capabilities.
- GaN-SiC hybrid switching:Converging wide-bandgap technologies enable multi-kilowatt output stages in half the chassis volume of legacy silicon designs.
Industry Challenges
- Analog-to-digital signal-path integration:Legacy Class AB design expertise does not transfer to DSP-controlled feedback architectures, creating talent scarcity in Midwest US and Central European manufacturing bases.
- REACH substance restrictions:Lead-free solder alternatives for high-thermal-cycling amplifier modules require requalification of entire supply chains under ECHA substance dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Power Amplifier Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Amplifiers, Power Amplifiers, Instrumentation Amplifiers, Operational Amplifiers, Others Technology: Class A, Class B, Class AB, Class D, Class G, Class H Application: Home Audio Systems, Professional Audio, Automotive Audio Systems, Public Address Systems, Portable Audio Devices, Broadcasting End User: Consumer Electronics Manufacturers, Sound Engineering Firms, Vehicle Manufacturers, Event Management Companies |
| Companies Covered | Texas Instruments Incorporated, Infineon Technologies AG, Analog Devices, Inc., STMicroelectronics, Broadcom, Skyworks Solutions, Inc., Renesas Electronics Corporation, NXP Semiconductors, Yamaha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Power Amplifier Market Emerging Trajectories
Wide-bandgap semiconductors and digital feedback architectures are compressing the performance gap between audiophile-grade linear amplifiers and efficient switching designs.
GaN HEMT power stages are overtaking silicon MOSFETs in premium Class D implementations by enabling switching frequencies above 1 MHz with sub-50 milliohm on-resistance. Tier-1 automotive suppliers in Germany and Japan have qualified GaN-based cabin amplifiers for 2027 model-year electric vehicles. This frequency headroom shrinks passive component sizes by 40 percent while reducing EMI filter costs.
REACH Annex XVII restrictions on halogenated flame retardants are forcing PCB laminate substitutions in amplifier assemblies sold across EU member states. Manufacturers must resubmit technical documentation to notified bodies for existing product lines. Professional audio OEMs with integrated in-house testing laboratories are internalizing compliance costs that previously flowed to third-party certification houses.
Automotive OEMs now specify amplifier modules with embedded diagnostic capabilities for predictive maintenance integration. Stuttgart-based tier suppliers are shipping Ethernet-AVB enabled units that stream real-time thermal and distortion telemetry to vehicle gateways. This behavioral shift is most visible in Germany's premium electric vehicle segment, where audio system downtime carries warranty exposure measured in thousands of euros per incident.
Audio Power Amplifier Market Segmentation
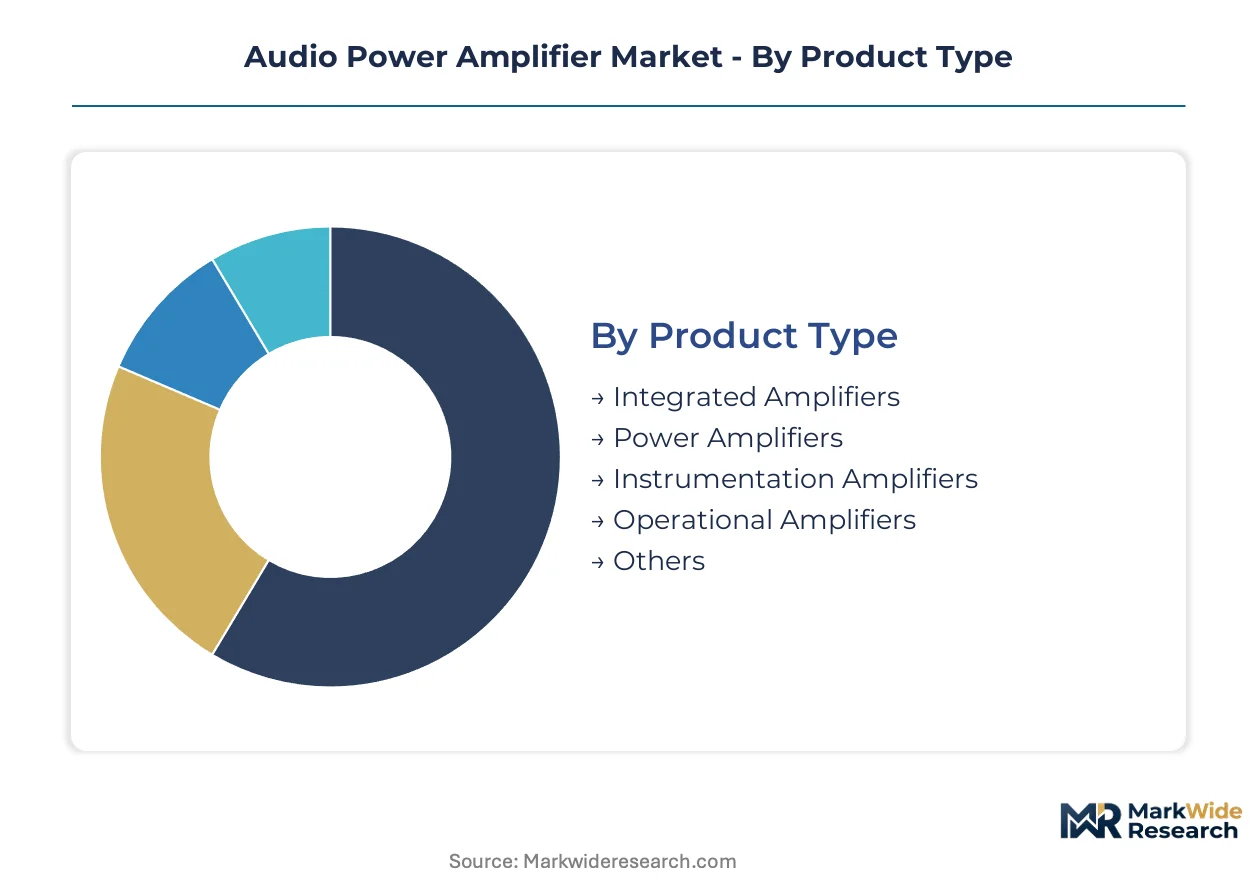
Amplifier segmentation reveals how integration depth shapes procurement patterns across consumer, automotive, and professional channels. Discrete power stages dominate high-current applications while integrated solutions capture space-constrained designs. Understanding these boundaries clarifies where GaN adoption and regulatory pressure concentrate competitive advantage.
Product Type:
Standalone amplifiers serve high-fidelity and professional installations where thermal headroom and upgrade paths matter; embedded variants shrink into smartphones, tablets, and vehicle head units where board space commands premium.
- Integrated Amplifiers:Combine preamplification and power stages in single chassis designs with shared power supplies and simplified signal routing. Home audio compact systems in Japan and Germany drive procurement as living-space constraints and METI efficiency labels push toward consolidated electronics.
- Power Amplifiers:Discrete output stages delivering dedicated current gain for loudspeaker drive, typically housed in separate enclosures with independent thermal management. Professional touring rigs and high-end residential installations in the United States sustain demand where channel count scalability and serviceability outweigh integration benefits.
- Instrumentation Amplifiers:Precision differential architectures with high common-mode rejection for sensor signal conditioning in measurement equipment. Laboratory and industrial automation OEMs specify these for audio-frequency vibration analysis and acoustic monitoring systems.
- Operational Amplifiers:General-purpose voltage amplification blocks operating in audio front-ends for filtering, buffering, and level translation. Consumer electronics manufacturers integrate billions annually into signal chains preceding Class D power stages.
- Others:Specialized architectures including current-feedback and transimpedance designs for niche measurement and broadcast applications. Broadcast infrastructure vendors in the United Kingdom and France specify these for studio monitoring chains.
Power amplifiers lead volumes today; integrated amplifiers are gaining share fastest.
Technology:
Topology selection trades efficiency against linearity, with switching architectures displacing linear designs wherever battery life or thermal budgets constrain system design.
- Class A:Continuous conduction through output devices delivering theoretically zero crossover distortion at the cost of 25% peak efficiency and substantial heat sinking. Audiophile-grade residential systems in Germany and Japan sustain niche production where distortion specifications below 0.001% justify energy waste.
- Class B:Complementary push-pull stages with each device conducting half the waveform, eliminating quiescent current but introducing crossover artifacts. Legacy public address installations in India and Brazil continue procurement for cost-sensitive voice-reinforcement where fidelity requirements remain modest.
- Class AB:Biased compromise between Class A and Class B, maintaining small quiescent current to reduce crossover distortion while preserving reasonable efficiency. Mid-tier home theater receivers and professional monitor controllers specify these where Class D switching noise remains unacceptable.
- Class D:Pulse-width modulation architectures achieving 90%+ efficiency through high-frequency switching, minimizing thermal management in battery-powered and space-constrained environments. Electric vehicle cabin systems and portable Bluetooth speakers drive steepest expansion trajectory as GaN devices enable MHz-range switching with reduced filter size.
- Class G:Rail-switching designs modulating supply voltage to track signal envelope, improving efficiency over Class AB without full switching complexity. Professional power amplifiers for live sound rental fleets adopt these where weight reduction matters and Class D EMI compliance costs prove prohibitive.
- Class H:Variants with continuously variable rail voltage approaching switching efficiency while maintaining linear output stage behavior. High-power subwoofer amplifiers in cinema and nightclub installations specify these for transient current delivery without switching artifacts.
Class D leads volumes today; Class G is climbing the fastest in professional channels.
Application:
Application boundaries determine whether efficiency, fidelity, or durability commands design priority, with automotive and professional segments imposing the most severe qualification requirements.
- Home Audio Systems:Residential stereo and multi-channel reproduction equipment spanning integrated microsystems through separates-based high-fidelity installations. European Ecodesign Directive standby limits below 0.5 watts force Class D adoption across mass-market product lines.
- Professional Audio:Touring-grade amplifiers, studio monitors, and installed sound reinforcement requiring 24/7 reliability and networked remote monitoring. Rental fleet operators in the United States and Germany specify modular chassis with hot-swappable power supplies and Ethernet-AVB telemetry.
- Automotive Audio Systems:Cabin amplification for infotainment, hands-free telephony, and premium branded audio packages. Stuttgart and Munich electronics corridors supply ISO 26262-qualified Class D modules for 2027 model-year electric vehicles with embedded diagnostic capabilities.
- Public Address Systems:Voice reinforcement for transportation hubs, educational institutions, and emergency notification networks. Indian railway and airport infrastructure projects drive volume procurement of 70V/100V constant-voltage distribution amplifiers.
- Portable Audio Devices:Battery-powered amplification in smartphones, tablets, wireless earbuds, and Bluetooth speakers. Shenzhen and Dongguan manufacturing clusters integrate wafer-scale Class D devices with MEMS microphones in single-package solutions.
- Broadcasting:Studio monitor amplification and transmitter audio processing for radio and television distribution. BBC and NPR technical specifications mandate extended frequency response and phase linearity beyond consumer requirements.
Portable audio devices lead volumes today; automotive audio systems are expanding most quickly.
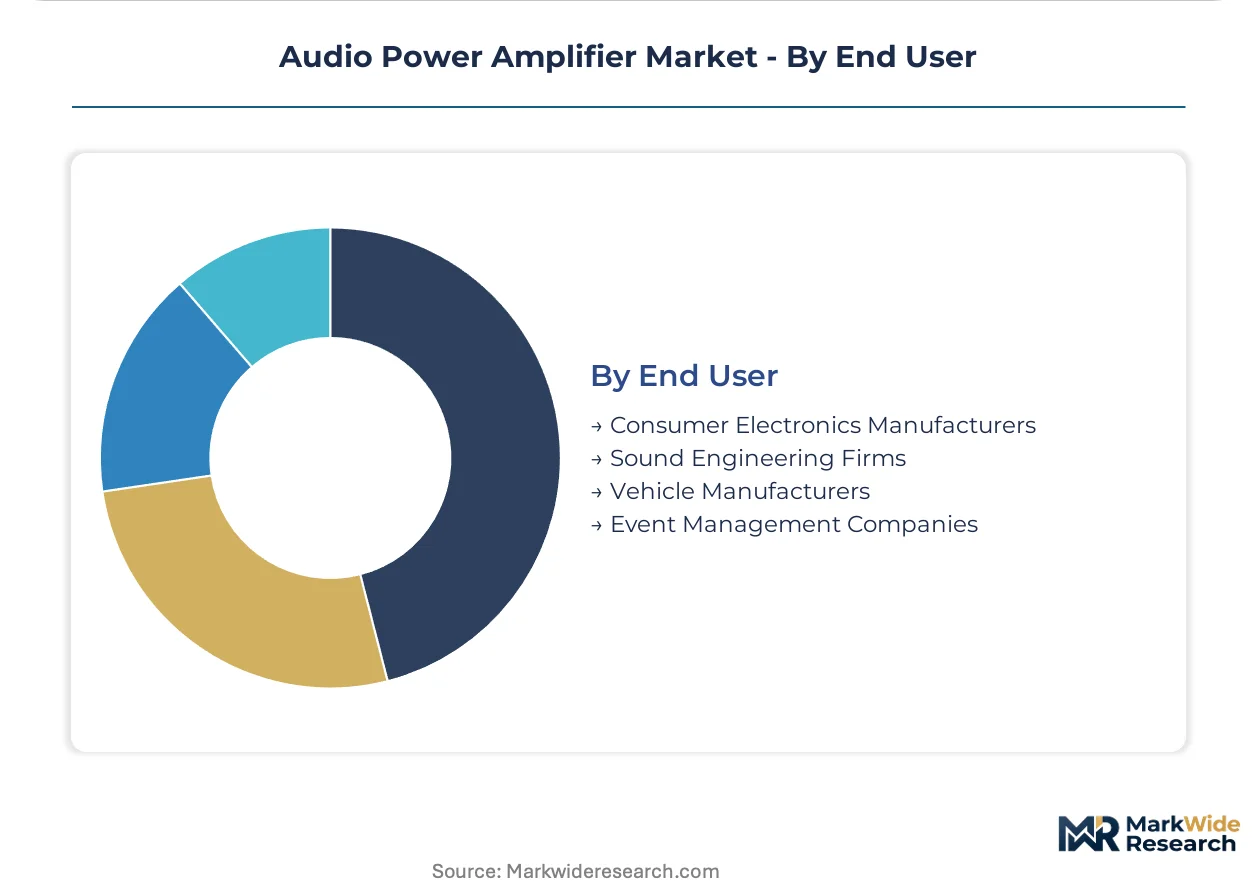
End User:
End-user categories reflect procurement sophistication, from specification-driven vehicle manufacturers to price-sensitive consumer electronics assemblers with compressed qualification cycles.
- Consumer Electronics Manufacturers:OEMs and ODMs assembling smartphones, televisions, home theater systems, and personal audio products. Foxconn, Luxshare, and Goertek procurement teams negotiate Class D die pricing on 12-month rolling forecasts with foundry partners in Taiwan and mainland China.
- Sound Engineering Firms:Independent contractors and production companies specifying and deploying amplification for live events, broadcast, and installed venues. Tour suppliers in Nashville and London prioritize amplifier weight, rental fleet interoperability, and remote monitoring over absolute distortion specifications.
- Vehicle Manufacturers:Tier-1 automotive suppliers and OEM audio engineering groups integrating cabin amplification with infotainment head units. BMW, Mercedes-Benz, and Volkswagen procurement contracts extend 36-60 months with mandatory ISO 26262 ASIL-B qualification and REACH substance documentation.
- Event Management Companies:Corporate and entertainment event producers renting temporary sound reinforcement for conferences, festivals, and sporting events. Indian and UAE event markets drive demand for flight-case-compatible amplifier racks with rapid deployment rigging.
Consumer electronics manufacturers lead volumes today; vehicle manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Munich anchor the automotive audio electronics corridor driving Class D amplifier demand for electric vehicle cabin systems. Battery-constrained architectures favor efficient switching topologies. Regulatory pressure from Brussels and Tokyo reshapes procurement patterns.
United States
FCC Part 15 emissions limits govern Class D switching noise for consumer and professional audio equipment. Nashville and Los Angeles sustain touring-grade amplifier fleet demand. Texas Instruments leverages integrated manufacturing footprints for automotive-grade die supply.
Germany
EU Ecodesign Directive standby power limits below 0.5 watts force redesign cycles across mass-market product lines. Infineon Technologies anchors premium segments through proprietary GaN-on-Si process technology. Baden-Württemberg tier suppliers qualify ISO 26262 ASIL-B modules for 2027 model-year electric vehicles.
Japan
METI energy-labeling programs drive efficiency benchmarking for consumer audio equipment sold domestically. Yamaha Corporation exemplifies integrated amplifier consolidation for space-constrained residential systems. Kanto manufacturing clusters source GaN devices from Taiwan foundry partners.
China
Shenzhen and Dongguan manufacturing clusters integrate wafer-scale Class D devices with MEMS microphones in single-package solutions. MIIT electromagnetic compatibility standards parallel FCC testing regimes. Domestic foundry scaling reduces die costs for high-frequency switching applications.
India
BIS energy-labeling expansion creates first-mover advantage for Class D suppliers with existing certification. Mumbai and Bengaluru event management companies drive flight-case-compatible amplifier rack procurement. Railway infrastructure projects sustain 70V/100V constant-voltage distribution amplifier demand.
Audio Power Amplifier Market Vendor Landscape
Global majors compete with regional champions across semiconductor process technology and automotive qualification timelines. The vendor base stratifies between integrated device manufacturers with captive fabrication and fabless designers relying on foundry partnerships. Three archetypes dominate: wide-bandgap semiconductor specialists, automotive-grade qualification leaders, and consumer electronics volume suppliers. Capacity expansion and strategic foundry partnerships constitute the dominant competitive moves.
Among semiconductor specialists, Texas Instruments Incorporated and Infineon Technologies AG exemplify integrated manufacturing archetypes, while STMicroelectronics occupies a position spanning foundry partnerships across European and Asian production bases. Analog Devices, Inc. represents the precision signal-chain tier. These anchors illustrate how competitive positioning depends on process technology access and automotive functional-safety certification depth.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| Analog Devices, Inc. |
| STMicroelectronics |
| Broadcom |
| Skyworks Solutions, Inc. |
| Renesas Electronics Corporation |
| NXP Semiconductors |
| Yamaha Corporation |
| Others |
Supply Flow & Price Mechanics
Epitaxial GaN wafer spot prices cascade through amplifier bill-of-materials into three distinct procurement tiers, with automotive-grade die premiums widening as ISO 26262 qualification timelines extend and foundry capacity concentrates in Taiwan and South Korea.
Pricing Analysis
Input-cost pass-through from GaN substrate suppliers to module assemblers shapes contract structures across the industry. Three-tier pricing structure across premium, standard, and economy levels separates automotive ASIL-B qualified units from consumer-grade Class D chips and legacy silicon MOSFET alternatives. Price differentiation rests on certification grade and volume scale, with 100k-unit automotive contracts commanding 40-60% premiums over 10M-unit consumer electronics offtake. Cost compression in consumer tiers is intensifying because Shenzhen ODMs are consolidating die procurement through Foxconn and Luxshare. Event management companies in India and the UAE exhibit highest price sensitivity, while German automotive OEMs prioritize qualification depth over unit economics.
Supply Chain Analysis
Reverse-logistics flows for professional touring amplifiers create secondary market refurbishment channels in Nashville and London, where rental fleet operators extend asset lifecycles through module replacement programs. Geographic supply concentration centers on Taiwan for GaN epitaxy, Germany for automotive module assembly, and China for consumer-grade Class D integration. Raw material dependencies draw from gallium metal refining in China, sapphire substrate supply from Russia and the United States, and copper laminate for PCB fabrication. Single-source vulnerability pervades 6-inch GaN-on-Si wafer supply from East Asian foundries. Distribution runs through tier-1 automotive suppliers for vehicle OEMs, direct OEM relationships for consumer electronics, and specialized pro-audio distributors for live sound applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive's standby power mandate below 0.5 watts compounds demand for Class D architectures, creating structural preference for suppliers with pre-certified module portfolios.
For Market Incumbents: Anchor automotive qualification pipelines through captive GaN supply agreements with Taiwan foundries, insulating design wins from 18-24 month ISO 26262 timeline exposure. Deepen backward integration into GaN-on-Si process development to defend margin position against fabless competitors dependent on single-source epitaxial supply. Prioritize REACH substance documentation automation to accelerate EU market requalification cycles. For New Entrants and Emerging Players: The premium-to-economy price gap in professional live-sound amplification offers white-space entry for modular, flight-case-compatible designs with Ethernet-AVB telemetry. Target India's BIS energy-labeling expansion as the most penetrable regulatory frontier, where existing Class D certification creates first-mover advantage against legacy Class AB incumbents. Pursue tour-grade rental fleet operators with outcome-based availability contracts rather than unit sales. For Investors and Strategic Acquirers: Asymmetric upside sits with wide-bandgap semiconductor specialists bridging GaN process maturity and automotive functional-safety certification. Long-term viability favors integrated device manufacturers with captive fabrication and established OEM qualification relationships over fabless designers exposed to foundry allocation volatility. Monitor GaN substrate spot price movements and automotive platform standardization announcements for early signals of margin compression or consolidation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-Si Process Maturation | Infineon's proprietary technology anchors premium automotive audio segments against silicon MOSFET alternatives. |
| Automotive Functional-Safety Certification | ISO 26262 ASIL-B qualification extends design win timelines but locks out non-automotive-grade competitors. |
| REACH Compliance Automation | Lead-free solder requalification under ECHA dossiers accelerates EU market access for prepared suppliers. |
| Professional Audio Telemetry Integration | Ethernet-AVB enabled units stream real-time thermal data to vehicle gateways, reducing warranty exposure. |
| India BIS Energy-Labeling Expansion | Mandatory efficiency grades for imported audio equipment favor pre-certified Class D suppliers. |
Methodological Framework
Coverage spans Germany, Japan, the United States, China, and India, with primary inputs from each market's automotive electronics clusters and consumer manufacturing bases. Primary interviews with semiconductor process engineers, tier-1 automotive procurement managers, professional audio rental fleet operators, and consumer electronics ODM sourcing leads combined with secondary validation from SEC 10-K filings, MIIT electromagnetic compatibility registrations, BIS certification databases, and ECHA REACH substance dossiers. Bottom-up die shipment estimates and top-down OEM procurement contract values were triangulated to anchor volume and value outputs.
Granularity-level modeling distinguished Class D from Class AB and legacy topologies, with separate treatment of integrated versus discrete amplifier architectures. Segmentation dimensions included technology class, product integration depth, application end-use, and geographic regulatory cluster. CAGRs were derived from fitted growth curves against historical die shipment data and OEM platform adoption timelines. Industry-specific forecast inputs incorporated GaN device qualification status for 2027 model-year electric vehicles and METI energy-labeling efficiency benchmarks.
Caveats apply where GaN substrate supply disruptions, extended ISO 26262 qualification delays, or REACH substance restriction expansions could materially shift the outlook. Forecasts reflect assumptions regarding foundry capacity expansion and automotive platform standardization continuity. Practitioners should monitor GaN epitaxial wafer spot prices, tier-1 automotive design win announcements, and EU Ecodesign Directive standby limit enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Coaxial Attenuators Market
Electronic Components
VPX SBC Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
Digital Isolator Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Primary Charge Roller Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Buffered Encoders and Decoders Market
Electronic Components
Flex-Rigid PCB Market