
 Asia-Pacific USB Retimer Market | 2026-2036
Asia-Pacific USB Retimer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific USB Retimer Market Insights
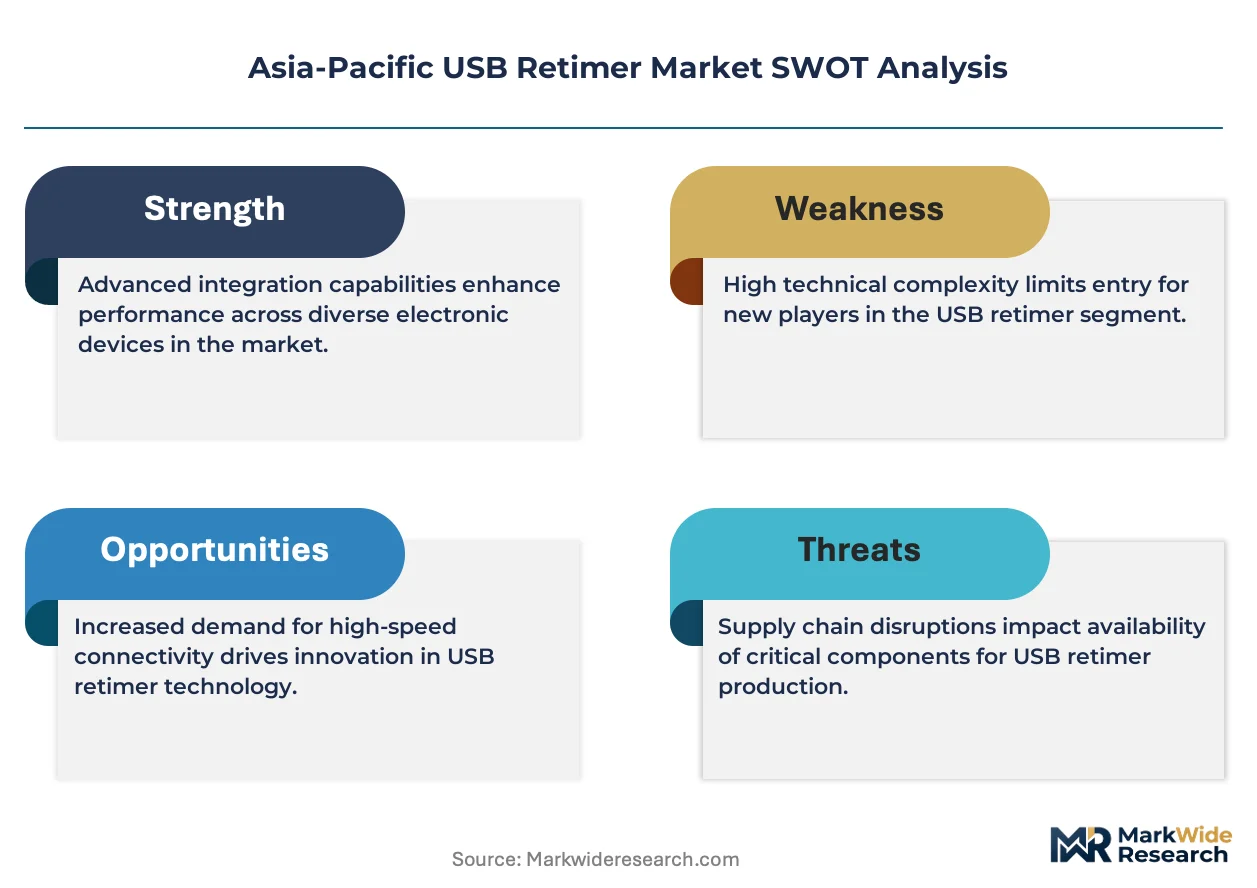
Software-defined signal tuning is broadening what retimer vendors monetize beyond discrete silicon. Parade Technologies leverages its mixed-signal IP portfolio to sustain premium positioning in Thunderbolt-compatible designs. Montage Technology anchors domestic supply security for Chinese server OEMs through captive controller-retimer integration. Renesas Electronics Corporation differentiates with automotive-qualified USB retimer variants that navigate AEC-Q100 compliance requirements.
A USB retimer is an active signal conditioning integrated circuit that recovers embedded clock information and retransmits clean data streams across degraded printed-circuit-board traces or cable assemblies, operating at multi-gigabit speeds up to 80 Gbps in asymmetric USB4 modes. The device compensates for intersymbol interference and jitter accumulation that passive redrivers cannot correct, enabling reliable connectivity in slim-form-factor laptops and dense rack servers. USB4 Retimers command the strongest margin pools as OEMs absorb higher ASPs for 40 Gbps and 80 Gbps certification complexity. Signal Equalization technology leads volume shipments today, though Clock Data Recovery architectures are gaining share in data center backplane applications where deterministic latency matters.
MIIT in China enforces GB standards for electromagnetic compatibility that retimer designs must satisfy before domestic system integration. METI in Japan coordinates JIS standards alignment with USB-IF certification to preserve export competitiveness for local semiconductor vendors. South Korea's MFDS does not directly regulate retimers, but KATS safety markings affect power-delivery subsystems that retimers support in consumer devices. Stakeholders must monitor how USB-IF specification updates and national 5G infrastructure buildouts reshape port-count requirements across notebook and base-station platforms.
Market Dynamics
USB4 asymmetric mode proliferation is compressing design cycles across Asia-Pacific system integrators, forcing retimer vendors to pre-certify silicon against evolving USB-IF compliance matrices before OEM lock-in decisions crystallize.
Growth Catalysts
- MIIT GB Standards:China's electromagnetic compatibility mandates for high-speed interfaces create captive demand for domestically certified retimer variants in server and notebook platforms.
- Data Center Port Densities:Hyperscale operators across South Korea's electronics manufacturing belt are mandating 80 Gbps retimer integration to support Thunderbolt-enabled rack architectures.
- Thunderbolt 5 Pre-Integration:Signal conditioning IP for 120 Gbps asymmetric signaling is converging with USB4 retimer roadmaps, pulling forward R&D commitments from fabless design houses.
Market Restraints
- Advanced Node Wafer Costs:7nm and 5nm retimer tape-outs face foundry allocation constraints, compressing gross margins for mid-tier vendors without volume commitments.
- USB-IF Certification Bottlenecks:Thunderbolt and USB4 interoperability testing queues at certified labs extend time-to-revenue by 4-6 months for new silicon entrants.
- Passive Redriver Substitution:Lower-cost signal conditioning alternatives capture socket share in cost-sensitive peripheral and docking station applications below 20 Gbps.
Strategic Opportunities
- Automotive USB-C Infotainment:AEC-Q100-qualified retimer variants for in-cabin connectivity remain underpenetrated across Japanese and South Korean OEM supply chains.
- METI Semiconductor Ecosystem Funding:Japanese government subsidies for domestic high-speed interface IP development reduce NRE barriers for local retimer startups.
- Edge AI Server Backplanes:Clock Data Recovery architectures are penetrating distributed inference nodes where deterministic latency separates competitive silicon offerings.
Industry Challenges
- SerDes Architecture Talent Scarcity:Mixed-signal design expertise for 80 Gbps PAM4 signaling concentrates among senior engineers at established vendors, constraining new entrant hiring pipelines.
- Legacy USB 3.2 Integration Complexity:Backward compatibility requirements for 5 Gbps and 10 Gbps modes inflate verification cycles and silicon area overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific USB Retimer Market |
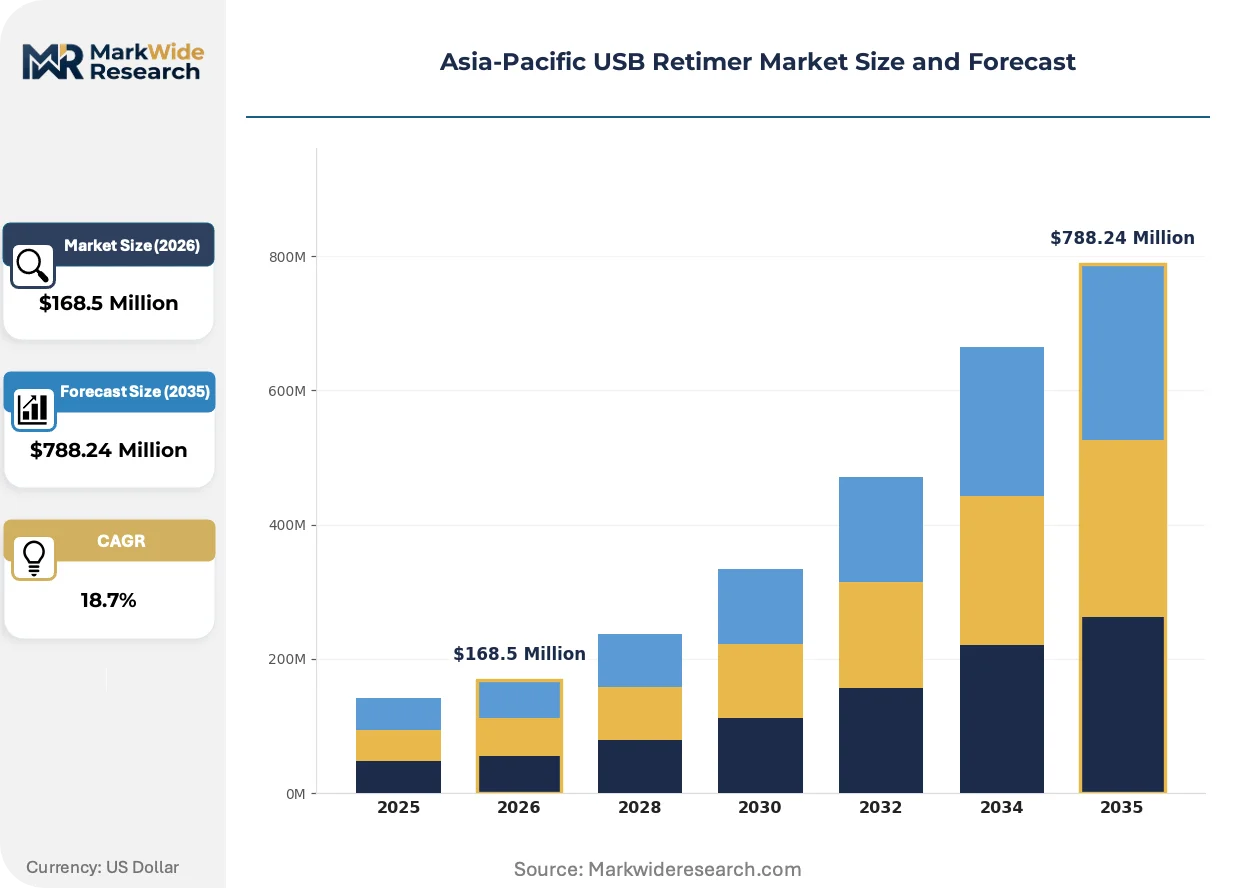
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $788.24 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB 3.1 Retimers, USB 3.2 Retimers, USB4 Retimers, Thunderbolt Retimers Technology: Signal Equalization, Clock Data Recovery, Redriver, Signal Regeneration Application: Consumer Electronics, Data Centers, Networking Equipment, Embedded Systems End User: Original Equipment Manufacturers, System Integrators, Electronics Assemblers, Independent Hardware Vendors |
| Companies Covered | Parade Technologies, Montage Technology, Renesas Electronics Corporation, Phison Electronics, Nuvoton Technology Corporation, Diodes Incorporated, Texas Instruments, NXP Semiconductors, Analogix Semiconductor, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific USB Retimer Market Trends and Innovations
Signal conditioning architectures are bifurcating between power-optimized mobile variants and latency-minimized data center implementations, with software-defined tuning layers emerging as the primary differentiation vector.
Clock Data Recovery retimer designs are converging with PCIe Gen5 and CXL 2.0 signaling requirements, enabling unified silicon platforms across server I/O subsystems. Hyperscale operators in Taiwan and Singapore are qualifying these converged parts for storage fabric deployments. This convergence is compressing vendor R&D spreads by forcing multi-protocol IP reuse rather than discrete USB-only development tracks.
METI in Japan coordinates JIS standards alignment with USB-IF certification protocols to preserve export competitiveness for local semiconductor vendors. The industrial consequence is accelerated domestic design-in activity for Thunderbolt-compatible retimers targeting North American notebook OEMs. Japanese fabless houses are responding by pre-integrating JIS electromagnetic compatibility testing into USB-IF pre-certification workflows.
System integrators across China's Pearl River Delta are consolidating retimer procurement under captive controller-retimer bundled sourcing agreements. Direct vendor relationships are displacing traditional distribution channels for volumes above 500K units annually. This consolidation is most visible in Shenzhen-based ODMs serving global PC brand supply chains.
Asia-Pacific USB Retimer Market Segmentation
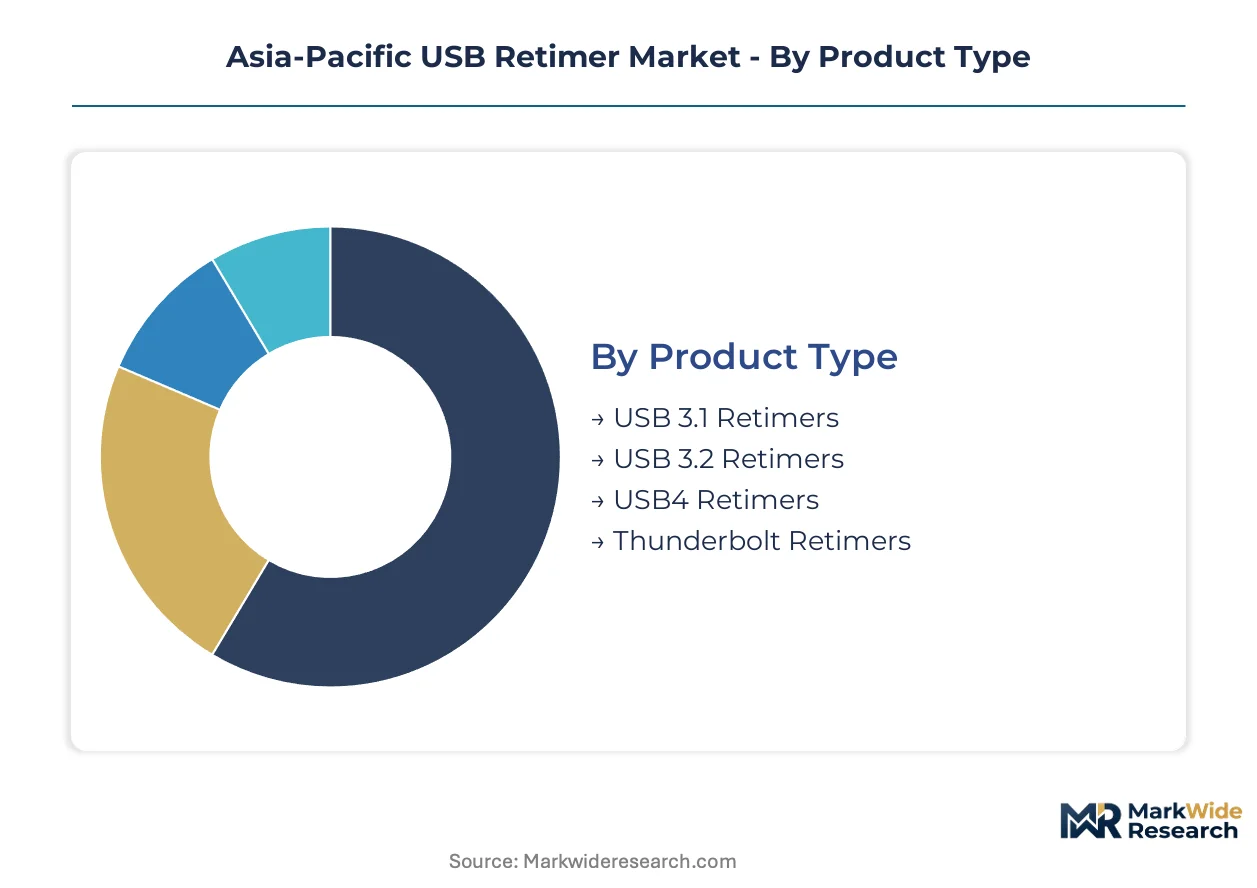
USB retimer segmentation in Asia-Pacific tracks how signal conditioning requirements diverge across mobile, data center, and automotive platforms. Each dimension reveals distinct procurement patterns and certification burdens that reshape vendor competitiveness.
Product Type:
Supply concentration tilts heavily toward next-generation interfaces as South Korean and Chinese OEMs absorb premium silicon for high-speed laptop and server designs.
- USB4 Retimers:These 40-80 Gbps devices incorporate asymmetric mode support and Thunderbolt compatibility, commanding the highest ASPs in the category. Data center operators across Singapore and Taiwan are locking in annual volume commitments for 80 Gbps variants to support dense rack architectures. USB4 certification complexity creates a barrier that favors established vendors with USB-IF pre-certification pipelines.
- Thunderbolt Retimers:Intel-licensed designs enable 120 Gbps asymmetric signaling in next-generation notebook docking stations. Japanese fabless houses are pre-integrating these into JIS-compliant modules for North American PC brand supply chains. The Thunderbolt 5 transition is compressing design cycles across Asia-Pacific system integrators.
- USB 3.2 Retimers:Mid-speed 10-20 Gbps variants serve cost-optimized peripheral and docking applications where passive redrivers compete aggressively.
- USB 3.1 Retimers:Legacy 5-10 Gbps designs retain socket share in industrial embedded systems with extended product lifecycles.
Today's leader: USB4 Retimers. Tomorrow's challenger: Thunderbolt Retimers.
Technology:
Cost tier separation runs deepest here, with Clock Data Recovery architectures commanding 40-60% premiums over Signal Equalization in data center procurement.
- Clock Data Recovery:These architectures extract and regenerate embedded clock information, delivering deterministic latency critical for server backplane applications. Hyperscale operators in Taiwan are qualifying converged USB4/PCIe Gen5 retimers for storage fabric deployments. CDR designs are gaining share fastest in distributed AI inference nodes where jitter tolerance separates competitive offerings.
- Signal Equalization:Power-optimized adaptive equalization dominates smartphone and tablet implementations across China's Pearl River Delta manufacturing belt. MIIT GB electromagnetic compatibility mandates favor domestically certified variants in server and notebook platforms. Volume shipments concentrate in Shenzhen-based ODMs serving global consumer brands.
- Signal Regeneration:Full signal reconstruction for extended cable runs finds niche adoption in industrial automation and medical imaging equipment.
- Redriver:Lower-complexity amplification without clock recovery captures peripheral and docking station sockets below 20 Gbps where BOM cost dominates.
CDR architectures are climbing the fastest in data center procurement, while Signal Equalization retains volume leadership in mobile platforms.
Application:
Customer type dictates margin structure, with data center procurement demanding multi-protocol convergence while consumer electronics rewards single-protocol cost optimization.
- Data Centers:Hyperscale rack architectures mandate 80 Gbps retimer integration for Thunderbolt-enabled storage and compute fabrics. South Korean electronics manufacturing clusters are driving the steepest volume ramps for certified USB4 silicon.
- Consumer Electronics:Slim-form-factor laptops and tablets require power-optimized retimers with minimal PCB footprint. China's MIIT standards for high-speed interface compliance accelerate local design-in activity for domestically certified variants.
- Networking Equipment:Base station and 5G infrastructure buildouts across Japan and South Korea are reshaping port-count requirements for retimer integration.
- Embedded Systems:Industrial and automotive applications demand AEC-Q100-qualified variants with extended temperature ranges, a segment where Japanese vendors differentiate through automotive certification expertise.
Data centers are expanding most quickly; consumer electronics retains the deepest volume base.
End User:
Procurement patterns are shifting as direct vendor relationships displace distribution channels for volumes above 500K units annually.
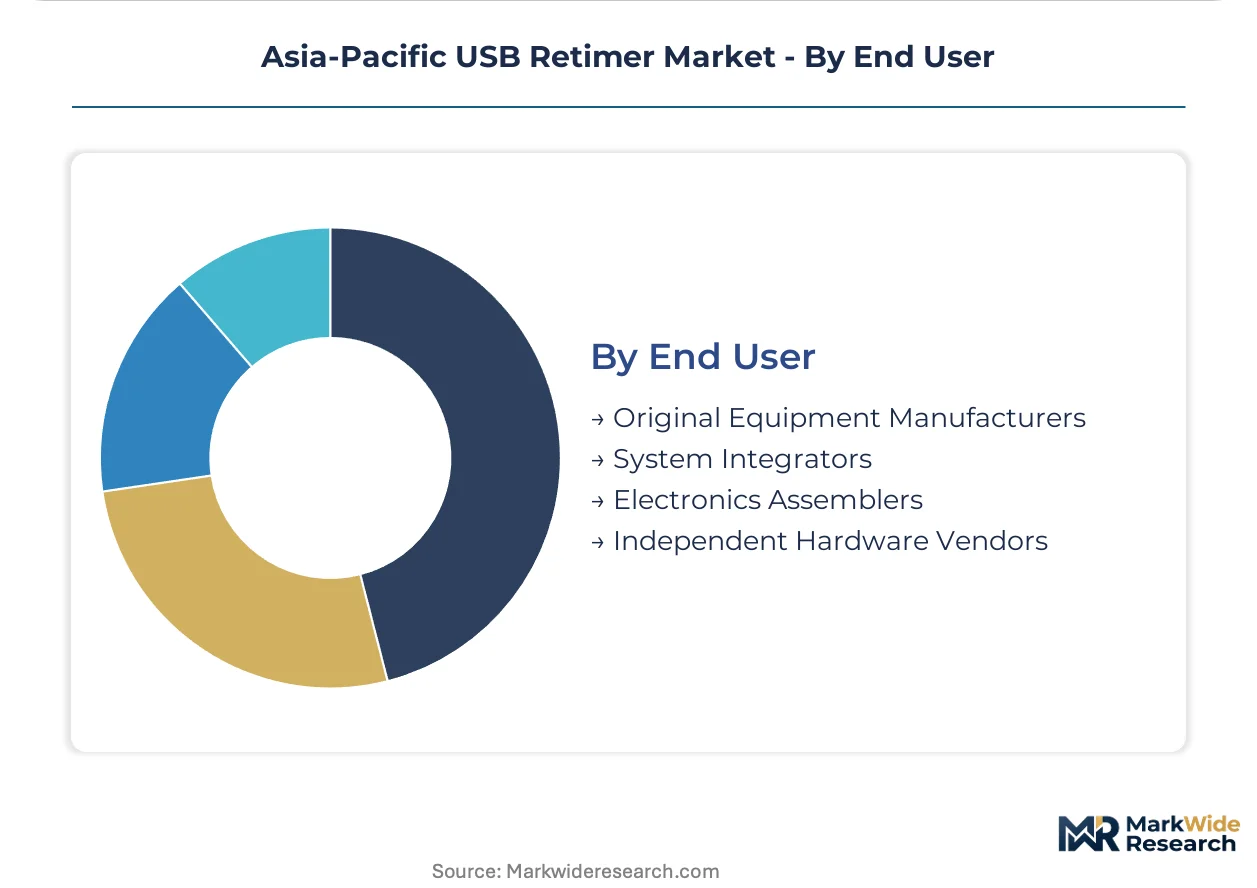
- Original Equipment Manufacturers:Global PC and smartphone brands are consolidating retimer procurement under multi-year supply agreements with pre-certified silicon vendors. Direct engagement accelerates USB-IF compliance matrix alignment.
- System Integrators:South Korean electronics manufacturing belt integrators serve as the primary demand aggregation point for global OEM supply chains, absorbing retimer volumes for notebook and server assembly.
- Electronics Assemblers:Contract manufacturers across China's Pearl River Delta are bundling retimer procurement with captive controller sourcing agreements to secure supply security.
- Independent Hardware Voters:Specialty peripheral and docking station vendors below 100K annual volumes rely on distribution inventory for USB 3.2 and legacy retimer variants.
OEMs dominate procurement value; system integrators control regional volume aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT standards enforcement creates captive demand for domestically certified retimers, while South Korea's electronics manufacturing belt absorbs the steepest volume ramps for 80 Gbps Thunderbolt-enabled silicon. Japan's METI semiconductor ecosystem investments accelerate local design-in activity for North American PC brand supply chains.
China
MIIT GB electromagnetic compatibility mandates for high-speed interfaces force server and notebook OEMs to source domestically certified retimer variants. Shenzhen-based ODMs in the Pearl River Delta manufacturing belt are consolidating procurement under captive controller-retimer bundled agreements to secure supply security. System integrators serving global PC brands drive annual volumes above 500K units through direct vendor relationships.
Japan
METI coordinates JIS standards alignment with USB-IF certification protocols to preserve export competitiveness for local semiconductor vendors. Automotive-qualified USB retimer variants navigate AEC-Q100 compliance requirements for in-cabin connectivity across domestic OEM supply chains. Tokyo and Osaka fabless houses pre-integrate JIS electromagnetic compatibility testing into USB-IF pre-certification workflows.
South Korea
Hyperscale data center operators mandate 80 Gbps retimer integration for Thunderbolt-enabled rack architectures across Seoul Capital Area server farms. MFDS safety markings affect power-delivery subsystems that retimers support in consumer devices. Busan-Ulsan electronics manufacturing clusters serve as the primary demand aggregation point for global OEM notebook and server assembly.
Singapore
Hyperscale operators qualify converged USB4/PCIe Gen5 retimers for storage fabric deployments in distributed AI inference nodes. The city-state's position as a regional semiconductor trading hub facilitates qualification workflows for multi-protocol silicon platforms. Data center port density requirements reshape procurement patterns for deterministic latency architectures.
Taiwan
Foundry allocation constraints for 7nm and 5nm retimer tape-outs compress gross margins for mid-tier vendors without volume commitments. Hsinchu Science Park semiconductor clusters anchor mixed-signal design expertise for 80 Gbps PAM4 signaling. System integrators face compressed design cycles as USB4 asymmetric mode proliferation forces pre-certification against evolving USB-IF compliance matrices.
Asia-Pacific USB Retimer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fabless design houses commanding premium positioning in Thunderbolt-compatible designs while integrated device manufacturers capture scale in consumer electronics. The vendor base organizes around three strategic archetypes: mixed-signal IP specialists, captive controller-retimer integrators, and automotive-qualified variant providers. Consolidation pressures intensify as USB-IF certification bottlenecks extend time-to-revenue timelines, favoring incumbents with established pre-certification pipelines. Dominant competitive moves include strategic partnerships for multi-protocol IP reuse and backward integration into high-speed SerDes architecture development.
Within the mixed-signal IP specialist tier, Parade Technologies and Analogix Semiconductor represent premium-positioned archetypes leveraging Thunderbolt licensing relationships. Montage Technology anchors the captive integration archetype for domestic supply security in Chinese server OEMs. Renesas Electronics Corporation exemplifies the automotive-qualified variant provider, occupying a position shaped by AEC-Q100 compliance expertise for in-cabin connectivity applications.
| Leading Market Players |
|---|
| Parade Technologies |
| Montage Technology |
| Renesas Electronics Corporation |
| Phison Electronics |
| Nuvoton Technology Corporation |
| Diodes Incorporated |
| Texas Instruments |
| NXP Semiconductors |
| Analogix Semiconductor |
| Others |
Pricing and Supply Chain Analysis
Hyperscale procurement consolidation for 80 Gbps Thunderbolt-enabled rack architectures is forcing retimer vendors to absorb advanced-node wafer premiums while defending socket share against passive redriver substitution in cost-sensitive tiers below 20 Gbps.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for 7nm and 5nm retimer tape-outs, though foundry allocation constraints preserve margin compression for mid-tier vendors without volume commitments. Three-tier pricing structure across USB4 premium, USB 3.2 standard, and legacy economy levels separates vendors by certification grade and protocol convergence capability. Cost compression in the USB 3.2 tier is intensifying because passive redrivers capture peripheral socket share. Electronics assemblers across China's Pearl River Delta exhibit the sharpest price sensitivity, while data center operators in Singapore and Taiwan prioritize deterministic latency over unit cost.
Supply Chain Analysis
Advanced-node wafer supply rests on Taiwan Semiconductor Manufacturing Company and Samsung Foundry capacity allocation, with photoresist and specialty substrate inputs drawing from Japanese chemical producers. Raw material dependencies center on silicon wafers, high-purity metals for SerDes architecture, and AEC-Q100-qualified packaging substrates for automotive variants. Single-source vulnerability concentrates in EUV lithography equipment access for sub-7nm retimer designs. Distribution runs through direct vendor relationships displacing traditional channels for volumes above 500K units annually, particularly among Shenzhen-based ODMs serving global PC brand supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hyperscale operator migration toward 80 Gbps asymmetric USB4 retimers with Thunderbolt 5 pre-integration roadmaps.
For Market Incumbents: Extend USB-IF pre-certification pipelines to compress 4-6 month interoperability testing queues before OEM lock-in decisions crystallize. Deepen backward integration into high-speed SerDes architecture development to offset SerDes talent scarcity constraining new entrant hiring. Defend against passive redriver substitution by bundling software-defined signal tuning layers that redrivers cannot replicate. For New Entrants and Emerging Players: Launch via automotive USB-C infotainment qualification pathways targeting AEC-Q100-compliant variants for Japanese and South Korean OEM supply chains, the most penetrable white-space segment. Target edge AI server backplane applications in Singapore and Taiwan where Clock Data Recovery architectures gain share fastest. Pursue METI semiconductor ecosystem funding to reduce NRE barriers for JIS-compliant Thunderbolt module development. For Investors and Strategic Acquirers: Asymmetric upside sits with mixed-signal IP specialists possessing Thunderbolt licensing relationships and established USB-IF pre-certification workflows. Long-term viability over the next decade hinges on multi-protocol convergence capability across USB4, PCIe Gen5, and CXL 2.0 signaling requirements. Monitor USB-IF specification update cadence as the critical inflection signal for port-count requirement shifts across notebook and base-station platforms.| Strategic Initiative | Industry Significance |
|---|---|
| USB-IF Pre-Certification Pipeline Expansion | Compresses 4-6 month testing queues before OEM procurement lock-in crystallizes. |
| Multi-Protocol IP Reuse Investment | Enables unified silicon platforms across USB4, PCIe Gen5, and CXL 2.0 server I/O subsystems. |
| AEC-Q100 Automotive Qualification Pathway | Opens underpenetrated in-cabin connectivity sockets across Japanese and South Korean OEM supply chains. |
| Captive Controller-Retimer Integration | Secures supply security for Chinese server OEMs under MIIT GB electromagnetic compliance mandates. |
| Software-Defined Signal Tuning Layer Development | Broadens monetization beyond discrete silicon through configurable performance optimization. |
Research Methodology
Bottom-up data center and consumer electronics modeling reconciled against top-down foundry capacity and USB-IF certification tracking forms the analytical core of this study. Primary interviews with retimer design engineers, hyperscale procurement officers, ODM supply chain managers, and fabless semiconductor executives combined with secondary validation from MIIT GB standard filings, METI semiconductor ecosystem reports, USB-IF compliance matrices, and foundry utilization disclosures. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map retimer unit demand by product type, technology architecture, application platform, and end-user procurement channel across the projection horizon. Segmentation dimensions modeled include USB protocol generation, signal conditioning technology, deployment environment, and customer scale tier. CAGRs derive from regression analysis against historical foundry allocation patterns and OEM design-in cycle data, with Thunderbolt 5 transition timelines and 5G infrastructure buildout curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry allocation disruption or USB-IF certification bottleneck extension. Forecasts reflect documented assumptions regarding protocol transition timing, OEM consolidation trajectories, and regulatory enforcement intensity across MIIT, METI, and MFDS jurisdictions. Material deviation in Thunderbolt 5 specification finalization or advanced-node wafer pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
USB Wall Charger Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Digital Audio Processor Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Buffered Encoders and Decoders Market
Electronic Components
AC Adapter Market
Electronic Components
Distribution Components Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Impulse Relays Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Motherboard Battery Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
High-Voltage Capacitor Market