
 Frequency Control and Timing Devices Market | 2026-2036
Frequency Control and Timing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Frequency Control and Timing Devices Market Foresight
IEC 60601-1 medical-grade timing qualification is bifurcating the supplier landscape into certified precision manufacturers and generalist component vendors. Nihon Dempa Kogyo leverages its quartz crystal vertical integration to dominate high-frequency oscillator supply for aerospace navigation systems. SiTime Corporation differentiates through MEMS-based programmable architectures that reduce lead times for telecommunications infrastructure customers. Murata Manufacturing anchors Asian supply chains with multi-site ceramic package production for temperature-compensated devices.
Frequency control and timing devices generate stable reference signals from quartz crystal resonators or silicon MEMS structures, maintaining phase coherence within parts-per-billion deviation across operating temperatures from minus forty to plus eighty-five degrees Celsius. These components synchronize data transmission, position navigation, and industrial control loops where jitter tolerance falls below one picosecond. Crystal oscillators retain the largest installed base across defense communications and test equipment, while MEMS oscillators capture the fastest expansion in consumer electronics and automotive telematics due to shock resistance and programmable frequency output. OCXOs command the deepest margin pools in satellite ground stations and calibration laboratories where oven-stabilized thermal environments justify premium positioning.
FCC Part 15 emissions standards in the United States and ETSI EN 300 019 environmental specifications in Europe constrain clock source architectures for network equipment deployed in telecommunications infrastructure. Japan's METI circular economy directives pressure manufacturers to eliminate lead-based solder in ceramic packaging for consumer electronics applications. Stakeholders must weigh quartz supply concentration against MEMS foundry scalability when qualifying second sources for aerospace navigation programs.
Market Dynamics
Quartz crystal supply concentration in China and Japan is forcing component buyers to dual-source with MEMS foundries as geopolitical friction disrupts traditional procurement channels for precision timing components.
Growth Catalysts
- 5G Base Station Deployment:Telecommunications infrastructure expansion across China, South Korea, and Germany consumes high volumes of temperature-compensated oscillators for network synchronization.
- REACH Compliance Deadlines:EU chemical substance restrictions are accelerating substitution of lead-based solder in ceramic packaging, creating upgrade cycles across installed equipment bases.
- Satellite Navigation Programs:China's BeiDou and Europe's Galileo ground station networks require oven-controlled crystal oscillators with parts-per-billion stability specifications.
Market Restraints
- Raw Material Concentration:High-purity synthetic quartz crystal production concentrates in Japanese and Chinese facilities, exposing buyers to single-source risk.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases constrain etching chemistries used in MEMS resonator fabrication, lengthening qualification timelines.
- Technical Performance Gap:MEMS oscillators still trail quartz devices in phase noise performance at frequencies above fifty megahertz, limiting aerospace adoption.
Strategic Opportunities
- Automotive Telematics:Vehicle-to-everything communication modules in electric vehicles present greenfield demand for shock-resistant timing components.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly are drawing quartz oscillator packaging operations to Gujarat and Tamil Nadu.
- IEC 60601-1 Certification:Medical-grade timing qualification creates premium positioning for suppliers serving imaging equipment and patient monitoring systems.
Industry Challenges
- Frequency Synthesis Expertise Shortage:Mixed-signal IC design talent for programmable oscillators concentrates in Taiwan and the US West Coast, constraining European and Japanese vendor roadmaps.
- Dual-Source Qualification Burden:Aerospace navigation programs require identical performance validation across quartz and MEMS architectures, doubling test cycle duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frequency Control and Timing Devices Market |
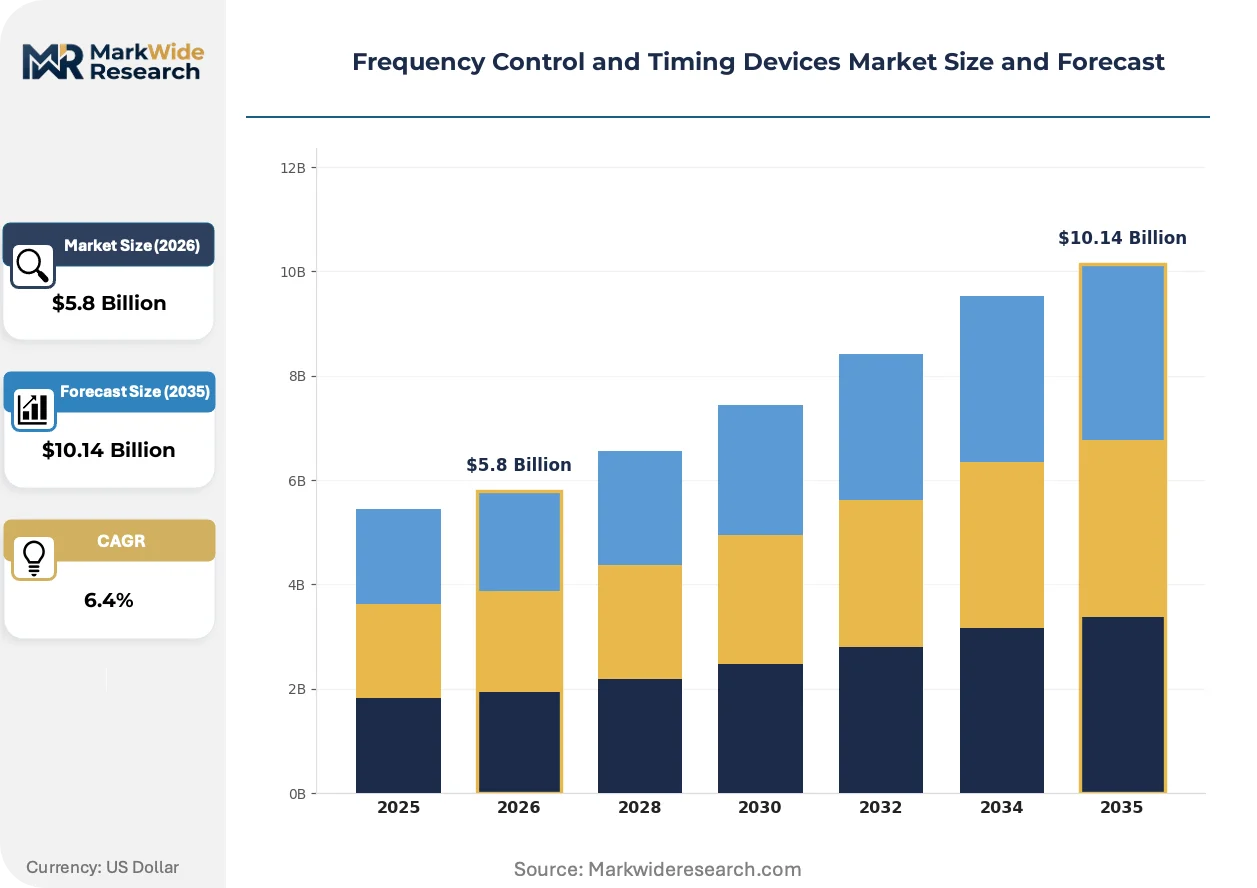
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystal Oscillators, MEMS Oscillators, RC Oscillators, SAW Devices, TCXOs, OCXOs Technology: Quartz, Microelectromechanical Systems, Surface Acoustic Wave, Temperature Compensated, Oven Controlled, Voltage Controlled Application: Telecommunications Infrastructure, Aerospace Navigation, Consumer Electronics, Industrial Automation, Defense Communications, Test & Measurement End User: Original Equipment Manufacturers, Network Service Providers, Aerospace Integrators, Industrial Manufacturers, Defense Contractors, Calibration Laboratories |
| Companies Covered | Nihon Dempa Kogyo, Kyocera Corporation, Seiko Epson Corporation, Rakon Limited, SiTime Corporation, TXC Corporation, Murata Manufacturing, Analog Devices, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frequency Control and Timing Devices Market Shifts & Advancements
Programmable MEMS architectures are compressing oscillator customization cycles from weeks to days, reshaping how telecommunications and automotive procurement teams manage frequency planning.
Silicon MEMS resonator technology is fragmenting the traditional quartz-dominated supply base by enabling field-programmable frequency output without crystal cutting lead times. Base station OEMs in China and South Korea are adopting these devices for software-defined radio platforms. The shift is fragmenting procurement patterns as buyers trade absolute phase noise performance for supply chain flexibility.
EU F-Gas Regulation restrictions on perfluorinated compounds are forcing MEMS foundries to retool etching processes for resonator cavity formation. The industrial consequence is extended qualification timelines for new device families. European automotive telematics suppliers are responding by pre-qualifying alternative chemistries ahead of 2027 phase-down deadlines.
Consolidated procurement by hyperscale cloud operators is compressing vendor negotiation cycles and unbundling traditional distribution markups. Network equipment manufacturers now source timing components through direct foundry relationships rather than authorized distributors. This pattern is most visible in China, where domestic cloud providers specify custom frequency plans for data center synchronization.
Frequency Control and Timing Devices Market Segmentation
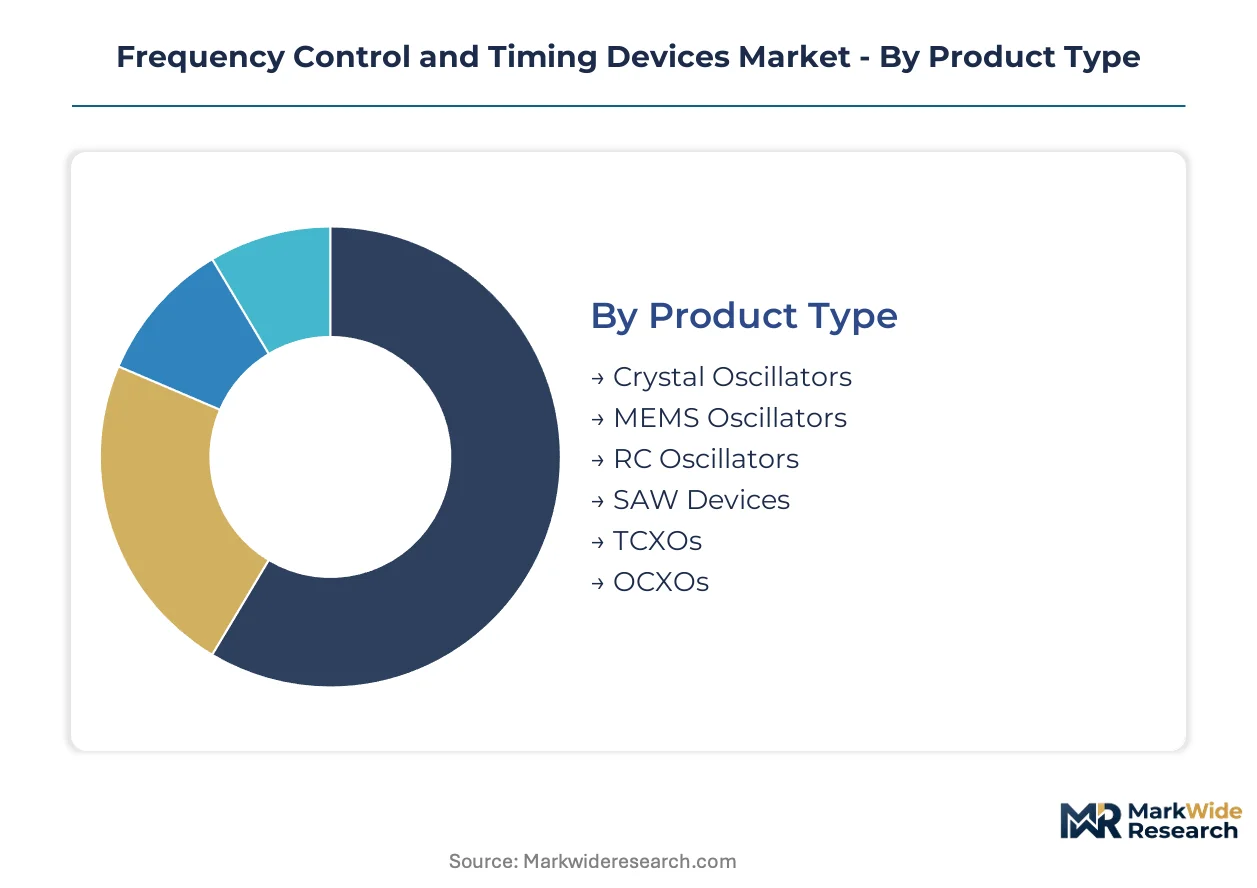
Segmentation in frequency control and timing devices reveals how technical specifications, regulatory compliance burdens, and supply chain configurations fragment procurement strategies across end-use verticals. Buyers in aerospace navigation programs source differently than consumer electronics manufacturers because phase noise tolerance and shock resistance requirements diverge by orders of magnitude.
Product Type:
Domestic absorption patterns vary sharply across product categories, with military-grade devices concentrating in national security supply chains while consumer-facing oscillators flow through export-oriented manufacturing hubs.
- Crystal Oscillators:Piezoelectric quartz resonators generate stable reference frequencies through mechanical vibration modes. Defense communications systems in the United States and test equipment manufacturers in Germany absorb the highest volumes of hermetically sealed ceramic packages. REACH compliance deadlines are forcing solder composition changes that extend qualification cycles.
- MEMS Oscillators:Silicon resonator structures enable programmable frequency output without crystal cutting lead times. Automotive telematics modules in South Korea and software-defined radio platforms in China represent the steepest expansion trajectory for shock-resistant surface-mount devices. F-Gas Regulation constraints on etching chemistries lengthen European foundry qualification timelines.
- RC Oscillators:Resistor-capacitor timing circuits serve cost-sensitive consumer electronics where absolute precision matters less than unit economics.
- SAW Devices:Surface acoustic wave resonators filter RF signals in mobile handsets and base station front-ends.
- TCXOs:Temperature-compensated crystal oscillators integrate thermistor networks to stabilize frequency drift across operating ranges.
- OCXOs:Oven-controlled variants maintain resonators at constant temperature for parts-per-billion stability in satellite ground stations.
Crystal oscillators hold the largest share; momentum sits with MEMS oscillators.
Technology:
Cost tier stratification separates premium oven-controlled architectures from economy-grade voltage-controlled devices, with temperature compensation occupying the mid-market.
- Quartz:Synthetic crystal growth from seed material delivers the lowest phase noise performance for frequencies above fifty megahertz. Aerospace integrators in Japan and defense contractors in the United States specify quartz for navigation systems where signal integrity is non-negotiable. Raw material concentration in Chinese and Japanese facilities exposes buyers to single-source risk.
- Microelectromechanical Systems:Photolithographically patterned silicon resonators integrate with CMOS drive circuits for programmable architectures. Network equipment manufacturers in China favor MEMS for telecommunications infrastructure deployment cycles that demand rapid frequency reconfiguration. Dual-source qualification burdens complicate aerospace adoption.
- Surface Acoustic Wave:Interdigital transducers on piezoelectric substrates enable compact RF filtering.
- Temperature Compensated:Analog or digital compensation circuits correct frequency drift across minus forty to plus eighty-five degrees Celsius.
- Oven Controlled:Thermal regulation maintains resonator temperature within fractions of a degree for calibration-grade stability.
- Voltage Controlled:Varactor diode tuning enables frequency modulation for phase-locked loop applications.
Quartz dominates absolute revenue; MEMS technology is climbing the fastest.
Application:
Volume concentration in consumer electronics contrasts with margin depth in specialized verticals where certification requirements create pricing power.
- Telecommunications Infrastructure:5G base station deployment consumes temperature-compensated and oven-controlled devices for network synchronization. Chinese domestic rollout and South Korean commercial networks absorb the highest volumes. FCC Part 15 emissions standards constrain clock source architectures for equipment deployed in the United States.
- Aerospace Navigation:BeiDou and Galileo ground station networks demand parts-per-billion stability specifications. European and Chinese satellite programs specify OCXOs for signal processing chains. Dual-source qualification across quartz and MEMS architectures doubles test cycle duration.
- Consumer Electronics:Wearables and mobile devices prioritize unit cost and form factor over absolute precision.
- Industrial Automation:Programmable logic controllers and motion control systems require jitter tolerance below one picosecond.
- Defense Communications:Secure transmission systems specify hermetic packaging and radiation-hardened designs.
- Test & Measurement:Calibration laboratories source oven-stabilized references for metrology traceability.
Telecommunications infrastructure holds the largest share; aerospace navigation commands the deepest margins.
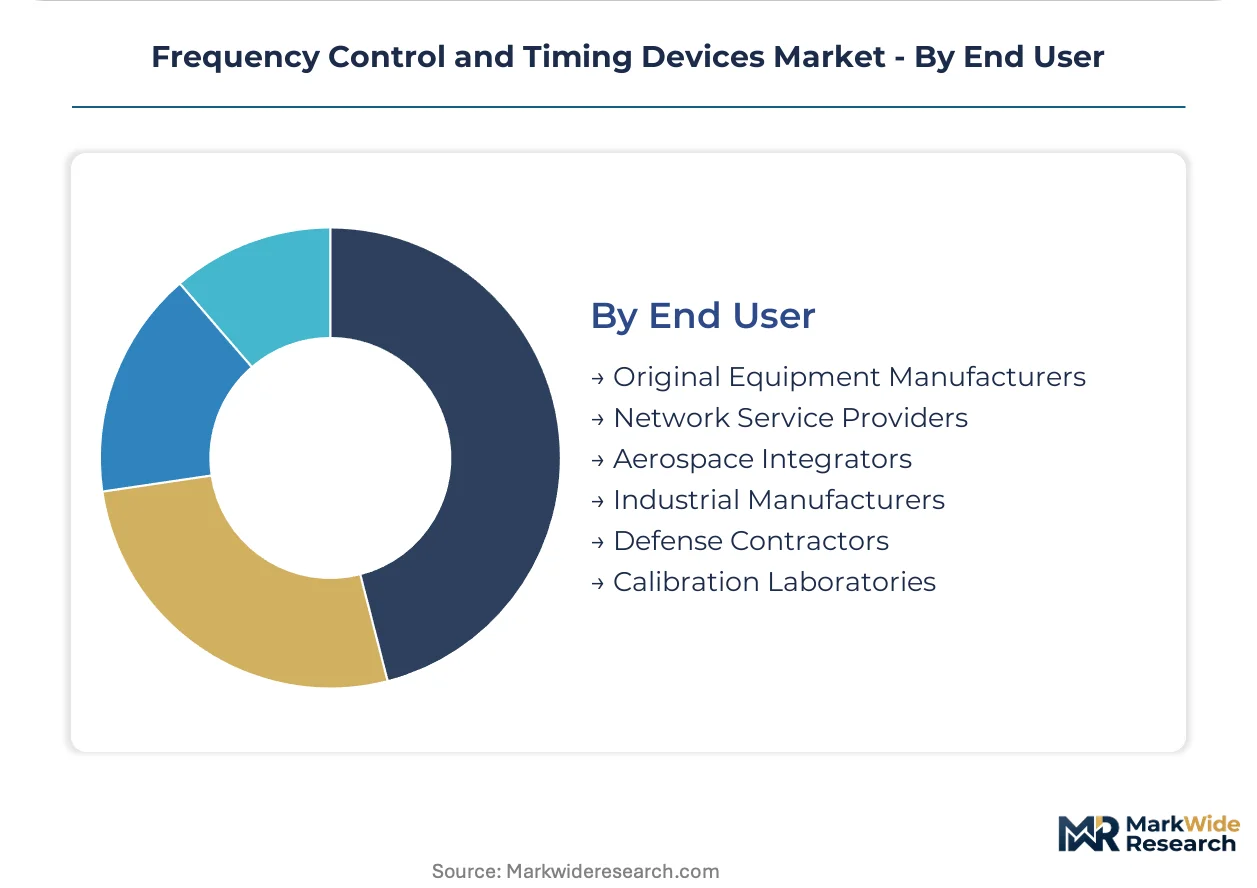
End User:
Customer type determines procurement modality, with defense contractors enforcing long-term supply agreements while industrial manufacturers spot-buy through distribution.
- Original Equipment Manufacturers:Base station and handset producers specify custom frequency plans and volume commitments. Direct foundry relationships are displacing traditional distribution channels for large-scale telecommunications infrastructure procurement.
- Network Service Providers:Hyperscale cloud operators in China consolidate timing component purchases for data center synchronization.
- Aerospace Integrators:Satellite and aircraft system builders enforce IEC and MIL-STD qualification protocols.
- Industrial Manufacturers:Automation equipment builders source through authorized distributors with shorter lead time requirements.
- Defense Contractors:National security supply chains mandate domestic sourcing and ITAR compliance.
- Calibration Laboratories:Metrology institutes procure oven-controlled references as primary frequency standards.
Original equipment manufacturers hold the largest share; network service providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and domestic semiconductor subsidies are redrawing procurement flows for precision timing components. Government-backed 5G infrastructure programs and satellite navigation investments are concentrating demand in specific industrial corridors across East Asia, North America, and Europe.
China
MIIT mandates for 5G base station densification and BeiDou ground station expansion absorb the highest volumes of OCXOs and TCXOs. The country's national environmental regulator enforces dual carbon goals that constrain energy-intensive synthetic quartz crystal growth operations. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces host precision oscillator packaging facilities serving domestic telecommunications equipment builders.
United States
FCC Part 15 emissions standards shape clock source architectures for network equipment deployed in hyperscale data centers and defense communications systems. The EPA oversees chemical handling protocols affecting MEMS foundry operations in Arizona and Texas. Greater Boston and Silicon Valley concentrate fabless timing IC design houses that supply programmable oscillator architectures to base station OEMs.
Japan
METI circular economy directives pressure manufacturers to eliminate lead-based solder in ceramic packaging for consumer electronics and automotive applications. Synthetic quartz crystal production concentrates in Yamanashi and Nagano prefectures, creating single-source exposure for global buyers. Kansai industrial corridors around Osaka anchor hermetic sealing and ceramic package manufacturing for aerospace-grade devices.
Germany
ETSI EN 300 019 environmental specifications constrain clock source designs for telecommunications infrastructure deployed across the European Union. The country's federal environmental agency enforces REACH compliance deadlines that accelerate substitution of restricted substances in oscillator manufacturing. Bavaria's precision engineering clusters in Munich and Nuremberg host test equipment manufacturers sourcing oven-stabilized references for metrology applications.
South Korea
MFDS certification requirements for medical-grade timing components create qualification barriers for foreign suppliers serving diagnostic imaging equipment builders. The Ministry of Trade, Industry and Energy coordinates PLI-style incentives for semiconductor packaging localization. Seoul Capital Area and Busan-Ulsan industrial zones concentrate automotive telematics module production consuming shock-resistant MEMS oscillators for vehicle-to-everything communication.
Frequency Control and Timing Devices Market Competitive Landscape
Player mix skews toward vertically integrated quartz crystal specialists and fabless MEMS programmable oscillator designers. The supplier base separates into three tiers: premium aerospace-grade manufacturers with IEC and MIL-STD qualifications; mid-market telecommunications-focused vendors optimizing for temperature stability; and commodity-grade producers serving consumer electronics cost targets. Dominant competitive moves include backward integration into synthetic quartz material production and strategic partnerships between MEMS foundries and base station OEMs for software-defined radio platforms.
Among Japanese precision component manufacturers, Nihon Dempa Kogyo, Seiko Epson Corporation, and Murata Manufacturing exemplify the vertically integrated archetype controlling resonator material supply through captive synthetic crystal growth operations. These companies occupy positions where hermetic packaging expertise and ceramic substrate manufacturing anchor defense and aerospace qualification pipelines. SiTime Corporation represents the fabless programmable architecture model that compresses oscillator customization cycles for telecommunications infrastructure customers requiring rapid frequency reconfiguration.
| Leading Market Players |
|---|
| Nihon Dempa Kogyo |
| Kyocera Corporation |
| Seiko Epson Corporation |
| Rakon Limited |
| SiTime Corporation |
| TXC Corporation |
| Murata Manufacturing |
| Analog Devices |
| Microchip Technology |
| Others |
Supply & Pricing Matrix
MEMS oscillator substitution for quartz crystal devices simultaneously redistributes manufacturing geography toward Taiwanese foundry clusters and compresses procurement economics through programmable architectures that eliminate crystal cutting lead times. Buyers in Chinese telecommunications infrastructure programs now negotiate against this dual-source backdrop where silicon resonator flexibility constrains premium pricing for traditional piezoelectric suppliers.
Pricing Analysis
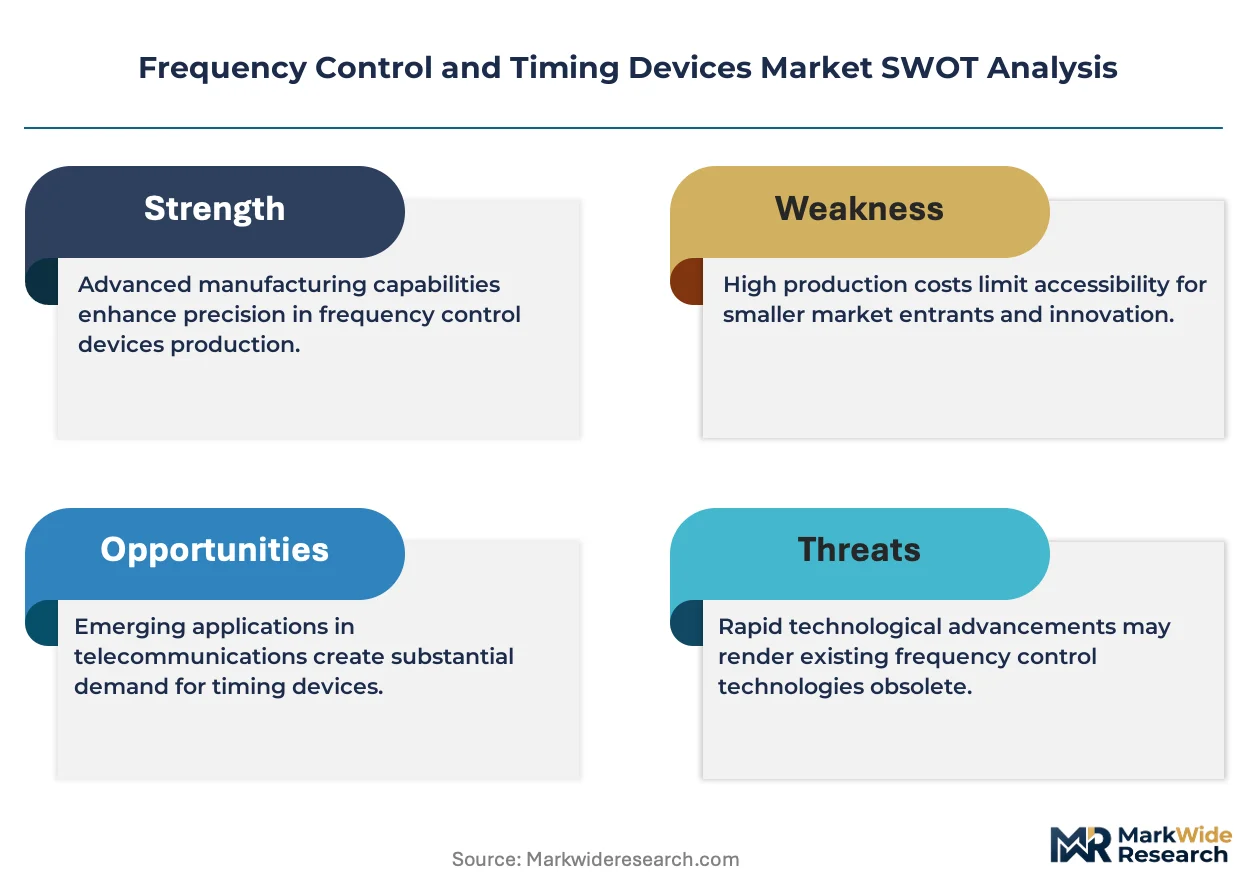
Cost-plus contracts with synthetic quartz crystal indexation dominate aerospace and defense procurement, locking buyers into Japanese and Chinese material pricing that fluctuates with energy-intensive growth furnace operating costs. Three-tier pricing structure across aerospace-grade OCXOs, telecommunications TCXOs, and consumer electronics XOs separates certification-burdened premium tiers from spot-market economy volumes. Cost compression in standard-grade crystal oscillators is intensifying because MEMS foundries in Taiwan and South Korea now field programmable alternatives at 40-60% phase noise parity. Network equipment manufacturers exhibit highest price sensitivity, while satellite ground station operators absorb premiums for parts-per-billion stability guarantees.
Supply Chain Analysis
Strait of Malacca transit underwrites precision oscillator supply security for European and Japanese buyers dependent on Southeast Asian ceramic packaging hubs and Chinese synthetic quartz crystal growth facilities. Synthetic quartz production concentrates in Yamanashi prefecture, Japan and Jiangsu province, China, while MEMS resonator fabrication rests on Taiwanese foundry capacity and Arizona-based etching operations. High-purity quartz crucibles, hermetic ceramic packages, and CMOS drive circuits constitute critical input dependencies. Single-source vulnerability in Japanese synthetic crystal growth exposes aerospace navigation programs to geopolitical disruption. Distribution runs through direct foundry relationships for hyperscale telecommunications OEMs and authorized distributors for industrial spot buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies early-cycle expansion positioning as 5G base station densification and satellite navigation ground station buildouts accelerate penetration of temperature-compensated and oven-controlled timing devices into infrastructure programs previously served by lower-precision alternatives.
For Market Incumbents: Compound defensive positioning through backward integration into captive synthetic quartz crystal growth and accelerated MEMS foundry partnerships that preserve dual-source qualification pipelines. Threat from SiTime Corporation's programmable architectures demands counterinvestment in rapid-customization service capabilities. Priority lever centers on pre-qualifying alternative etching chemistries ahead of EU F-Gas Regulation phase-down deadlines to defend aerospace margin pools. For New Entrants and Emerging Players: IEC 60601-1 certification fast-track unlocks medical imaging equipment procurement channels where incumbent concentration remains lowest and qualification timelines create defensible positioning. White-space targets include Indian PLI scheme packaging facilities in Gujarat and Tamil Nadu, plus automotive telematics modules for South Korean electric vehicle platforms. Go-to-market angle emphasizes shock-resistant MEMS architectures with field-programmable frequency output that compresses OEM frequency planning cycles. For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors vertically integrated quartz specialists with captive material supply and established aerospace qualification pipelines. Long-term viability over the next decade hinges on dual-technology portfolios spanning both quartz precision and MEMS flexibility. Acquisition target archetype comprises mid-scale Japanese or German oscillator manufacturers with IEC 60601-1 and MIL-STD-883 certification assets. Signal to watch is MEMS phase noise performance crossing 50 MHz thresholds that would unlock aerospace navigation substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Quartz Crystal Growth | Captive material supply insulates aerospace margins against Japanese and Chinese production concentration risks. |
| MEMS Foundry Partnership for Programmable Architectures | Taiwanese foundry relationships compress customization cycles for Chinese base station OEM procurement. |
| Alternative Etching Chemistry Pre-qualification | European automotive telematics suppliers secure supply continuity ahead of EU F-Gas Regulation enforcement. |
| IEC 60601-1 Certification Investment | Medical imaging equipment qualification creates premium positioning against generalist component vendors. |
| Indian PLI Scheme Packaging Localization | Gujarat and Tamil Nadu facilities capture government incentives for semiconductor assembly operations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, ETSI environmental specifications, and MIIT infrastructure deployment disclosures through structured interviews with timing component procurement managers at telecommunications OEMs, aerospace navigation system integrators, MEMS foundry operations directors, and quartz crystal growth facility engineers. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Japanese, Chinese, and Taiwanese manufacturing clusters.
Segmentation dimensions modeled span product type hierarchy from OCXOs through MEMS oscillators, technology base distinguishing quartz from silicon resonator architectures, application verticals across telecommunications infrastructure and aerospace navigation, and end-user procurement modalities separating direct foundry relationships from distribution channel purchasing. CAGRs derive from installed base replacement cycles, 5G base station deployment trajectories, and satellite navigation program capital expenditure patterns. Industry-specific forecast inputs include REACH compliance-driven upgrade cycles and F-Gas Regulation etching chemistry substitution timelines.
The analysis sits within stated boundaries; outcomes outside sustained telecommunications infrastructure investment and stable synthetic quartz crystal supply conditions would require recalibration. Forecasts reflect documented assumptions regarding MEMS phase noise performance convergence, regulatory enforcement timelines, and aerospace qualification protocol stability. Practitioners should keep alternative scenarios live as geopolitical friction, etching chemistry availability, and mixed-signal IC design talent concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
USB Charger Market
Electronic Components
Americas MPU Market
Electronic Components
Distribution Components Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Audio Capacitor Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Motherboard Battery Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Digital Isolator Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Global Multilayer Varistors Market
Electronic Components
High-Voltage Capacitor Market