
 Braking Resistors Market | 2026-2036
Braking Resistors Market Size, Share, and Industry Trends Forecast 2026-2036
Braking Resistors Market Outlook
Buyer concentration among railway operators and wind farm developers is restructuring procurement patterns across the braking resistors supply chain. ABB Ltd. leverages its traction power portfolio to anchor long-term service contracts with European rail authorities. Siemens AG sustains R&D intensity in ceramic-composite resistor designs for high-frequency regenerative applications. Schneider Electric competes through integrated drive-resistor packages that reduce installation complexity for industrial OEMs.
Braking resistors are electrical components that dissipate excess kinetic energy as heat during deceleration, typically constructed from nickel-chromium or stainless-steel alloy elements wound on ceramic cores and rated for continuous duty cycles up to 1000°C surface temperature. Their primary purpose is to protect variable-frequency drives, traction inverters, and grid-tie converters from overvoltage damage during rapid load changes. Wirewound resistors dominate heavy-industry applications where thermal mass and durability outweigh cost sensitivity, while ceramic segments capture share in electric vehicle inverters where space constraints and thermal cycling resistance command premium positioning. The rail transit application category generates concentrated margin pools due to extended qualification periods and incumbent supplier stickiness, whereas renewable energy installations are fragmenting across regional turbine OEMs seeking localized resistor sourcing.
The EU F-Gas Regulation and REACH compliance frameworks constrain material choices for resistor housings and thermal interface compounds sold into European rail and wind markets. China's NMPA-aligned rail equipment certification and India's CEA grid-code requirements for renewable interconnection are creating parallel compliance pathways that favor suppliers with multi-jurisdiction testing capabilities. Stakeholders must monitor how evolving traction energy-recovery efficiency mandates in major economies reshape the trade-off between resistor-based dissipation and regenerative storage systems.
Market Dynamics
Railway electrification mandates and regenerative braking retrofits are compressing supplier qualification timelines while fragmenting procurement across Asia-Pacific operators. China's GB standards revision and India's CEA grid-code updates are forcing parallel certification investments that favor multi-jurisdiction testing capabilities.
Growth Catalysts
- Urban metro expansion:India's freight corridor electrification and urban transit buildouts are generating concentrated demand for wirewound resistor systems rated for continuous duty cycles.
- EU F-Gas Regulation:REACH compliance requirements for thermal interface compounds are accelerating material substitution toward ceramic-composite housings in European rail applications.
- Regenerative braking retrofit:Legacy rolling stock modernization across Asia-Pacific operators is creating aftermarket replacement cycles for nickel-chromium alloy resistor elements.
Market Restraints
- Nickel price volatility:Input cost swings for nickel-chromium alloys are compressing margin buffers for wirewound resistor manufacturers serving heavy-industry OEMs.
- Supplier concentration:Ceramic core substrate production clusters in East Asia are creating single-source vulnerability for high-temperature resistor assemblies.
- Supercapacitor substitution:Traction energy-recovery storage systems are displacing resistor-based dissipation in premium rail electrification projects.
Strategic Opportunities
- Wind farm localization:India's renewable interconnection mandates under CEA grid-code are creating openings for domestic resistor sourcing partnerships with regional turbine OEMs.
- Integrated drive packages:Convergence of variable-frequency drives and braking resistors into single-source supply agreements is reducing installation complexity for industrial automation buyers.
- PLI scheme alignment:India's production-linked incentive framework for electrical equipment is attracting component localization investments from multinational resistor suppliers.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel GB standards, REACH, and CEA compliance pathways are extending product qualification periods by 18-24 months for rail equipment suppliers.
- Thermal cycling durability testing:Ceramic-composite resistor validation for electric vehicle inverters requires accelerated life-cycle protocols that strain R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Braking Resistors Market |
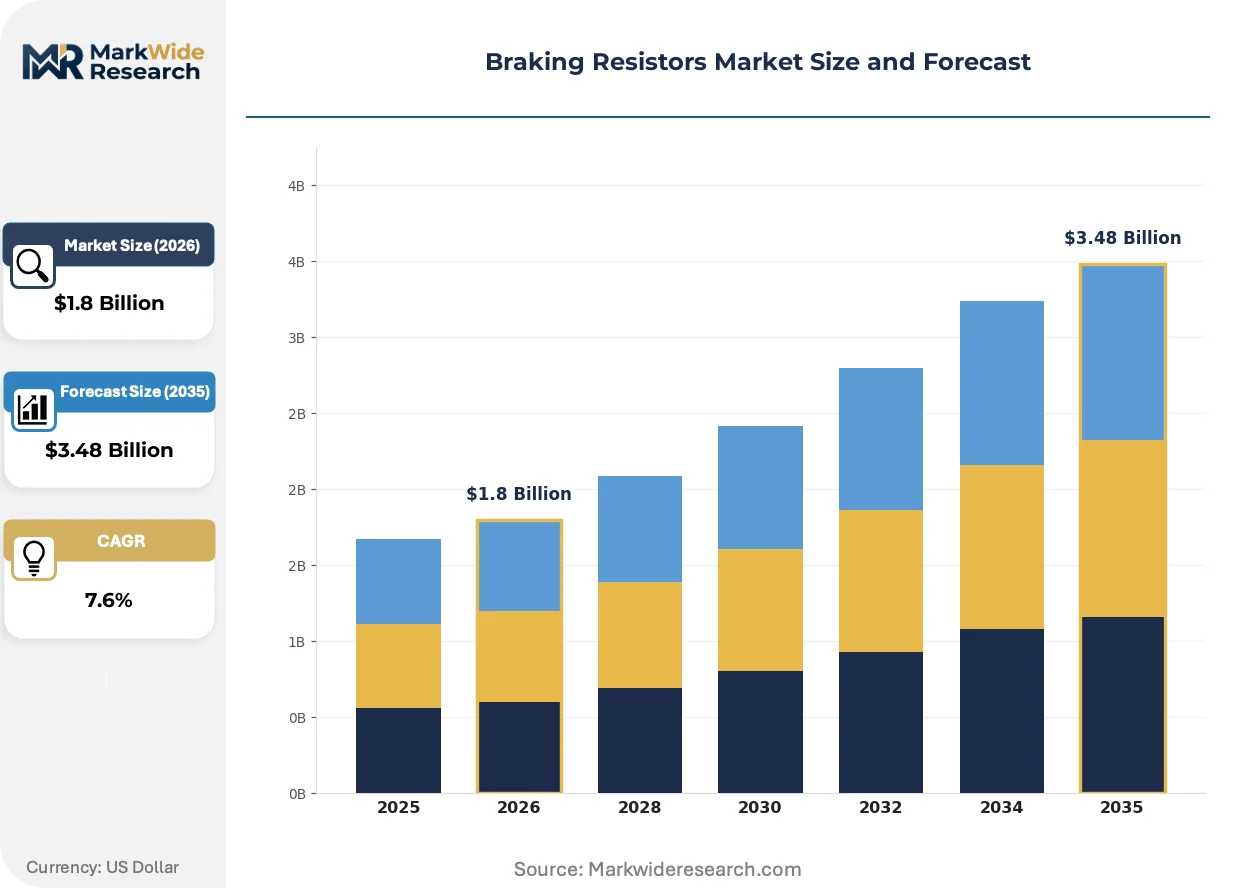
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wirewound, Ceramic, Non-inductive, Reactive Application: Electric Vehicles, Renewable Energy, Industrial Drives, Rail Transit End User: Automotive OEMs, Energy Providers, Manufacturing, Transport Logistics Installation: Integrated, Modular, Standalone, Custom |
| Companies Covered | ABB Ltd., Siemens AG, Schneider Electric, Vishay Intertechnology, Yaskawa Electric Corporation, Sandvik AB, Eaton Corporation, Toshiba International Corporation, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Braking Resistors Market Strategic Shifts
Material science advances and procurement model compression are restructuring competitive positioning across braking resistor segments. Suppliers are racing to anchor long-term service contracts before qualification windows close on electrified rail projects.
Ceramic-composite resistor designs are electrifying traction power applications through enhanced thermal cycling resistance and reduced footprint profiles. Railway operators in Germany and France are adopting these elements for high-frequency regenerative braking systems. The technology is electrifying margin structures by enabling premium positioning in space-constrained electric vehicle inverters.
China's updated GB standards for rail equipment safety are tightening product certification requirements for energy recovery components. Manufacturers must now submit thermal performance data under standardized duty cycles before market entry. European suppliers with existing REACH-compliant material portfolios are accelerating documentation transfers to capture retrofit demand.
Service contract unbundling is fragmenting traditional equipment-procurement relationships in the rail transit segment. European rail authorities are separating resistor supply from installation and long-term maintenance obligations. This pattern is most visible in Germany's regional operator consortiums, where multi-vendor sourcing is compressing incumbent supplier stickiness.
Braking Resistors Market Segmentation
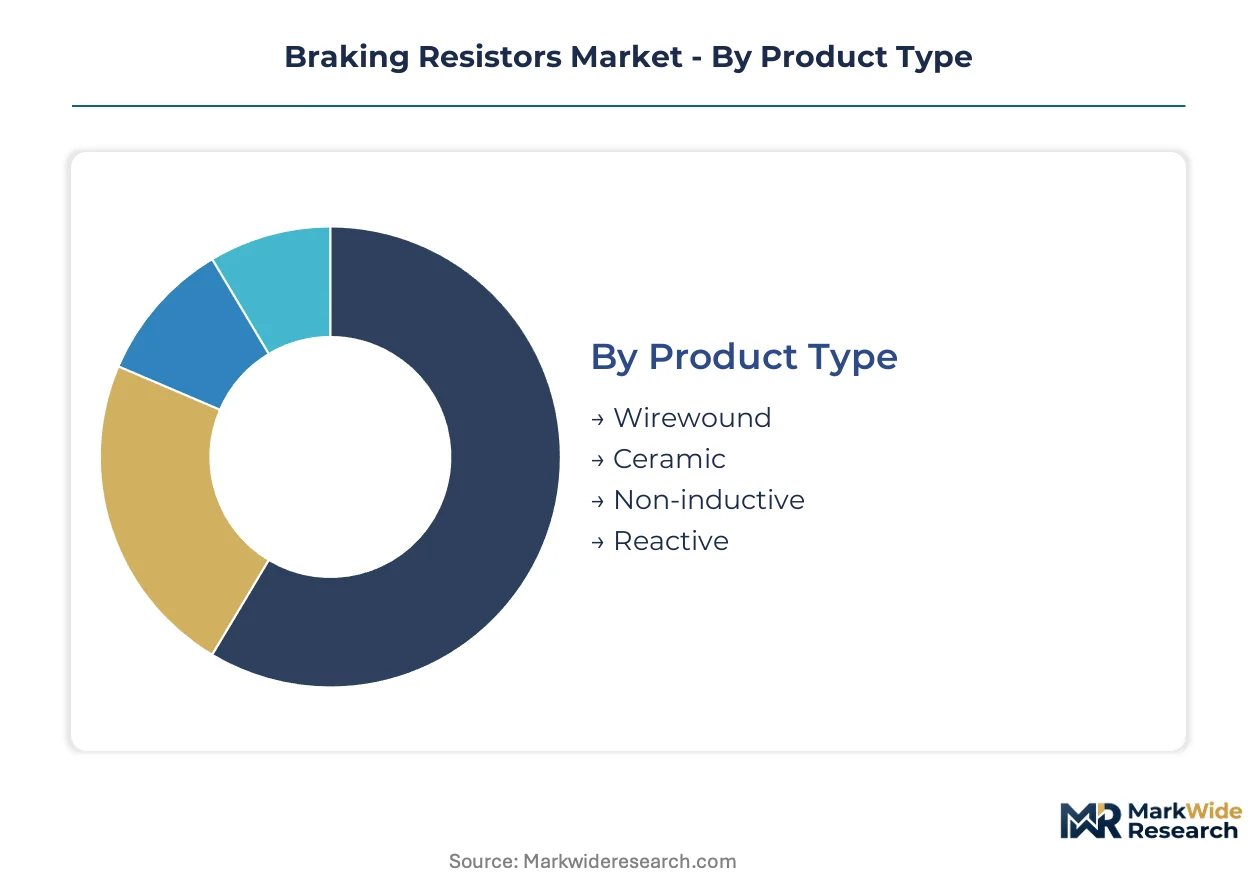
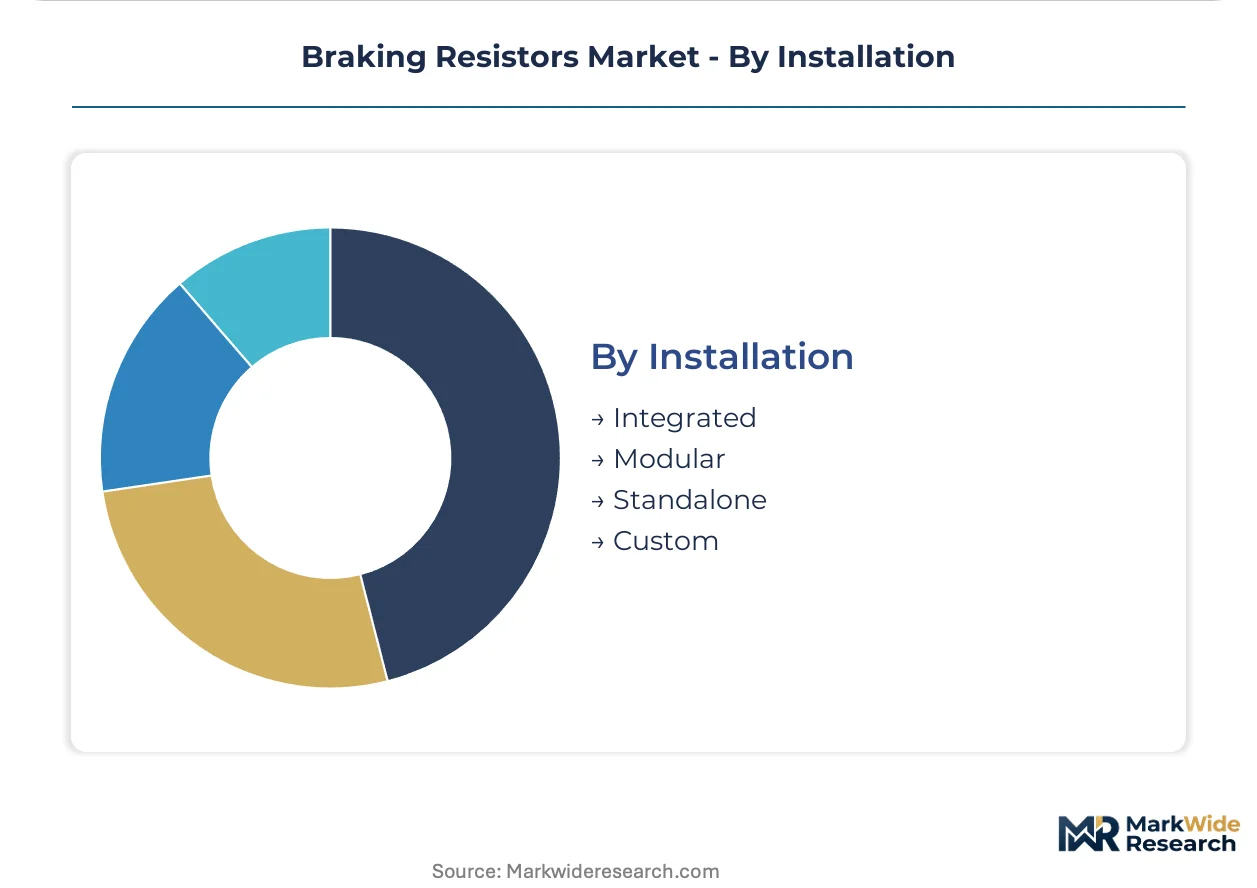
Braking resistor procurement patterns diverge sharply across product architectures and installation configurations. Buyer priorities shift from thermal durability in heavy-industry settings to footprint optimization in electric vehicle powertrains.
Product Type:
Material composition dictates duty-cycle tolerance and dominates total cost of ownership calculations for specifiers.
- Wirewound:Nickel-chromium or stainless-steel alloy elements wound on ceramic cores deliver thermal mass for continuous 1000°C surface operation. Demand concentrates in India's freight corridor electrification and urban metro buildouts where extended duty cycles override upfront cost sensitivity.
- Ceramic:Composite substrates with enhanced thermal cycling resistance enable reduced footprint profiles. Railway operators in Germany and France specify these for high-frequency regenerative braking systems; electric vehicle inverters command premium positioning for space-constrained applications.
- Non-inductive:Specialized winding geometries minimize parasitic inductance for high-frequency inverter applications.
- Reactive:Inductive-capacitive designs address specific harmonic filtering requirements in grid-tie converter installations.
Volume sits with Wirewound; growth tilts toward Ceramic.
Application:
End-use thermal profiles and duty-cycle intensity reshape supplier qualification requirements.
- Rail Transit:Extended qualification periods and incumbent supplier stickiness generate concentrated margin pools. China's GB standards revision and India's CEA grid-code updates force parallel certification investments favoring multi-jurisdiction testing capabilities.
- Electric Vehicles:Space constraints and thermal cycling resistance command premium positioning. Ceramic-composite designs are electrifying margin structures in inverter applications.
- Renewable Energy:Regional turbine OEMs fragment procurement across localized resistor sourcing partnerships.
- Industrial Drives:Variable-frequency drive integration demands drive-resistor packages reducing installation complexity.
Revenue concentrates in Rail Transit; expansion accelerates most quickly in Electric Vehicles.
End User:
Procurement centralization versus fragmentation determines contract structure and pricing leverage.
- Transport Logistics:Railway operator concentration restructures procurement patterns toward long-term service contracts.
- Automotive OEMs:Tier-1 inverter suppliers drive specification authority for resistor integration.
- Energy Providers:Wind farm developers fragment sourcing across regional turbine OEMs.
- Manufacturing:Industrial automation buyers favor integrated drive-resistor packages from single-source suppliers.
Contract value aggregates with Transport Logistics; specification influence shifts toward Automotive OEMs.
Installation:
System integration depth determines aftermarket service attach rates and supplier margin capture.
- Integrated:Factory-embedded resistor-drive combinations reduce field installation labor.
- Modular:Swappable cartridge designs accelerate maintenance intervals in rail applications.
- Standalone:Separate resistor enclosures persist in retrofit installations.
- Custom:Application-engineered thermal management solutions address extreme duty-cycle requirements.
Deployment frequency favors Modular; engineering intensity peaks with Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel-chromium alloy production clusters in China and stainless-steel wire drawing facilities in Germany anchor the braking resistors supply chain geography. Railway electrification programs and renewable interconnection mandates are redistributing demand across manufacturing hubs and end-use markets.
China
Urban metro expansion in Chengdu and Xi'an drives wirewound resistor procurement for continuous-duty traction systems. GB standards revision for rail equipment safety tightens thermal performance documentation requirements. Zhejiang and Jiangsu provinces concentrate ceramic core substrate manufacturing, with suppliers scaling capacity for high-frequency regenerative braking applications.
Germany
Regional rail operator consortiums in Bavaria and North Rhine-Westphalia unbundle service contracts from equipment supply. EU F-Gas Regulation and REACH compliance accelerate material substitution toward ceramic-composite housings. Stuttgart and Munich industrial clusters host traction power specialists anchoring long-term maintenance agreements with Deutsche Bahn affiliates.
India
Freight corridor electrification and Delhi-Mumbai-Ahmedabad metro buildouts generate concentrated demand for heavy-duty resistor systems. CEA grid-code requirements for renewable interconnection create domestic sourcing mandates for wind farm resistor partnerships. Gujarat and Maharashtra production zones attract PLI scheme investments from multinational component suppliers.
United States
Industrial automation buyers in Michigan and Ohio favor integrated drive-resistor packages reducing field installation complexity. EPA and OSHA thermal safety protocols constrain resistor enclosure designs for heavy-manufacturing environments. Texas and California wind farm developers fragment procurement across regional turbine OEMs seeking localized supply chains.
Japan
Electric vehicle inverter manufacturers in Aichi and Kanagawa prefectures command premium ceramic-composite resistor positioning for space-constrained powertrains. METI energy efficiency mandates reshape trade-offs between resistor dissipation and regenerative storage in rail applications. Osaka-based industrial electronics clusters sustain demand for high-frequency non-inductive winding geometries.
Braking Resistors Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue integrated drive-resistor packaging and ceramic-composite specialization. The vendor base stratifies across multinational electrical equipment conglomerates, mid-scale wirewound specialists, and regional substrate fabricators. Two archetypes dominate: traction power incumbents leveraging service contract anchoring, and materials-science players capturing premium thermal cycling applications. Competitive moves concentrate on backward integration into ceramic core production and geographic expansion through PLI-aligned manufacturing.
Among diversified electrical equipment conglomerates, ABB Ltd. and Siemens AG exemplify the traction power incumbent archetype, anchoring long-term relationships with European rail authorities through bundled service offerings. Schneider Electric occupies a position within the integrated solutions tier, representing the drive-resistor convergence strategy that reduces procurement complexity for industrial OEMs. These three entities illustrate how scale and service infrastructure create defensive positioning against specialized ceramic-composite entrants.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Schneider Electric |
| Vishay Intertechnology |
| Yaskawa Electric Corporation |
| Sandvik AB |
| Eaton Corporation |
| Toshiba International Corporation |
| Rockwell Automation |
| Others |
Value Chain & Pricing Dynamics
Railway operator unbundling of service contracts from equipment supply in Germany and France is forcing resistor manufacturers to absorb aftermarket margin compression while maintaining thermal performance documentation under EU REACH compliance. This procurement shift is reshaping how suppliers structure long-term agreements and recover certification costs.
Pricing Analysis
Warranty and maintenance bundling now separates premium-tier suppliers from economy competitors in rail transit procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under China's GB standards and India's CEA grid-code. Price differentiation stems from ceramic-composite thermal cycling validation versus basic wirewound durability. Cost compression in standard-grade wirewound assemblies is intensifying because nickel-chromium alloy volatility erodes margin buffers. Industrial automation buyers exhibit lowest price sensitivity due to integrated drive-resistor convenience premiums.
Supply Chain Analysis
Nickel-chromium alloy feedstock rests on Chinese smelting capacity and German stainless-steel wire drawing facilities. Ceramic core substrate production draws from Zhejiang and Jiangsu province clusters, while India attracts PLI scheme investments for domestic component sourcing. Single-source vulnerability concentrates in high-temperature ceramic substrate manufacturing. Distribution runs through traction power specialists anchoring long-term maintenance agreements with European rail authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic core substrate production clusters in East Asia create a supply-constrained environment where qualified capacity shortages prop pricing for validated thermal cycling components.
For Market Incumbents: Deploy backward integration into ceramic core manufacturing to capture margin pools from substrate supply bottlenecks. Anchor long-term service contracts with Deutsche Bahn affiliates and Indian metro operators before qualification windows close on electrified rail projects. Counter supercapacitor substitution threats by emphasizing resistor reliability in extreme duty-cycle environments. For New Entrants and Emerging Players: The premium-economy price gap in ceramic-composite resistors for electric vehicle inverters offers white-space entry. Target India's domestic wind farm resistor partnerships under CEA grid-code localization mandates. Pursue modular cartridge designs for swappable rail maintenance applications as the most penetrable aftermarket segment. Lead with application-engineered thermal management solutions for extreme duty-cycle requirements. For Investors and Strategic Acquirers: Re-rating potential sits with ceramic-composite specialists given METI energy efficiency mandates reshaping electric vehicle powertrain specifications. Long-term viability favors materials-science players with validated thermal cycling protocols over commodity wirewound assemblers. Monitor traction energy-recovery storage deployment rates as the inflection signal for resistor displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Core Production | Captures margin from Zhejiang substrate supply bottlenecks while securing qualification timelines. |
| Long-term Service Contract Anchoring | Locks recurring revenue with Deutsche Bahn affiliates amid procurement unbundling trends. |
| CEA Grid-code Certification Investment | Opens India's domestic wind farm sourcing partnerships under renewable interconnection mandates. |
| Ceramic-composite R&D Intensification | Addresses METI efficiency mandates for space-constrained electric vehicle inverter applications. |
| PLI-aligned Manufacturing Localization | Positions multinational suppliers for India's production-linked incentive scheme in electrical equipment. |
Study Parameters
Trade association filings, customs documentation, and equipment certification databases formed the secondary backbone for this analysis. Primary interviews with traction power procurement officers, ceramic substrate plant managers, rail operator maintenance directors, and renewable energy EPC contractors validated demand assumptions. Bottom-up unit economics triangulated against top-down market sizing from regulatory filing disclosures.
Historical trendline analysis of electrified rail fleet deployments and wind turbine installation rates established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product architecture, application thermal profile, end-user procurement centralization, and installation integration depth. CAGRs derived from regression analysis of capital expenditure cycles in railway electrification and renewable interconnection programs.
Inputs from Chinese GB standards documentation and Indian CEA grid-code filings were available through the study window; gaps in real-time nickel alloy pricing transparency introduce uncertainty bands around wirewound resistor margin forecasts. Forecasts reflect assumptions regarding traction energy-recovery efficiency mandate trajectories and supercapacitor cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Speaker Membranes Market
Electronic Components
Switch Diode Market
Electronic Components
Screw Washer Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
Motherboard Market
Electronic Components
Breadboards Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Structural Electronics Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Asia-Pacific USB Retimer Market