

High Precision Mechanical Machine Components Market Size, Share, and Industry Trends Forecast 2026-2036
High Precision Mechanical Machine Components Market Insights
Aerospace and semiconductor equipment demand is hardening as the dominant end-use mix shift. Bosch Rexroth leverages its hydraulics-to-precision motion portfolio to anchor German automotive and industrial automation demand. SKF competes through bearing specialization across wind turbine and electric vehicle powertrain applications. Danaher sustains R&D intensity in metrology and motion control systems that serve lithography equipment makers.
High precision mechanical machine components are engineered structures manufactured to tolerances typically below five micrometers, using processes such as CNC machining, wire EDM, and precision grinding to achieve dimensional stability under load, temperature variation, and rotational stress. These components transmit motion, bear loads, or maintain alignment in equipment where failure margins approach zero. Bearings and gears command the largest value pools due to replacement frequency and friction-critical performance requirements, while wire EDM and laser cutting technology segments attract fastest-growing demand from medical device and semiconductor fabrication tool builders. Springs and couplings occupy narrower but higher-margin niches where custom metallurgy and fatigue resistance justify premium pricing.
ISO 9001 quality management and ISO 14001 environmental standards govern baseline certification for component suppliers accessing European and North American OEM supply chains, while China's GB/T precision standards and SAMR market access rules shape competitive entry for foreign manufacturers. The EU Machinery Directive and CE marking requirements enforce safety-integrated design protocols that ripple backward into component specification sheets. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking will recast material sourcing and energy-intensive finishing processes.
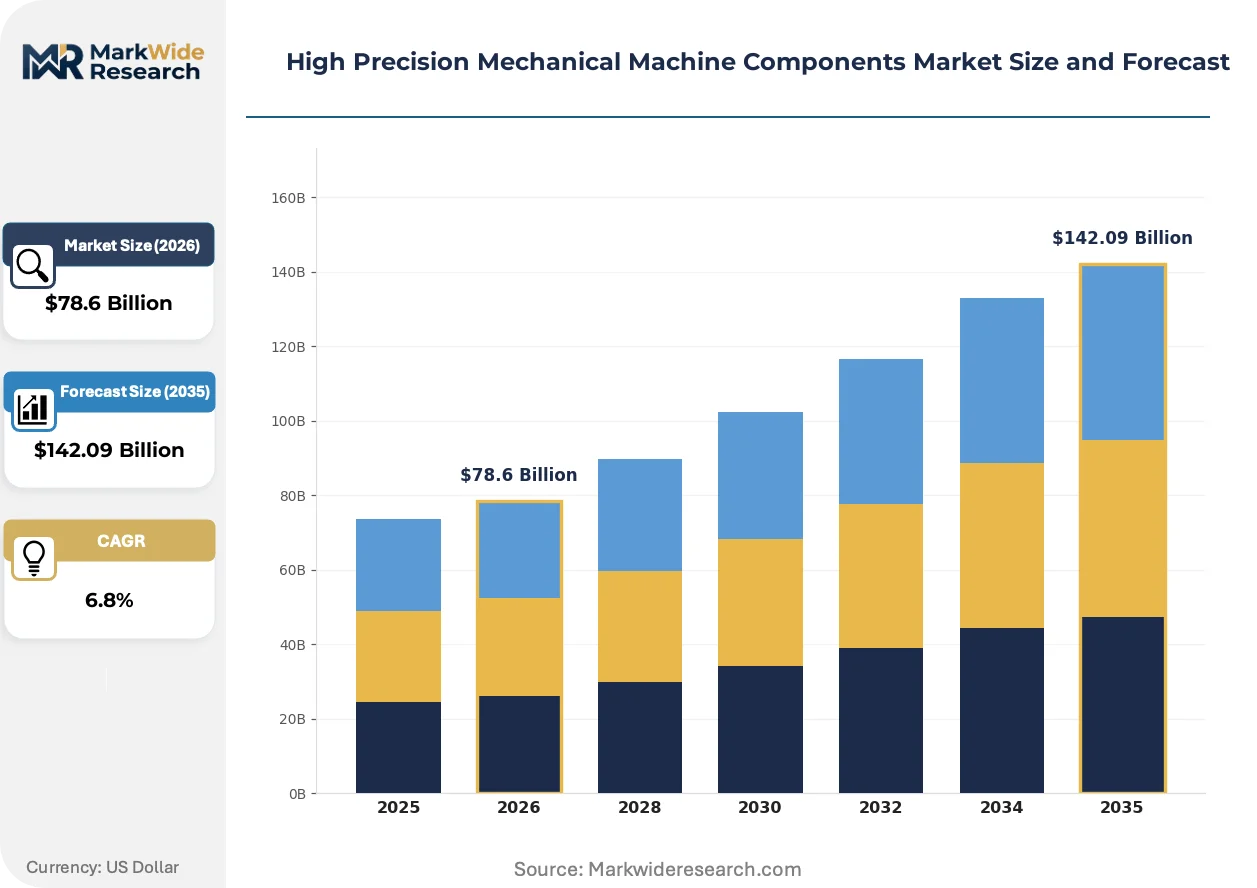
Market Dynamics
Sub-micron tolerance requirements from semiconductor lithography equipment builders are compressing supplier qualification timelines and forcing capital retooling across precision machining networks.
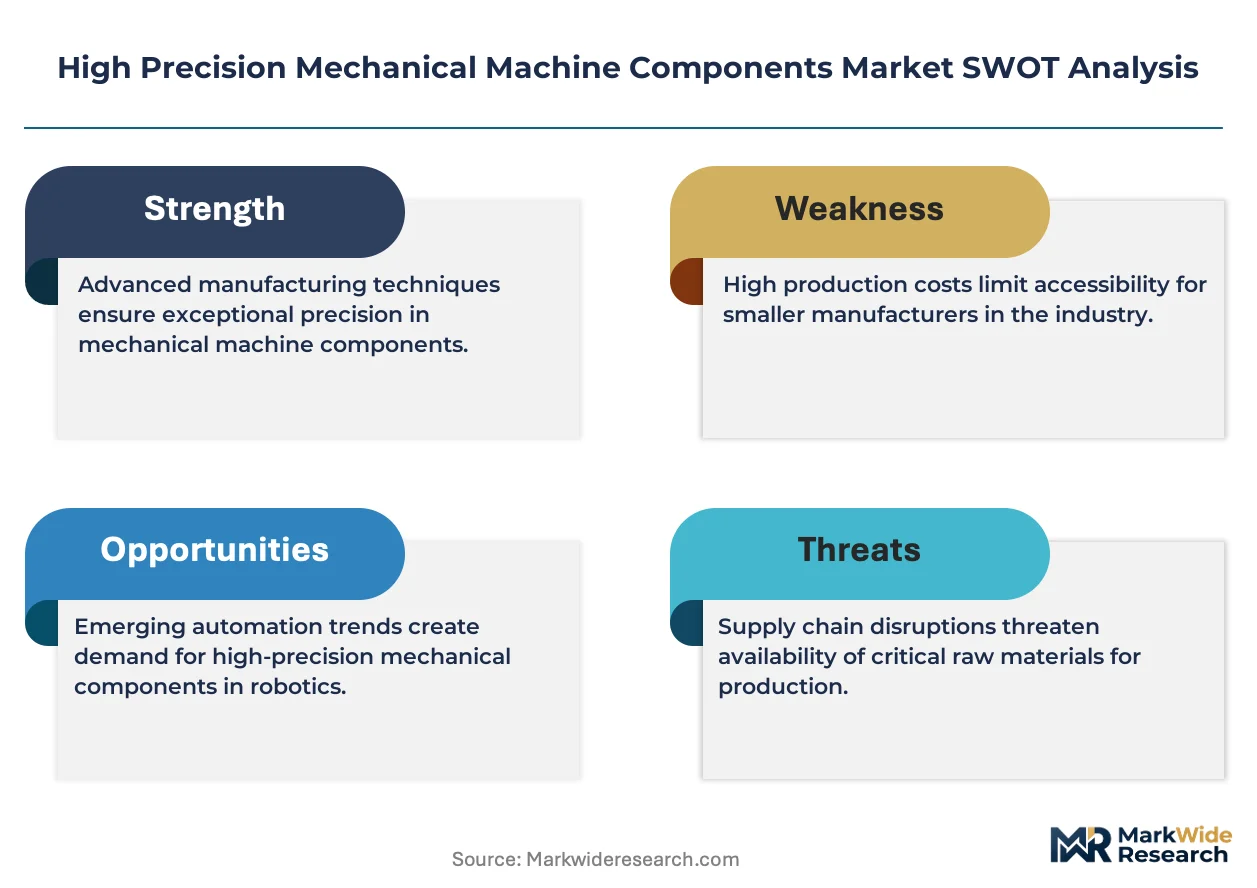
Growth Catalysts
- EU CE marking requirements:Machinery Directive safety-integrated design protocols are mandating higher-grade component specifications that expand addressable premium tiers for certified suppliers.
- Wire EDM technology:Medical device manufacturers in Germany's industrial corridor are expanding orders for micro-machined surgical instruments requiring sub-five-micron surface finishes.
- Wind turbine powertrain demand:Bearing replacement cycles in offshore installations are accelerating procurement of fatigue-resistant precision components.
Market Restraints
- Tungsten carbide supply concentration:Powder metallurgy feedstock for cutting tools and wear parts faces sourcing risk from limited geographic supplier bases.
- ISO 14001 environmental compliance:Energy-intensive finishing processes face carbon accounting pressure under EU Green Deal embodied carbon tracking rules.
- Additive manufacturing substitution:Metal 3D printing for low-volume custom geometries is displacing conventional subtractive machining in prototyping phases.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for semiconductor and medical device manufacturing are attracting precision component suppliers to establish domestic machining capacity.
- GB/T precision standards alignment:Foreign manufacturers certifying to China's national standards unlock SAMR market access for industrial automation equipment.
- Laser cutting and ultra-precision grinding convergence:Hybrid processing lines serving semiconductor fabrication tools command premium positioning through single-source capability.
Industry Challenges
- Metrology technician scarcity:CMM programming and surface measurement expertise gaps extend supplier qualification timelines for sub-micron tolerance contracts.
- Dual carbon goals compliance:China's MEE enforcement of energy intensity reductions forces capital reallocation toward renewable-powered finishing operations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Precision Mechanical Machine Components Market Trends and Innovations
Precision machining workflows are converging with in-process metrology and adaptive control systems that compress tolerance verification cycles and reduce scrap rates.
Ultra-precision diamond turning and deterministic micro-grinding is consolidating position as the dominant process for aspheric optics and semiconductor wafer handling components. Lithography equipment builders in Germany and Japan are standardizing on these processes for EUV mirror substrates and vacuum-stage bearings. The technology is consolidating supplier tiers by eliminating secondary finishing steps and reducing lot-to-lot variation.
REACH substance restrictions on hexavalent chromium coatings are forcing conversion to trivalent alternatives and physical vapor deposition for corrosion protection. Surface treatment houses serving aerospace and medical device OEMs face reformulation costs and qualification delays. Bearing and gear manufacturers with captive plating capacity are accelerating in-house PVD investments to maintain supply continuity.
Buyer consolidation among semiconductor capital equipment makers is concentrating procurement leverage and compressing component supplier margins. Tier-one lithography and inspection equipment builders are mandating vendor-managed inventory and consignment stocking arrangements. This pattern is most pronounced in Germany's Stuttgart-Munich industrial corridor where Bosch Rexroth and regional automation specialists dominate demand aggregation.
High Precision Mechanical Machine Components Market Segmentation
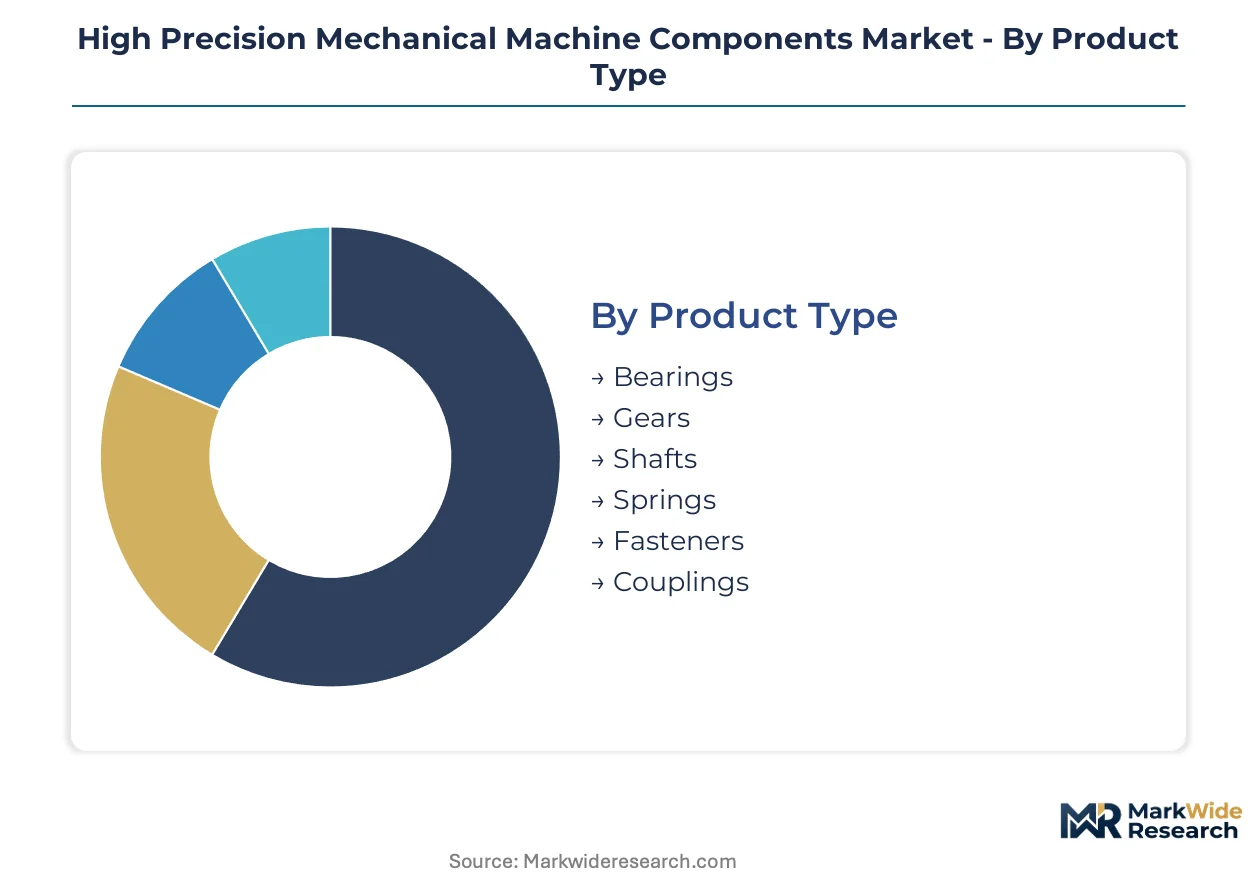
Precision mechanical components serve radically different performance regimes across end-uses, from fatigue-critical wind turbine gearboxes to sub-micron semiconductor wafer stages. Segmentation reveals where capital equipment investments concentrate and which manufacturing processes command premium positioning.
Product Type:
Customization intensity varies from catalog-standard bearings to metallurgically bespoke springs engineered for specific fatigue cycles.
- Bearings:Rolling-element and fluid-film designs manufactured to ABEC 7/9 tolerances for rotational stability under combined radial and thrust loads. Demand concentrates in Germany's Stuttgart-Munich corridor for automotive and industrial automation powertrains, driven by replacement cycles in electrified drivetrains requiring lower friction coefficients.
- Gears:Ground and honed tooth profiles achieving AGMA 14 quality or DIN 1-3 class for mesh precision and noise suppression. Aerospace actuation systems in France and Germany specify these grades for flight-control redundancy, with procurement tightening under EASA CS-25 airworthiness protocols.
- Shafts:Hardened and ground cylindrical forms with runout tolerances below 2 micrometers for rotational assemblies.
- Springs:Custom alloy wire forms including Inconel and Elgiloy for corrosion resistance and stress relaxation performance.
- Fasteners:Precision-threaded and rolled components for structural joints requiring preload consistency.
- Couplings:Disc, diaphragm, and bellows configurations accommodating misalignment while transmitting torque without backlash.
Most installed capacity flows through Bearings. Expansion is steepest in Couplings as semiconductor motion stages demand zero-backlash torque transmission.
Technology:
Process selection tracks volume economics versus geometric complexity, with subtractive methods dominating aerospace and hybrid approaches capturing medical device work.
- CNC Machining:Multi-axis milling and turning centers achieving positional accuracies of ±3 micrometers through thermal compensation and direct-drive rotary tables. Contract manufacturers in India's PLI-subsidized semiconductor corridors are installing five-axis capacity to serve domestic lithography tool builders.
- Wire EDM:CNC-controlled electrical discharge machining using brass or stratified wire electrodes for conductive materials regardless of hardness. Medical device manufacturers in Germany's industrial corridor specify this for micro-machined surgical instruments requiring sub-five-micron surface finishes and no burr formation.
- Grinding:Precision abrasive processes including cylindrical, surface, and centerless configurations for dimensional and form accuracy.
- Milling:Material removal through rotary cutters for prismatic geometries and pocket features in structural components.
- Turning:Single-point cutting for rotational symmetry in shafts, pins, and threaded forms.
- Laser Cutting:Thermal separation processes for thin-gauge metals and specialty alloys in prototyping and low-volume production.
Capacity investment tilts toward CNC Machining for volume scalability. Technology convergence between Wire EDM and ultra-precision grinding commands the steepest pricing premiums in semiconductor fabrication tool supply chains.
Application:
End-use segmentation maps directly to certification burden and tolerance specification stringency.
- Semiconductor Manufacturing:Vacuum-compatible motion stages, wafer handling robots, and lithography projection optics requiring sub-micron positioning stability. Equipment builders in Germany and Japan standardize on ultra-precision diamond turning and deterministic micro-grinding for EUV mirror substrates, consolidating supplier tiers by eliminating secondary finishing.
- Aerospace:Flight control actuators, landing gear mechanisms, and engine accessory drive trains governed by EASA and FAA airworthiness directives. REACH substance restrictions on hexavalent chromium coatings force conversion to trivalent alternatives and physical vapor deposition for corrosion protection in bearing and gear applications.
- Robotics:Harmonic drive components, joint bearings, and precision reducers for industrial and collaborative automation.
- Precision Instruments:Metrology frames, optical benches, and analytical device mechanisms requiring thermal stability.
- Marine Equipment:Propulsion shafting, steering gear, and subsea hydraulic components for corrosion resistance.
- Optical Devices:Aspheric lens mounts, interferometer stages, and laser cavity structures for wavefront control.
Procurement volume aggregates in Semiconductor Manufacturing. Application expansion is most rapid in Robotics as collaborative automation penetrates medical device assembly and electronics manufacturing.
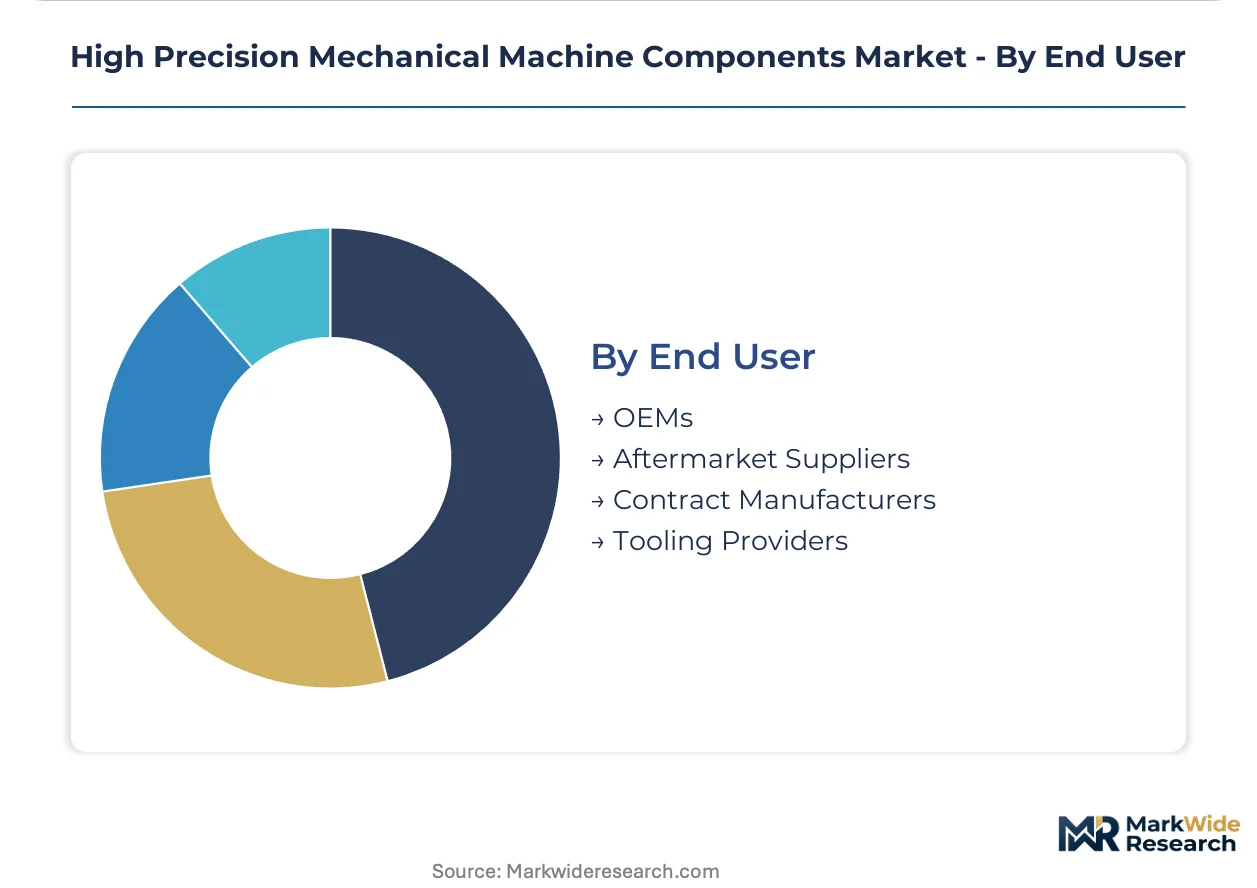
End User:
Channel structure determines inventory risk allocation and technical support depth.
- OEMs:Original equipment manufacturers with captive design authority specifying components directly for integrated systems. Semiconductor capital equipment makers concentrate procurement leverage through vendor-managed inventory and consignment stocking arrangements, compressing supplier margins in Germany's industrial corridor.
- Aftermarket Suppliers:Independent distributors and service organizations supporting replacement demand and maintenance operations. Wind turbine offshore installations accelerate bearing replacement cycles, creating procurement urgency for fatigue-resistant precision components through non-OEM channels.
- Contract Manufacturers:Build-to-print machining houses serving as extended capacity for OEMs lacking internal precision processing.
- Tooling Providers:Cutting tool, die, and mold manufacturers consuming precision components as production inputs.
Order flow concentrates through OEMs. Aftermarket Suppliers are gaining share fastest as asset-heavy industries extend equipment service life through predictive maintenance programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart-Munich industrial corridor anchors procurement concentration for high precision mechanical machine components, with semiconductor lithography equipment builders and automotive powertrain manufacturers driving sub-micron tolerance demand across multiple continents.
Germany
Semiconductor lithography and industrial automation powertrains dominate component procurement in Baden-Württemberg and Bavaria. The EU Machinery Directive's CE marking requirements enforce safety-integrated design protocols that elevate specification thresholds for bearing and gear suppliers. Bosch Rexroth anchors demand aggregation in Stuttgart, while precision machining networks around Munich qualify for EUV mirror substrate contracts.
China
Domestic lithography tool builders and electric vehicle powertrain manufacturers are expanding orders for GB/T-certified precision components. SAMR market access rules and dual carbon goals enforced by MEE recast supplier qualification around energy intensity metrics. Yangtze River Delta machining clusters in Suzhou and Wuxi attract foreign joint ventures seeking local content compliance.
Japan
EUV equipment supply chains and robotics precision reducers drive demand for deterministic micro-grinding capacity. METI industrial policy supports domestic sourcing for semiconductor fabrication tools under national technology security frameworks. Chubu region manufacturers around Nagoya consolidate ultra-precision diamond turning for wafer handling components.
United States
Aerospace actuation systems and medical device micro-machining absorb high-volume bearing and wire EDM output. FAA airworthiness directives and FDA device regulations impose traceability requirements that extend into component supply chains. Precision machining corridors in Greater Boston and the Pacific Northwest specialize in flight-critical gear and fastener production.
India
PLI scheme subsidies for semiconductor and medical device manufacturing are attracting five-axis CNC capacity investments. BIS standards alignment and DGFT import substitution policies shape local content requirements for industrial automation equipment. Karnataka and Telangana machining clusters near Bangalore and Hyderabad qualify for domestic lithography tool supplier tiers.
High Precision Mechanical Machine Components Market Competitive Landscape
Capacity expansion dominates the current landscape as precision machining networks retool for sub-micron semiconductor contracts. The vendor base stratifies across three tiers: integrated motion control houses with captive component production, specialized bearing and gear manufacturers with metallurgical differentiation, and contract machining houses serving as overflow capacity. Tier-one lithography equipment builders are compressing supplier margins through vendor-managed inventory mandates. Technology licensing agreements and backward integration into finishing processes represent the dominant competitive moves.
Among diversified industrial technology groups, Bosch Rexroth and Danaher exemplify distinct archetypes. Bosch Rexroth occupies a position as an integrated motion control supplier with hydraulics-to-precision portfolio breadth. Danaher represents the precision instrumentation and metrology vector with R&D intensity in measurement systems. SKF anchors the bearing specialization archetype across fatigue-critical applications. These three entities illustrate how scale, integration depth, and technical focus define competitive positioning without requiring specific strategic action claims.
| Leading Market Players |
|---|
| Bosch Rexroth |
| Danaher |
| JTEKT Corporation |
| Mitsubishi Heavy Industries |
| NSK Ltd. |
| NTN Corporation |
| Parker Hannifin |
| Renishaw |
| SKF |
| Others |
Pricing and Supply Chain Analysis
Ultra-precision diamond turning and deterministic micro-grinding adoption is compressing secondary finishing costs while consolidating supplier tiers around Germany and Japan, creating asymmetric pricing power for integrated motion control houses that captive these processes.
Pricing Analysis
Input-cost pass-through from tungsten carbide powder metallurgy and energy-intensive PVD finishing runs through component price structures. Three-tier pricing structure across premium, standard, and economy levels separates ABEC 9 bearings with CE marking from DIN-standard gears and catalog fasteners. Cost compression in standard-tier CNC-machined shafts is intensifying because India's PLI-subsidized capacity expansion floods mid-precision segments. Contract manufacturers exhibit highest price sensitivity; lithography equipment OEMs show least sensitivity due to zero-failure tolerance requirements.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Suzhou, and Nagoya anchor hub-and-spoke patterns for just-in-time delivery to semiconductor fabrication tool builders. Manufacturing concentrates in Germany, China, and Japan, with Yangtze River Delta clusters feeding domestic lithography programs. Supply chains draw from tungsten carbide feedstock, specialty alloy wire, and rare-earth magnetic materials. Single-source vulnerability around EUV mirror substrate suppliers in Germany's industrial corridor threatens equipment builder procurement continuity. Distribution runs through vendor-managed inventory mandates with consignment stocking at OEM assembly sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's MEE-enforced energy intensity compliance and Germany's EU Green Deal embodied carbon tracking creates cost differentials for finishing operations, rewarding suppliers with renewable-powered capacity in both jurisdictions.
For Market Incumbents: Cement qualification lock-in with lithography equipment builders by accelerating captive ultra-precision grinding investments before India's PLI-subsidized entrants achieve sub-micron certification. Defend against additive manufacturing substitution in prototyping phases by bundling metrology services with production contracts. Prioritize backward integration into PVD coating to circumvent REACH-driven surface treatment bottlenecks.
For New Entrants and Emerging Players: Digital-channel route through vendor-managed inventory platforms offers entry path into semiconductor capital equipment supply chains without direct OEM salesforce investment. Target India's Karnataka and Telangana machining clusters where domestic lithography tool builders lack qualified local bearing suppliers. Pursue GB/T precision standards alignment as gating credential for SAMR market access before foreign competitors establish joint venture footprints.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract machining houses with wire EDM capacity but without lithography qualification, offering platform consolidation targets. Five-to-ten-year viability hinges on deterministic micro-grinding technology access for EUV substrate contracts. Watch for MEE enforcement actions on Yangtze River Delta finishing operations as signal for supply chain reconfiguration toward renewable-powered competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVD Coating | Captive corrosion protection capacity bypasses REACH-driven surface treatment delays for aerospace bearings. |
| GB/T Precision Standards Certification | SAMR market access unlocks procurement from China's domestic lithography tool builders expanding under dual carbon goals. |
| Ultra-Precision Grinding Capacity Expansion | EUV mirror substrate contracts consolidate with German and Japanese suppliers eliminating secondary finishing steps. |
| Vendor-Managed Inventory Platforms | Digital procurement integration meets lithography OEM consignment mandates compressing traditional distributor margins. |
| Renewable-Powered Finishing Operations | MEE energy intensity enforcement and EU Green Deal carbon tracking recast cost structures for precision components. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lithography equipment procurement directors, precision machining plant managers, metrology service heads, and aftermarket bearing distributors with secondary validation. Sources included SEC filings from diversified industrial technology groups, German mechanical engineering association production surveys, China's SAMR market access bulletins, and EU Machinery Directive implementation guidance. Bottom-up capacity assessments across Stuttgart-Munich, Yangtze River Delta, and Chubu region machining clusters triangulated against top-down semiconductor capital equipment spend projections.
Historical reference periods anchored volume and value outputs to pre-pandemic baseline capacity utilization and post-recovery sub-micron tolerance demand inflection. Segmentation modeling spanned product type, manufacturing technology, end-use application, and regional regulatory cluster. CAGRs derived from equipment builder order backlogs, replacement cycle analysis for wind turbine powertrains, and PLI scheme capacity commissioning timelines. Forecast inputs incorporated wire EDM technology adoption curves and REACH substance restriction phase-out schedules.
The model assumes a particular technology adoption path; alternative pathways for metal additive manufacturing in low-volume custom geometries would alter the outlook for subtractive machining demand. Forecasts reflect documented assumptions around semiconductor fabrication tool build rates and energy transition policy enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.