
 Smart Screen Market | 2026-2036
Smart Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Screen Market Insights
Enterprise buyers are gaining share over consumer households as the smart screen demand base is bifurcating between premium home automation installations and bulk commercial deployments. Samsung Electronics leverages its captive semiconductor and display panel capacity to control component costs across product tiers. LG Electronics anchors its position through OLED technology leadership in high-margin professional signage segments. Amazon.com, Inc. competes aggressively on voice-recognition integration and recurring-services attachment rather than hardware margins alone.
A smart screen is an interactive display system integrating touch, voice, or gesture input with network connectivity, typically employing LCD or OLED panels with embedded processors, ambient light sensors, and wireless modules for real-time content rendering and user response. These systems serve commercial command centers, retail environments, educational campuses, and residential settings where information must be dynamically presented and manipulated without peripheral devices. OLED product types command premium positioning in healthcare and broadcast monitoring applications where color accuracy and contrast ratio determine purchasing decisions. IoT Integration technology is expanding fastest in retail displays and home automation as buyers prioritize seamless ecosystem connectivity over standalone functionality. Gaming applications remain a concentrated margin pool for manufacturers that specialize in sub-10ms input lag and variable refresh rate certification.
The Federal Communications Commission in the United States enforces electromagnetic compatibility and radio-frequency emission standards that constrain wireless module design and certification timelines for smart screen vendors. The European Union's REACH regulation and RoHS directive restrict hazardous substance use in display manufacturing, compelling suppliers to reformulate solder compositions and backlight phosphor chemistry. China's MIIT mandates GB standard compliance for network-connected display products, creating a separate certification track for products targeting domestic versus export channels. Stakeholders must monitor diverging energy-efficiency and data-privacy compliance pathways across these jurisdictions to avoid product redesign cycles that erode development budgets.
Market Dynamics
Enterprise procurement of interactive displays is decomposing the traditional consumer-electronics supply chain, forcing panel makers to reconfigure production lines for commercial-grade durability and extended warranty terms.
Growth Catalysts
- Healthcare digitization:United States hospital systems are accelerating deployment of bedside interactive terminals for patient engagement and clinical workflow integration.
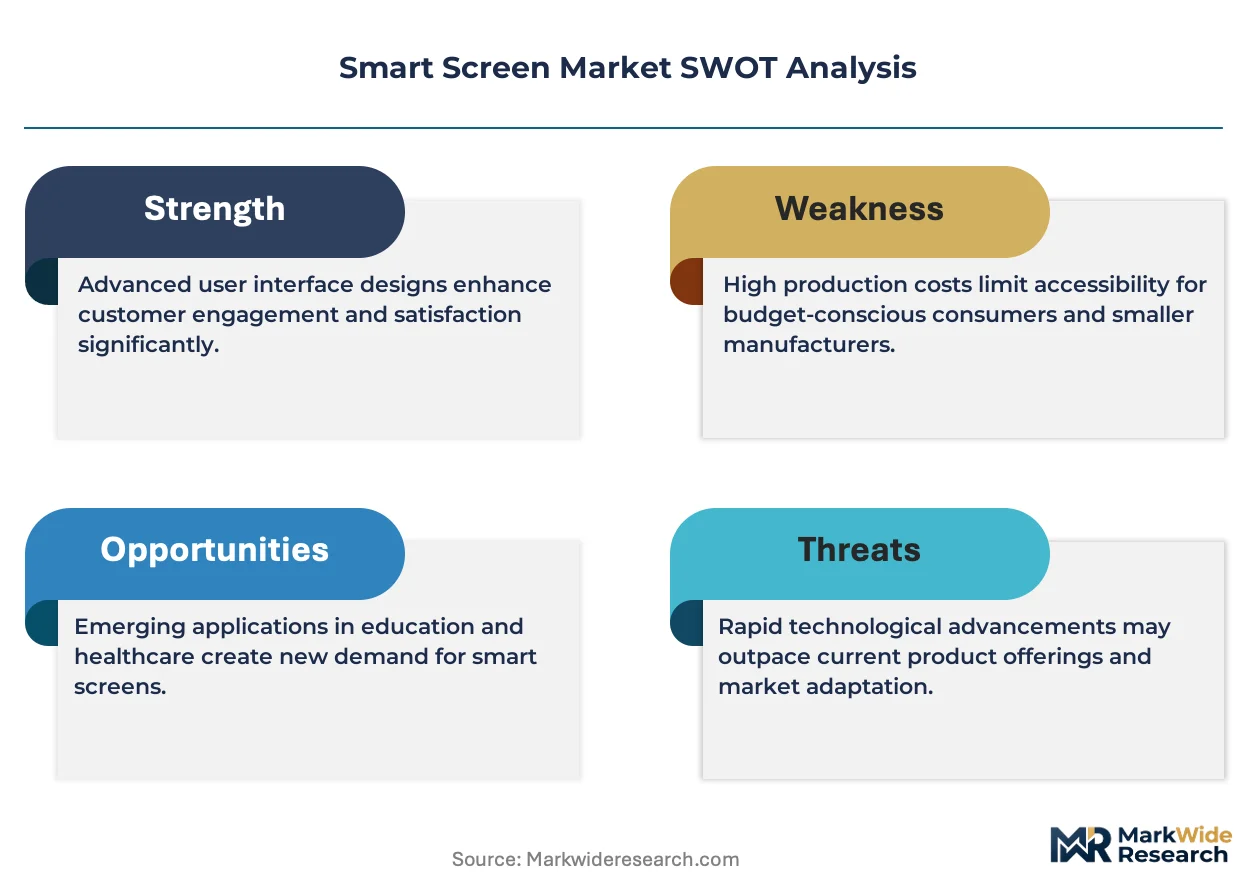
- REACH compliance:European Union material disclosure rules are compelling display manufacturers to reformulate solder compositions, creating first-mover advantages for suppliers with certified green chemistry.
- Guangdong cluster density:Shenzhen-based ODMs and panel makers in China's Guangdong Province benefit from component ecosystem proximity that compresses procurement lead times.
Market Restraints
- Input cost volatility:Rare earth phosphor prices for OLED backlighting fluctuate with Chinese export quota policies, squeezing margin predictability.
- Supply concentration risk:Taiwan and South Korea dominate advanced semiconductor display driver IC fabrication, creating single-source vulnerability.
- Regulatory friction:FCC electromagnetic compatibility certification timelines for wireless modules extend product launch windows by 4-8 months.
Strategic Opportunities
- Underpenetrated education vertical:India's K-12 and higher education institutions remain below 15% interactive display penetration, offering volume scale for cost-optimized product tiers.
- Regulatory tailwind:China's MIIT GB standard compliance mandate for network-connected displays creates a captive domestic certification track that foreign competitors struggle to navigate.
- Technology convergence:Edge AI inference chips and low-latency wireless protocols are enabling real-time gesture recognition without cloud dependency.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineering for touch controller integration and ambient light calibration exceeds available specialized labor pools.
- Certification timeline compression:Simultaneous FCC, CE marking, and MIIT GB testing requirements demand parallel regulatory submissions that strain quality assurance bandwidth.
- Legacy AV infrastructure incompatibility:Commercial buyers require HDMI-CEC and RS-232 backward compatibility that complicates SoC architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Screen Market |
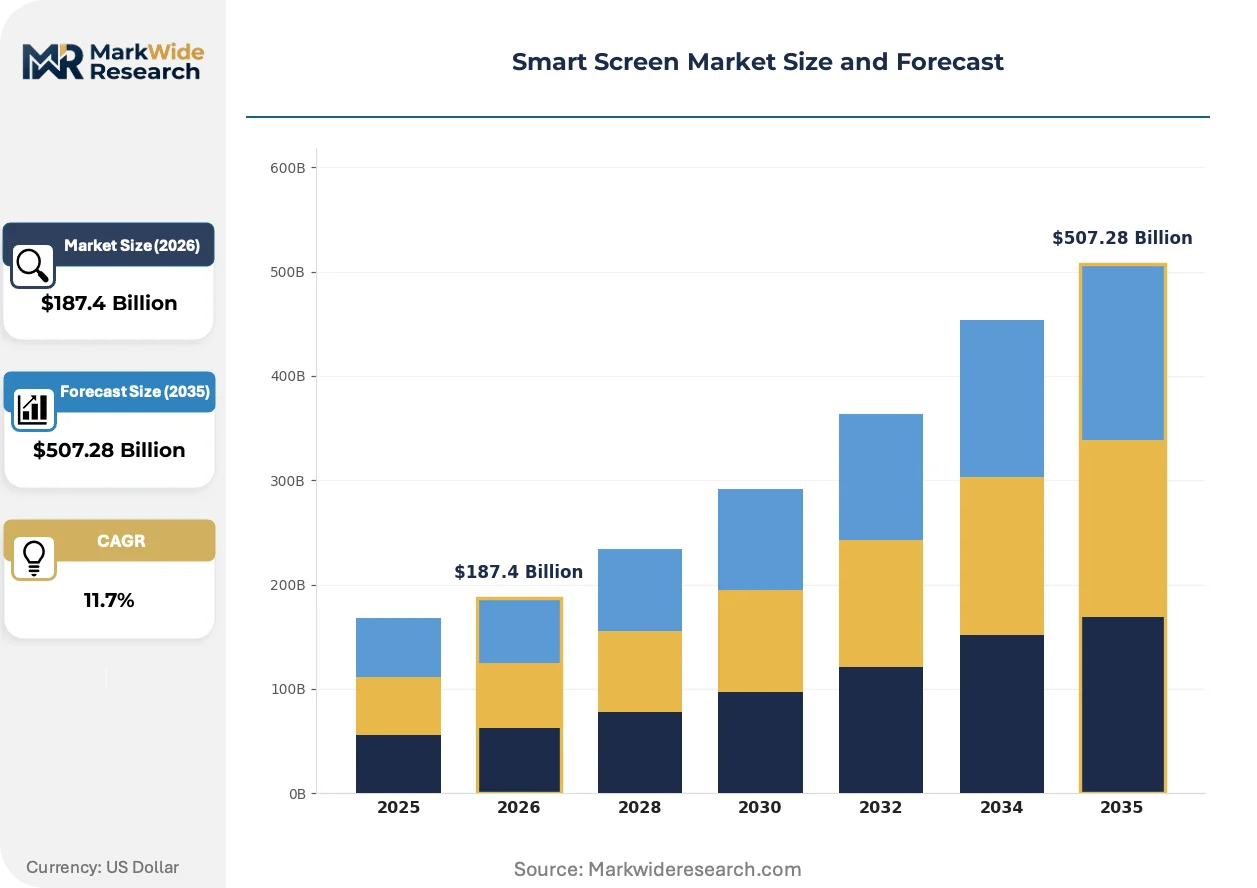
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, LED, QLED Application: Retail Displays, Home Automation, Education, Gaming End User: Residential, Commercial, Educational Institutions, Healthcare Technology: Touchscreen, Voice Recognition, Gesture Control, IoT Integration |
| Companies Covered | Samsung Electronics, LG Electronics, Amazon.com, Inc., Alphabet Inc., Lenovo Group Limited, Sony Corporation, Panasonic Corporation, BenQ Corporation, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Screen Market Trends and Innovations
Display technology architectures are fragmenting as specialized use cases demand customized performance profiles rather than one-size-fits-all consumer panels.
Mini-LED backlighting is decomposing the premium display tier by delivering OLED-comparable contrast ratios at lower burn-in risk and higher peak brightness. Broadcast monitoring suites and surgical visualization systems in Germany and Japan are adopting these panels fastest. The technology is compressing the addressable market for conventional OLED in professional signage applications where static image retention previously blocked adoption.
REACH and RoHS directive enforcement is tightening hazardous substance thresholds for display manufacturing, compelling reformulation of lead-free solder and mercury-free backlight phosphors. European ODMs are consolidating supplier audits to pre-certify component streams. Medical-grade display segments face the steepest compliance cost escalation due to extended warranty obligations and traceability documentation requirements.
Enterprise buyers are consolidating vendor relationships through multi-year framework agreements that bundle hardware, software licenses, and field service. Systems integrators in the United States and United Kingdom are displacing traditional distributor channels for projects above 500-unit scale. This concentration is most visible in corporate command center deployments where single-source accountability reduces integration risk.
Smart Screen Market Segmentation
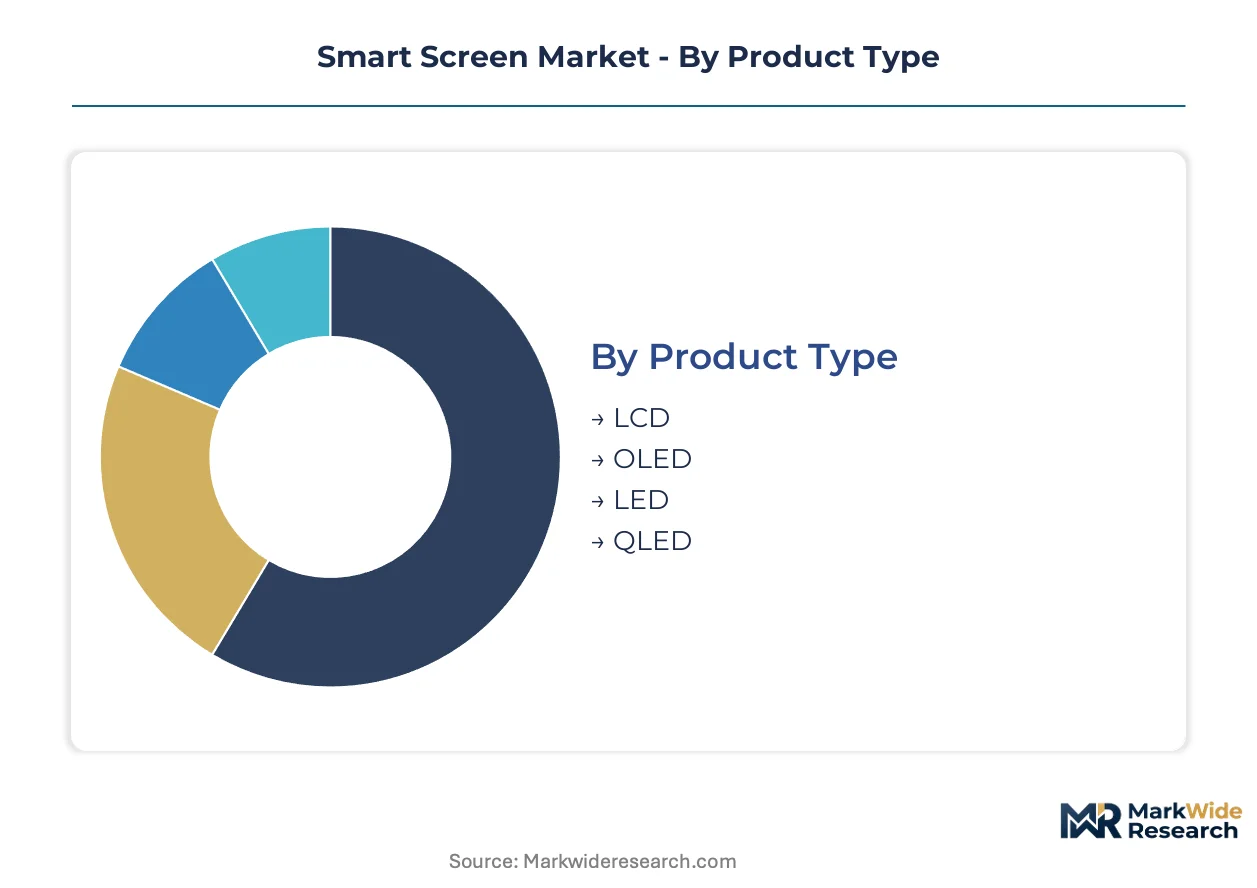
Smart screen purchasing decisions diverge sharply across technical specifications, deployment contexts, and integration requirements. Manufacturers must architect product portfolios that span divergent certification standards, durability expectations, and ecosystem compatibility demands without fragmenting development resources.
Product Type:
REACH and RoHS thresholds reshape competitive positioning across display chemistries, with hazardous substance compliance costs concentrating in premium professional tiers.
- LCD:Liquid crystal panels with LED edge or direct backlighting dominate volume manufacturing due to mature supply chains and lower unit economics. Hospital systems in the United States specify these displays for nursing station dashboards where 24/7 operational reliability outweighs color fidelity requirements.
- OLED:Organic light-emitting diode technology delivers self-emissive pixels with infinite contrast ratios and sub-millisecond response times. Broadcast monitoring facilities in Germany and surgical visualization suites in Japan absorb premium pricing for color accuracy certification and extended grayscale performance.
- LED:Direct-view LED arrays scale to architectural dimensions for outdoor signage and arena installations. Shenzhen-based manufacturers cluster production for modular cabinet systems serving transit hubs across China's tier-one cities.
- QLED:Quantum dot-enhanced LCD layers expand color gamut coverage through nanoparticle phosphor films. Samsung Electronics leverages captive semiconductor capacity to control quantum dot material costs across consumer and professional product lines.
Established volume favors LCD; emerging adoption favors OLED.
Application:
Cost tier differentiation separates turnkey consumer bundles from custom-engineered commercial deployments requiring field service integration.
- Retail Displays:Interactive kiosks and digital signage networks prioritize sunlight readability and tamper-resistant enclosures. European Union Ecodesign standby power limits constrain always-on connectivity architectures for in-store product locators.
- Home Automation:Wall-mounted control panels and kitchen displays demand seamless voice-recognition integration with existing smart home ecosystems. Amazon competes through recurring-services attachment rather than hardware margins alone in this segment.
- Education:Interactive whiteboards and student collaboration screens require sub-35ms touch latency and anti-glare surface treatments. India's K-12 institutions remain below 15% penetration, offering volume scale for cost-optimized product tiers.
- Gaming:High-refresh-rate monitors with variable refresh certification command concentrated margins from esports venues and enthusiast households. Sub-10ms input lag specifications differentiate specialist manufacturers from generalist panel suppliers.
Procurement scale concentrates in retail; margin expansion concentrates in gaming.
End User:
Customer type determines warranty duration, service level agreements, and regulatory documentation burdens.
- Residential:Consumer households prioritize voice-recognition integration and streaming service compatibility over commercial-grade durability. FCC electromagnetic compatibility certification for wireless modules extends residential product launch windows.
- Commercial:Corporate command centers and hospitality venues require multi-year framework agreements bundling hardware, software licenses, and field service. Systems integrators in the United States displace traditional distributor channels for projects above 500-unit scale.
- Educational Institutions:K-12 and university procurement cycles align with fiscal year budgets and technology refresh grants. Extended warranty terms and theft-resistant mounting hardware differentiate education-specific product configurations.
- Healthcare:Bedside terminals and clinical workflow displays demand IEC 60601 medical electrical safety certification and antimicrobial surface coatings. United States hospital systems accelerate deployment for patient engagement and EMR integration.
Procurement velocity favors residential; contract value favors commercial.
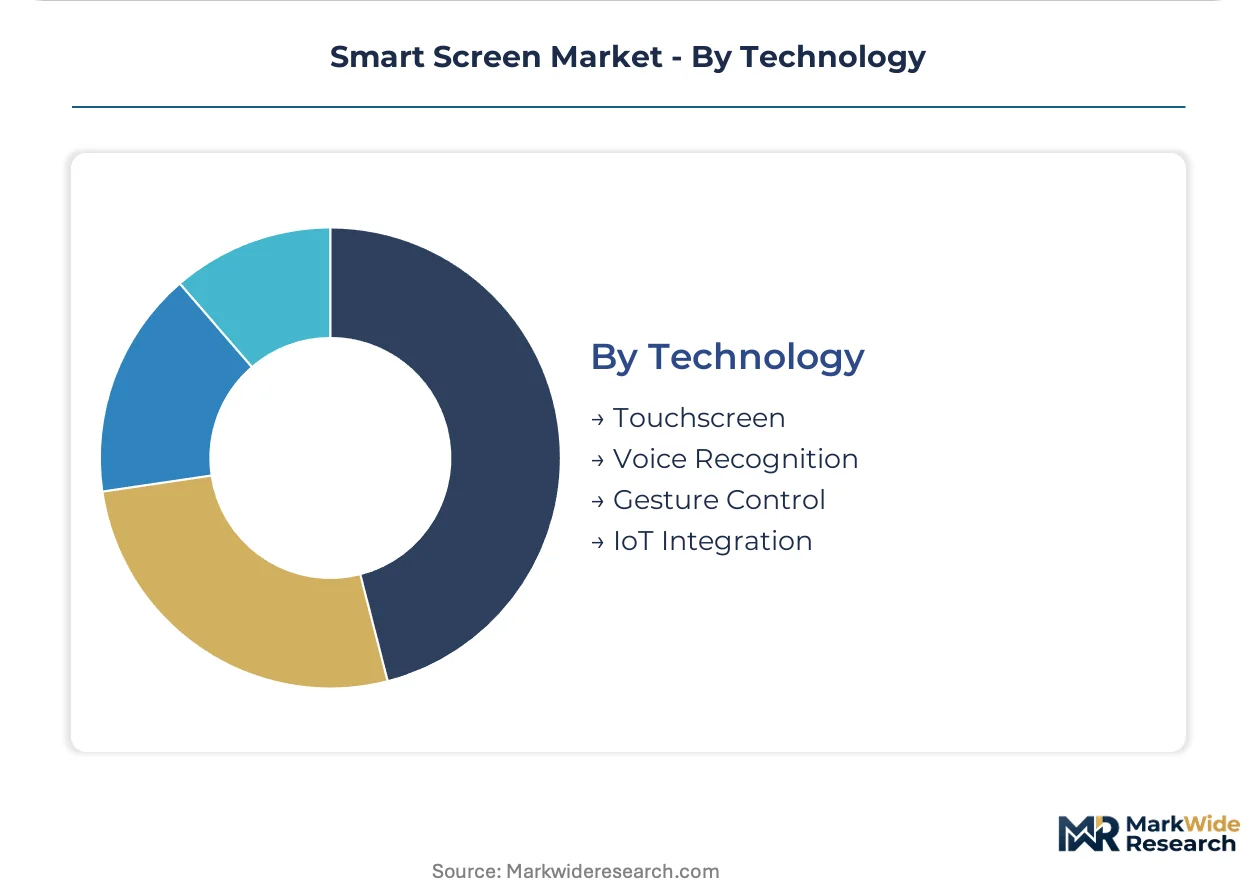
Technology:
Maturity curves separate proven input modalities from emerging gesture and edge-AI inference capabilities.
- Touchscreen:Capacitive and infrared touch layers dominate input method share across all price tiers. Embedded systems talent scarcity for touch controller firmware exceeds available specialized labor pools.
- Voice Recognition:Far-field microphone arrays and natural language processing engines enable hands-free operation in kitchen and healthcare settings. Cloud-dependent architectures face data privacy compliance friction under GDPR and emerging state-level regulations.
- Gesture Control:Time-of-flight sensors and computer vision algorithms interpret mid-air hand movements without surface contact. Edge AI inference chips are enabling real-time processing without cloud dependency in retail and automotive demonstration environments.
- IoT Integration:Zigbee, Z-Wave, and Matter protocol support embed displays within broader automation ecosystems. Guangdong Province ODMs compress procurement lead times for wireless module integration through component ecosystem proximity.
Deployment reliability favors touchscreen; ecosystem expansion favors IoT Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shenzhen anchors Asia-Pacific smart screen logistics, handling over 25 million TEU annually and connecting Guangdong Province panel makers to global assembly networks through direct transpacific routes.
United States
Hospital systems in Texas and California accelerate procurement of bedside interactive terminals for patient engagement and EMR integration. FCC electromagnetic compatibility certification for wireless modules extends product launch windows by 4-8 months. Greater Boston hosts medical-grade display engineering clusters serving surgical visualization and broadcast monitoring applications.
Germany
Broadcast monitoring facilities and surgical visualization suites absorb premium OLED pricing for color accuracy certification. ECHA REACH enforcement tightens hazardous substance thresholds, compelling reformulation of lead-free solder and mercury-free backlight phosphors. Bavaria concentrates medical display engineering talent alongside precision optics manufacturers.
China
Guangdong Province panel makers and ODMs cluster near component ecosystems that compress procurement lead times. MIIT mandates GB standard compliance for network-connected display products, creating a separate certification track for domestic versus export channels. Shenzhen-based manufacturers dominate modular LED cabinet systems for transit hub deployments.
Japan
Surgical visualization suites and broadcast monitoring facilities demand extended grayscale performance and sub-millisecond response times. METI industrial standards guide display quality benchmarks for professional applications. Chubu region maintains precision manufacturing clusters for medical-grade panel calibration equipment.
India
K-12 and higher education institutions remain below 15% interactive display penetration, offering volume scale for cost-optimized product tiers. BIS certification requirements for electronic imports create compliance barriers for unestablished suppliers. Maharashtra and Karnataka concentrate systems integrator capacity for education technology deployments.
Smart Screen Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and component supply dimensions. The vendor base organizes around three tiers: diversified electronics conglomerates with captive semiconductor capacity, display-technology pure-plays, and cloud-services platforms subsidizing hardware penetration. Strategic moves concentrate on backward integration into panel supply and multi-year framework agreements bundling hardware with software licenses.
Within the diversified conglomerate tier, Samsung Electronics and LG Electronics exemplify scale-driven positioning through captive display panel and semiconductor capacity. Amazon.com, Inc. occupies a distinct services-anchored position, competing through voice-recognition integration and recurring-services attachment rather than hardware margins alone. These three entities represent divergent competitive logics: component control, technology specialization, and ecosystem lock-in.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Amazon.com, Inc. |
| Alphabet Inc. |
| Lenovo Group Limited |
| Sony Corporation |
| Panasonic Corporation |
| BenQ Corporation |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Mini-LED backlighting substitution for OLED in professional signage is redrawing procurement geography toward Shenzhen and Kaohsiung while compressing premium-tier pricing spreads that previously rewarded burn-in risk tolerance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs commercial procurement, with IEC 60601 medical certification and FCC wireless module approval driving spreads between tiers. Cost compression in standard-tier LCD panels is intensifying because Guangdong ODMs are absorbing rare earth phosphor volatility through captive material hedging. Hospital systems in Texas exhibit lowest price sensitivity for bedside terminals, while Indian education procurement teams demand economy-tier quotations with extended warranty bundling.
Supply Chain Analysis
Taiwan Strait maritime transit underwrites semiconductor display driver IC flows from Hsinchu Science Park fabs to Shenzhen assembly floors. Advanced node fabrication draws from Taiwan and South Korea, while quantum dot phosphors and OLED emitter materials rest on Chinese rare earth processing. Single-source vulnerability concentrates in 28nm display driver supply. Distribution runs through systems integrators for commercial deployments above 500 units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart screen demand sits in early-cycle expansion as hospital digitization and education refresh grants accelerate replacement of static displays with interactive terminals.
For Market Incumbents: Fortify captive semiconductor capacity through backward integration into display driver IC design, insulating margin structures from Taiwan foundry concentration risk. Accelerate MIIT GB standard pre-certification to lock out foreign competitors from China's domestic channel. Mini-LED cost curves threaten OLED premium positioning in broadcast monitoring. For New Entrants and Emerging Players: BIS certification fast-track for Indian education procurement offers the most penetrable entry vector, with Maharashtra systems integrators seeking cost-optimized interactive whiteboard suppliers. Target K-12 deployment through state-level technology refresh grants, positioning on sub-35ms touch latency specifications that differentiate from consumer-grade imports. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors component-control archetypes over pure-play hardware assemblers. Five-to-ten year viability hinges on captive panel supply and edge-AI inference chip integration. Watch for MIIT GB certification backlog clearance as inflection signal for domestic Chinese market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Display Driver ICs | Taiwan foundry concentration creates margin vulnerability that captive design teams can neutralize. |
| MIIT GB Standard Pre-Certification | China's network-connected display mandate erects compliance barriers that first-movers exploit. |
| Edge AI Inference Chip Integration | Real-time gesture recognition without cloud dependency opens retail and automotive demonstration environments. |
| Multi-Year Framework Agreement Bundling | Corporate command centers in the United States prioritize single-source accountability for 500-plus unit deployments. |
| Mini-LED Backlighting Transition | Surgical visualization suites in Germany and Japan adopt panels that match OLED contrast without burn-in risk. |
Research Methodology
Operator-level perspectives from display panel procurement managers, hospital biomedical engineering directors, education technology integrators, and FCC certification consultants anchored the qualitative base. Secondary validation drew from SEC 10-K filings of listed electronics conglomerates, MIIT GB standard disclosure databases, ECHA REACH substance registration archives, and hospital procurement contract aggregators. Bottom-up unit economics triangulated against top-down addressable market sizing.
Sensitivity analysis tested volume assumptions across product type, application vertical, end-user category, and input technology modality dimensions over the projection horizon. CAGRs derived from installed base replacement cycles, penetration rate trajectories, and pricing elasticity coefficients. Forecast inputs incorporated rare earth export quota policy scenarios and FCC certification timeline distributions.
Underlying assumptions cover hospital digitization spend persistence, education grant continuity, and semiconductor foundry capacity expansion, with deviation risk concentrated in Chinese environmental enforcement intensity and REACH substance threshold tightening. Practitioners should keep alternative scenarios live as medical-grade certification requirements and wireless protocol standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Semiconductor Components Market
Display Technologies
Interactive Display Market
Display Technologies
4K VR Displays Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
8K Display Resolution Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Global Display Panel Market
Display Technologies
Touch Screen Display Market
Display Technologies
Global Wearable Display Market
Display Technologies
4K Technology Market
Display Technologies
OLED Display Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
Video Wall Display Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Flexible Screens Market