
 Radiation Hardened Electronics Market | 2026-2036
Radiation Hardened Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Hardened Electronics Market Intelligence
Commercial-grade semiconductor manufacturing techniques adapted for radiation tolerance is rewriting the cost structure of space-grade electronics. BAE Systems leverages decades of defense contracting relationships to anchor high-reliability product lines. Microchip Technology sustains broad portfolio coverage across memory and microcontroller segments. Honeywell International dominates avionics-grade hardened electronics with integrated thermal management capabilities.
Radiation hardened electronics are electronic components and systems engineered to withstand ionizing radiation effects including single-event upsets, total ionizing dose degradation, and displacement damage, typically fabricated on specialized silicon-on-insulator or epitaxial substrates with operating temperature ranges spanning cryogenic to elevated thermal environments. FPGAs lead product type revenue contribution due to reconfigurable mission profiles in satellites and interplanetary probes. Memory devices represent the fastest-expanding segment as on-board data storage requirements multiply with high-resolution sensing payloads. Government end users command the largest contract values, though commercial aerospace procurement is broadening the customer base.
ESA radiation hardness assurance standards and NASA-STD-8739 govern component qualification trajectories for European and American space missions respectively. The U.S. Department of Defense mandates MIL-STD-883 test methods for defense system electronics, creating barrier-to-entry conditions for non-domestic suppliers. Stakeholders must weigh qualification timeline compression against the technical risk of emerging commercial space vendors entering heritage supply chains.
Market Dynamics
Commercial satellite constellation operators are compressing radiation qualification timelines from heritage multi-year cycles to 18-month windows, forcing component suppliers to adapt MIL-STD-883 test protocols without sacrificing ionizing dose tolerance thresholds. This acceleration is restructuring supplier-customer contracting relationships across the space electronics value chain.
Growth Catalysts
- LEO Constellation Deployment:Commercial aerospace operators in the United States are procuring hardened components at volumes previously reserved for government missions, expanding addressable demand beyond traditional defense contractors.
- NASA-STD-8739 Tightening:Revised qualification protocols for deep-space missions are mandating higher total ionizing dose thresholds, creating upgrade cycles for existing satellite electronics inventories.
- Silicon-on-Insulator Process Maturation:Foundry-level SOI fabrication advances are reducing unit costs for radiation-tolerant FPGAs while maintaining single-event upset immunity specifications.
Market Restraints
- Epitaxial Wafer Supply Concentration:Japanese and German substrate suppliers control critical SOI and epitaxial material flows, creating vulnerability to geopolitical trade restrictions or capacity constraints.
- MIL-STD-883 Compliance Burden:Defense qualification requirements impose 24-36 month certification timelines that exclude commercial space vendors from heritage supply chains regardless of technical capability.
- Commercial FPGA Substitution:Radiation-tolerant commercial-off-the-shelf components are displacing fully hardened alternatives in low-earth orbit applications, compressing margins for qualified suppliers.
Strategic Opportunities
- Cislunar Mission Electronics:NASA Artemis program requirements for lunar surface operations are opening new qualification categories for extreme-temperature radiation-hardened components outside traditional geostationary specifications.
- On-Orbit Servicing Infrastructure:Satellite life-extension vehicles and orbital tugs require reconfigurable computing platforms with radiation tolerance profiles distinct from conventional payload electronics.
- European Space Agency Partnership Pathways:ESA radiation hardness assurance standard harmonization initiatives are creating entry mechanisms for qualified non-European suppliers into previously closed procurement channels.
Industry Challenges
- Radiation Effects Modeling Talent Scarcity:The specialized skill set combining semiconductor physics with Monte Carlo simulation for single-event effects prediction is concentrated among a shrinking cohort of heritage program engineers approaching retirement.
- Qualification Facility Bottlenecks:Heavy-ion accelerator access for ground-based radiation testing is constrained to national laboratory facilities in the United States, France, and Japan, creating 6-9 month queue delays for new component validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Hardened Electronics Market |
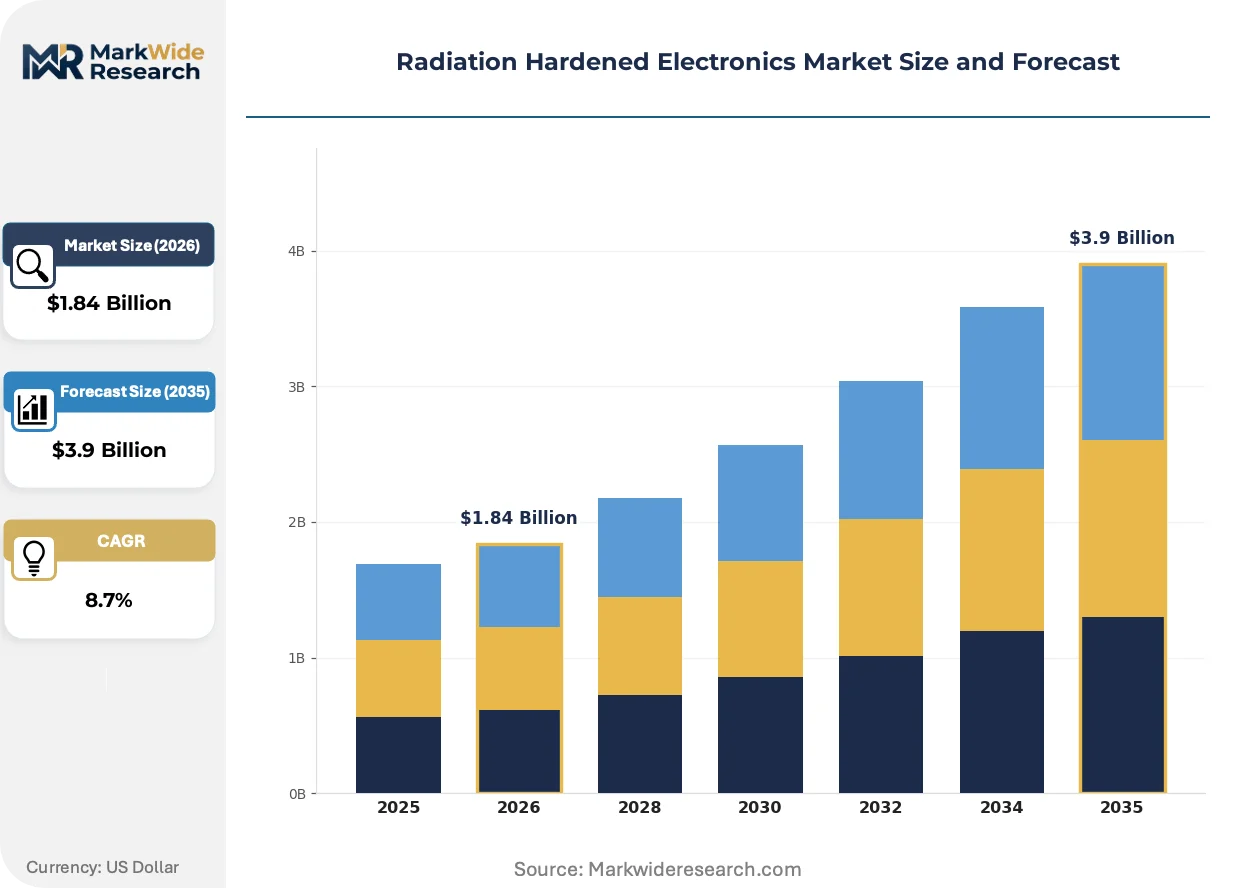
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $3.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, FPGAs, Memory Devices, Power Management ICs Application: Aerospace, Defense Systems, Medical Imaging, Space Exploration Technology: Circuit Design, Triple Modular Redundancy, CMOS Technology, Versatile Low-Noise Amplifiers End User: Government, Commercial Aerospace, Medical Institutions, Research Organizations |
| Companies Covered | BAE Systems, Microchip Technology, Honeywell International, Texas Instruments, STMicroelectronics, Infineon Technologies, Renesas Electronics, Analog Devices, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Hardened Electronics Market Strategic Shifts & Innovations
Virtualization of hardware functions through software-defined architectures is compressing the traditional boundary between radiation-hardened and radiation-tolerant component categories. This convergence is enabling new procurement models while complicating established qualification frameworks.
Software-defined payload architectures are virtualizing hardware redundancy schemes that previously required discrete component duplication. Satellite operators deploying reconfigurable computing platforms are accepting higher single-event upset rates in exchange for real-time fault recovery through software. This trade-off is virtualizing the traditional hardened-versus-commercial segmentation that governed space electronics procurement for three decades.
REACH substance restrictions are forcing reformulation of packaging materials and solder alloys used in space-grade electronics. European component suppliers are redesigning thermal interface materials to eliminate restricted substances while maintaining outgassing specifications for vacuum operation. ESA contractors face 2026 compliance deadlines that are accelerating material qualification programs ahead of hardware development cycles.
Consolidated prime contractor procurement is displacing fragmented component sourcing across commercial constellation programs. SpaceX and Amazon Kuiper are mandating direct supplier relationships that bypass traditional distribution channels for radiation-hardened memory and power management devices. This concentration is most visible in United States LEO deployments, where prime contractors are internalizing supply chain risk management previously distributed across tiered vendor bases.
Radiation Hardened Electronics Market Segmentation
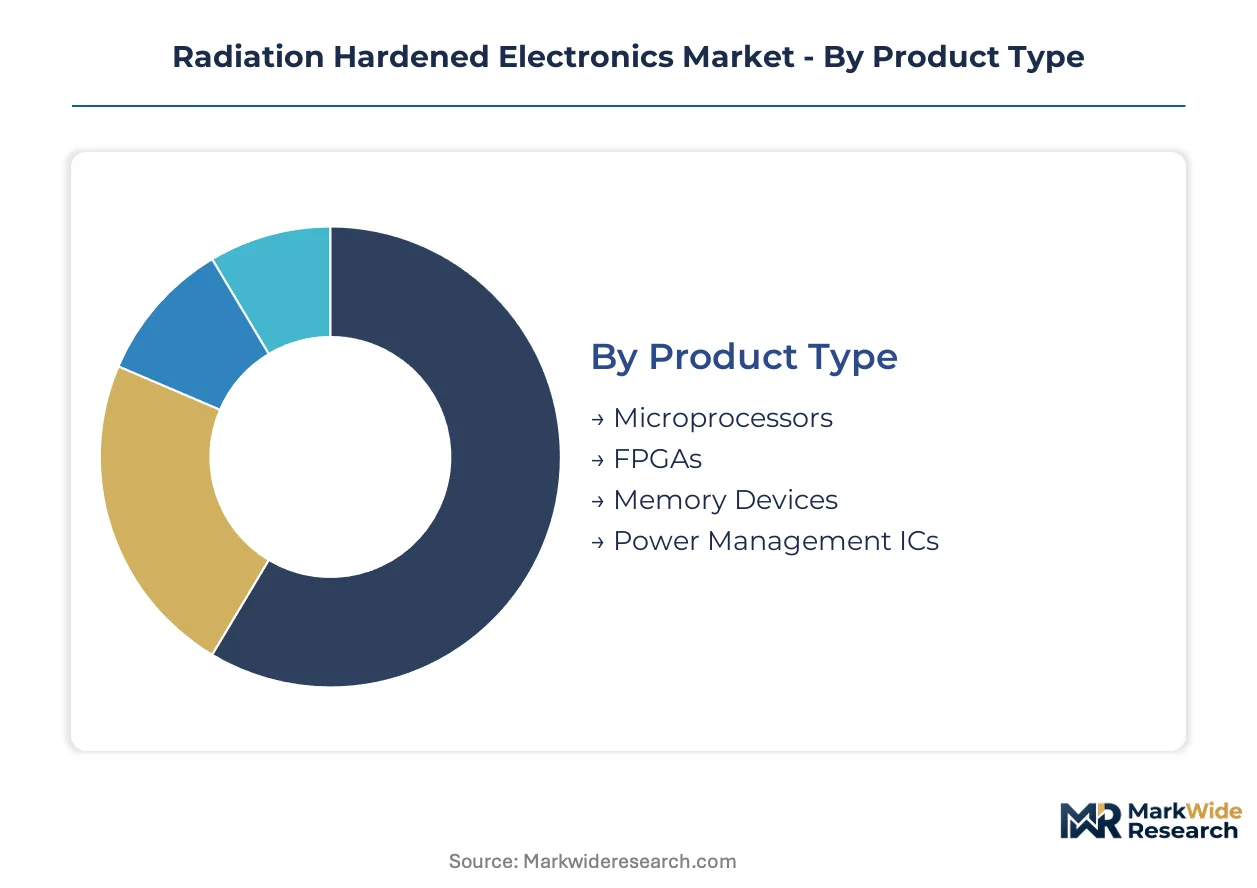
Radiation hardened electronics procurement patterns diverge sharply across mission profiles, with government deep-space programs demanding full qualification heritage while commercial constellation operators prioritize cost-optimized tolerance thresholds. Component suppliers must architect parallel product lines serving these incompatible specification regimes without fragmenting manufacturing scale.
Product Type:
Cost tier stratification in radiation hardened electronics separates reconfigurable computing platforms from commodity memory and power management functions, with qualification burden and unit economics diverging by an order of magnitude across the spectrum.
- FPGAs:Field-programmable gate arrays fabricated on silicon-on-insulator substrates enable mission-profile reconfiguration without hardware replacement. Satellite constellation operators in the United States procure these components at volumes previously reserved for NASA planetary missions, compressing supplier lead times from 36 months to 18-month qualification windows. NASA-STD-8739 tightening for deep-space total ionizing dose thresholds is forcing FPGA suppliers to redesign radiation-hardened product lines while maintaining commercial LEO cost structures.
- Memory Devices:Static RAM and non-volatile flash components engineered with error correction coding and hardened bit-cell architectures address single-event upset susceptibility in data storage functions. On-board storage requirements are multiplying with high-resolution sensing payloads across commercial Earth observation constellations, expanding addressable demand beyond traditional defense satellite programs. Memory devices are climbing the fastest share rankings as data-intensive missions proliferate.
- Microprocessors:Central processing units with radiation-hardened instruction set architectures execute flight software in spacecraft avionics and rover navigation systems.
- Power Management ICs:Voltage regulators and DC-DC converters with enhanced total dose tolerance maintain electrical stability across orbital thermal cycling extremes.
FPGAs hold installed capacity. Memory devices are rotating up the share rankings.
Application:
Application segmentation reflects mission-criticality gradients, with human-rated space exploration commanding full MIL-STD-883 qualification while medical imaging and commercial aerospace accept radiation-tolerant commercial derivatives.
- Space Exploration:Interplanetary probes, lunar surface systems, and deep-space observatories require components qualified to NASA-STD-8739 and ESA radiation hardness assurance standards with total ionizing dose thresholds exceeding 1 Mrad(Si). NASA Artemis program cislunar mission requirements are opening new qualification categories for extreme-temperature operation outside traditional geostationary specifications. Government end users in the United States command the largest contract values through Space Force modernization programs.
- Defense Systems:Strategic satellite communications, missile guidance electronics, and nuclear command-and-control infrastructure mandate MIL-STD-883 test method compliance with 24-36 month certification timelines. The U.S. Department of Defense sustains large-volume contracts through prime contractor relationships with BAE Systems and Honeywell International, creating barrier-to-entry conditions for non-domestic suppliers regardless of technical capability. Defense systems hold installed capacity. Space exploration is rotating up the share rankings.
- Aerospace:Commercial satellite constellations and launch vehicle avionics operate with radiation-tolerant commercial-off-the-shelf components in low-Earth orbit environments.
- Medical Imaging:Particle therapy equipment and radiology systems employ radiation-hardened detectors and signal processing electronics in high-radiation clinical environments.
Defense systems anchor qualification heritage. Space exploration is capturing incremental procurement volume.
Technology:
Technology segmentation tracks fault tolerance implementation depth, from process-level hardening through system-level redundancy architectures that virtualize reliability without specialized fabrication.
- Triple Modular Redundancy:Voting-based fault masking architectures deploy three parallel computation channels with majority voting logic to suppress single-event upset propagation without radiation-hardened process nodes. Satellite operators deploying reconfigurable computing platforms are accepting higher upset rates in exchange for real-time fault recovery through software, compressing margins for fully qualified component suppliers. Commercial aerospace procurement is broadening the customer base for TMR-based system architectures.
- Circuit Design:Hardened cell libraries and layout techniques including guard rings and enclosed geometry transistors mitigate charge collection at the semiconductor physics level. Foundry-level silicon-on-insulator fabrication advances are reducing unit costs for radiation-tolerant implementations while maintaining single-event upset immunity specifications. Circuit design holds installed capacity. Triple modular redundancy is rotating up the share rankings.
- CMOS Technology:Complementary metal-oxide-semiconductor processes on specialized substrates provide the foundation for digital logic functions in space-grade electronics.
- Versatile Low-Noise Amplifiers:RF front-end components with enhanced total dose tolerance maintain signal integrity in satellite communications and deep-space telemetry links.
Circuit design dominates wafer starts. Triple modular redundancy is gaining procurement traction.
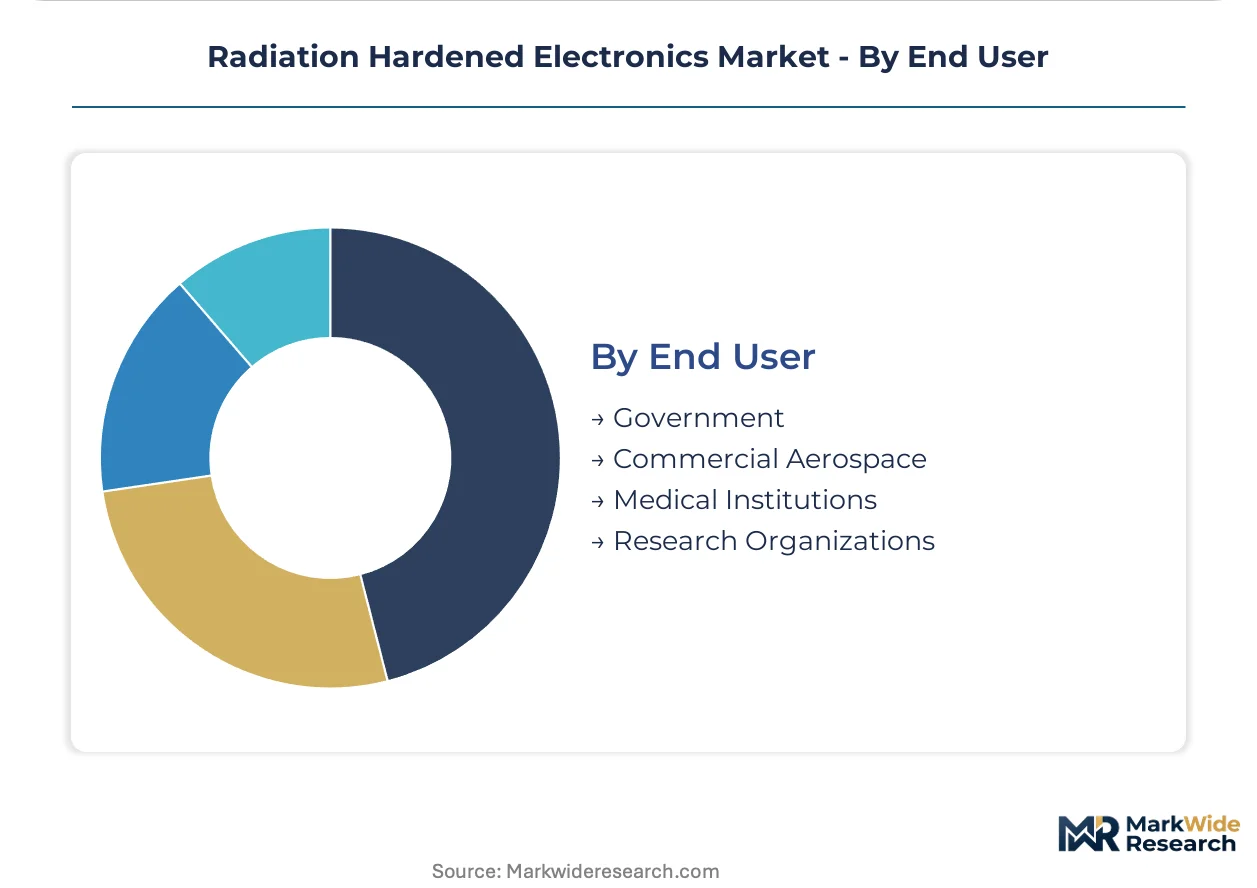
End User:
End user segmentation captures contracting mechanism divergence, with government procurement governed by federal acquisition regulations and commercial aerospace operating through consolidated prime-direct supplier relationships.
- Government:NASA, ESA, and national defense agencies procure radiation hardened electronics through cost-plus contracting vehicles with extensive qualification documentation requirements. The U.S. Department of Defense mandates MIL-STD-883 compliance for defense system electronics, excluding commercial space vendors from heritage supply chains regardless of technical capability. Government end users command the largest contract values through multi-year program-of-record commitments.
- Commercial Aerospace:SpaceX, Amazon Kuiper, and constellation operators are mandating direct supplier relationships that bypass traditional distribution channels for radiation-hardened memory and power management devices. This concentration is internalizing supply chain risk management previously distributed across tiered vendor bases, compressing qualification timelines from heritage multi-year cycles to 18-month windows. Commercial aerospace is expanding most quickly as a demand category.
- Medical Institutions:Hospital systems and research clinics procure radiation-hardened imaging detectors and particle therapy electronics through medical device procurement channels.
- Research Organizations:University laboratories and national science facilities acquire specialized components for experimental particle physics and space science instrumentation.
Government holds installed capacity. Commercial aerospace is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of radiation-hardened electronics concentrate in the United States, where Department of Defense procurement absorbs the majority of qualified component output. Import dependency for specialized substrates creates strategic vulnerability for European and Asian fabricators seeking to expand indigenous supply chains.
United States
Space Force modernization programs and NASA Artemis cislunar missions drive procurement volumes exceeding other national markets combined. MIL-STD-883 compliance mandates create barrier-to-entry conditions that sustain domestic supplier dominance. Colorado Springs and the broader Denver-Aurora corridor host concentrated prime contractor operations serving national security space architectures.
United Kingdom
BAE Systems anchors defense electronics manufacturing with heritage satellite and missile guidance programs. The UK Space Agency's National Space Strategy directs procurement toward qualified domestic suppliers for sovereign capability preservation. Harwell Space Cluster in Oxfordshire concentrates radiation effects testing infrastructure and specialized engineering talent.
Germany
Infineon Technologies maintains foundry-level silicon-on-insulator fabrication serving ESA qualification pathways. The country's national space regulator enforces harmonized radiation hardness assurance standards aligned with European procurement frameworks. Munich and the Bavarian aerospace corridor host integrated supply chains linking substrate suppliers to system integrators.
France
Thales Alenia Space and ArianeGroup sustain demand for deep-space qualified components through ESA planetary missions and launch vehicle avionics. CNES radiation test facilities at Toulouse provide heavy-ion accelerator access critical for component validation. The Aerospace Valley cluster spanning Toulouse and Bordeaux concentrates qualified supplier ecosystems.
Japan
Renesas Electronics and specialized substrate suppliers control epitaxial wafer flows critical for global radiation-hardened fabrication. METI industrial policy supports domestic qualification infrastructure to reduce import dependency for space-grade electronics. Tsukuba Science City hosts national laboratory radiation testing capabilities serving regional component developers.
Radiation Hardened Electronics Market Key Industry Players
On the supply side, the industry is bifurcated between heritage defense contractors with decades-long qualification relationships and commercial semiconductor fabricators adapting process nodes for radiation tolerance. Three archetypes dominate: integrated prime contractors with captive electronics divisions, specialized radiation-hardened component suppliers, and commercial foundries offering radiation-tolerant process variants. Consolidated prime contractor procurement is compressing distribution channels, while silicon-on-insulator process licensing is enabling new market entry from commercial semiconductor players.
Within the heritage defense contractor tier, BAE Systems and Northrop Grumman exemplify vertically integrated suppliers controlling qualification heritage through direct government relationships. Microchip Technology occupies a position bridging commercial semiconductor scale with radiation-hardened product line diversification. These three anchors represent divergent strategic postures: prime contractor integration versus component-level specialization versus portfolio breadth across memory and microcontroller segments.
| Leading Market Players |
|---|
| BAE Systems |
| Microchip Technology |
| Honeywell International |
| Texas Instruments |
| STMicroelectronics |
| Infineon Technologies |
| Renesas Electronics |
| Analog Devices |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
The Denver-Aurora logistics corridor channels specialized substrate shipments from Japanese and German suppliers to U.S. radiation-hardened fabricators, with freight cost volatility amplifying price spreads between MIL-STD-883 qualified components and radiation-tolerant commercial alternatives. This geographic concentration of inbound material flows reinforces pricing power for heritage defense contractors while compressing margins for commercial space entrants facing accelerated qualification timelines.
Pricing Analysis
Current-generation silicon-on-insulator FPGAs command substantial premiums over prior-generation epitaxial CMOS implementations, while next-generation extreme-temperature cislunar components are pre-priced at qualification-stage premiums before volume production ramps. Three-tier pricing structure across deep-space qualified, defense-grade, and commercial LEO-tolerant levels separates NASA-STD-8739 certified products from MIL-STD-883 compliant alternatives from radiation-tolerant COTS derivatives. Cost compression in commercial LEO tiers is intensifying because SpaceX and Amazon Kuiper are mandating direct supplier relationships that eliminate distribution markups. Commercial aerospace operators exhibit highest price sensitivity, accepting elevated single-event upset rates in exchange for unit cost reductions, while government deep-space programs remain least sensitive due to mission-criticality requirements.
Supply Chain Analysis
Export control regimes including U.S. ITAR restrictions and Japanese METI licensing requirements limit epitaxial wafer and SOI substrate flows to qualified defense contractors, constraining supply elasticity for radiation-hardened fabrication. Geographic supply concentration centers on Japan and Germany for specialized substrates, the United States for qualified component manufacturing, and France for heavy-ion validation infrastructure. Raw material dependencies include high-resistivity silicon wafers, specialized packaging ceramics, and radiation-tolerant solder alloys reformulated for REACH compliance. Single-source vulnerability runs through Japanese substrate suppliers controlling critical material flows. Distribution runs through consolidated prime-direct relationships that displace traditional tiered vendor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power in radiation-hardened electronics is concentrating through consolidated prime contractor procurement, with SpaceX and Amazon Kuiper internalizing supply chain risk management previously distributed across fragmented vendor bases.
For Market Incumbents: Pre-empt commercial space vendor encroachment by accelerating silicon-on-insulator process licensing to commercial foundries, creating captive supply of radiation-tolerant derivatives that capture volume without diluting full-qualification premium tiers. Lock in multi-year substrate offtake agreements with Japanese and German suppliers before capacity constraints tighten. Defense contracting heritage remains the priority lever for sustaining margin position against emerging entrants.
For New Entrants and Emerging Players: Build out radiation-tolerant FPGA product lines targeting commercial LEO constellations where 18-month qualification windows replace heritage multi-year cycles, exploiting the penetrable segment between fully hardened defense components and unqualified commercial alternatives. European Space Agency partnership pathways offer the most accessible geographic entry mechanism for qualified non-European suppliers. Go-to-market positioning should emphasize software-defined fault recovery architectures that virtualize hardware redundancy.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized radiation-hardened component suppliers with established qualification heritage but sub-scale commercial aerospace penetration, as silicon-on-insulator process maturation enables portfolio expansion without foundry capital intensity. Long-term viability over the coming decade hinges on capturing commercial constellation volume without sacrificing defense margin structures. The signal to watch is ESA radiation hardness assurance standard harmonization progress, which would signal opening procurement channels previously closed to non-European suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-on-Insulator Process Licensing | Commercial foundry partnerships reduce capital intensity for radiation-tolerant product line expansion. |
| Heavy-Ion Accelerator Capacity Expansion | Additional validation infrastructure alleviates 6-9 month queue delays constraining new component introduction. |
| Direct Prime Contractor Relationships | Bypassing distribution channels captures margin compression from consolidated SpaceX and Amazon Kuiper procurement. |
| REACH-Compliant Material Qualification | Reformulated packaging and solder alloys address 2026 ESA contractor compliance deadlines ahead of hardware cycles. |
| Software-Defined Payload Architecture Development | Virtualized fault recovery enables margin capture from satellite operators accepting higher upset rates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with satellite constellation procurement directors, radiation effects modeling engineers, defense program managers, and commercial space vendor business development leads. Secondary validation drew from NASA-STD-8739 qualification documentation, ESA radiation hardness assurance standards, MIL-STD-883 test method protocols, and Department of Defense program-of-record disclosures. Bottom-up component demand modeling and top-down aerospace electronics market sizing were triangulated to constrain forecast variance.
Calibration against historical qualification timeline compression and silicon-on-insulator process cost curves anchored projections across the analysis window. Segmentation dimensions modeled include product type, application mission profile, technology implementation depth, and end-user contracting mechanism, with additional granularity on total ionizing dose threshold specifications. CAGRs were derived from volume-weighted average growth across qualified and commercial-tolerant component categories, incorporating NASA Artemis program procurement schedules and Space Force modernization commitments as demand anchors.
Stress conditions across epitaxial wafer supply disruptions, qualification facility access constraints, and commercial FPGA substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SOI process maturation trajectories and ESA standard harmonization timelines. Material shifts in U.S. export control enforcement or Japanese substrate capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Camera Battery Charger Market
Electronic Components
GPIO Expanders Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Europe Water Cooled Capacitors Market
Electronic Components
Safety Relay Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
North America USB Retimer Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
SAW Filters Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
Amplifier Market
Electronic Components
Loudspeaker Market