
 Electronic Shelf Label Market | 2026-2036
Electronic Shelf Label Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Shelf Label Market Intelligence
EU Green Deal compliance thresholds are repositioning the cost-of-entry calculus for shelf-label vendors entering European retail. Hanshow leverages its manufacturing scale to anchor supply contracts with major continental supermarket operators. Pricer differentiates through proprietary infrared communication protocols that sustain real-time price synchronization across dense store footprints. VusionGroup navigates software-hardware integration demands by extending cloud-native platforms that control pricing logic at the network edge.
Electronic shelf labels are battery-powered display units mounted at retail shelf edges, typically employing electrophoretic e-paper screens readable at 180-degree viewing angles with power draw measured in microwatts per update cycle; their primary commercial purpose is to automate price changes and inventory signaling across distributed store networks. E-paper product types dominate installed volumes due to bistable image retention that eliminates refresh power between updates, while wireless technology infrastructure leads capital deployment as retailers prioritize centralized price orchestration over aisle-level cabling. LCD variants occupy select high-refresh environments such as promotional zones where color animation justifies higher energy budgets.
F-Gas Regulation phase-down timelines across Europe are pressuring retailers to abandon legacy fluorescent tube pricing displays, directly amplifying ESL retrofit demand in Germany, France, and Italy. CE marking requirements and Ecodesign standards enforced by national market surveillance authorities shape product certification pathways and electromagnetic compatibility testing burdens for hardware imports. Stakeholders must monitor how EU AI Act risk classifications apply to automated pricing algorithms that dynamically adjust shelf labels based on real-time demand signals.
Market Dynamics
EU F-Gas Regulation phase-down timelines are compressing replacement cycles for fluorescent tube pricing displays across continental grocery retail, forcing capital allocation toward e-paper infrastructure ahead of natural equipment end-of-life.
Growth Catalysts
- Ecodesign standards:CE marking requirements under EU Ecodesign directives mandate energy-efficient retail display retrofits, accelerating ESL deployment in German and French supermarket chains.
- Labor cost inflation:European grocery retailers face wage pressure that automates price-update workflows previously handled by floor staff across high-sku environments.
- Dynamic pricing mandates:Real-time demand signaling capabilities enable shelf-edge responsiveness to inventory velocity and competitor positioning.
Market Restraints
- Battery chemistry constraints:Lithium coin cell supply concentration in East Asian manufacturing creates input cost volatility and extended procurement lead times for label vendors.
- Infrastructure retrofit costs:Dense urban store footprints in Paris and Milan require aisle-level wireless gateway installation that disrupts trading operations during deployment.
- Fluorescent tube substitution:Legacy LED price displays offer lower capital outlay for smaller format retailers, delaying full ESL adoption in convenience segments.
Strategic Opportunities
- Italian underpenetration:Southern European grocery modernization lags northern counterparts, creating whitespace for infrastructure-first vendors targeting Coop and Conad networks.
- EU AI Act compliance:Automated pricing algorithm classification as limited-risk systems creates demand for audit-trail software integrated at the network edge.
- Pharmacy retail convergence:E-paper label adoption in European pharmacy chains combines inventory signaling with regulatory batch-tracking requirements.
Industry Challenges
- Electromagnetic compatibility certification:RED (Radio Equipment Directive) testing timelines extend product launch windows by four to six months for new wireless protocol implementations.
- Legacy POS integration:Middleware development for real-time synchronization with heterogeneous enterprise resource planning systems consumes disproportionate engineering resources.
- RF engineer scarcity:Specialized talent for dense-store wireless network design commands premium compensation in European technology labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Shelf Label Market |
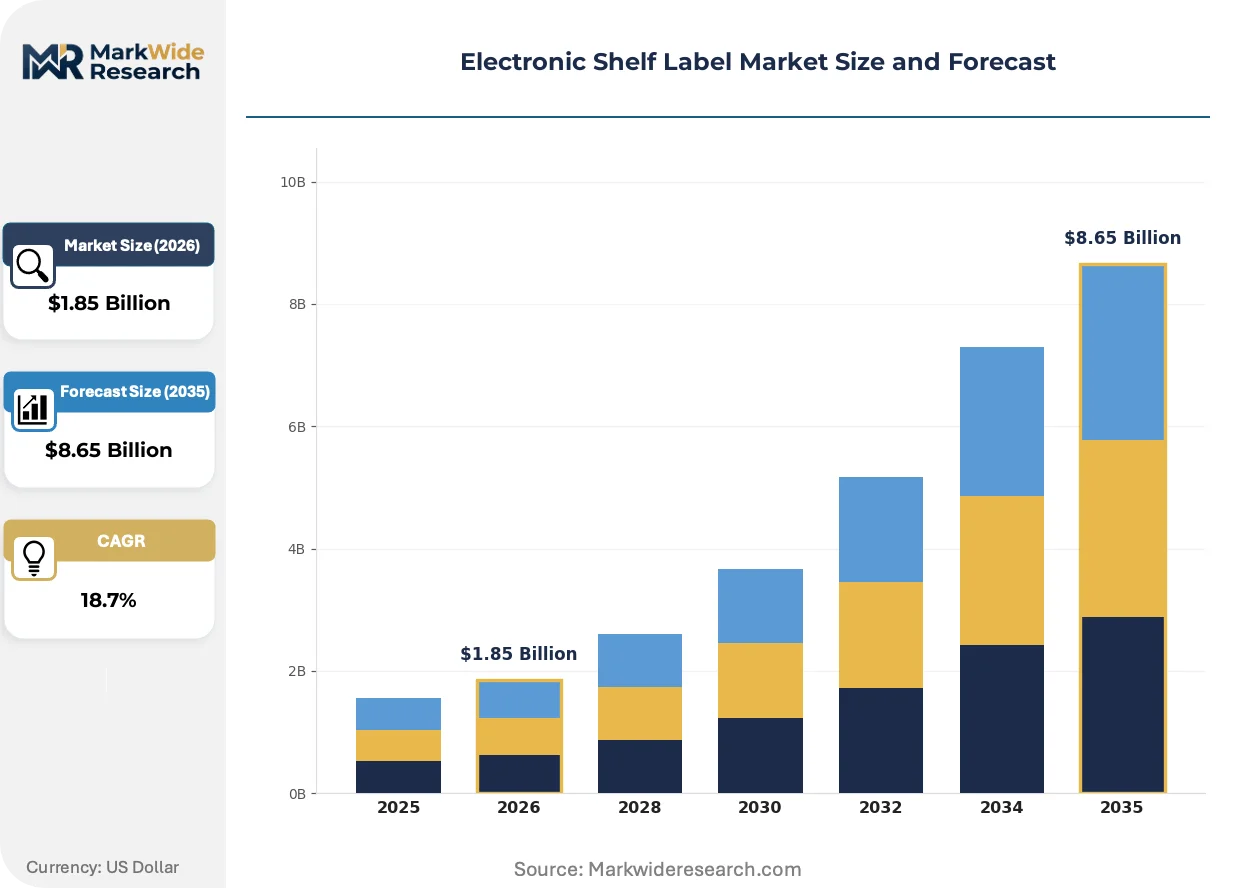
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, E-Paper, LED, OLED Technology: Wireless, Infrared, NFC, Bluetooth End User: Retail Stores, Supermarkets, Warehouses, Pharmacies Distribution Channel: Online, Offline, Direct Sales, Resellers |
| Companies Covered | Displaydata Ltd., Teraoka Seiko Co., Ltd., VusionGroup, Opticon, M2COMM, Pricer, Hanshow, PARTRON ESL, SOLUM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Shelf Label Market Strategic Shifts & Innovations
Three interconnected developments are compressing deployment timelines and expanding addressable use cases beyond core grocery applications into specialty retail and healthcare environments.
Tri-color e-paper displays capable of rendering red, black, and yellow pixels without backlighting are rewriting category expectations for promotional zone applications. European discount grocers including Aldi and Lidl are piloting these units in high-traffic aisle endcaps where color differentiation drives basket attachment. The technology is compressing the historical tradeoff between animation capability and energy autonomy that previously forced retailers toward LCD compromises.
F-Gas Regulation bans on hydrofluorocarbon refrigerants are indirectly amplifying ESL demand through synchronized store modernization programs. Retailers replacing cooling infrastructure simultaneously upgrade shelf-edge systems to minimize repeated customer disruption. German market surveillance authorities are enforcing stricter electromagnetic compatibility testing regimes that favor established vendors with documented RED compliance histories.
Consolidated procurement by European grocery buying alliances is compressing vendor evaluation cycles and favoring full-stack platform providers over component specialists. Retailers in the Netherlands and Belgium now require unified software-hardware-service contracts that bundle installation, cloud management, and predictive maintenance. This pattern concentrates contract awards among vendors with captive supply chains and direct service footprints across multiple member states.
Electronic Shelf Label Market Segmentation
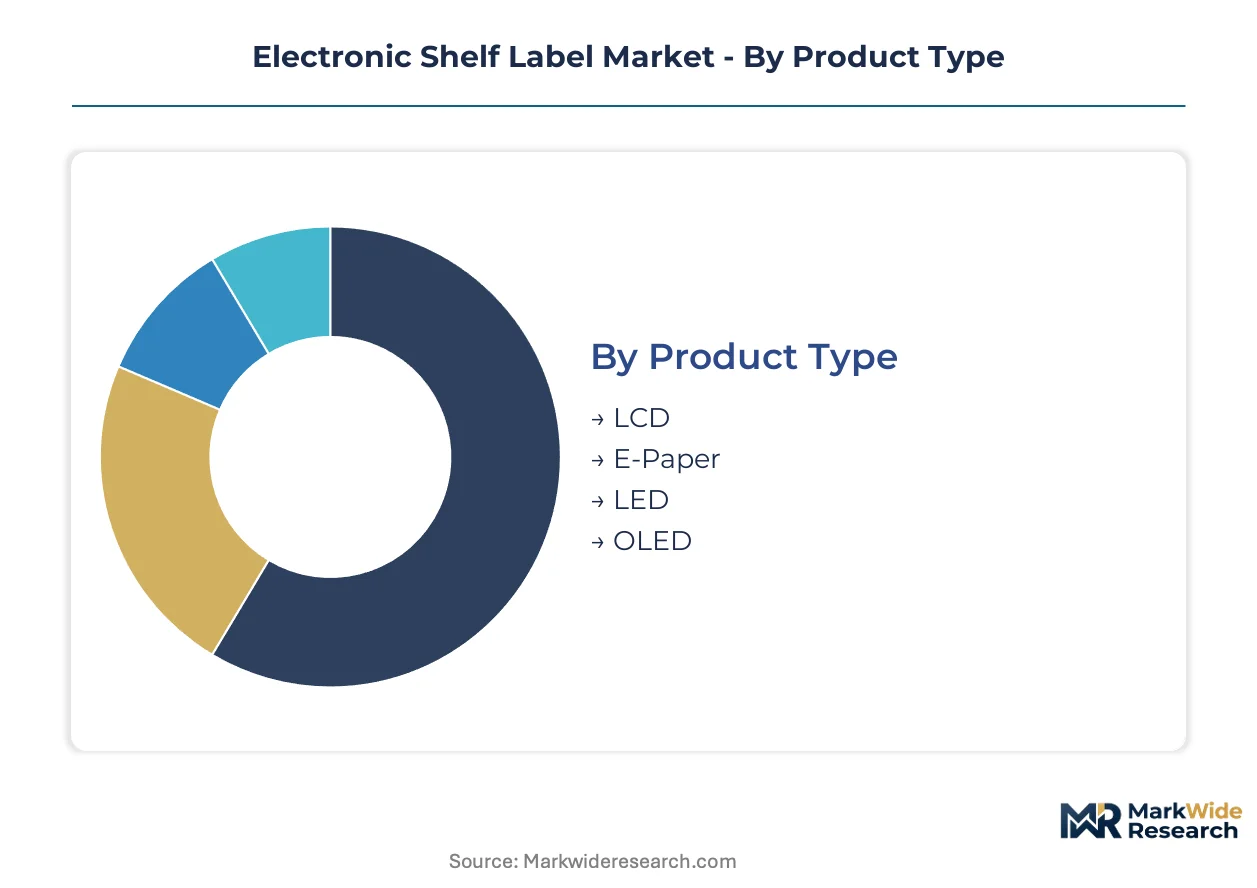
Electronic shelf label procurement patterns diverge sharply across display technologies, wireless infrastructure, and retail verticals. Capital allocation decisions hinge on balancing upfront hardware investment against operational labor savings and compliance-driven retrofit timelines.
Product Type:
Capital intensity peaks with display technologies requiring active backlighting or specialized substrate manufacturing, while passive bistable formats minimize ongoing power infrastructure.
- E-Paper:Electrophoretic displays retain images without power draw between updates, utilizing microwatt-scale energy per refresh cycle. German and French supermarket chains concentrate demand here as EU Ecodesign mandates eliminate fluorescent alternatives and F-Gas Regulation phase-downs compress replacement windows.
- LCD:Active-matrix liquid crystal displays deliver full-color animation and rapid refresh rates for promotional zones. Aldi and Lidl pilot these units in high-traffic endcaps where dynamic content justifies higher energy budgets and backlighting hardware costs.
- LED:Emissive diode arrays suit outdoor and high-ambient-light installations where luminance trumps energy efficiency.
- OLED:Organic electroluminescent layers enable flexible form factors and superior contrast ratios for premium retail environments.
E-Paper absorbs the bulk of installed capacity; LCD is expanding most quickly in promotional applications.
Technology:
Wireless protocol selection determines gateway density, electromagnetic certification burden, and real-time synchronization latency across dense store footprints.
- Wireless:Proprietary radio frequency mesh networks dominate large-format grocery deployments, enabling centralized price orchestration across thousands of nodes. Dutch and Belgian buying alliances now mandate unified cloud-native management platforms bundling RF infrastructure with predictive maintenance.
- Infrared:Directional optical communication protocols eliminate RF interference in electromagnetically congested urban stores. Pricer's proprietary infrared systems sustain sub-second price synchronization across dense Paris and Milan footprints where RED certification timelines extend product launches.
- NFC:Near-field coupling supports tap-to-interact consumer engagement and staff inventory verification workflows.
- Bluetooth:Standardized BLE stacks reduce component costs for smaller format retailers and enable smartphone-integrated experiences.
Wireless protocols anchor the majority of capital deployment; infrared is gaining share fastest in metropolitan electromagnetic-constrained environments.
End User:
Customer scale and SKU velocity dictate infrastructure amortization periods, with high-turnover grocery operations recovering hardware costs faster than specialty formats.
- Supermarkets:Hypermarket and full-line grocery operators achieve fastest payback through labor cost avoidance in high-sku environments. Coop and Conad networks in Italy represent underpenetrated whitespace as southern European modernization lags northern counterparts.
- Retail Stores:Specialty and department store formats prioritize aesthetic integration and flexible merchandising over pure operational efficiency.
- Warehouses:Industrial inventory signaling applications demand ruggedized enclosures and extended temperature operating ranges.
- Pharmacies:European pharmacy chains combine shelf-edge pricing with regulatory batch-tracking requirements, creating convergent demand for e-paper inventory signaling.
Supermarkets command the dominant share of installed base; pharmacy retail is climbing the fastest as regulatory compliance converges with operational automation.
Distribution Channel:
Channel structure reflects vendor scale economics and service footprint requirements, with consolidated procurement favoring direct relationships over intermediaries.
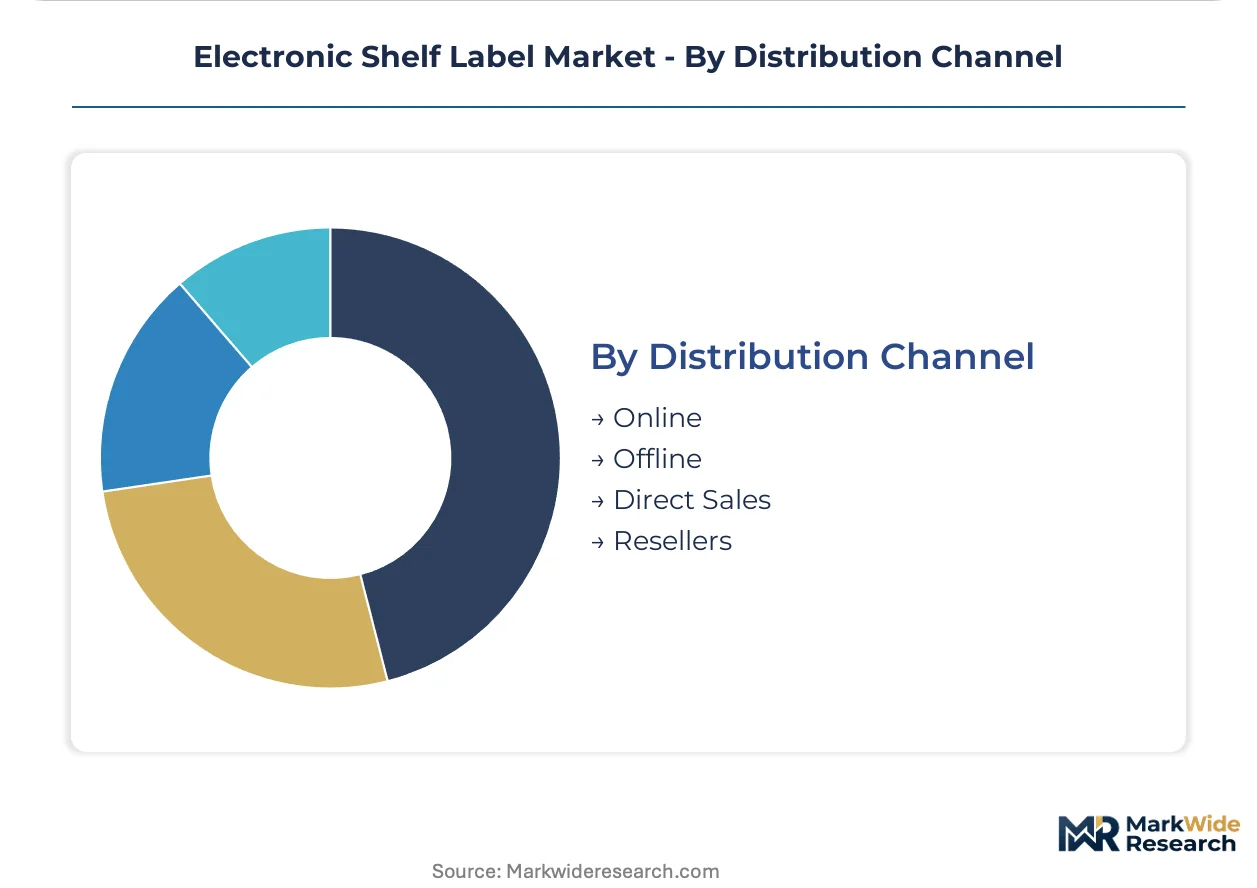
- Direct Sales:Full-stack platform providers with captive supply chains and multi-state service organizations capture alliance-level contracts. Hanshow leverages manufacturing scale to anchor supply agreements with major continental operators.
- Resellers:Regional system integrators address mid-market retailers lacking internal IT infrastructure for cloud platform management.
- Online:Digital procurement channels serve replacement label and accessory demand for existing installations.
- Offline:Traditional trade show and specification-led sales persist in pharmacy and specialty retail verticals with extended evaluation cycles.
Direct sales channels handle the majority of primary infrastructure deployment; reseller networks are expanding fastest in mid-market convenience and specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German supermarket chains concentrate the heaviest installed base of electronic shelf labels, while French and Italian retailers are compressing deployment timelines to meet regulatory deadlines. National energy efficiency mandates and labor cost pressures are reshaping procurement patterns across continental Europe.
Germany
Rewe and Edeka networks are accelerating ESL retrofits to satisfy F-Gas Regulation phase-down timelines for legacy fluorescent displays. CE marking requirements under EU Ecodesign directives enforce electromagnetic compatibility testing that favors vendors with established RED compliance documentation. Berlin and Hamburg retail clusters are witnessing synchronized infrastructure upgrades as buying alliances consolidate procurement around full-stack platform contracts.
France
Carrefour and Intermarché operators are deploying infrared-based ESL systems to sustain real-time price synchronization across dense Parisian store footprints. EU Green Deal waste reduction thresholds are eliminating paper label alternatives in hypermarket formats. Lyon and Marseille retail zones are experiencing aisle-level wireless gateway installation disruptions as urban electromagnetic congestion drives protocol selection toward optical communication.
United Kingdom
Tesco and Sainsbury's chains are automating price-update workflows to offset wage inflation in high-sku grocery environments. The UK's post-Brexit regulatory alignment with EU Ecodesign standards maintains energy efficiency retrofit pressure without direct F-Gas Regulation jurisdiction. London and Birmingham metropolitan stores are prioritizing cloud-native management platforms that bundle predictive maintenance with hardware deployment.
Italy
Coop and Conad networks represent underpenetrated whitespace as southern European modernization lags northern counterparts. National market surveillance authorities are beginning to enforce electromagnetic compatibility certification timelines that extend product launch windows. Milan and Rome retail corridors are emerging as pilot zones for infrastructure-first vendors targeting consolidated procurement opportunities.
Netherlands
Ahold Delhaize and Jumbo buying alliances are mandating unified software-hardware-service contracts that compress vendor evaluation cycles. Dutch Ecodesign enforcement agencies prioritize energy-efficient display retrofits in supermarket chains above convenience formats. Rotterdam and Amsterdam retail clusters are concentrating demand for tri-color e-paper displays in promotional zone applications.
Electronic Shelf Label Market Key Industry Players
East Asian producers anchor one tier of manufacturing scale; European specialists hold differentiated protocol positions. The vendor base organizes around three strategic archetypes: full-stack platform providers with captive supply chains, component specialists licensing wireless communication protocols, and regional system integrators addressing mid-market service gaps. Consolidated procurement by grocery buying alliances is compressing contract awards toward vendors with direct multi-state service footprints. Competitive positioning hinges on backward integration into display substrate manufacturing and cloud-native software development capacity.
Within the full-stack platform tier, Hanshow and VusionGroup exemplify vendors consolidating hardware production with edge-computing pricing logic. Pricer occupies a differentiated position through proprietary infrared communication systems purpose-built for electromagnetically congested urban retail environments. Teraoka Seiko Co., Ltd. represents the precision manufacturing archetype with electro-optical component heritage applicable to display substrate production.
| Leading Market Players |
|---|
| Displaydata Ltd. |
| Teraoka Seiko Co., Ltd. |
| VusionGroup |
| Opticon |
| M2COMM |
| Pricer |
| Hanshow |
| PARTRON ESL |
| SOLUM |
| Others |
Cost & Logistics Intelligence
Captive integration into e-paper display substrate manufacturing anchors both supply security and margin protection for dominant ESL vendors competing for European grocery alliance contracts. Hanshow and VusionGroup leverage in-house electrophoretic panel production to buffer lithium coin cell cost volatility while commanding premium positioning in bundled software-hardware-service procurement.
Pricing Analysis
Volume-margins split sharply between alliance-scale deployments and mid-market convenience retail. Project-based infrastructure contracts with full-stack platform providers command premium positioning through predictive maintenance bundling and RED certification guarantees. Price differentiation rests on electromagnetic compliance documentation depth and cloud-native management sophistication. Cost compression in standard-tier LCD alternatives is intensifying because legacy LED price displays offer lower capital outlay for smaller format retailers. Discount grocers exhibit highest price sensitivity; pharmacy chains with regulatory batch-tracking mandates show lowest.
Supply Chain Analysis
Freight cost exposure from East Asian lithium coin cell concentration shapes inventory positioning strategies for European ESL vendors. Manufacturing gravity centers on China for electrophoretic display substrates, South Korea for precision wireless components, and Taiwan for semiconductor controllers. Raw material dependencies include lithium carbonate for power cells, indium tin oxide for transparent electrodes, and specialized polymers for substrate encapsulation. Single-source vulnerability in East Asian battery chemistry creates procurement lead time risk. Distribution runs through direct vendor-to-retailer contracts for primary infrastructure, with reseller networks addressing replacement label demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium coin cell supply concentration in East Asian manufacturing props pricing power for vendors with captive battery procurement arrangements, constraining capacity expansion timelines for European market entrants.
For Market Incumbents: Lock in multi-year supply agreements with East Asian lithium cell producers before procurement lead times extend further. Deepen backward integration into electrophoretic display substrate manufacturing to defend margin position against emerging Chinese component specialists. Prioritize RED certification investment to exploit German market surveillance authority enforcement timelines that disadvantage new wireless protocol implementations. For New Entrants and Emerging Players: Cloud-native platform licensing offers the lowest capital route into European pharmacy retail convergence opportunities. Italian Coop and Conad networks represent the most penetrable whitespace as southern European modernization lags northern counterparts. Target infrared communication protocol specialization for dense Paris and Milan urban footprints where electromagnetic congestion blocks RF mesh deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisition by full-stack platform providers seeking wireless protocol differentiation or geographic service expansion. Five-to-ten year viability hinges on software-hardware integration depth rather than component manufacturing scale. Watch Italian national market surveillance authority electromagnetic compatibility enforcement acceleration as inflection indicator for infrastructure-first vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Display Substrates | Hanshow leverages captive e-paper manufacturing to anchor European alliance contracts against component specialists. |
| Infrared Protocol Specialization | Pricer's proprietary optical communication sustains sub-second synchronization in electromagnetically congested Paris retail corridors. |
| Cloud-Native Platform Expansion | VusionGroup extends edge-computing pricing logic to meet Dutch buying alliance unified contract requirements. |
| Pharmacy Vertical Penetration | European pharmacy chains combine e-paper labeling with EMA batch-tracking compliance for convergent demand capture. |
| Tri-Color E-Paper Pilot Programs | Aldi and Lidl discount grocers test red-black-yellow displays in high-traffic endcaps for promotional zone expansion. |
Research Approach
Independent corroboration across ESL vendor engineering directors, European grocery procurement leads, and RF network implementation specialists underwrites the qualitative findings. Primary interviews with supermarket chain IT infrastructure heads, pharmacy retail operations managers, and electromagnetic compatibility testing laboratory directors combined with secondary validation. Secondary sources include EU Ecodesign directive implementation reports, RED certification databases maintained by German market surveillance authorities, F-Gas Regulation phase-down compliance filings, and grocery alliance procurement disclosure documents. Bottom-up installation volume estimates triangulate against top-down retail modernization capital expenditure tracking.
Comparable-period anchoring to pre-pandemic retrofit baselines and post-F-Gas Regulation enforcement windows shaped the projection horizon calibration. Segmentation modeling spans display technology, wireless protocol infrastructure, retail vertical end-use, and geographic regulatory cluster dimensions. CAGRs derive from installed base growth rates cross-referenced against labor cost inflation elasticity and compliance-driven replacement cycle compression. Forecast inputs incorporate lithium coin cell supply lead time trajectories and EU AI Act automated pricing algorithm risk classification timelines.
Inputs from national market surveillance authority certification databases and grocery alliance procurement registers were available through the study window; gaps in real-time inventory signaling adoption rates in Italian retail networks introduce uncertainty bands. Forecasts reflect assumptions about F-Gas Regulation enforcement consistency and electromagnetic compatibility testing timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Docking Station Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Intel Motherboards Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Digital Isolator Market
Electronic Components
AC Adapter Market
Electronic Components
SAW Filters Market
Electronic Components
Dual Relay Board Market
Electronic Components
Lowpass Filters Market
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market
Electronic Components
Coin Battery Holder Market