
 Industrial Controllers Market | 2026-2036
Industrial Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Controllers Market Outlook
Semiconductor manufacturing is rebalancing the end-use mix as fabs expand capacity and demand nanometer-precision motion control. Siemens AG leverages its embedded systems portfolio to anchor European supply relationships. Rockwell Automation Inc. competes through FactoryTalk-integrated architectures in North American process industries. Schneider Electric SE differentiates via EcoStruxure platforms that bridge IT-OT convergence for energy-intensive users.
Industrial controllers are electromechanical or software-based systems that execute closed-loop regulation of process variables—temperature, pressure, position, flow—using PID algorithms, programmable logic, or adaptive control protocols with cycle times from milliseconds to microseconds. Their primary purpose is to maintain setpoint accuracy, synchronize multi-axis operations, and enable deterministic response in manufacturing and infrastructure environments. Programmable logic controllers occupy the largest installed base due to decades of standardization in discrete manufacturing, while industrial IoT controllers capture the fastest expansion as edge analytics and cloud-native architectures displace legacy SCADA hierarchies. Motion controllers concentrate margin pools in semiconductor and aerospace applications where servo-loop precision commands premium pricing.
The EU Cyber Resilience Act mandates security-by-design for connected industrial products, compelling controller vendors to embed hardware trust modules and secure boot capabilities. IEC 62443 and NIST SP 800-82 standards shape product development roadmaps by defining zone-conduit architectures and device-level security profiles. China's MIIT GB standards and SAMR certification requirements add compliance layers for market access in Asia-Pacific manufacturing hubs. Stakeholders must monitor convergence between functional safety standards and cybersecurity mandates as procurement specifications increasingly fuse SIL ratings with encryption requirements.
Market Dynamics
The EU Cyber Resilience Act and IEC 62443 standards are compressing vendor certification timelines while semiconductor fabs demand nanometer-precision motion control, creating a bifurcation between security-hardened platforms and legacy architectures.
Growth Catalysts
- EU Cyber Resilience Act:Mandates hardware trust modules and secure boot capabilities for connected industrial products, compelling controller vendors to redesign embedded architectures for European market access.
- Semiconductor fabrication expansion:New fab capacity in Germany and Taiwan requires multi-axis motion controllers with sub-micron positioning accuracy, pulling advanced servo-loop technology into high-volume deployment.
- IT-OT convergence protocols:Edge-native controllers with OPC UA and MQTT integration are capturing greenfield installations in energy-intensive process industries seeking unified data architectures.
Market Restraints
- Silicon supply concentration:Advanced microcontroller and FPGA fabrication concentrates in Taiwan and South Korea, exposing controller vendors to single-source disruption risk for critical processing components.
- IEC 62443 certification costs:Zone-conduit architecture validation and device-level security profiling add eighteen-to-twenty-four month qualification timelines, freezing smaller vendors from premium connected segments.
- Legacy PLC installed base:Decades of standardized ladder-logic programming and technician familiarity create switching friction against cloud-native controller architectures in discrete manufacturing.
Strategic Opportunities
- India's PLI scheme for automation:Production-linked incentives for advanced manufacturing are drawing controller vendors to establish local assembly and certification facilities for automotive and electronics end-uses.
- Predictive maintenance integration:Convergence of vibration sensing, edge analytics, and controller firmware creates bundled platform opportunities in rotating machinery and pump applications.
- Direct-to-fab distributor models:Semiconductor equipment makers are bypassing traditional industrial distributors, opening channel restructuring possibilities for precision motion controller specialists.
Industry Challenges
- Cyber-physical systems engineering:Vendors struggle to recruit firmware developers with simultaneous expertise in functional safety (IEC 61508) and cryptographic implementation, slowing secure product pipelines.
- Multi-standard certification stacking:Controllers targeting global deployment must simultaneously satisfy EU Cyber Resilience Act, China MIIT GB standards, and US NIST SP 800-82, fragmenting engineering resources.
- Legacy SCADA integration:Brownfield installations require protocol translation gateways and phased controller replacement, complicating margin structures for hybrid architecture deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Controllers Market |
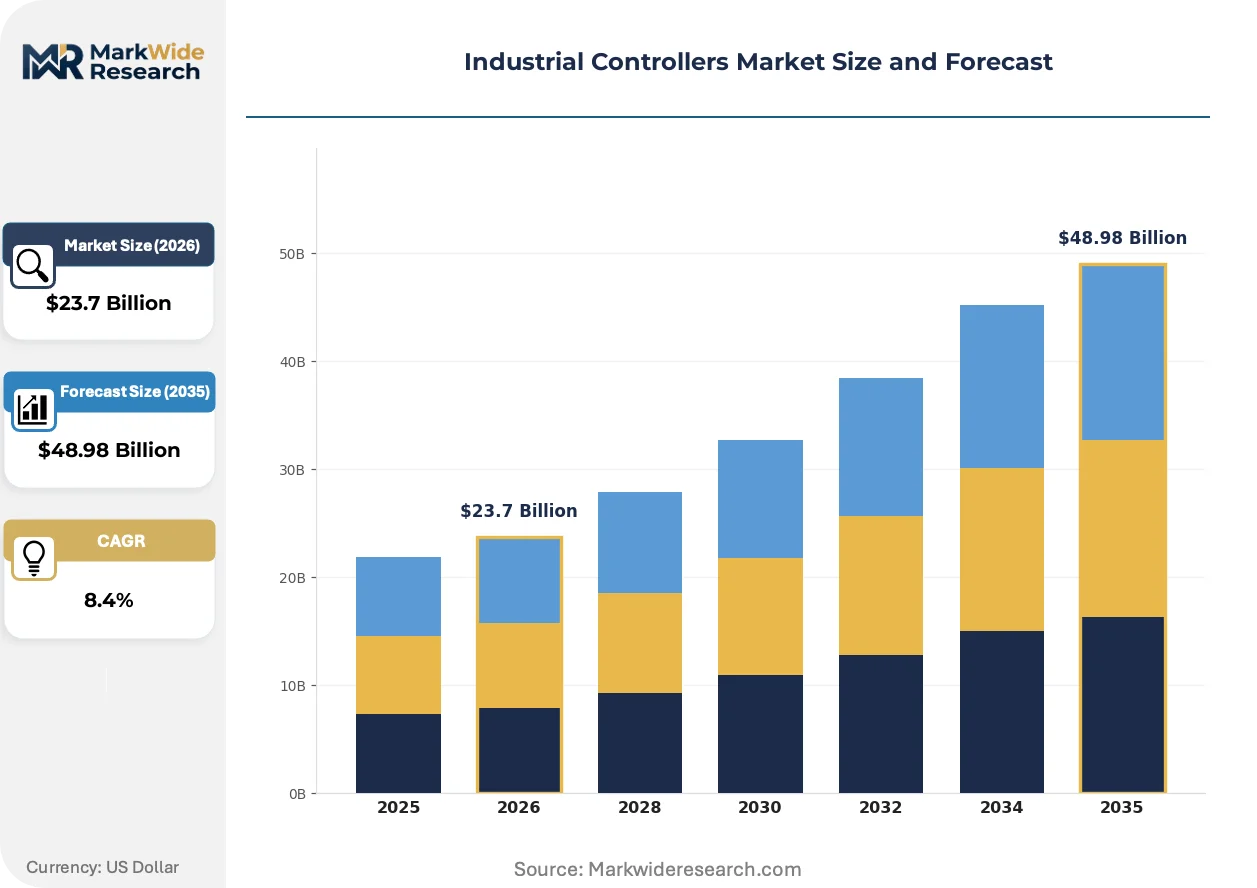
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Motion Controllers, Temperature Controllers, Pressure Controllers Technology: SCADA, DCS, Embedded Systems, Industrial IoT End User: Manufacturing, Energy, Automotive, Aerospace Application: Process Automation, Factory Automation, Home Automation, Building Management |
| Companies Covered | Siemens AG, ABB Ltd., Rockwell Automation Inc., Schneider Electric SE, Honeywell International Inc., Mitsubishi Electric Corporation, Emerson Electric Co., Omron Corporation, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Controllers Market Strategic Shifts
Controller architectures are compressing from hierarchical SCADA pyramids toward flat, edge-native networks where intelligence distributes across nodes rather than concentrating in central servers.
Time-sensitive networking over Ethernet is consolidating deterministic communication for motion control and safety-critical loops onto standard IEEE 802.1 infrastructure. Automotive battery gigafactories in Germany and Hungary are deploying TSN-enabled controllers to synchronize welding robotics with microsecond jitter tolerance. This consolidation collapses separate fieldbus layers into unified cabling, reducing installation complexity while demanding new switch hardware and configuration expertise.
REACH restrictions on per- and polyfluoroalkyl substances are forcing controller vendors to reformulate cable insulation and conformal coatings for European market compliance. The industrial consequence extends beyond materials substitution to supply chain requalification, as PFAS-free alternatives require validation against decades of field reliability data. Motion controller suppliers serving semiconductor cleanrooms face the steepest reformulation timelines, as particulate and chemical resistance specifications tolerate minimal deviation.
Equipment-as-a-service contracting is restructuring capital expenditure patterns in packaging and material handling, with controller vendors embedding usage telemetry to enable outcome-based billing. System integrators in the US Midwest are piloting subscription models where controller firmware updates and predictive analytics bundle into per-hour machine availability fees. This shift concentrates vendor risk on uptime performance while demanding cloud-connected controller architectures that legacy PLC platforms cannot satisfy without gateway overlays.
Industrial Controllers Market Segmentation
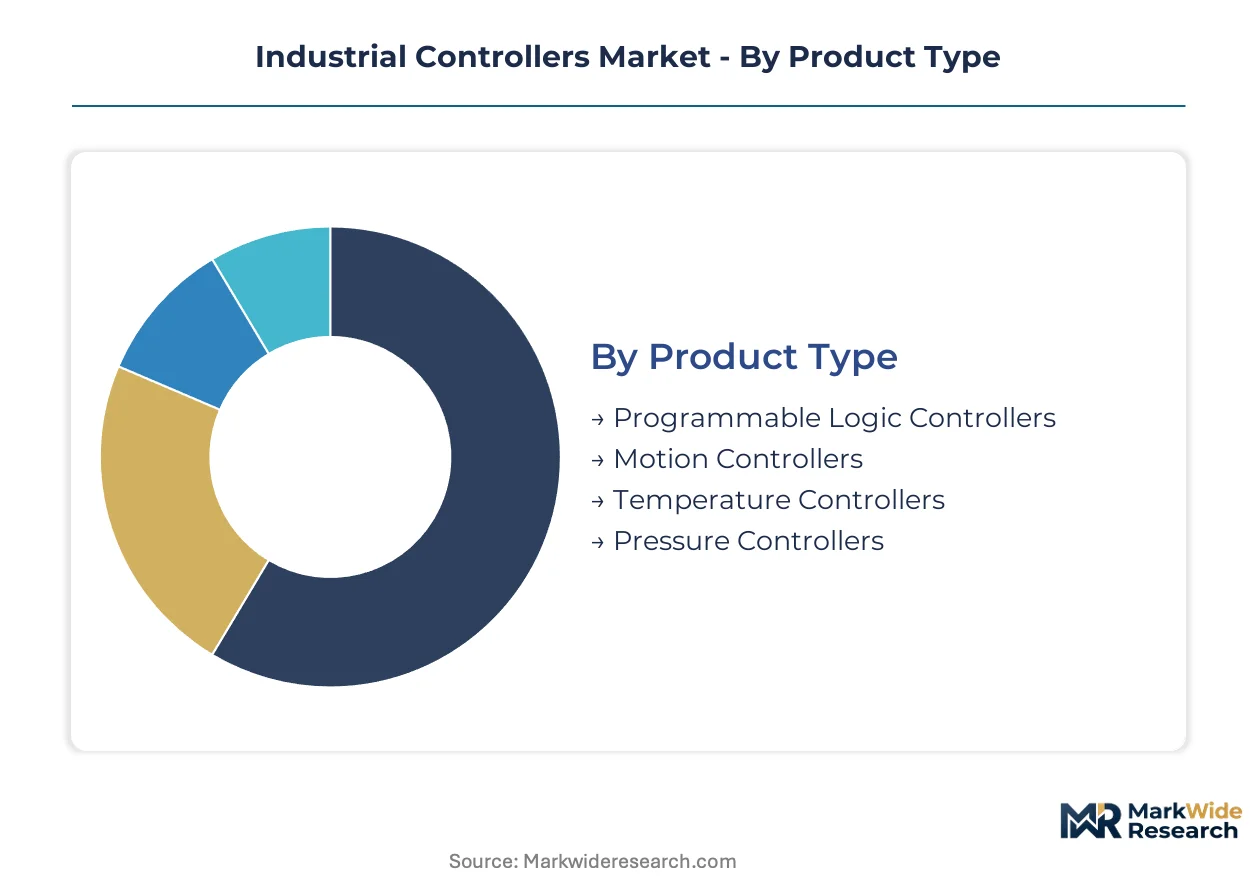
Controller architectures fragment across precision requirements, connectivity protocols, and safety certification tiers. Procurement specifications increasingly fuse functional performance with cybersecurity mandates, reshaping how vendors position product portfolios.
Product Type:
Precision specifications and loop-response characteristics define competitive positioning across electromechanical control categories.
- Programmable Logic Controllers:Ruggedized processors execute ladder-logic sequences with millisecond scan times for discrete manufacturing sequences. Decades of technician familiarity and standardized IEC 61131-3 programming cement installed base dominance in automotive assembly plants across Germany and the US.
- Motion Controllers:Multi-axis servo processors manage sub-micron positioning accuracy through adaptive PID algorithms with microsecond cycle times. Semiconductor fabrication facilities in Taiwan and Germany pull these into high-volume deployment as fab capacity expands.
- Temperature Controllers:Thermocouple-input devices regulate heat zones in extrusion and molding equipment through PID or fuzzy-logic algorithms.
- Pressure Controllers:Transducer-feedback systems maintain pneumatic or hydraulic setpoints in process industries and material handling equipment.
Programmable logic controllers lead on scale; motion controllers lead on momentum.
Technology:
Architecture choices determine integration depth with enterprise IT systems and cloud-native analytics platforms.
- Industrial IoT:Edge-native controllers embed MQTT and OPC UA protocols for direct cloud connectivity without SCADA intermediaries. Greenfield battery gigafactories in Hungary and Germany deploy these for unified data architectures spanning IT-OT boundaries.
- SCADA:Centralized supervisory systems aggregate remote terminal unit data through proprietary or open protocols. Legacy installations in North American oil and gas infrastructure create sustained replacement demand despite cloud-native displacement pressure.
- DCS:Distributed control architectures partition process loops across redundant controller nodes for continuous chemical and petrochemical operations.
- Embedded Systems:Dedicated microcontrollers integrate sensing, processing, and actuation in compact form factors for OEM equipment.
SCADA retains the largest installed footprint; industrial IoT climbs the fastest.
End User:
Sector-specific safety ratings and environmental tolerances drive certification requirements and margin structures.
- Manufacturing:Discrete automation demands high-speed I/O scanning and deterministic response for robotics and conveyor synchronization. Germany's industrial corridor around Stuttgart concentrates demand for precision motion control in automotive component production.
- Automotive:Battery gigafactories and electric drivetrain assembly require SIL-rated controllers with TSN-enabled synchronization. Hungary and Germany host the steepest capacity expansion for welding robotics with microsecond jitter tolerance.
- Energy:Power generation and grid infrastructure specify hardened controllers for wide temperature ranges and electromagnetic immunity.
- Aerospace:Flight-critical systems demand DO-178C software certification and extreme reliability margins for actuation control.
Manufacturing dominates volume; automotive gains share fastest.
Application:
Deployment context determines networking topology, environmental sealing, and regulatory compliance layers.
- Process Automation:Continuous-flow industries require DCS or PLC architectures with intrinsic safety barriers and hazardous area certification. Chemical complexes along the US Gulf Coast and Germany's Rhine corridor sustain demand for explosion-proof controller enclosures.
- Factory Automation:Discrete manufacturing deploys PLC and motion controller networks with deterministic Ethernet for robotics coordination. Taiwan's semiconductor equipment supply chain and Germany's automotive tier-one suppliers anchor procurement concentration.
- Building Management:HVAC and lighting control systems prioritize BACnet and Modbus interoperability over high-speed loop response.
- Home Automation:Residential controllers emphasize wireless connectivity and consumer-grade interfaces with minimal industrial ruggedization.
Process automation leads on margin contribution; factory automation leads on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping controller manufacturing footprints as vendors relocate final assembly to jurisdictions with shorter cybersecurity certification timelines. The EU Cyber Resilience Act imposes eighteen-to-twenty-four month validation cycles that favor established European incumbents, while Asian manufacturing hubs attract volume production through streamlined SAMR and MIIT pathways.
Germany
Stuttgart and Munich anchor Europe's densest automation corridor, where automotive tier-one suppliers and semiconductor equipment makers pull precision motion controllers into high-volume deployment. The EU Cyber Resilience Act and IEC 62443 standards compress vendor certification timelines, freezing smaller competitors from premium connected segments. Bavaria's battery gigafactories deploy TSN-enabled controllers for welding robotics synchronization.
United States
Process industries along the Gulf Coast sustain demand for explosion-proof PLC enclosures in chemical and petrochemical complexes. NIST SP 800-82 shapes zone-conduit architectures for critical infrastructure, while the Inflation Reduction Act channels investment toward domestic semiconductor fabrication. Arizona and Texas fabs require multi-axis motion controllers with sub-micron positioning accuracy.
China
MIIT GB standards and SAMR certification requirements add compliance layers for market access, with Yangtze River Delta and Pearl River Delta manufacturing clusters driving volume consumption. Domestic battery gigafactories and EV assembly plants deploy edge-native controllers with OPC UA integration. Shanghai and Shenzhen concentrate demand for IT-OT convergence platforms.
Japan
Meti industrial policy prioritizes autonomous manufacturing and carbon neutrality, pulling advanced servo-loop technology into automotive and electronics applications. Nagoya's automotive corridor and Tokyo's semiconductor equipment supply chain anchor procurement concentration. JIS standards govern functional safety integration in robotics-intensive production environments.
India
The PLI scheme for advanced manufacturing draws controller vendors to establish local assembly facilities for automotive and electronics end-uses. Maharashtra and Gujarat host the steepest capacity expansion as contract manufacturers seek to bypass import duty structures. BIS certification requirements shape product localization strategies for industrial automation deployments.
Industrial Controllers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium motion control concentrating around semiconductor-qualified vendors while volume PLC supply fragments across regional system integrators. The vendor base organizes into three archetypes: diversified industrial conglomerates with embedded systems portfolios, pure-play automation specialists with vertical software integration, and Asian electronics conglomerates leveraging captive semiconductor supply. Consolidation pressure intensifies through strategic partnerships for TSN switch hardware and capacity expansion in European cybersecurity-certified manufacturing.
Among diversified industrial conglomerates, Siemens AG and ABB Ltd. exemplify the integrated-architecture approach, anchoring European supply relationships through combined hardware-software portfolios. Rockwell Automation Inc. occupies a position within the North American process automation tier, representing FactoryTalk-integrated positioning. These three entities sit within distinct geographic anchor points—German, Swiss-Swedish, and American—each reflecting regional procurement concentration and certification pathway specialization.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Emerson Electric Co. |
| Omron Corporation |
| Yokogawa Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Cyber Resilience Act certification mandates are compressing procurement timelines for connected controllers, forcing vendors to absorb eighteen-to-twenty-four month validation costs into premium-tier pricing while legacy architectures face margin erosion from security-hardened competition.
Pricing Analysis
Distributor margin structures in industrial automation typically capture fifteen-to-twenty-five percent for PLC and motion controller lines, though direct-to-fab semiconductor equipment makers are extracting volume discounts that compress channel economics. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62443-certified platforms with hardware trust modules from uncertified legacy stock and white-label alternatives. Pricing pressure stems from Taiwan and South Korea silicon concentration exposing buyers to single-source disruption premiums. Automotive tier-one suppliers in Germany exhibit highest price sensitivity due to capital-intensive battery gigafactory rollouts, while aerospace contractors tolerate premium positioning for DO-178C certified motion control.
Supply Chain Analysis
Controller refurbishment and remanufacturing flows are expanding as REACH PFAS restrictions force cable and coating reformulation, creating aftermarket value recovery for pre-restriction inventory. Advanced microcontroller and FPGA fabrication concentrates in Taiwan, South Korea, and the United States, drawing controller vendors into captive supply relationships with TSMC and Samsung Foundry. Raw material dependencies span silicon wafers, rare-earth magnets for servo motors, and halogen-free flame retardants for PCB substrates. Single-source vulnerability in EUV-grade semiconductor equipment exposes motion controller specialists to allocation risk. Distribution runs through authorized industrial distributors in Europe and direct OEM relationships in Asian manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Industrial Controllers Market reads as a late-cycle quality story where EU Cyber Resilience Act compliance is filtering procurement toward security-hardened platforms with embedded hardware trust modules and certified secure boot architectures.
For Market Incumbents: Cement European supply relationships through IEC 62443 zone-conduit certification investments that freeze smaller competitors from premium connected segments. Deepen backward integration into FPGA and secure microcontroller supply through foundry partnerships in Taiwan and South Korea, reducing single-source exposure while capturing margin from security-hardened controller premiums. Channel control through authorized distributor networks in Germany's Stuttgart-Munich corridor defends against direct-to-fab disintermediation. For New Entrants and Emerging Players: Mid-sized automotive component suppliers in India's Maharashtra and Gujarat PLI zones present underserved buyer archetypes seeking localized assembly with BIS certification bypassing import duty structures. White-space targets include predictive maintenance-integrated controller bundles for rotating machinery and TSN-enabled edge-native platforms for Hungarian battery gigafactories. Go-to-market through system integrator partnerships in US Midwest packaging automation pilots enables outcome-based contracting without legacy PLC switching friction. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor-qualified motion controller specialists holding sub-micron positioning IP and cleanroom-proven reliability records. Long-term viability over the next decade hinges on IT-OT convergence platform architecture and cybersecurity certification stacking capability across EU, China, and US regulatory frameworks. Watch for IEC 62443 certification timeline compression as early signal of vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| TSN Switch Hardware Partnership | Automotive battery gigafactories in Hungary and Germany demand microsecond jitter tolerance for welding robotics synchronization. |
| Hardware Trust Module Integration | EU Cyber Resilience Act mandates secure boot capabilities that differentiate premium controller tiers from legacy stock. |
| India Local Assembly Expansion | PLI scheme incentives in Maharashtra and Gujarat attract controller vendors seeking automotive and electronics end-use access. |
| Predictive Maintenance Platform Bundle | Vibration sensing and edge analytics convergence creates recurring revenue opportunities in pump and rotating machinery applications. |
| Direct-to-Fab Channel Restructuring | Semiconductor equipment makers bypassing traditional distributors opens margin capture for precision motion controller specialists. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and cybersecurity compliance officers with secondary validation through SEC 10-K filings, IEC certification registries, and customs trade data. Bottom-up controller shipment estimates by product type and technology tier triangulated against top-down industrial automation capex surveys across Germany, United States, China, Japan, and India.
Segment-weighting approaches distributed value and volume across programmable logic controllers, motion controllers, industrial IoT architectures, and SCADA systems, with end-use allocation spanning manufacturing, automotive, energy, and aerospace applications. CAGRs derived from regression analysis of historical adoption curves and forward projection of fab capacity expansion, IT-OT convergence penetration, and regulatory compliance phase-in schedules. Forecast inputs incorporated semiconductor equipment capital expenditure patterns and battery gigafactory deployment pipelines.
Underlying measurement precision varies by segment; industrial IoT and motion controller categories carry tighter precision than legacy SCADA replacement estimates given faster technology turnover. Forecasts reflect assumptions around EU Cyber Resilience Act enforcement timing, Taiwan semiconductor supply stability, and REACH PFAS restriction implementation. Practitioners should monitor IEC 62443 certification backlog lengths, foundry allocation announcements, and India's PLI scheme uptake rates for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Window Sensors Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Lidar Ceilometer Market