
 Breadboards Market | 2026-2036
Breadboards Market Size, Share, and Industry Trends Forecast 2026-2036
Breadboards Market Analytics
Surface-mount technology migration is fragmenting the breadboard ecosystem into solderless prototyping, printed circuit board rapid fabrication, and hybrid development kits. Nippon Mektron leverages its precision substrate expertise to anchor high-reliability prototyping supply chains in East Asia. Zhen Ding Technology competes through vertical control over laminate and copper-clad materials, sustaining cost advantages in volume production. TTM Technologies specializes in quick-turn PCB services that bypass traditional breadboard stages for professional engineers.
A breadboard is a reusable solderless construction base for temporary electronic circuit prototypes, typically featuring a perforated plastic housing with embedded metal spring clips arranged in interconnected rows at 2.54 mm pitch spacing. Its primary purpose is to enable rapid iteration of analog and digital circuit designs without permanent soldering or PCB fabrication delays. Solderless breadboards retain dominance in educational settings where reusability and low error cost matter most, while printed circuit board segments capture margin pools from professionals seeking faster transition to manufacturable layouts. Plastic substrates lead by unit volume due to cost and moldability, though metal variants gain traction in high-frequency prototyping where shielding and thermal dissipation become critical.
The European Chemicals Agency enforces REACH substance restrictions on phthalates and flame retardants used in plastic breadboard housings, directly constraining material sourcing for suppliers serving EU educational institutions. China's State Administration for Market Regulation applies GB standards for electrical insulation and fire safety that shape export certification requirements for domestic manufacturers. ISO 9001 quality management systems and IEC 61131 programmable controller standards further influence procurement specifications in industrial training environments. Stakeholders must monitor how semiconductor packaging miniaturization below 1.0 mm pitch gradually erodes compatibility with conventional spring-clip breadboard architectures.
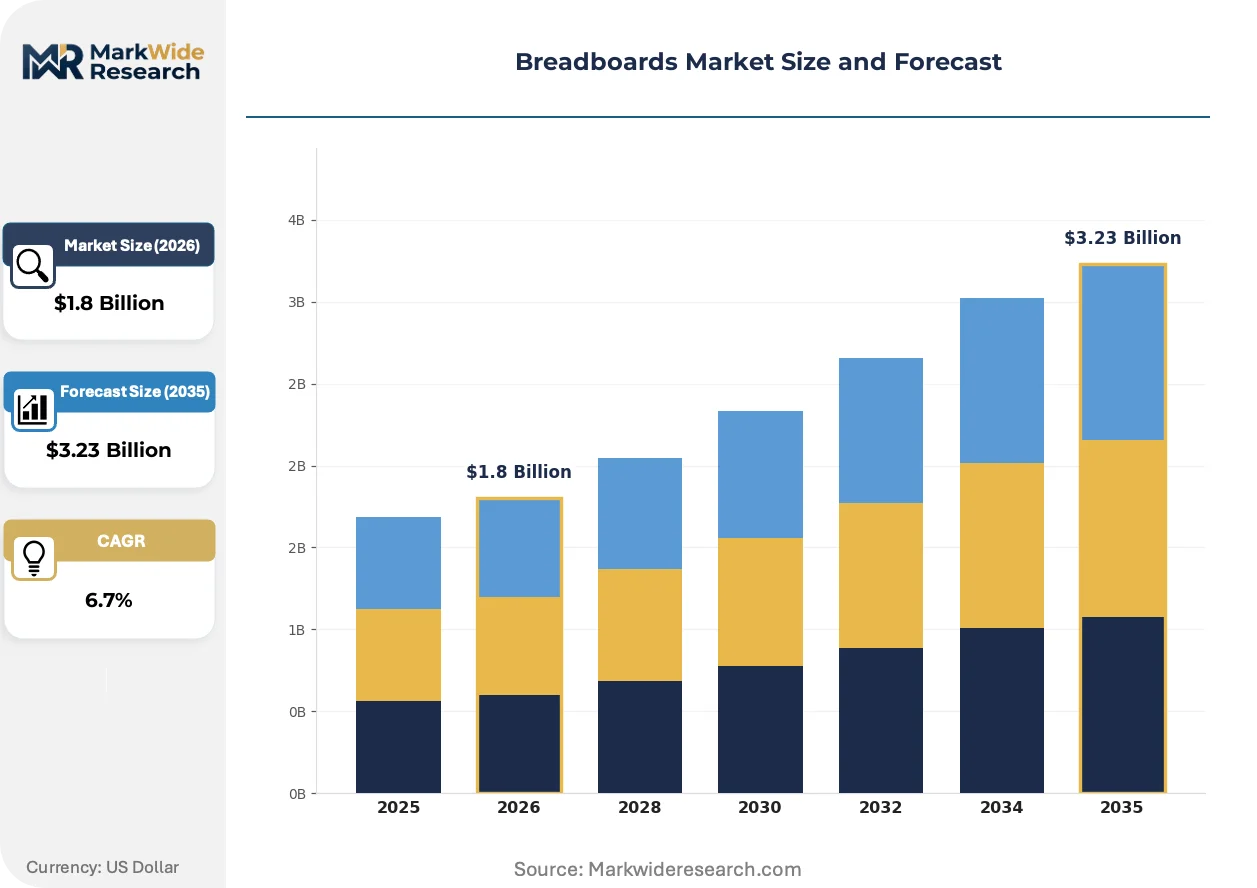
Market Dynamics
Semiconductor packaging miniaturization below 1.0 mm pitch is compressing compatibility with conventional spring-clip breadboard architectures, forcing suppliers to recalibrate prototyping platform specifications or cede professional engineering segments to quick-turn PCB fabricators.
Growth Catalysts
- University engineering curriculum expansion:Technical institutions across Germany, Japan, and the United States are embedding hands-on electronics labs into undergraduate programs. This institutional procurement wave sustains volume demand for solderless prototyping platforms.
- REACH substance compliance:The European Chemicals Agency's restrictions on phthalates and flame retardants are filtering non-compliant suppliers from EU educational channels. Certified manufacturers capture protected market share within European institutional procurement.
- Guangdong-Shenzhen manufacturing corridor concentration:PCB prototyping services and component distribution hubs cluster in this southern Chinese zone. Proximity between breadboard production and downstream electronics manufacturing reduces logistics friction for export-oriented suppliers.
Market Restraints
- Copper-clad laminate input volatility:Zhen Ding Technology's vertical control over laminate materials creates supply concentration risk for independent breadboard assemblers lacking backward integration into substrate production.
- Surface-mount pitch incompatibility:Conventional 2.54 mm spring-clip spacing cannot accommodate modern semiconductor packages below 1.0 mm pitch. This technical ceiling excludes breadboards from professional prototyping workflows for advanced integrated circuits.
- Quick-turn PCB substitution:TTM Technologies and similar rapid fabrication services offer 24-hour turnaround on functional prototypes. Professional engineers bypass breadboard stages entirely when time-to-test compression outweighs reusability value.
Strategic Opportunities
- Hybrid development kit convergence:Combining solderless breadboard modularity with surface-mount adapter boards bridges the pitch-compatibility gap. Early movers capture engineers transitioning between educational and professional prototyping environments.
- Metal substrate high-frequency prototyping:Shielding and thermal dissipation requirements in radio-frequency circuit development favor metal-housed breadboards. This premium segment commands pricing separation from commodity plastic variants.
- Industrial training certification alignment:ISO 9001 quality management systems and IEC 61131 programmable controller standards shape procurement specifications. Suppliers embedding these certifications into product documentation access industrial automation training contracts.
Industry Challenges
- Material certification timeline compression:GB standards from China's State Administration for Market Regulation and REACH compliance in Europe require parallel testing protocols. Suppliers serving both markets face duplicated certification costs and extended product launch cycles.
- Legacy spring-clip manufacturing equipment stranded:Conventional metal stamping and plastic injection tooling optimized for 2.54 mm pitch architectures cannot retool economically for sub-millimeter adapter production. Capital replacement requirements strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breadboards Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Mini, Solderless, Printed Circuit Board Material: Plastic, Wood, Metal, Composite Application: Prototyping, Education, DIY Projects, Product Development End User: Students, Engineers, Hobbyists, Designers |
| Companies Covered | Nippon Mektron, Compeq Manufacturing, Zhen Ding Technology, Suzhou Dongshan Precision Manufacturing, Tripod Technology, Unimicron Technology, AT&S, Ibiden, TTM Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breadboards Market Evolving Landscape
Prototyping platform architecture is fragmenting across three functional layers: reusable solderless bases, rapid PCB fabrication, and integrated development kits. This functional specialization is compressing the addressable market for any single-format supplier.
Modular surface-mount adapter systems is hybridizing breadboard utility with modern semiconductor packaging requirements. University labs and hobbyist segments adopt these hybrid platforms fastest, sustaining breadboard relevance while professional engineers migrate to direct PCB prototyping. The technology is hybridizing two previously separate prototyping workflows into a single educational-to-professional continuum.
REACH substance restrictions enforced by the European Chemicals Agency are reshaping material sourcing for plastic breadboard housings. Phthalate and flame retardant limitations eliminate certain Asian substrate suppliers from EU certification pathways. Educational institutions in Germany, France, and the Netherlands now require supplier documentation proving compliance before procurement authorization.
Buyer concentration around institutional procurement offices is consolidating purchasing authority previously distributed across individual academic departments. German technical universities and Japanese national colleges have centralized electronics lab equipment acquisition through dedicated procurement divisions. This channel consolidation favors suppliers with established educational distribution relationships and documented regulatory compliance over direct-to-consumer brands.
Breadboards Market Segmentation
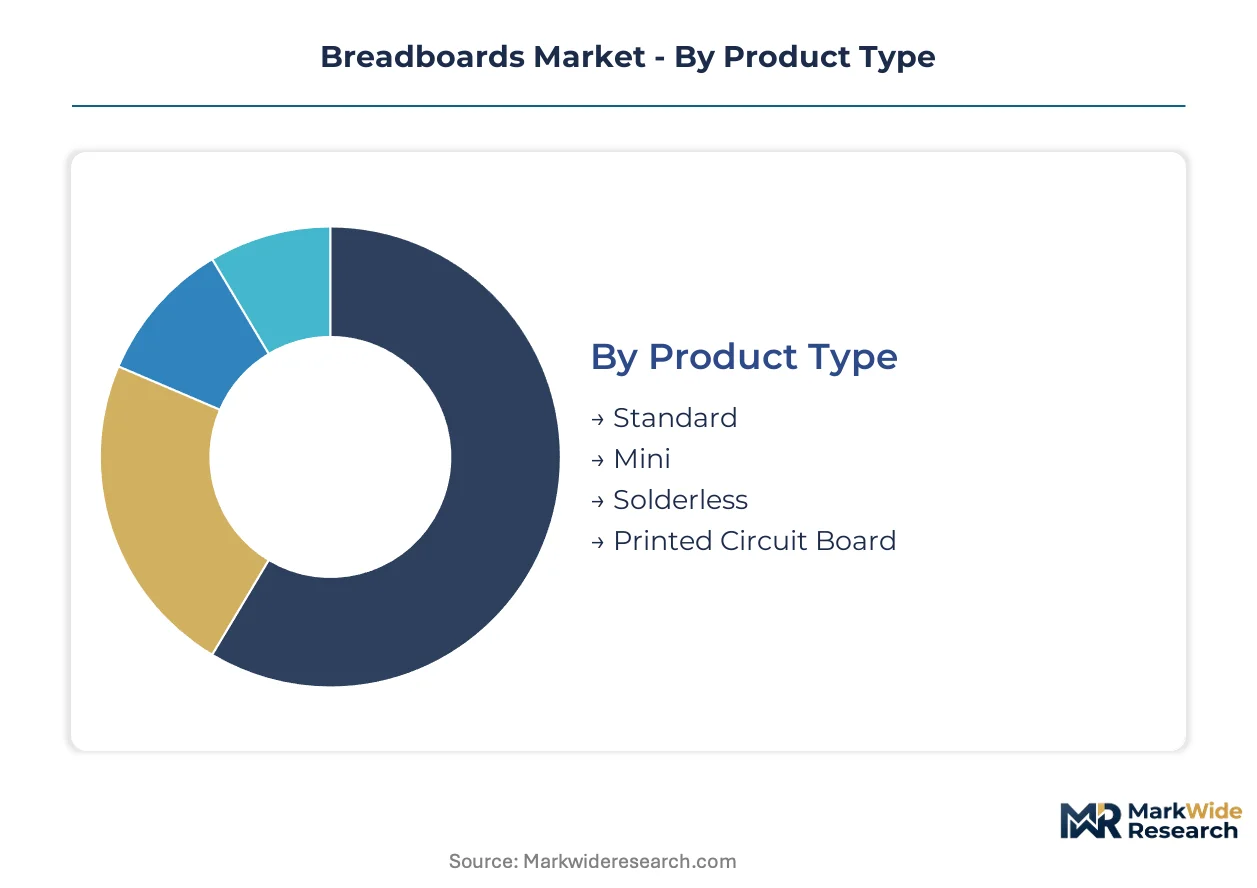
Breadboard segmentation reveals how prototyping workflows fragment across user sophistication levels and performance requirements. Product architecture, substrate material, application intensity, and end-user technical capability each create distinct procurement channels with separate pricing logic and certification demands.
Product Type:
The use-case spectrum spans disposable classroom units to precision platforms for RF circuit validation, with each format optimizing for reusability, density, or transition speed to manufactured layouts.
- Solderless:Spring-clip architectures at 2.54 mm pitch enable rapid iteration without soldering equipment. University labs across Germany and Japan favor these for undergraduate electronics courses where error recovery speed outweighs signal integrity concerns.
- Printed Circuit Board:Rapid-fabrication services bypass reusable breadboard stages entirely, delivering functional prototypes within 24-hour turnaround. Professional engineers in China's Guangdong-Shenzhen corridor select this route when time-to-test compression dominates project economics.
- Standard:Full-size perforated housings with 830+ tie points accommodate complex analog and digital designs. Institutional procurement offices specify these for centralized electronics lab equipment.
- Mini:Compact 170-400 tie-point variants suit portable field testing and constrained workspace environments. Hobbyist channels and mobile repair technicians drive volume here.
The dominant share belongs to solderless platforms, while printed circuit board rapid fabrication is closing the gap fastest among professional engineering segments.
Material:
Cost tier stratification separates commodity substrates from precision-engineered alternatives where thermal or electromagnetic performance commands premium positioning.
- Plastic:ABS and polycarbonate housings dominate unit economics through injection molding scalability. ECHA REACH restrictions on phthalates and flame retardants constrain EU-serving suppliers to certified substrate formulations.
- Metal:Aluminum and steel enclosures provide electromagnetic shielding and thermal dissipation for RF prototyping. Aerospace and telecommunications training programs specify these for high-frequency circuit validation.
- Composite:Glass-reinforced polymer blends balance mechanical rigidity with reduced weight. Specialty industrial automation training contracts favor these for durability under repeated component insertion cycles.
- Wood:Vintage aesthetic variants serve boutique educational settings and maker-space installations where tactile experience influences procurement decisions.
Plastic retains volume leadership through moldability advantages, though metal substrates are expanding share fastest in professional training environments.
Application:
Customer type concentration shapes demand intensity, with institutional buyers prioritizing durability and certification documentation against individual purchasers emphasizing unit cost.
- Education:Curriculum-integrated electronics labs require documented REACH compliance and ISO 9001 quality management certification. German technical universities and Japanese national colleges centralize procurement through dedicated acquisition divisions.
- Product Development:Commercial engineering teams demand hybrid platforms bridging solderless modularity with surface-mount adapter compatibility. This segment exhibits highest willingness-to-pay for pitch-convergence solutions.
- Prototyping:Iterative circuit design workflows prioritize reusability and rapid reconfiguration. Independent developers and startup hardware teams populate this channel.
- DIY Projects:Hobbyist and maker communities drive demand through direct-to-consumer retail and online distribution. Price sensitivity here exceeds institutional channels substantially.
Education commands the largest installed base, while product development applications are gaining share fastest as professional engineers seek prototyping platforms compatible with sub-1.0 mm pitch semiconductor packaging.
End User:
Technical capability gradients separate users by soldering proficiency, circuit design sophistication, and tolerance for permanent commitment to layout decisions.
- Engineers:Professional hardware developers require platforms supporting mixed-signal prototyping with documented signal integrity specifications. Quick-turn PCB substitution threatens this segment's breadboard attachment most directly.
- Students:Undergraduate and vocational trainees need error-forgiving platforms with low replacement cost per iteration. Institutional procurement consolidation favors suppliers with established educational distribution relationships.
- Hobbyists:Enthusiast communities prioritize accessibility and community documentation over performance specifications. Online forums and maker-space networks influence brand selection here.
- Designers:Industrial and interaction designers require rapid physical validation of electronic behavior without deep circuit theory preparation. Hybrid development kits serve this emerging user profile.
Students represent the most stable demand pool, while engineers are migrating fastest toward direct PCB fabrication services that bypass breadboard stages entirely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports breadboard assemblies and substrate materials to educational institutions across Germany, Japan, and the United States. The Guangdong-Shenzhen corridor anchors this trade flow with concentrated PCB prototyping services and component distribution infrastructure.
United States
University engineering programs in Texas and California are expanding hands-on electronics laboratories. The FCC regulates electromagnetic compatibility standards for educational equipment procurement. Boston's Route 128 technology corridor hosts hardware startup incubators that sustain demand for rapid prototyping platforms.
Germany
Technical universities in Bavaria and Baden-Württemberg are centralizing electronics lab equipment acquisition through dedicated procurement divisions. ECHA REACH substance restrictions on phthalates constrain supplier certification pathways for EU educational channels. Stuttgart's industrial automation training centers specify ISO 9001-certified prototyping equipment.
China
The State Administration for Market Regulation applies GB standards for electrical insulation and fire safety that shape export certification requirements. Guangdong province's Shenzhen-Dongguan manufacturing zone clusters breadboard production with downstream PCB fabrication services. Domestic vocational training institutes are expanding enrollment in electronics technician programs.
Japan
METI supports precision manufacturing education through national college of technology programs. JIS standards govern material specifications for educational equipment distributed to technical high schools. The Nagoya-Chubu region concentrates electronics component distribution infrastructure serving prototyping supply chains.
India
Indian Institutes of Technology are embedding hardware design laboratories into undergraduate engineering curricula. The Bureau of Indian Standards enforces electrical safety certification for imported educational equipment. Karnataka's Bengaluru electronics manufacturing cluster hosts contract assemblers serving institutional procurement channels.
Breadboards Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. The market exhibits moderate concentration with substrate-integrated manufacturers holding cost advantages over independent assemblers. Strategic archetypes include precision substrate specialists, rapid-fabrication service providers, and educational distribution channel controllers. Dominant competitive moves center on backward integration into laminate materials and hybrid platform development bridging solderless and surface-mount compatibility.
Among East Asian substrate specialists, Nippon Mektron and Zhen Ding Technology exemplify the precision-manufacturing archetype with captive control over laminate and copper-clad material supply. TTM Technologies occupies a position representing the quick-turn fabrication alternative that bypasses traditional breadboard stages entirely. These three anchors illustrate how competitive positioning fragments between substrate-integrated cost leadership and rapid-prototyping service velocity.
| Leading Market Players |
|---|
| Nippon Mektron |
| Compeq Manufacturing |
| Zhen Ding Technology |
| Suzhou Dongshan Precision Manufacturing |
| Tripod Technology |
| Unimicron Technology |
| AT&S |
| Ibiden |
| TTM Technologies |
| Others |
Value Network & Pricing Analysis
Guangdong province's Shenzhen-Dongguan manufacturing cluster concentrates breadboard substrate production alongside downstream PCB fabrication services, granting vertically integrated manufacturers pricing leverage over independent assemblers lacking captive laminate supply. This geographic concentration compresses margins for commodity plastic variants while shielding premium metal-substrate producers from direct cost competition.
Pricing Analysis
Cost-plus contracts indexed to copper-clad laminate spot prices dominate procurement relationships between substrate-integrated manufacturers and institutional buyers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified metal enclosures from uncertified plastic classroom units. Price differentiation hinges on REACH compliance documentation and thermal performance specifications. Pricing pressure stems from quick-turn PCB fabricators compressing the addressable window for professional-grade breadboards. Hobbyist channels exhibit highest price sensitivity, while industrial training programs demonstrate lowest elasticity due to certification requirements.
Supply Chain Analysis
Export-control regimes restricting precision metal stamping equipment to certain Asian manufacturing jurisdictions constrain substrate production expansion outside established corridors. Supply concentrates in China, Japan, and Taiwan, with raw material dependencies spanning ABS resin, copper-clad laminates, and spring-clip alloys. Single-source vulnerability characterizes the laminate substrate tier where Zhen Ding Technology and Nippon Mektron control critical capacity. Distribution runs through educational procurement offices and electronics component distributors serving university labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face structural substitution from rapid PCB fabrication services that bypass breadboard stages entirely, requiring defensive repositioning around hybrid prototyping platforms.
For Market Incumbents: Pre-empt quick-turn PCB substitution by embedding surface-mount adapter compatibility into solderless platforms. Capture engineers transitioning from educational to professional environments. Backward integration into laminate materials defends margin position against copper-clad input volatility. Prioritize ISO 9001 certification investment to access centralized German and Japanese institutional procurement channels. For New Entrants and Emerging Players: India's Bengaluru electronics manufacturing cluster offers underpenetrated institutional procurement channels as Indian Institutes of Technology expand hardware design laboratories. Target vocational training institutes in secondary Chinese cities beyond the Guangdong-Shenzhen corridor. Metal-substrate RF prototyping for aerospace training programs presents white-space opportunity with premium pricing potential. Partner with established educational distributors rather than building direct-to-institution sales infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors substrate-integrated specialists with captive laminate supply and documented REACH compliance pathways. Five-to-ten year viability rests on bridging the sub-1.0 mm pitch compatibility gap before semiconductor packaging miniaturization erodes breadboard relevance. Acquisition targets should demonstrate hybrid platform development capabilities and established educational distribution relationships. Monitor quick-turn PCB pricing compression as the inflection signal for breadboard addressable market contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Development | Surface-mount adapter integration sustains breadboard relevance against PCB substitution. |
| REACH Compliance Certification | ECHA substance restrictions filter non-compliant suppliers from EU educational channels. |
| Educational Distribution Partnership | Centralized German and Japanese procurement offices favor established channel relationships. |
| Metal Substrate Capacity Expansion | RF prototyping demand from aerospace training programs commands premium positioning. |
| Backward Integration into Laminates | Captive copper-clad supply insulates margins from raw material volatility. |
Research Methodology
Cross-validation between primary interviews with procurement officers at German technical universities and secondary analysis of ECHA REACH compliance databases anchors the qualitative findings. Conversations with electronics lab directors, institutional purchasing managers, substrate manufacturing engineers, and educational equipment distributors informed demand-side dynamics. Secondary sources include GB standards filings with China's State Administration for Market Regulation, JIS specification documents, SEC 10-K disclosures from listed substrate manufacturers, and customs trade data tracking breadboard assembly exports. Bottom-up unit economics modeling triangulates against top-down market sizing from educational procurement budget allocations.
Calibration against historical procurement volumes at Japanese national colleges of technology validates the projection framework across the analysis window. Segmentation modeling incorporates product architecture, substrate material grade, application intensity, and end-user technical capability dimensions. CAGRs derive from trend extrapolation of institutional enrollment growth and curriculum modernization rates. Forecast inputs include semiconductor packaging pitch evolution timelines and quick-turn PCB pricing trajectories.
Practitioners should monitor quick-turn PCB turnaround time compression and sub-1.0 mm pitch semiconductor adoption rates for early signals requiring forecast revision. Cross-checking against Bureau of Indian Standards electrical safety certification trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio DSP Market
Electronic Components
Efuse Market
Electronic Components
North America USB Retimer Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
AC Adapter Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Motherboard Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Resonators Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Americas MPU Market
Electronic Components
Industrial Relays Market