
 Data Acquisition Hardware Market | 2026-2036
Data Acquisition Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Data Acquisition Hardware Market Analysis
Direct distribution through manufacturer-authorized technical representatives is tilting toward hybrid models that blend field engineering support with digital configuration tools. National Instruments leverages its software-hardware ecosystem to sustain developer loyalty across research institutions. Keysight Technologies anchors its position through precision instrument calibration services that extend equipment lifecycle value. Emerson Electric competes by integrating data acquisition modules into its broader automation platform architecture.
Data acquisition hardware comprises sensor interfacing electronics, signal conditioning circuits, and analog-to-digital conversion subsystems that sample physical phenomena at rates from kilohertz to gigahertz for computer-based analysis and control. These systems translate temperature, pressure, vibration, and electrical signals into digital streams for industrial monitoring, scientific research, and product validation workflows. Ethernet-connected chassis dominate factory floor deployments where distributed measurement nodes reduce cabling complexity across production lines. Modular PXI and CompactDAQ architectures capture expanding R&D budgets as engineers swap converter cards without replacing entire systems. Wireless data loggers are gaining traction in environmental monitoring applications where physical tethering proves impractical.
FCC equipment authorization rules govern radiated emissions from wireless acquisition nodes sold into US industrial facilities, while CE marking under the EU Radio Equipment Directive shapes product development roadmaps for European market entry. ISO 17025 calibration standards drive recurring service revenue as accredited traceability becomes mandatory for aerospace and automotive supplier certifications. NHTSA vehicle safety testing protocols and EPA emissions certification requirements create sustained demand for high-fidelity acquisition systems in Detroit and Stuttgart engineering centers. Stakeholders must weigh the capital efficiency of modular upgrade paths against integrated platform consolidation as channel strategies and regulatory scopes continue to diverge across major economies.
Market Dynamics
The EU AI Act and CE marking requirements are compressing product development timelines, forcing vendors to certify modular architectures before European market entry while automotive test engineers in Stuttgart and Munich expand high-channel-count validation systems for electric vehicle programs.
Growth Catalysts
- Electric vehicle validation protocols:NHTSA safety testing mandates in Detroit engineering centers sustain demand for precision acquisition systems capable of sampling battery thermal runaway signatures at millisecond resolution.
- CE marking under EU Radio Equipment Directive:Wireless data logger manufacturers must demonstrate electromagnetic compatibility compliance, accelerating modular chassis designs that isolate radiated emissions from sensitive analog front-ends.
- ISO 17025 calibration accreditation:Aerospace suppliers in Toulouse and Hamburg require traceable measurement chains, generating recurring service revenue for vendors maintaining accredited laboratories.
Market Restraints
- Precision analog-to-digital converter supply concentration:High-resolution sigma-delta architectures depend on foundry capacity concentrated in East Asian semiconductor fabrication facilities, exposing lead time volatility.
- Copper and rare earth magnet input costs:Signal conditioning modules incorporating shielded transformers face raw material price swings that compress gross margins on mid-range product tiers.
- Wireless spectrum congestion:FCC Part 15 unlicensed band saturation in dense industrial environments limits reliable deployment of battery-powered acquisition nodes without proprietary mesh protocols.
Strategic Opportunities
- Environmental monitoring in remote watersheds:Hydrological research stations in Norway and Switzerland deploy solar-powered wireless loggers where cabled infrastructure proves cost-prohibitive across alpine terrain.
- EU Green Deal industrial decarbonization tracking:Steel and cement producers in the Ruhr Valley require continuous emissions monitoring systems to verify carbon intensity benchmarks under emerging carbon border adjustment mechanisms.
- Edge computing convergence with time-sensitive networking:Factory automation integrators in Bavaria combine IEEE 802.1AS time synchronization with local preprocessing to reduce cloud data transfer volumes for predictive maintenance applications.
Industry Challenges
- Mixed-signal firmware engineering scarcity:Vendors compete for talent capable of optimizing real-time operating systems for deterministic sampling jitter below 100 nanoseconds across multi-channel PXI chassis.
- Legacy GPIB interface integration:Research laboratories in Cambridge and Heidelberg maintain decades-old test equipment, requiring modern USB-C and Ethernet-connected acquisition hardware to emulate obsolete bus protocols.
- Multi-jurisdiction certification parallelism:Simultaneous FCC, CE, and VCCI approvals for wireless nodes extend product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Acquisition Hardware Market |
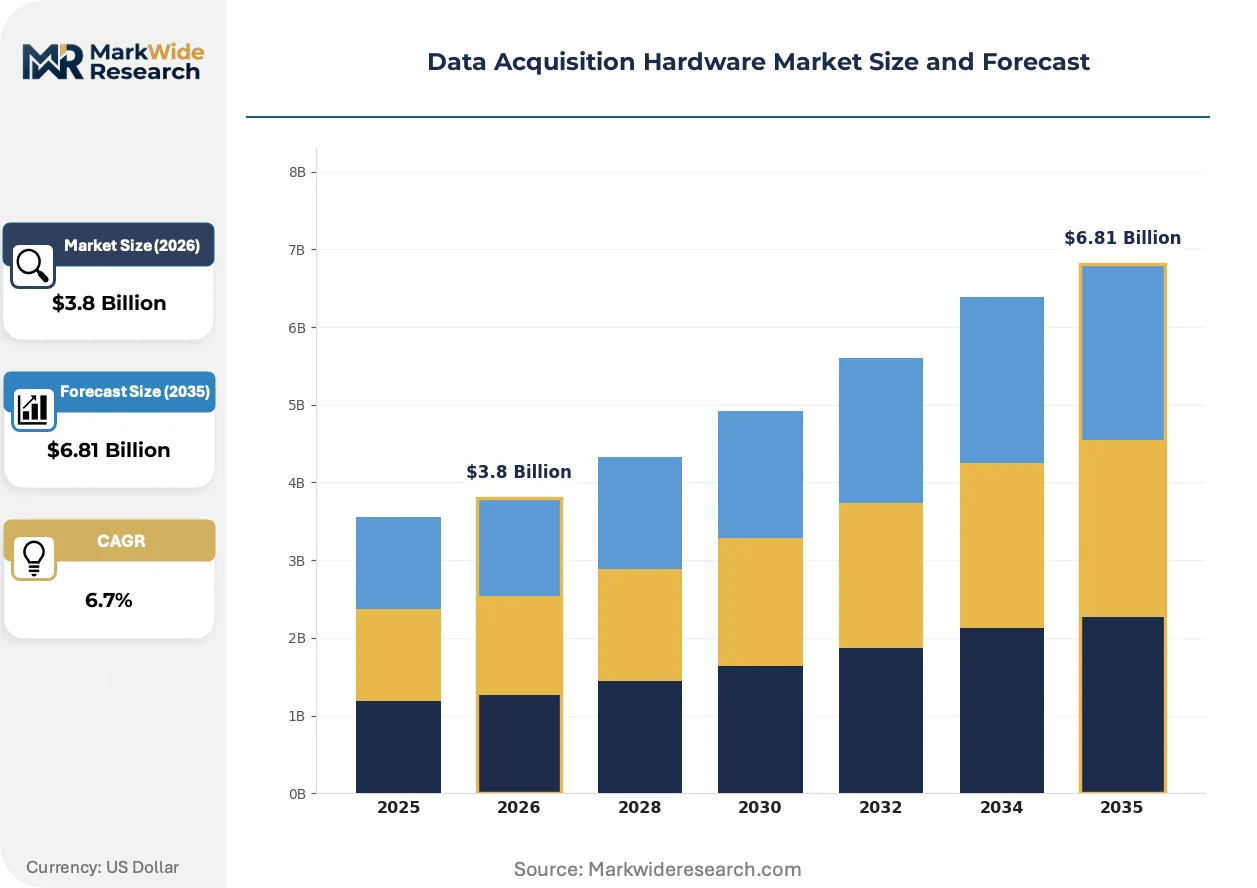
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Loggers, Signal Conditioners, Multiplexers, Analog-to-Digital Converters Connection Type: USB, Ethernet, Wireless, Serial End User: Manufacturing, Automotive, Aerospace, Research Institutions Technology: Modular, Compact, Integrated, Standalone |
| Companies Covered | National Instruments, Keysight Technologies, Emerson Electric, Spectris, Yokogawa Electric Corporation, AMETEK Inc., Agilent Technologies, TE Connectivity, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Acquisition Hardware Market Emerging Trajectories
Hardware architectures are fragmenting between edge-preprocessing intelligence and cloud-dependent raw data streaming, while regulatory pressure and procurement model evolution reshape how validation systems reach end-users.
Time-sensitive networking is hybridizing factory floor measurement topologies by embedding IEEE 1588 precision timing directly into Ethernet-connected chassis. Automotive tier-one suppliers in Wolfsburg and Ingolstadt deploy these synchronized nodes to correlate powertrain vibration data with battery management system telemetry. The technology is hybridizing traditional star-wiring configurations into distributed daisy-chain layouts that halve installation labor.
REACH substance restrictions on lead-bearing solders and cadmium-plated connectors are forcing redesigns of ruggedized industrial enclosures. Vendors serving German machine builders must substitute tin-bismuth alloys and zinc-nickel finishes without compromising thermal cycling reliability. CompactDAQ module manufacturers report eighteen-month qualification cycles to verify alternative metallurgy across -40°C to +85°C operating ranges.
Buyer organizations are consolidating vendor relationships around calibration-coverage contracts rather than discrete equipment purchases. Aerospace primes in Toulouse now negotiate five-year service agreements bundling hardware, accredited traceability, and firmware updates. This restructuring concentrates procurement authority with metrology departments and marginalizes distributors lacking in-house ISO 17025 laboratories.
Data Acquisition Hardware Market Segmentation
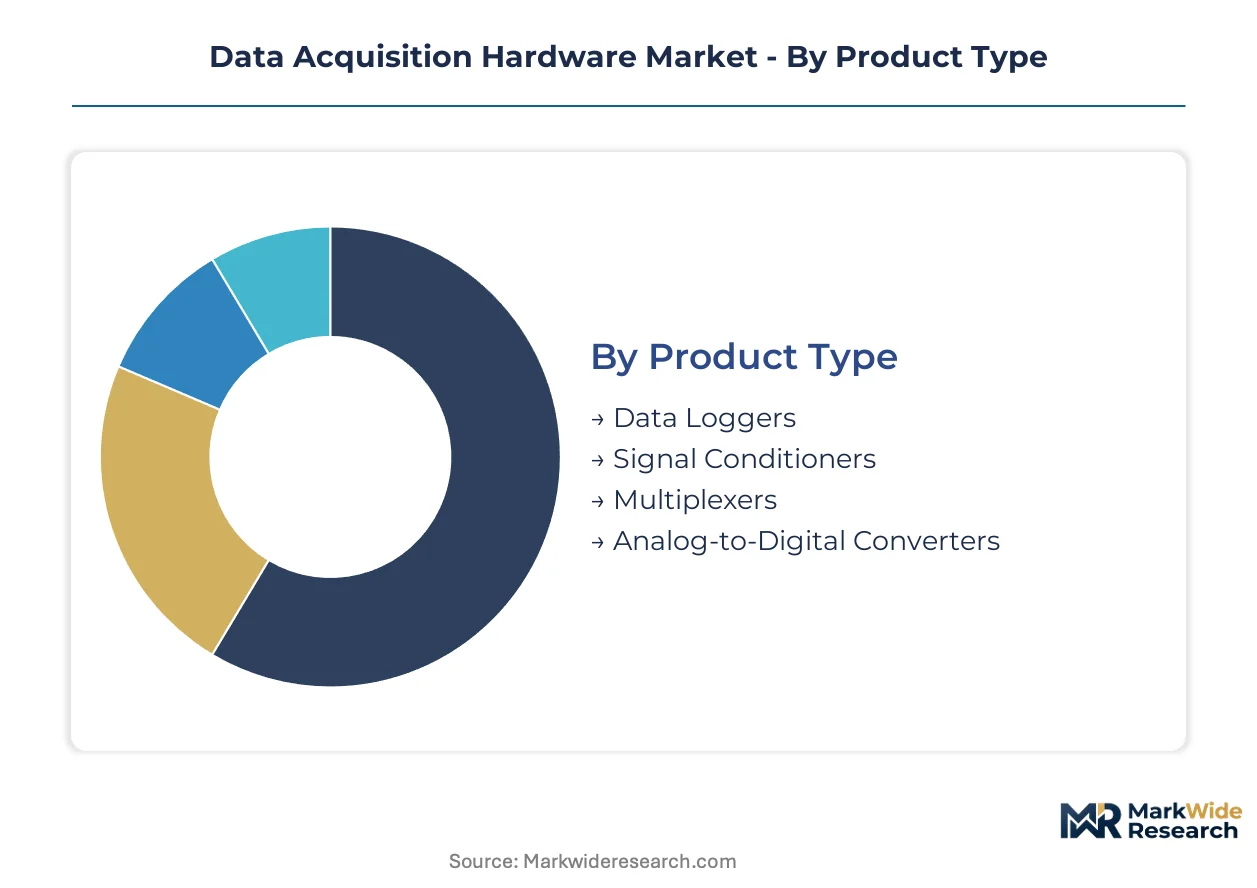
Segmentation in data acquisition hardware reveals how procurement decisions split between legacy infrastructure compatibility and emerging connectivity requirements. Engineers select architectures based on channel density needs, environmental constraints, and integration complexity with existing test environments.
Product Type:
Mature analog conversion technologies dominate installed bases while digital integration modules emerge as upgrade priorities for modernized facilities.
- Data Loggers:Battery-powered or mains-connected devices record temperature, humidity, and pressure over extended periods with onboard storage for later retrieval. Environmental monitoring stations in Norway's hydrological networks and pharmaceutical cold-chain operations in Switzerland deploy these units where continuous tethering proves impractical.
- Signal Conditioners:Amplification and filtering electronics normalize sensor outputs to standard voltage ranges before digitization, incorporating isolation barriers to protect downstream equipment from industrial transients. Automotive battery test cells in Stuttgart engineering centers require these modules to handle high-voltage isolation during thermal runaway characterization studies.
- Multiplexers:Switching matrices route multiple analog inputs through shared conversion resources to reduce per-channel cost in high-density applications.
- Analog-to-Digital Converters:Precision sampling circuits translate continuous voltage waveforms into discrete digital codes at resolutions from 12 to 24 bits.
Data Loggers retains volume leadership; Signal Conditioners holds the steepest expansion curve.
Connection Type:
Physical interface selection hinges on cable routing constraints, bandwidth requirements, and electromagnetic immunity in target deployment environments.
- USB:Plug-and-play connectivity suits benchtop instrumentation and portable diagnostic equipment with guaranteed bandwidth up to 20 Gbps in latest revisions. Research laboratories in Cambridge maintain USB-tethered modules for rapid reconfiguration during iterative prototype validation cycles.
- Ethernet:IEEE 802.3 wired networking enables distributed measurement nodes across factory floors with Power-over-Ethernet simplifying installation. Bavarian automation integrators combine these chassis with IEEE 802.1AS time synchronization for correlated multi-point vibration analysis in predictive maintenance deployments.
- Wireless:Unlicensed radio links eliminate cabling in rotating machinery monitoring and remote environmental sensing applications.
- Serial:RS-232 and RS-485 legacy interfaces persist in industrial control systems requiring deterministic timing over multi-drop bus architectures.
Ethernet commands the largest installed base; Wireless gains share fastest in new project specifications.
End User:
Vertical application requirements drive divergent specifications for sampling rates, environmental sealing, and calibration traceability.
- Manufacturing:Production line monitoring systems prioritize channel density and hot-swappable modules to minimize downtime during format changeovers. Steel producers in Germany's Ruhr Valley deploy continuous emissions monitoring under EU Green Deal carbon intensity verification protocols.
- Automotive:Electric vehicle validation demands microsecond-resolution sampling across hundreds of synchronized channels for battery and powertrain characterization. NHTSA safety testing mandates in Detroit engineering centers sustain procurement of high-fidelity systems capable of capturing thermal runaway signatures.
- Aerospace:Flight test instrumentation and structural health monitoring require DO-160 environmental qualification and ISO 17025 calibration chains.
- Research Institutions:Flexible modular architectures accommodate evolving experimental requirements across physics, materials science, and biomedical investigations.
Manufacturing retains volume leadership; Automotive holds the steepest expansion curve.
Technology:
Architectural philosophy separates systems optimized for reconfigurability from those prioritizing integration density and cost minimization.
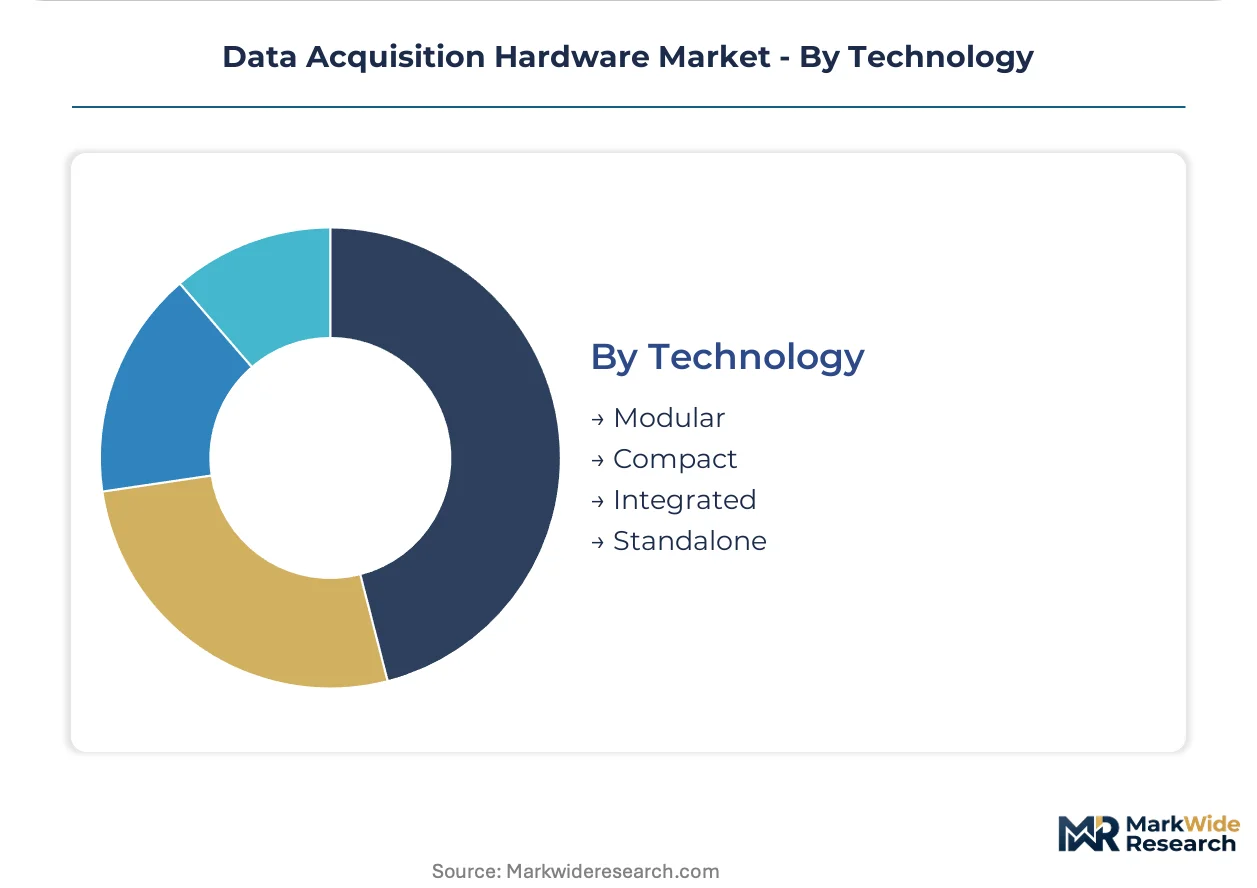
- Modular:Chassis-based platforms accept interchangeable input, output, and processing cards to adapt measurement capability without full system replacement. PXI and CompactDAQ ecosystems capture expanding R&D budgets as engineers swap converter cards to match evolving test protocols.
- Compact:Self-contained units integrate limited channel counts with embedded processing in reduced footprints for space-constrained installations.
- Integrated:Fixed-function designs embed acquisition subsystems within larger equipment platforms such as test stands or analytical instruments.
- Standalone:Battery-powered or self-contained loggers operate without host computer tethering for field deployment scenarios.
Modular architectures retain volume leadership; Compact form factors gain traction fastest in edge-computing convergence applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering centers command 15-20% pricing premiums over North American equivalents for certified modular systems, while US procurement concentrates around Detroit automotive validation clusters with shorter certification cycles but lower service attach rates.
United States
NHTSA safety testing mandates and EPA emissions protocols sustain procurement of high-channel-count systems in Detroit engineering centers. FCC equipment authorization rules govern wireless node deployments across industrial facilities. Automotive tier-one suppliers in Michigan deploy synchronized measurement networks for electric vehicle battery characterization.
Germany
CE marking under the EU Radio Equipment Directive and EU AI Act compliance requirements compress product development timelines for modular architectures. REACH substance restrictions force metallurgical redesigns of ruggedized enclosures. Industrial automation integrators in Munich and Stuttgart combine time-sensitive networking with predictive maintenance deployments.
China
MIIT standards and GB certification requirements shape product roadmaps for domestic semiconductor test applications. Dual carbon goals accelerate emissions monitoring system procurement in steel and cement sectors. Yangtze River Delta manufacturing clusters drive demand for Ethernet-connected chassis with Power-over-Ethernet simplification.
Japan
METI industrial digitization programs and JIS standards compliance sustain precision instrument demand in automotive and electronics sectors. PMDA-aligned calibration traceability requirements serve pharmaceutical manufacturing applications. Nagoya-area automotive suppliers deploy compact modular systems for powertrain validation workflows.
Switzerland
Swissmedic-aligned measurement traceability and ISO 17025 accreditation requirements generate premium service revenue opportunities. Alpine hydrological research stations deploy solar-powered wireless loggers for remote watershed monitoring. Precision instrument manufacturers in Zurich and Basel maintain calibration-coverage contract structures with aerospace and pharmaceutical clients.
Data Acquisition Hardware Market Vendor Landscape
Precision instrument specialists and automation platform integrators split the market between calibration-intensive service models and embedded module architectures. Consolidation pressure concentrates procurement authority around metrology departments with ISO 17025 laboratory requirements. Three archetypes dominate: ecosystem-anchored software-hardware bundlers, calibration-service extenders, and automation-platform integrators. Competitive moves center on five-year service agreement bundling and firmware update subscription structures.
Among US-based precision instrument specialists, National Instruments and Keysight Technologies exemplify divergent ecosystem strategies. Emerson Electric occupies a position within the automation-platform integrator tier. These three entities represent the primary competitive anchors around which vendor consolidation and procurement restructuring currently organize.
| Leading Market Players |
|---|
| National Instruments |
| Keysight Technologies |
| Emerson Electric |
| Spectris |
| Yokogawa Electric Corporation |
| AMETEK Inc. |
| Agilent Technologies |
| TE Connectivity |
| Rockwell Automation |
| Others |
Supply Flow & Price Mechanics
East Asian semiconductor fabrication capacity for high-resolution sigma-delta analog-to-digital converters concentrates upstream leverage among foundry operators, pushing margin pools downstream toward calibration-service bundlers and firmware-locked platform ecosystems. Procurement departments in Stuttgart and Detroit now negotiate five-year service agreements that capture recurring revenue streams detached from hardware unit economics.
Pricing Analysis
Configured-to-order chassis pricing commands spreads of 40-60% above standard catalog configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 calibration accreditation status and channel density. Cost compression in mid-range signal conditioning modules intensifies because copper and rare-earth magnet input volatility erodes fixed-price contract viability. Automotive tier-one suppliers exhibit lowest price sensitivity due to NHTSA-mandated traceability requirements, while environmental monitoring agencies in alpine regions face acute budget constraints.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates supply chain risk planning for precision converter sourcing. Taiwan, South Korea, and Japan anchor wafer fabrication for 24-bit sigma-delta architectures, while Germany and Switzerland host final assembly of ruggedized PXI chassis. Raw material dependencies span copper for shielded transformers, rare-earth magnets for isolation components, and tin-bismuth alloys substituting lead-bearing solders under REACH restrictions. Distribution runs through manufacturer-authorized technical representatives transitioning toward hybrid digital-field models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around metrology departments consolidating vendor relationships through calibration-coverage contracts, fragmenting distributor influence across aerospace and automotive procurement hierarchies.
For Market Incumbents: Build firmware-locked ecosystem moats by embedding IEEE 802.1AS time synchronization protocols into Ethernet chassis architectures. Deepen backward integration into precision analog-to-digital converter sourcing through strategic foundry partnerships in Taiwan and South Korea. Defend against emerging compact edge-computing entrants by accelerating ISO 17025 laboratory accreditation in Toulouse and Hamburg service centers. For New Entrants and Emerging Players: Mid-market environmental monitoring stations in Norway and Switzerland represent the most penetrable entry point for solar-powered wireless logger deployments. Alpine hydrological research networks lack incumbent calibration infrastructure, creating white-space for service-light hardware models. Target EU Green Deal decarbonization tracking applications in the Ruhr Valley through direct sales to steel producer sustainability departments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed precision instrument specialists lacking automation platform integration capabilities. Long-term viability hinges on five-to-ten-year service contract renewal rates rather than hardware replacement cycles. Watch for inflection signals in FCC Part 15 spectrum reallocation proceedings affecting wireless node deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration-Coverage Contract Bundling | Aerospace primes in Toulouse now mandate five-year service agreements combining hardware, ISO 17025 traceability, and firmware updates. |
| Time-Sensitive Networking Integration | Bavarian automation integrators deploy IEEE 802.1AS synchronization to correlate battery management telemetry with powertrain vibration data. |
| REACH-Compliant Metallurgy Redesign | German machine builders substitute tin-bismuth alloys and zinc-nickel finishes across -40°C to +85°C operating ranges. |
| Edge-Computing Convergence | Factory automation integrators combine local preprocessing with IEEE 1588 timing to reduce cloud data transfer volumes for predictive maintenance. |
| Hybrid Distribution Model Transition | Field engineering support blends with digital configuration tools to sustain developer loyalty across research institutions. |
Methodological Framework
A standing panel of automotive test engineers, metrology laboratory directors, industrial automation integrators, and precision instrument procurement managers provided ongoing calibration against secondary validation sources. Primary interviews combined with regulatory filings from NHTSA, ECHA, and FCC equipment authorization databases, trade customs records for semiconductor converter imports, and SEC 10-K disclosures from listed precision instrument manufacturers. Bottom-up channel shipment analysis triangulated against top-down R&D budget allocations across automotive and aerospace verticals.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled encompass product architecture, connection interface, end-use vertical, and geographic regulatory cluster. CAGRs derived from instrumented growth rate convergence across hardware unit shipments, service contract attach rates, and firmware subscription penetration. Industry-specific inputs incorporated electric vehicle validation protocol evolution and EU AI Act compliance timeline compression.
Practitioners should monitor FCC spectrum reallocation proceedings, REACH substance restriction expansion, and foundry capacity utilization rates for early signals of forecast revision triggers. Forecasts reflect assumptions regarding modular architecture certification parallelism and wireless mesh protocol adoption curves. Material shifts in East Asian semiconductor export controls or EU carbon border adjustment mechanism implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
North America USB Retimer Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Audio DSP Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
Global Tantalum Capacitors Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Serial Device Servers Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market
Electronic Components
Lowpass Filters Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Electronic Shelf Label Market