
 Distribution Components Market | 2026-2036
Distribution Components Market Size, Share, and Industry Trends Forecast 2026-2036
Distribution Components Market Outlook
Market Context
The EU Green Deal is hardening efficiency requirements for medium-voltage distribution equipment across European utilities. Schneider Electric leverages its integrated energy management portfolio to capture replacement demand from aging substations. Siemens anchors its position through digital twin technology for switchgear lifecycle optimization. ABB competes with modular substation architectures that reduce installation downtime for renewable interconnection projects.
Technical Definition and Segment Structure
Distribution components encompass electromechanical and solid-state devices engineered to control, protect, and transform electrical power across voltage classes from low-voltage residential circuits through high-voltage transmission interfaces, typically operating at insulation coordination levels rated per IEC 60694 and thermal withstand criteria defined by IEC 60909. Circuit breakers and switchgear command the largest value share due to mandatory protection requirements, while prefabricated and modular installation modes are gaining traction as utilities compress project timelines and labor costs. The service-type dimension shows maintenance contracts generating recurring revenue streams that now rival initial equipment sales for established fleet operators.
Regulatory Frame and Outlook
IEC standards, the EU F-Gas Regulation, and national electrical safety codes in India and the United States shape product certification requirements and cross-border market access for distribution component manufacturers. ECHA restrictions on sulfur hexafluoride intensify R&D investment in vacuum interrupter and clean air insulation technologies. Stakeholders must monitor evolving carbon-border adjustment mechanisms and local content rules that threaten to fragment procurement standards across major demand centers.
Market Dynamics
Grid decentralization is compressing procurement cycles for distribution components as utilities fragment large substation projects into modular, scalable deployments. This structural shift favors suppliers with rapid configuration capabilities over traditional equipment vendors.
Growth Catalysts
- Rural Electrification Mandates:India's CEA directives are accelerating distribution panel procurement across underserved states. State utilities are issuing bundled tenders for transformers and circuit breakers.
- F-Gas Phase-Down:The EU F-Gas Regulation is forcing replacement of SF6-insulated switchgear. Vacuum interrupter technology is capturing this regulatory pull.
- Renewable Interconnection Queues:Solar and wind project backlogs in Germany and Spain are driving demand for medium-voltage switchgear with fast-track certification.
Market Restraints
- Copper and Electrical Steel Volatility:Raw material price swings are compressing margins for transformer manufacturers. Long-term procurement contracts are becoming harder to secure.
- SF6 Disposal Liabilities:ECHA restrictions are creating stranded asset risks for utilities with legacy gas-insulated switchgear. Decommissioning costs are deterring fleet upgrades.
- Technical Talent Scarcity:Specialized expertise in IEC 61850 protocol integration is concentrating among a narrow contractor base. Project delays are lengthening.
Strategic Opportunities
- Digital Twin Convergence:Integration of asset performance monitoring with predictive maintenance platforms is opening recurring revenue streams. Siemens and ABB are anchoring early positions.
- Modular Substation Demand:Prefabricated architectures are reducing installation downtime for renewable interconnection projects. European utilities are piloting containerized designs.
- India PLI Incentives:The government's production-linked incentive scheme for electrical equipment is attracting component manufacturing investment. Domestic sourcing requirements are shifting procurement patterns.
Industry Challenges
- IEC 61850 Certification Bottlenecks:Testing laboratory capacity constraints are extending product approval timelines. Manufacturers face launch delays.
- Legacy System Integration Complexity:Retrofitting digital monitoring into electromechanical protection schemes requires custom engineering. Project costs are ballooning.
- Supply Chain Reconfiguration Friction:Shifting from SF6 to vacuum or clean air insulation is straining supplier qualification processes. Component interoperability gaps persist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distribution Components Market |
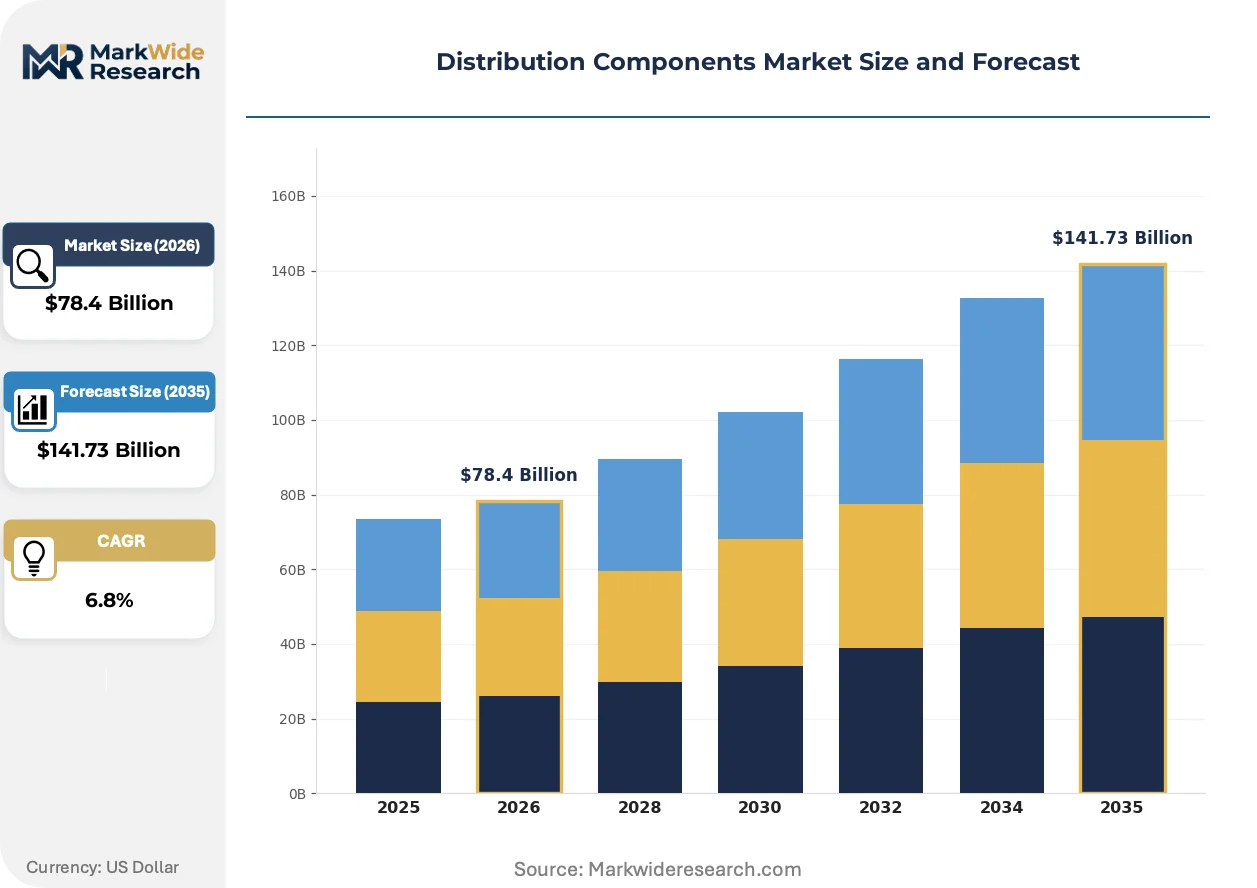
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Circuit Breakers, Switchgear, Transformers, Cables End User: Manufacturing, Construction, Utilities, Residential Installation Mode: Onsite, Prefabricated, Modular, Integrated Service Type: Maintenance, Installation, Design, Consultancy |
| Companies Covered | Schneider Electric, ABB, Eaton, Siemens, Mitsubishi Electric, Legrand, Larsen & Toubro, General Electric, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distribution Components Market Strategic Shifts
Solid-state protection devices and digital monitoring architectures are displacing electromechanical relays. This transition is compressing maintenance cycles and enabling remote asset management across utility fleets.
Silicon carbide power semiconductors are decentralizing protection and control functions in medium-voltage networks. European utilities are deploying these devices in renewable interconnection substations. The technology is enabling smaller footprint switchgear designs that reduce civil works costs.
The EU F-Gas Regulation is accelerating R&D investment in alternative insulation mediums. Vacuum interrupter manufacturers are scaling production capacity to capture replacement demand. Switchgear producers are redesigning product lines around clean air insulation for ratings up to 24 kV.
Utility procurement departments are unbundling equipment purchases from long-term service agreements. European transmission operators are negotiating separate maintenance contracts with specialized service providers. This shift is fragmenting vendor relationships and compressing upfront equipment margins.
Distribution Components Market Segmentation
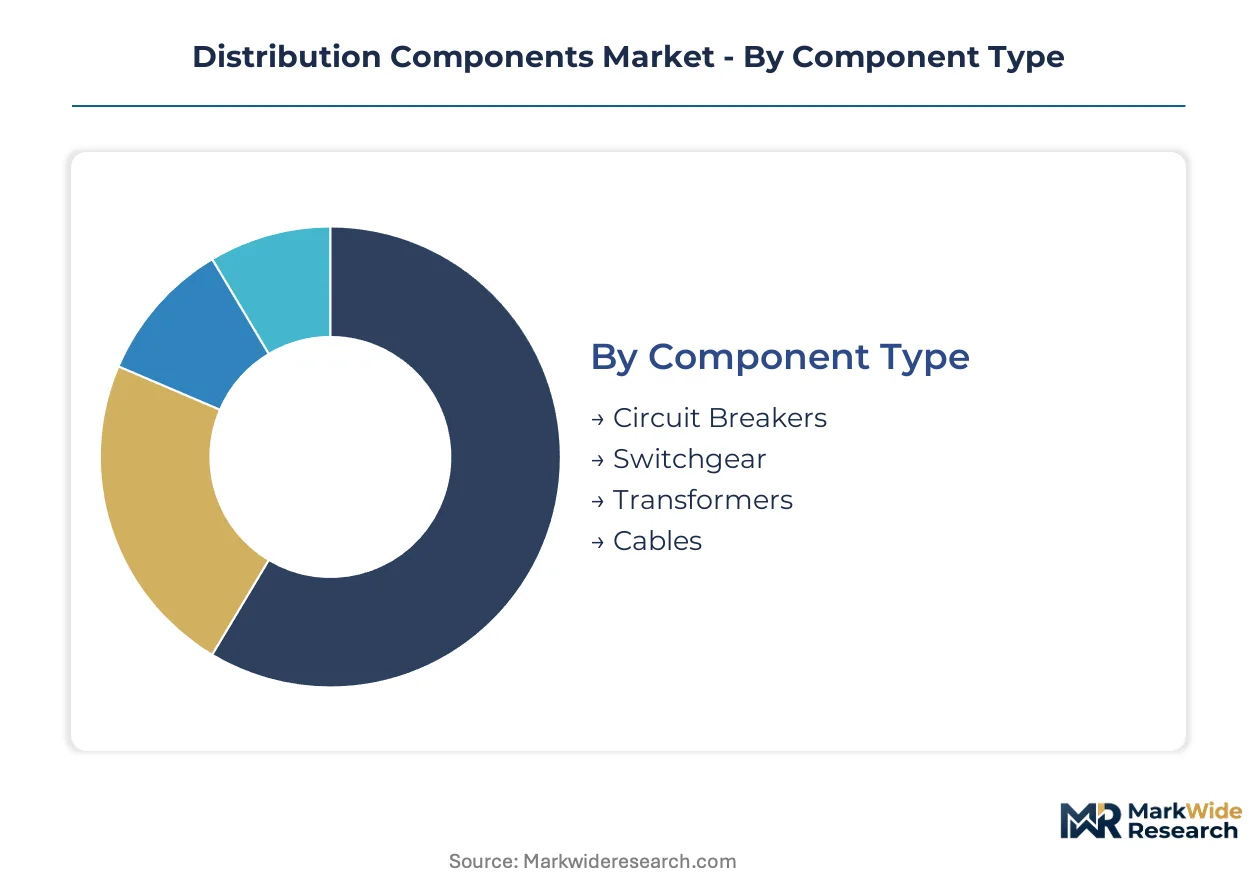
Distribution components serve divergent technical requirements across voltage classes and deployment contexts. Segmentation reveals where certification burdens concentrate and which procurement patterns dominate capital allocation decisions.
Component Type:
IEC 60909 short-circuit calculations and IEC 60694 insulation coordination drive certification intensity for high-voltage ratings, while low-voltage segments face faster approval cycles.
- Circuit Breakers:Electromechanical and solid-state interrupting devices rated for fault current containment. Demand concentrates in German renewable interconnection substations where ECHA F-Gas restrictions are accelerating vacuum interrupter procurement.
- Switchgear:Enclosed assemblies combining control, protection, and metering functions. Indian state utilities are bundling medium-voltage switchgear tenders under CEA rural electrification directives, prioritizing rapid-deployment configurations.
- Transformers:Electromagnetic voltage conversion equipment subject to thermal withstand testing. Copper and electrical steel volatility is compressing manufacturer margins.
- Cables:Insulated conductors for power transmission across voltage classes. Cross-linked polyethylene dominates new installations.
Leading the category by volume: Circuit Breakers. Growing fastest: Switchgear.
End User:
Procurement scale and technical specification authority vary sharply across customer types, with utilities wielding standard-setting power that cascades to other segments.
- Utilities:Grid operators with fleet-wide standardization authority and long-term maintenance contracting power. European transmission operators are unbundling equipment purchases from service agreements.
- Manufacturing:Industrial facilities requiring captive power distribution and process-critical protection schemes. Automotive and semiconductor fabs drive demand for high-reliability switchgear.
- Construction:Project developers procuring temporary and permanent distribution infrastructure. Urban infrastructure buildouts in India are accelerating panel procurement.
- Residential:Single-family and multi-unit developers sourcing low-voltage distribution panels and circuit protection. Regulatory pressure on arc-fault detection is reshaping product specifications.
Dominating procurement volume: Utilities. Expanding most quickly: Manufacturing.
Installation Mode:
Project timeline compression and labor cost pressures are shifting preference toward factory-tested configurations that minimize field commissioning.
- Prefabricated:Factory-assembled substations and switchgear enclosures delivered as complete units. Containerized designs are reducing civil works costs for Spanish and German renewable projects.
- Modular:Scalable architectures enabling phased capacity expansion without full substation rebuilds. European utilities are piloting these for solar farm interconnection.
- Onsite:Traditional stick-built construction with component-by-component assembly. Remains prevalent for legacy system retrofits requiring custom engineering.
- Integrated:Turnkey solutions combining equipment, installation, and commissioning under single-contractor responsibility. Appeals to construction sector buyers with limited in-house electrical expertise.
Highest volume currently: Onsite. Steepest expansion trajectory: Modular.
Service Type:
Recurring revenue streams from maintenance contracts now rival initial equipment sales for established fleet operators, reshaping vendor business models.
- Maintenance:Scheduled inspection, testing, and component replacement programs. Predictive maintenance platforms using digital twin technology are capturing premium pricing.
- Installation:Field assembly, testing, and commissioning services. Specialized IEC 61850 protocol expertise is concentrating among narrow contractor bases.
- Design:Engineering services for custom distribution architecture development. Required for legacy system integration projects.
- Consultancy:Advisory services on regulatory compliance, asset lifecycle optimization, and technology migration planning. ECHA SF6 disposal liability assessments are driving demand.
Largest revenue share: Maintenance. Gaining share fastest: Consultancy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for distribution components concentrates in Germany and China, while consumption gravity shifts toward India and the United States where grid modernization and electrification programs absorb imported equipment and domestic manufacturing alike.
Germany
Renewable interconnection queues for solar and wind projects are accelerating medium-voltage switchgear procurement across Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation is forcing utilities to replace SF6-insulated equipment with vacuum interrupter alternatives. Siemens anchors digital twin development from its Munich headquarters, while ABB scales modular substation production for European export markets.
United States
FERC interconnection reform and state-level decarbonization mandates are driving transformer and circuit breaker replacement cycles. The EPA is tightening emissions standards for electrical equipment manufacturing. Texas and California utilities are unbundling equipment purchases from long-term service agreements, fragmenting traditional vendor relationships in the ERCOT and CAISO markets.
India
Rural electrification directives from the CEA are bundling distribution panel and transformer tenders across Maharashtra and Gujarat. The PLI scheme for electrical equipment is attracting component manufacturing investment to Tamil Nadu and Karnataka. State utilities in Telangana and Andhra Pradesh are prioritizing rapid-deployment switchgear configurations for urban infrastructure buildouts.
China
Dual carbon goals and provincial grid expansion targets are sustaining demand for high-voltage transformers and switchgear across the Yangtze River Delta. MIIT efficiency standards are reshaping product certification requirements for domestic manufacturers. Shanghai and Jiangsu province industrial clusters are scaling silicon carbide semiconductor production for next-generation protection devices.
Japan
Grid resilience investments following recent natural disasters are driving replacement demand for earthquake-resistant switchgear in the Kanto region. METI carbon neutrality roadmaps are accelerating SF6 phase-out timelines for Tokyo Electric Power and other regional utilities. Osaka-based manufacturers are exporting vacuum interrupter technology to Southeast Asian markets.
Distribution Components Market Competitive Environment
The competitive structure tilts toward integrated energy management specialists with digital service portfolios. Three tiers have crystallized: multinational conglomerates with full-stack capabilities, regional specialists in modular architectures, and component-focused manufacturers competing on qualification speed. M&A activity targets predictive maintenance platforms, while capacity expansion concentrates on vacuum interrupter production lines.
Among European-headquartered conglomerates, Schneider Electric exemplifies the integrated portfolio archetype spanning switchgear through software layers. ABB occupies a position within the modular infrastructure tier, with its emphasis on containerized substation designs. Siemens anchors the digital twin convergence vector, representing predictive maintenance platform integration. These three structures illustrate how vendor relationships are fragmenting as utilities unbundle equipment from service contracts.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Eaton |
| Siemens |
| Mitsubishi Electric |
| Legrand |
| Larsen & Toubro |
| General Electric |
| Hitachi Energy |
| Others |
Value Chain & Pricing Dynamics
India's CEA-mandated rural electrification procurement is forcing suppliers to compress delivery timelines and absorb field logistics costs, shifting pricing power toward state utilities with bundled tender leverage.
Pricing Analysis
Outcome-based pricing tied to substation uptime guarantees anchors premium tiers for European transmission operators. Three-tier pricing structure across premium, standard, and economy levels separates digital twin-enabled service bundles from basic equipment sales. Cost compression in transformer manufacturing is intensifying because copper and electrical steel volatility has eliminated long-term contract security. Manufacturing end-users exhibit the least price sensitivity due to process-critical reliability requirements, while construction sector buyers drive aggressive bidding for integrated turnkey packages.
Supply Chain Analysis
IEC 61850 certification bottlenecks at testing laboratories are gating supplier qualification and extending approval timelines for new market entrants. Manufacturing concentrates in Germany, China, and India, with vacuum interrupter production scaling fastest in Japan and Germany. Component sourcing draws from electrical steel mills in China, copper refineries in Chile, and silicon carbide foundries in the Yangtze River Delta. Single-source vulnerability around SF6 gas disposal infrastructure creates stranded asset exposure for utilities with legacy switchgear fleets. Distribution runs through direct utility contracts for large projects and specialized electrical distributors for retrofit and maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
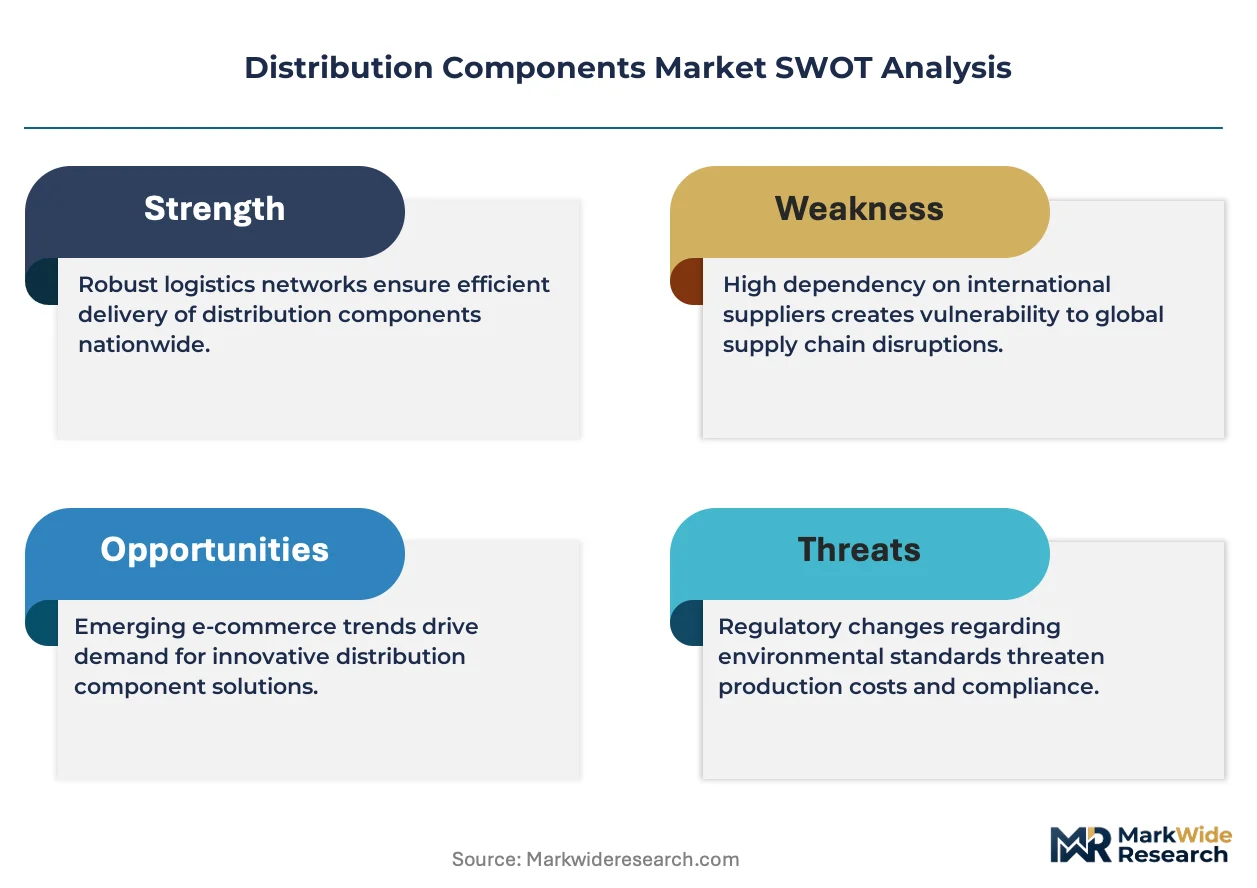
The EU F-Gas Regulation has erected a cost-of-compliance moat that rewards early movers in vacuum interrupter and clean air insulation technologies while stranding capital for SF6-dependent legacy players.
For Market Incumbents: Hedge against stranded asset risk by accelerating vacuum interrupter capacity expansion in Germany and India before ECHA disposal liabilities crystallize. Secure backward integration into electrical steel and copper processing to defend margin position against raw material volatility. Digital twin platform consolidation represents the priority defensive lever against unbundling of equipment and service contracts. For New Entrants and Emerging Players: Containerized modular substation buyers in Spanish and German renewable interconnection queues represent the most penetrable white-space segment for qualified challengers. State utilities in Telangana and Andhra Pradesh offer procurement entry points through PLI-linked domestic manufacturing requirements. A certification-fast-track go-to-market angle targeting IEC 61850 testing bottlenecks can compress time-to-revenue versus established competitors. For Investors and Strategic Acquirers: The window for entry favors predictive maintenance platform specialists with utility fleet integration capabilities over pure equipment manufacturers. Long-term viability centers on recurring revenue models that decouple from cyclical capital expenditure cycles. Watch for inflection when European transmission operators complete their SF6 replacement cycle and shift procurement toward lifecycle service bundling.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Interrupter Capacity Expansion | Captures EU F-Gas regulatory replacement demand across German and Spanish utilities. |
| Digital Twin Platform Integration | Enables predictive maintenance contracts that rival equipment sales for Siemens and ABB. |
| Modular Substation Certification | Reduces civil works costs for renewable interconnection projects in Bavaria. |
| Backward Integration into Electrical Steel | Insulates transformer margins from commodity volatility in China and India. |
| IEC 61850 Protocol Specialization | Concentrates scarce technical talent for utility retrofit projects in North America. |
Study Parameters
Multi-period observation of utility procurement patterns, raw material price indices, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with grid planning officers, substation engineers at European transmission operators, EPC contractors specializing in renewable interconnection, and procurement directors at Indian state utilities. Secondary validation drew from IEC standard revision drafts, ECHA restriction proposals, CEA directive publications, and customs trade data for electrical steel and copper. Bottom-up segment sizing triangulated against top-down utility capital expenditure disclosures.
Input-output matrices mapped component demand across voltage classes, installation modes, and service types throughout the forecast period. Segmentation dimensions included voltage rating tiers, end-user procurement authority, factory versus field assembly methods, and recurring versus transactional revenue structures. CAGRs were derived from regression analysis of historical utility investment cycles and regulatory mandate implementation schedules. Forecast inputs incorporated renewable interconnection queue backlogs in Germany and Spain, plus PLI scheme uptake rates in Tamil Nadu and Karnataka.
Revisions become necessary when ECHA accelerates SF6 phase-out timelines, India modifies PLI domestic content requirements, or testing laboratory capacity constraints ease and compress certification bottlenecks. A model refresh is warranted upon material change in copper and electrical steel futures curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Microspeaker Market
Electronic Components
Trackpad Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Digital Potentiometer Market
Electronic Components
China Data Converter Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
Chip Shield Market
Electronic Components
Timing Relay Market