
 Gigabit Interface Converter Market | 2026-2036
Gigabit Interface Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Gigabit Interface Converter Market Foresight
RoHS and REACH substance restrictions are hardening material compliance costs for Gigabit Interface Converter vendors entering European supply chains. Cisco leverages backward integration into custom photonic chip designs to protect margin pools in enterprise networking segments. Advantech Co., Ltd. anchors its position through industrial-grade temperature specifications that differentiate against standard commercial offerings. Moxa specializes in ruggedized form factors for railway and factory automation environments where shock resistance defines procurement criteria.
A Gigabit Interface Converter is a hot-swappable transceiver module that interfaces network hardware with fiber-optic or copper cabling, typically supporting data rates from 1 Gbps to 10 Gbps through electrical-to-optical signal conversion. These devices enable modular port configuration in switches and routers without requiring full equipment replacement when upgrading link speeds. Single-Mode variants command premium positioning for metro and long-haul telecom networks where dispersion tolerance justifies higher unit economics. QSFP technology leads volume shipments in hyperscale data centers, while SFP+ maintains entrenched positions in enterprise refresh cycles where backward compatibility constrains format migration.
FCC Part 15 emissions rules in the United States and CE marking requirements under the EU Radio Equipment Directive shape electromagnetic compatibility testing burdens that filter out uncertified module suppliers. China's GB standards and MIIT type-approval processes add incremental homologation steps for vendors targeting state-owned carrier procurement. BIS certification in India and Japan's TELEC conformity requirements extend this regulatory patchwork across Asia-Pacific deployment corridors. Stakeholders must monitor IEEE P802.3dj and subsequent standards drafts that will redefine electrical interface specifications and potentially obsolete current module generations before physical layer investments fully depreciate.
Market Dynamics
Hyperscale data center operators are consolidating optical port procurement around QSFP-DD and OSFP form factors, compressing demand for legacy SFP modules and rewiring supplier qualification pipelines.
Growth Catalysts
- AI Training Cluster Buildouts:Cloud operators in Northern Virginia and Dallas-Fort Worth are installing high-density fiber-optic switching to support GPU interconnects at 400 Gbps and above.
- RoHS Substance Bans:ECHA restrictions on lead and cadmium in electronics are forcing module vendors to redesign PCB assemblies, creating first-mover advantages for compliant suppliers.
- Copper-to-Fiber Migration:Enterprise campus networks are replacing Cat6A cabling with single-mode fiber to enable 10 Gbps desktop connectivity without distance limitations.
Market Restraints
- Indium Phosphide Supply Concentration:Laser chip fabrication depends on a handful of foundries in Japan and the United States, exposing module assemblers to wafer allocation shocks.
- Electromagnetic Compatibility Testing Burden:FCC Part 15 and CE marking under the EU Radio Equipment Directive impose six-month certification timelines that lock out unfinanced entrants.
- Active Optical Cable Substitution:Pre-terminated AOC assemblies are capturing rack-level interconnect demand that previously flowed to discrete transceiver modules.
Strategic Opportunities
- Industrial Temperature Hardening:Railway and utility automation sectors in Germany and Japan require -40°C to +85°C operating ranges that standard commercial modules fail to meet.
- Co-Packaged Optics Convergence:Integration of silicon photonics with switch ASICs is creating demand for optical engines that bypass traditional pluggable form factors entirely.
- India PLI Incentives:Production-linked schemes for telecom equipment are attracting module assembly investments targeting state-owned carrier procurement under BIS certification.
Industry Challenges
- Optical Packaging Skill Scarcity:Precision alignment of laser diodes to fiber ferrules requires technicians trained on active die-bonding equipment that few vocational programs cover.
- Legacy Equipment Integration Friction:Enterprises running Cisco Catalyst 6500 chassis face firmware lock-in that prevents QSFP migration without full switch replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gigabit Interface Converter Market |
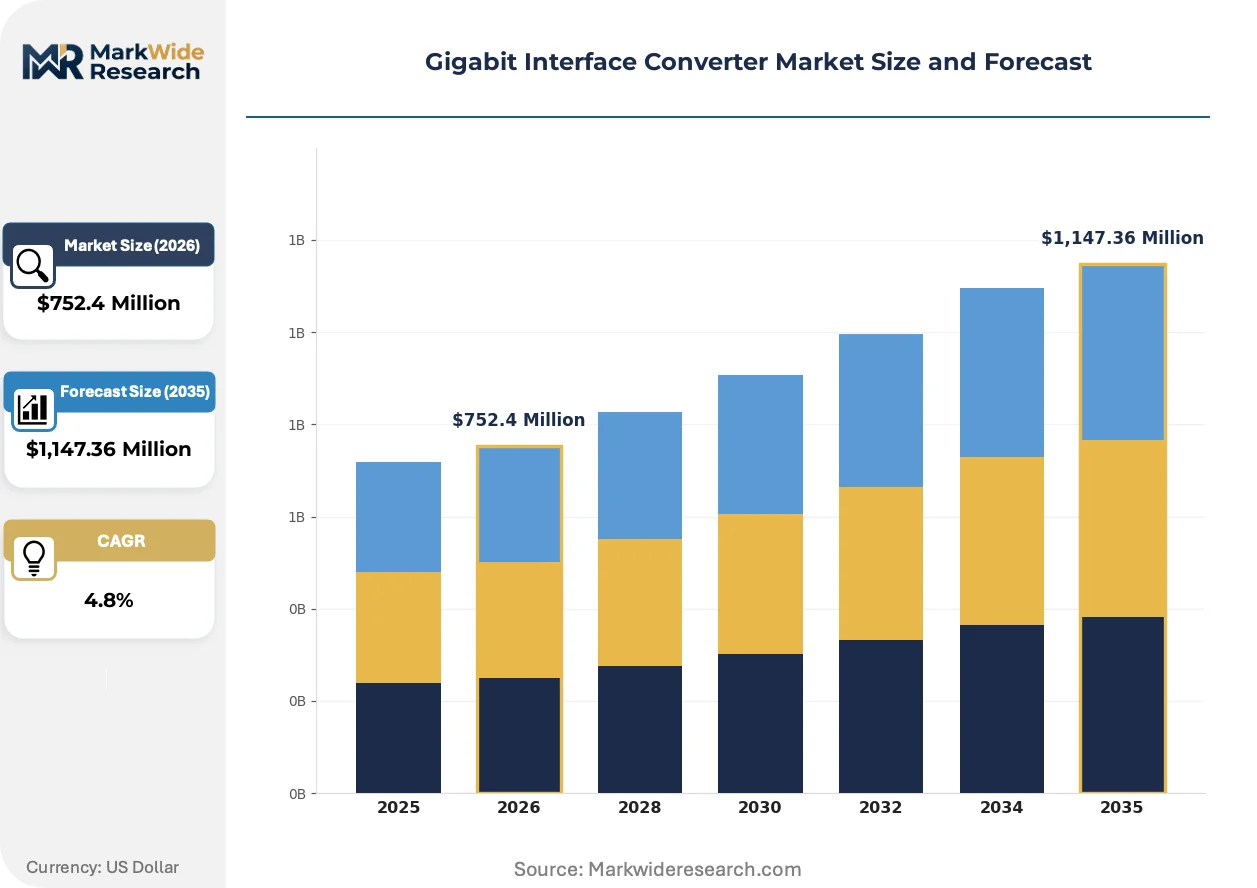
| Market Size in 2026 | $752.4 Million |
| Market Size in 2035 | $1,147.36 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, Copper, Active Optical Cable Technology: Small Form-Factor Pluggable, XFP, SFP+, QSFP Application: Data Centers, Telecom Networks, Enterprise Networking, Broadcast Systems End User: Network Equipment Manufacturers, Internet Service Providers, Cloud Service Operators, Hyperscale Data Centers |
| Companies Covered | Cisco, Moxa, Advantech Co., Ltd., Allied Telesis, PLANET Technology, TP-Link, Phoenix Contact, Belden, Transition Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gigabit Interface Converter Market Shifts & Advancements
Silicon photonics is collapsing the cost structure of optical transceivers while IEEE standards activity is redefining electrical interfaces ahead of current product depreciation cycles.
Linear-drive pluggable optics is overtaking traditional DSP-based architectures in hyperscale data centers. These devices eliminate digital signal processors to cut power consumption by half. Meta and Google are qualifying LPO modules for 800 Gbps links in their AI training fabrics. The technology is compressing the addressable market for high-margin retimer chips from Broadcom and Marvell.
REACH substance restrictions are tightening purity requirements for optical subcomponents sold into European supply chains. ECHA added four phthalates to the candidate list in 2023, forcing suppliers to requalify plastic housings and cable jackets. Module vendors serving Deutsche Telekom and Orange are absorbing six-figure reformulation costs that Asian competitors avoid by focusing on domestic Chinese carriers.
Direct procurement from contract manufacturers is displacing distribution channels for volume buyers. Amazon Web Services and Microsoft are qualifying Foxconn and Jabil lines to build custom-coded transceivers bypassing Finisar and Lumentum branding. This pattern is most visible in the United States, where hyperscale technical specifications now travel straight to ODM engineering teams without traditional value-added distributor involvement.
Gigabit Interface Converter Market Segmentation
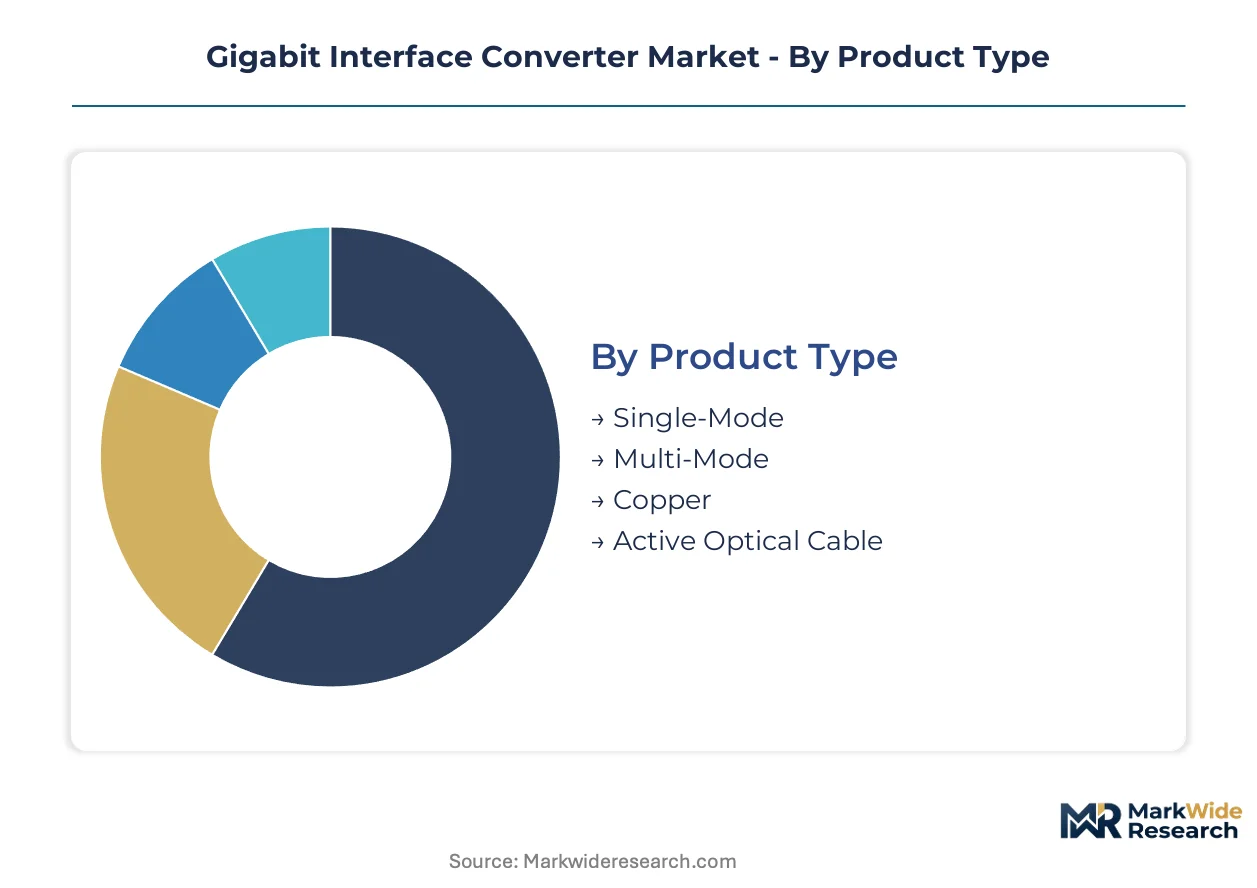
Segmentation in the Gigabit Interface Converter market reveals how physical layer specifications, deployment environments, and procurement authority patterns fragment demand across incompatible technical requirements and compliance regimes.
Product Type:
Optical physics and transmission distance requirements partition the market across fiber types and copper alternatives, with cost-per-meter economics driving format selection.
- Single-Mode:Laser-optimized for 1310nm and 1550nm wavelengths with dispersion-shifted fiber cores. Metro and long-haul telecom networks in Germany and Japan specify this format for 80km+ spans where chromatic dispersion tolerance justifies premium unit economics.
- Multi-Mode:Vertical-cavity surface-emitting laser technology supporting 850nm transmission over graded-index fiber. Data center operators in Northern Virginia deploy this format for intra-campus links under 500 meters where fiber cost minimization outweighs distance performance.
- Copper:Direct attach copper assemblies using passive or active equalization for sub-10 meter reaches within server racks.
- Active Optical Cable:Pre-terminated fiber assemblies with embedded transceiver engines eliminating separate module procurement.
Mature deployment sits with Multi-Mode in hyperscale data centers. Newer deployment is concentrated in Active Optical Cable for rack-level interconnect consolidation.
Technology:
Form factor evolution tracks port density demands and backward compatibility constraints across switching hardware generations.
- QSFP:Quad-channel packaging delivering 40 Gbps to 400 Gbps through parallel fiber lanes. Cloud operators in Dallas-Fort Worth specify QSFP-DD variants for AI training clusters requiring 800 Gbps aggregate bandwidth per switch port.
- SFP+:Enhanced small form-factor supporting 10 Gbps electrical interfaces with legacy SFP mechanical compatibility. Enterprise refresh cycles in the United States favor this format for Cisco Catalyst chassis where firmware lock-in prevents migration to denser packaging.
- Small Form-Factor Pluggable:Original 1 Gbps specification maintaining presence in industrial automation and utility networks.
- XFP:10 Gbps form factor with larger thermal envelope for telecom line cards requiring extended temperature operation.
Volume concentration sits with QSFP in hyperscale procurement. Sustained demand persists in SFP+ for enterprise backward compatibility requirements.
Application:
End-use environment dictates electromagnetic compatibility thresholds, temperature specifications, and mean-time-between-failure requirements.
- Data Centers:Controlled-environment deployments prioritizing power efficiency and port density over extended temperature ranges. Operators in Northern Virginia and Dallas-Fort Worth drive qualification of linear-drive pluggable optics for 800 Gbps AI fabric interconnects.
- Telecom Networks:Outdoor cabinet and central office installations requiring -40°C to +85°C operation and 20-year service life predictions. Deutsche Telekom and Orange specify hardened modules for metro aggregation nodes under EU Radio Equipment Directive compliance.
- Enterprise Networking:Campus and branch office deployments with mixed copper-fiber infrastructure and 5-year depreciation cycles.
- Broadcast Systems:Professional video transport applications requiring synchronous timing and low jitter for uncompressed SDI over IP conversion.
Procurement scale concentrates in Data Centers. Technical complexity peaks in Telecom Networks with dual homologation requirements.
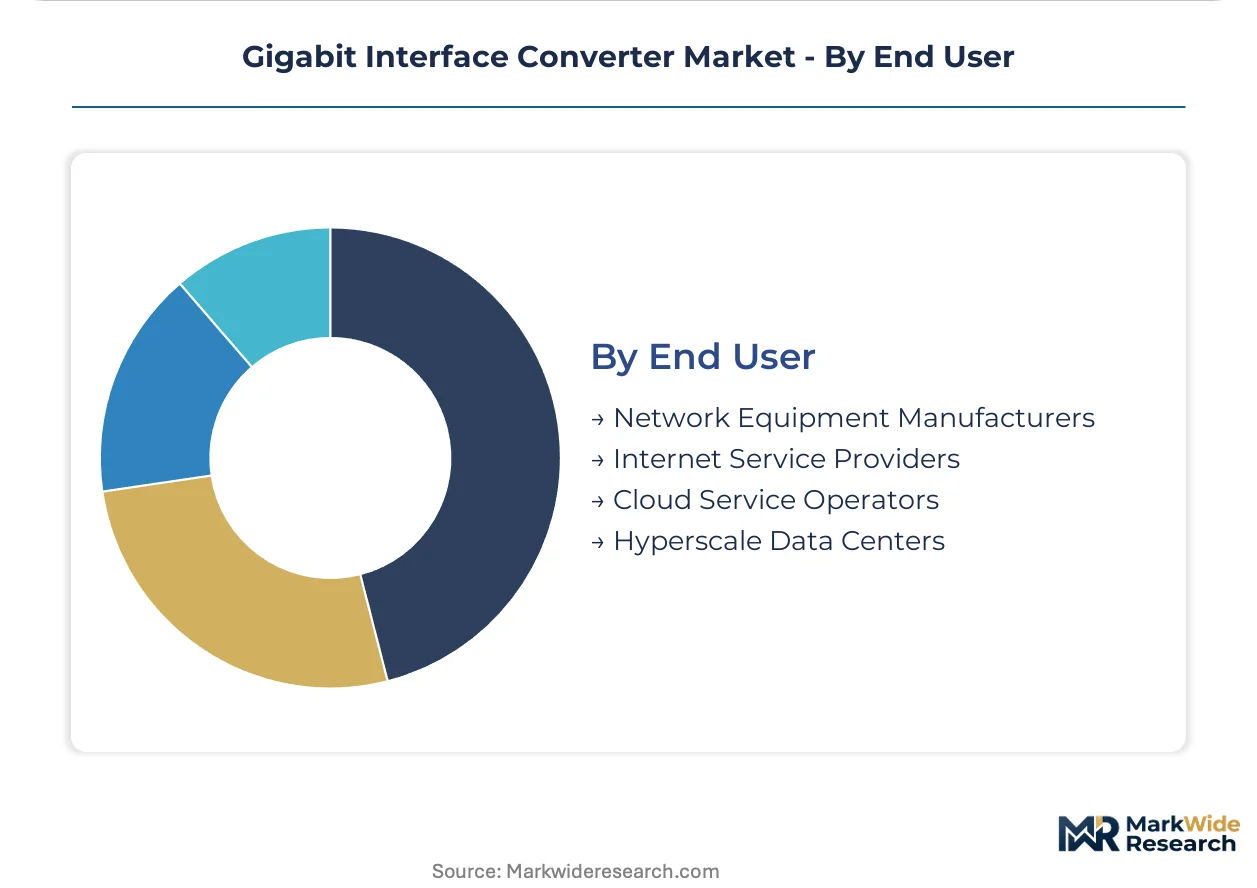
End User:
Buying authority patterns separate direct procurement from channel-mediated distribution, with volume thresholds determining supplier qualification pathways.
- Hyperscale Data Centers:Direct engagement with Foxconn and Jabil for custom-coded transceivers bypassing branded module vendors. Amazon Web Services and Microsoft qualify ODM lines under proprietary technical specifications that travel straight to contract manufacturing engineering teams.
- Cloud Service Operators:Mid-tier providers balancing customization needs against minimum order quantity constraints from Finisar and Lumentum.
- Internet Service Providers:National and regional carriers procuring through distribution channels with BIS certification requirements for Indian state-owned carrier contracts.
- Network Equipment Manufacturers:Switch and router OEMs integrating modules into system-level FCC Part 15 and CE marking submissions.
Channel bypass is most advanced among Hyperscale Data Centers. Distribution dependence persists for Internet Service Providers below volume thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in the United States concentrate procurement volumes for SFP+ and QSFP modules, while industrial automation demand in Germany and Japan drives specialized temperature-hardened specifications.
United States
Cloud campuses in Northern Virginia and Dallas-Fort Worth drive bulk procurement of 400 Gbps and 800 Gbps optical interconnects for AI training clusters. FCC Part 15 emissions rules impose six-month certification timelines that filter uncertified module suppliers. Microsoft and Amazon Web Services qualify contract manufacturers directly, bypassing traditional distribution channels for custom-coded transceivers.
Germany
Railway and factory automation sectors demand -40°C to +85°C operating ranges that standard commercial modules fail to meet. ECHA REACH restrictions on phthalates force suppliers to requalify plastic housings for Deutsche Telekom and Orange procurement. Industrial clusters in Bavaria and Baden-Württemberg anchor precision manufacturing of optical packaging equipment.
Japan
Metro and long-haul telecom networks specify single-mode formats for 80km+ spans where chromatic dispersion tolerance justifies premium unit economics. METI industrial standards and TELEC conformity requirements extend homologation steps for state-owned carrier procurement. Laser chip fabrication concentrates in foundries serving domestic module assemblers.
China
MIIT type-approval processes and GB standards add incremental steps for vendors targeting state-owned carrier procurement. Domestic cloud operators are consolidating optical port procurement around QSFP-DD form factors. Yangtze River Delta manufacturing clusters supply precision active die-bonding equipment for laser diode alignment.
India
Production-linked incentive schemes for telecom equipment attract module assembly investments targeting BSNL and MTNL procurement. BIS certification requirements filter suppliers for state-owned carrier contracts. Tamil Nadu and Karnataka industrial corridors host emerging contract manufacturing lines for European and North American buyers.
Gigabit Interface Converter Market Competitive Landscape
United States producers anchor one tier; Taiwanese and Chinese specialists hold volume manufacturing positions. The vendor base separates into three tiers: vertically integrated networking equipment vendors, pure-play optical module specialists, and contract manufacturing lines serving hyperscale direct procurement. Strategic archetypes include backward-integrated chip designers, industrial-grade temperature hardeners, and ruggedized form factor specialists. Competitive moves concentrate on custom photonic chip development and direct ODM qualification bypassing branded distribution.
Among the named players, Cisco represents backward integration into custom photonic designs that protect margin pools in enterprise networking. Advantech Co., Ltd. anchors the industrial-grade temperature specification tier through hardened operating range differentiation. Moxa occupies a position within ruggedized form factors for railway and factory automation environments where shock resistance defines procurement criteria.
| Leading Market Players |
|---|
| Cisco |
| Moxa |
| Advantech Co., Ltd. |
| Allied Telesis |
| PLANET Technology |
| TP-Link |
| Phoenix Contact |
| Belden |
| Transition Networks |
| Others |
Supply & Pricing Matrix
Indium phosphide wafer pricing cascades through module assembly tiers, compressing margins for QSFP-DD producers serving hyperscale cloud operators in Northern Virginia while elevating premiums for single-mode variants bound for Deutsche Telekom metro networks. This raw-material cost structure stratifies pricing across industrial-grade, telecom-hardened, and standard commercial specifications.
Pricing Analysis
High-volume hyperscale procurement compresses per-unit margins to commodity levels, while low-volume industrial-temperature modules retain pricing power through certification differentiation. Three-tier pricing structure across telecom-hardened, enterprise-standard, and high-volume cloud tiers reflects FCC Part 15 and CE marking compliance costs. Price erosion runs through QSFP-DD lines as Amazon Web Services and Microsoft qualify Foxconn directly. Cloud operators exhibit extreme price sensitivity; railway operators in Germany accept premiums for -40°C operation.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Dallas-Fort Worth, and Amsterdam coordinate hub-and-spoke fulfillment patterns for module vendors serving divergent compliance regimes. Laser chip fabrication draws from concentrated foundry capacity in Japan and the United States, exposing assemblers to wafer allocation shocks. Indium phosphide substrates, precision ferrule assemblies, and DSP retimer chips anchor bill-of-materials dependencies. Tariff exposure on Chinese-manufactured PCBs shapes supplier qualification decisions. Distribution runs through contract manufacturing lines for hyperscale buyers, traditional distribution for sub-scale carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indium phosphide foundry constraints prop module pricing through the analysis window, creating supply-constrained conditions that favor incumbents with secured wafer allocations and certified product portfolios.
For Market Incumbents: Extend backward integration into custom photonic chip designs to protect margin pools in enterprise networking segments where Cisco has established precedent. Secure dedicated foundry capacity through long-term offtake agreements with Japanese laser chip suppliers. Counter active optical cable substitution by qualifying direct attach copper alternatives for sub-10 meter rack interconnects.
For New Entrants and Emerging Players: Begin with industrial temperature hardening for railway and utility automation sectors in Germany and Japan where Advantech and Moxa have validated procurement criteria. Target BIS certification pathways for Indian state-owned carrier contracts under PLI incentive schemes. Pursue ODM qualification relationships with mid-tier cloud operators lacking direct Foxconn and Jabil access.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision optical packaging specialists in Japan and Germany with active die-bonding technician benches and TELEC conformity track records. Long-term viability hinges on silicon photonics convergence positioning ahead of co-packaged optics displacement. Watch IEEE P802.3dj standardization progress as inflection indicator for electrical interface obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom Photonic Chip Development | Cisco's backward integration protects enterprise margin pools against commodity QSFP compression. |
| Industrial Temperature Certification | Advantech's -40°C to +85°C specifications capture Deutsche Telekom railway procurement. |
| Direct ODM Qualification | Amazon Web Services bypasses Finisar branding through Foxconn custom-coded transceiver lines. |
| Silicon Photonics Migration | Linear-drive pluggable optics halves power consumption for Meta's 800 Gbps AI fabric links. |
| REACH Compliance Reformulation | ECHA phthalate restrictions force six-figure requalification costs for European supply chain entry. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across optical module engineering directors, hyperscale data center procurement officers, telecom carrier technical specification leads, and precision packaging equipment vendors. FCC Part 15 certification databases, IEEE standards committee documentation, ECHA REACH candidate list updates, and MIIT type-approval registries supplied compliance tracking dimensions. Bottom-up bill-of-materials costing and top-down hyperscale capex aggregation triangulated volume estimates.
Granularity-level modeling distinguished QSFP-DD, QSFP, SFP+, and legacy form factors across single-mode, multi-mode, copper, and active optical cable physics. Data center, telecom network, enterprise networking, and broadcast system applications carried distinct temperature specification and electromagnetic compatibility assumptions. CAGRs derived from shipment volume trajectories mapped to cloud operator buildout schedules in Northern Virginia and Dallas-Fort Worth. Indium phosphide foundry capacity forecasts and IEEE P802.3dj standardization timelines informed substitution risk parameters.
Underlying measurement precision varies by segment; hyperscale data center procurement carries tighter precision than industrial automation due to concentrated buyer visibility. Forecasts reflect assumptions on AI training cluster buildout persistence, foundry capacity expansion, and standards migration timelines. Periodic stress-testing of base assumptions is recommended against silicon photonics substitution velocity and co-packaged optics convergence patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Circuit Protection Kits Market
Electronic Components
Electronic Wipe Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Motherboard Battery Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Power Inductors Market
Electronic Components
Film Capacitor Market
Electronic Components
Power Resistor Market
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Screw Washer Market