
 Americas MPU Market | 2026-2036
Americas MPU Market Size, Share, and Industry Trends Forecast 2026-2036
Americas MPU Market Insights
Capital-intensity divergence between foundry-dependent and captive-fabrication players is bifurcating competitive dynamics across the Americas MPU landscape. Intel Corporation leverages its Arizona and New Mexico wafer fabs to sustain domestic vertical integration. Advanced Micro Devices anchors its design leadership through fabless partnerships with TSMC while competing aggressively in data-center MPU sockets.
A microprocessor unit executes digital instructions via integrated arithmetic logic and control circuitry, typically fabricated on silicon wafers using sub-7nm or mature-node processes to balance performance against thermal design power. The Americas MPU ecosystem spans embedded units for real-time control, general-purpose processors for compute workloads, digital signal processors for algorithmic acceleration, and microcontrollers for dedicated tasks. Automotive Systems application demand leads absolute volume as electric powertrains and advanced driver-assistance systems multiply sensor-fusion requirements. ARM Architecture technology dominates mobile and embedded segments through licensable energy-efficient cores, while x86 Architecture retains enterprise and cloud compute margins.
The U.S. CHIPS and Science Act directs Department of Commerce funding toward domestic MPU fabrication, tightening supply-chain security standards for federal procurement. Mexico's Secretariat of Economy coordinates maquiladora incentives with U.S. EPA environmental compliance for cross-border semiconductor assembly. Brazil's ANATEL certification requirements shape telecommunications MPU import protocols. Stakeholders must monitor how U.S. export controls on advanced lithography equipment reshape foundry access for RISC-V development in the hemisphere.
Market Dynamics
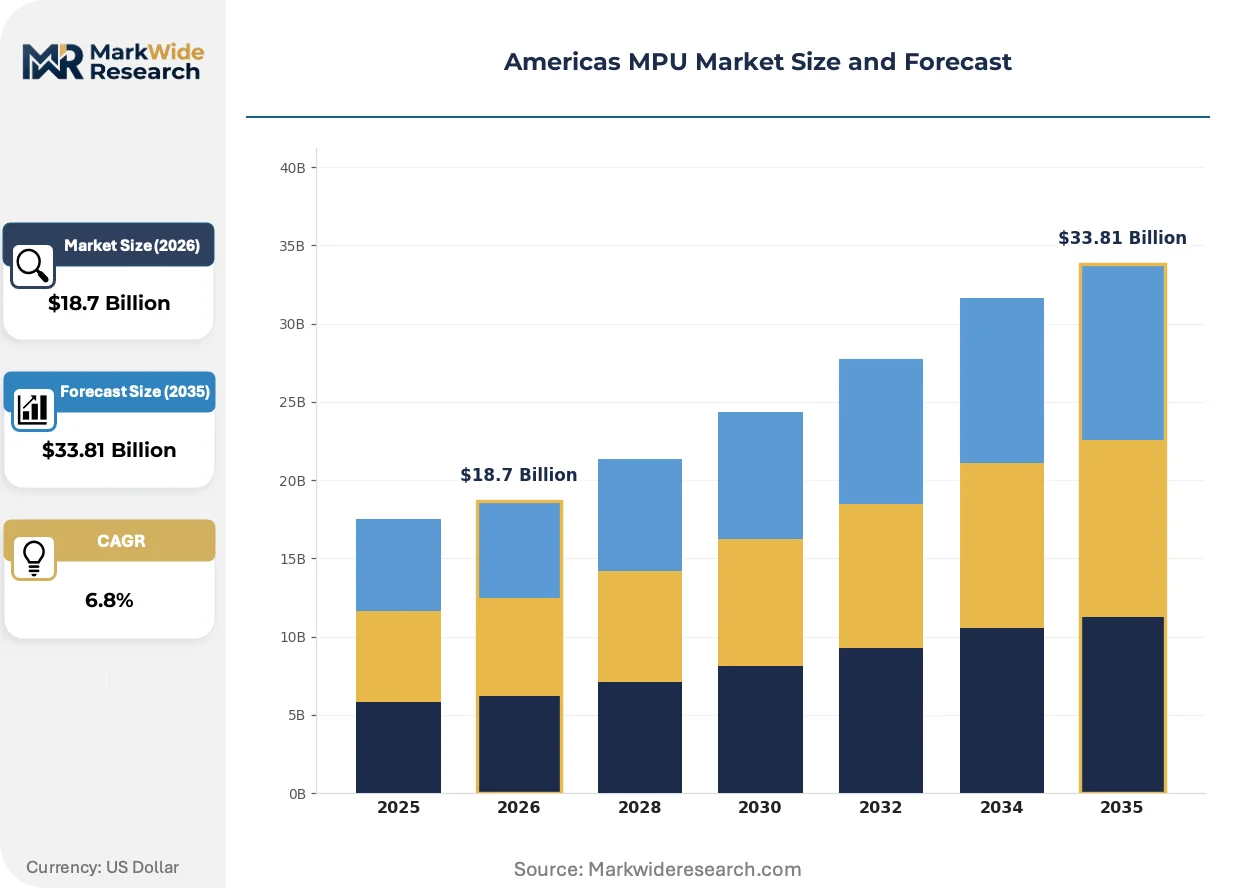
Automotive electrification is compressing MPU design cycles as Tier-1 suppliers demand real-time sensor-fusion capabilities for advanced driver-assistance systems. The U.S. CHIPS and Science Act is redirecting capital toward domestic wafer fabrication, altering foundry access patterns across the hemisphere.
Growth Catalysts
- U.S. CHIPS and Science Act incentives:Department of Commerce funding accelerates domestic MPU fabrication capacity expansion in Arizona and New Mexico, tightening supply-chain security standards for federal procurement.
- Electric vehicle powertrain integration:Battery management systems and motor control units multiply embedded MPU content per vehicle, concentrating demand in Detroit and northern Mexico maquiladora corridors.
- Sub-7nm process maturation:Advanced lithography yields improve cost-efficiency for high-performance computing workloads, enabling broader data-center adoption across São Paulo and Toronto financial hubs.
Market Restraints
- Advanced lithography equipment concentration:Dutch and Japanese toolmakers control extreme ultraviolet scanner supply, creating chokepoints for domestic U.S. foundry scaling.
- Neon gas supply fragility:Ukrainian and Russian neon purification infrastructure disruptions threaten laser lithography input stability for mature-node MPU production.
- RISC-V architecture fragmentation:Inconsistent instruction-set extensions across open-source implementations complicate software ecosystem development for embedded automotive applications.
Strategic Opportunities
- Nearshoring acceleration in Chihuahua and Baja California:Mexico's Secretariat of Economy maquiladora incentives attract cross-border semiconductor assembly and test operations from Asian suppliers.
- Edge AI inference at manufacturing nodes:Convergence of ARM-based MPUs with tensor processing units enables predictive maintenance without cloud dependency in Brazilian automotive plants.
- Brazil ANATEL certification streamlining:Simplified telecommunications MPU import protocols reduce time-to-market for IoT gateway deployments in Latin American smart city infrastructure.
Industry Challenges
- Compound semiconductor integration complexity:Silicon carbide and gallium nitride power electronics require heterogeneous packaging expertise scarce in traditional MPU design houses.
- Export control compliance engineering:U.S. Bureau of Industry and Security advanced compute restrictions demand end-use verification systems that extend sales cycle timelines for RISC-V developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas MPU Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded MPU, General-Purpose MPU, Digital Signal Processor, Microcontroller Application: Consumer Electronics, Automotive Systems, Industrial Automation, Smart Appliances End User: Aerospace, Healthcare, Telecommunications, Home Automation Technology: ARM Architecture, x86 Architecture, RISC-V, MIPS |
| Companies Covered | Intel Corporation, Advanced Micro Devices, Qualcomm Technologies, NVIDIA Corporation, Micron Technology, Samsung Electronics, Broadcom, Apple, Texas Instruments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas MPU Market Trends and Innovations
Chiplets are fragmenting monolithic MPU architectures into disaggregated functional blocks, enabling mix-and-match performance configurations. This architectural shift is redrawing competitive boundaries between integrated device manufacturers and fabless designers.
3D stacking technology using through-silicon vias is miniaturizing memory-processor interfaces, collapsing latency between DRAM and compute cores. Cloud hyperscalers in Ashburn and Querétaro are adopting these configurations for AI training clusters. The technology is miniaturizing form factors while amplifying thermal design power constraints that dictate cooling infrastructure investments.
The U.S. EPA cross-border environmental compliance framework is tightening water-usage standards for semiconductor fabrication in maquiladora zones. Mexico's northern border states must upgrade wastewater treatment to maintain EPA certification for U.S.-bound MPU assembly. Automotive suppliers in Nuevo León are retrofitting facilities to meet these discharge limits ahead of 2027 permit renewals.
Direct foundry contracting is displacing traditional distributor channels for high-volume MPU procurement. Tier-1 automotive suppliers in Michigan and Ontario now negotiate wafer-start agreements directly with TSMC and GlobalFoundries. This pattern concentrates purchasing power among consolidated OEMs while squeezing margin for regional distributors serving mid-volume industrial customers.
Americas MPU Market Segmentation
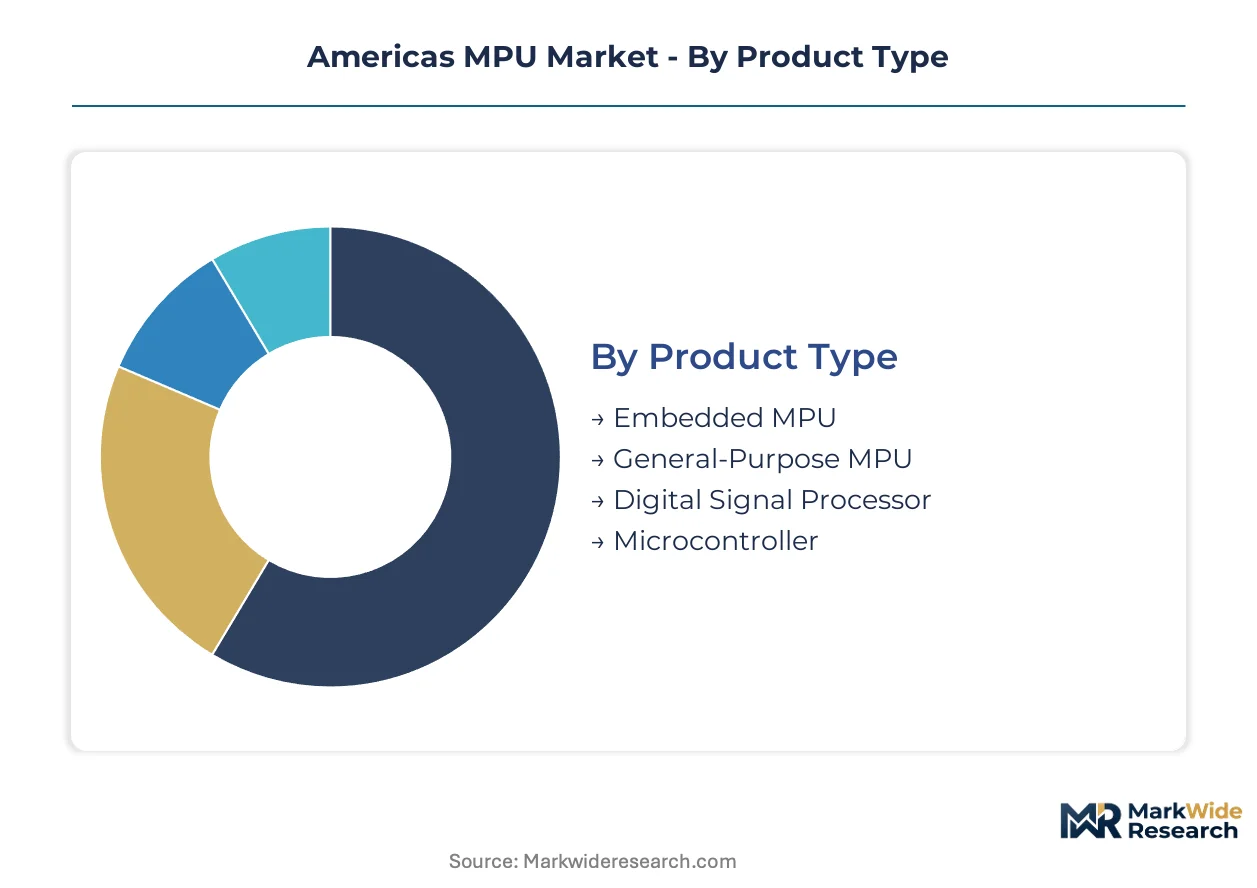
Americas MPU procurement channels diverge sharply by segment complexity. High-volume automotive and industrial buyers negotiate direct foundry contracts, while fragmented consumer and home automation segments flow through authorized distributors with inventory risk transfer.
Product Type:
Channel mix splits between long-term wafer agreements for high-complexity units and spot-market purchasing for commoditized variants.
- General-Purpose MPU:Multi-core silicon executing diverse compute workloads across operating systems. Data-center demand concentrates in Ashburn and Querétaro hyperscaler clusters, where cloud providers negotiate multi-year wafer-start commitments with TSMC and GlobalFoundries. By volume, General-Purpose MPU leads. By growth pace, Embedded MPU is ahead.
- Embedded MPU:Dedicated instruction-set processors integrated into single-function systems with deterministic response requirements. Real-time control demand concentrates in Detroit automotive corridors and northern Mexico maquiladora zones, driven by electric powertrain sensor-fusion requirements.
- Digital Signal Processor:Optimized arithmetic units for algorithmic acceleration in audio and RF processing.
- Microcontroller:Compact integrated systems combining processor core with memory and peripherals on single die.
Cost tiering separates premium sub-7nm general-purpose units from mature-node embedded variants with 40-60% fabrication cost differentials.
Application:
Volume concentration and margin profile vary dramatically across end-use contexts.
- Automotive Systems:Safety-critical MPUs meeting AEC-Q100 thermal and reliability standards. Electric vehicle powertrain integration multiplies unit content per vehicle, with Tier-1 suppliers in Michigan and Ontario demanding automotive-grade process nodes from foundries.
- Industrial Automation:Ruggedized MPUs operating across extended temperature ranges with deterministic latency guarantees. Demand concentrates in São Paulo manufacturing hubs and Toronto financial infrastructure, driven by predictive maintenance and edge AI inference requirements.
- Consumer Electronics:Cost-optimized MPUs for smartphones, tablets, and wearables with aggressive thermal constraints.
- Smart Appliances:Connectivity-enabled MPUs for HVAC, refrigeration, and lighting control with Wi-Fi and Bluetooth integration.
Margin structure inverts between segments: Automotive commands premium pricing for reliability certification, while Consumer Electronics competes on die-size efficiency.
End User:
Procurement sophistication escalates with regulatory burden and failure-cost exposure.
- Telecommunications:MPUs meeting ANATEL certification and FCC Part 15 emissions standards for network infrastructure. Brazil's simplified import protocols accelerate IoT gateway deployments, while 5G base station demand concentrates in Mexican and Colombian carrier rollouts.
- Aerospace:Radiation-hardened and fault-tolerant MPUs for avionics and satellite systems with DO-178C software assurance.
- Healthcare:FDA-regulated MPUs for diagnostic imaging and patient monitoring with IEC 62304 software lifecycle compliance.
- Home Automation:Cost-sensitive MPUs for smart speakers, security systems, and energy management with Matter protocol support.
Supply concentration follows regulatory intensity: Aerospace and Healthcare consolidate procurement through qualified supplier lists, while Home Automation fragments across distributor channels.
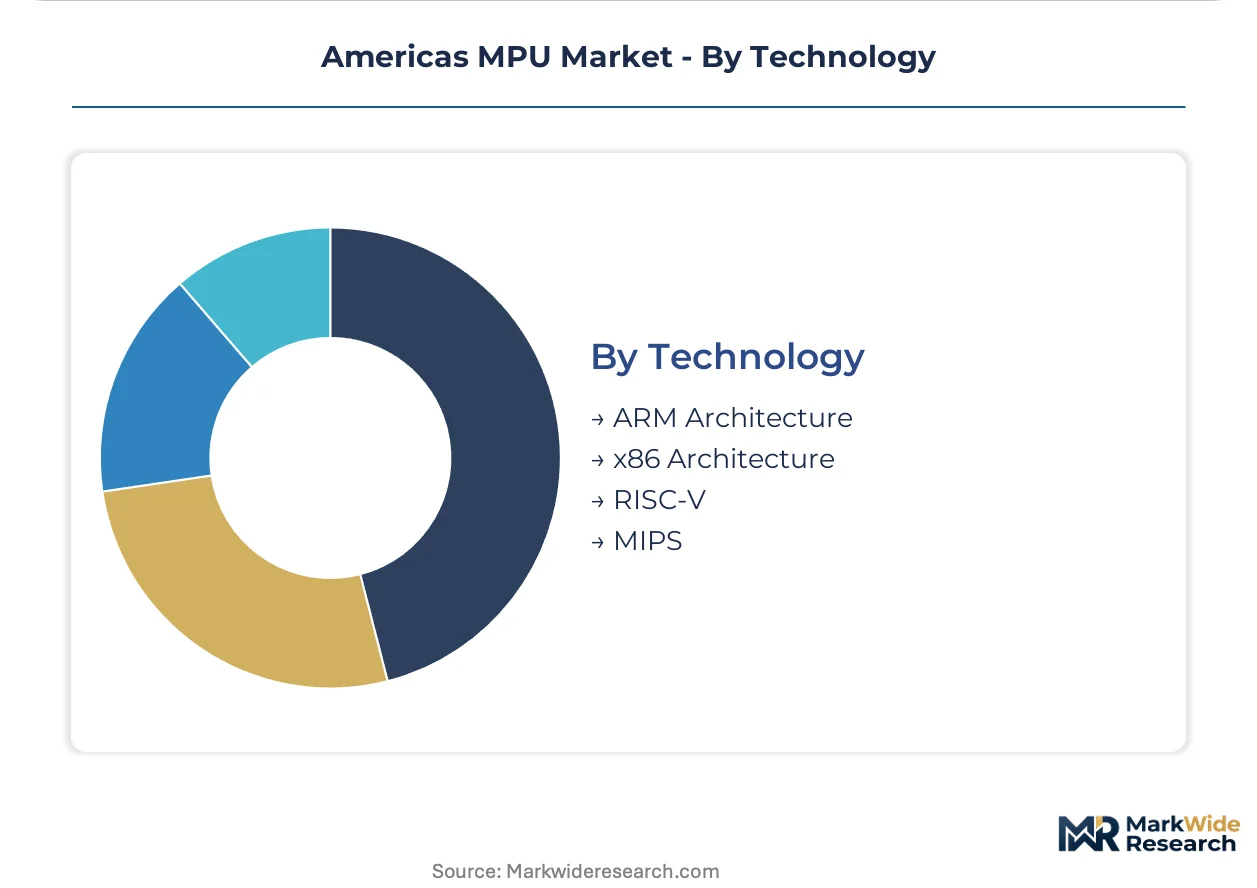
Technology:
Architecture choice determines software ecosystem depth and licensing cost structure.
- ARM Architecture:Licensable energy-efficient cores dominating mobile and embedded segments with Thumb-2 instruction set density. Mobile device demand concentrates through Qualcomm and MediaTek fabless partnerships, while automotive adoption accelerates for infotainment and ADAS subsystems.
- x86 Architecture:Complex instruction-set computing with deep legacy software compatibility. Enterprise and cloud compute demand sustains premium margins, with Intel's Arizona and New Mexico fabs anchoring domestic vertical integration.
- RISC-V:Open-source instruction set with modular extension framework attracting embedded automotive development.
- MIPS:Reduced instruction-set architecture with historical networking and set-top box presence.
By installed base, x86 Architecture leads. By expansion trajectory, ARM Architecture is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Americas MPU consumption mix diverges sharply by latitude: the United States prioritizes high-performance general-purpose processors for hyperscaler data centers, while Latin American demand concentrates in cost-optimized embedded units for industrial automation and telecommunications infrastructure.
United States
Data-center expansion in Ashburn, Virginia and Querétaro-adjacent U.S. border zones drives sub-7nm general-purpose MPU procurement. The CHIPS and Science Act directs Department of Commerce funding toward Arizona and New Mexico wafer fabrication facilities. Intel Corporation anchors domestic vertical integration through captive production in these southwestern states.
Mexico
Electric vehicle powertrain integration and advanced driver-assistance systems multiply embedded MPU content per vehicle across automotive supplier networks. The Secretariat of Economy coordinates maquiladora incentives with U.S. EPA cross-border environmental compliance standards. Northern border states—Chihuahua, Baja California, and Nuevo León—attract semiconductor assembly and test operations from Asian suppliers accelerating nearshoring.
Canada
Financial infrastructure modernization in Toronto and predictive maintenance deployment in Ontario manufacturing hubs sustain industrial automation MPU demand. Health Canada certification requirements shape telecommunications and healthcare MPU import protocols. Southwestern Ontario automotive corridors concentrate procurement from Tier-1 suppliers sourcing automotive-grade process nodes.
Brazil
Smart city infrastructure rollout and IoT gateway deployment drive telecommunications MPU consumption across São Paulo manufacturing zones. ANATEL certification requirements historically complicated import timelines, though streamlined protocols now accelerate time-to-market. Edge AI inference adoption in automotive plants converges ARM-based MPUs with tensor processing units for predictive maintenance without cloud dependency.
Argentina
Industrial automation retrofits in Buenos Aires manufacturing districts sustain mature-node embedded MPU demand despite macroeconomic volatility. The national telecommunications regulator shapes import protocols for network infrastructure MPUs. Córdoba's automotive supplier base sources cost-optimized units for powertrain control systems serving Mercosur export markets.
Americas MPU Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive fabrication capacity separating the former from fabless competitors dependent on foundry partnerships. The market structure concentrates around three strategic archetypes: integrated device manufacturers with domestic wafer fabs, fabless designers leveraging Taiwan-based foundry access, and diversified technology conglomerates with captive silicon strategies. Competitive moves center on direct foundry contracting displacement of distributor channels and heterogeneous packaging investments for compound semiconductor integration.
Within the integrated device manufacturer tier, Intel Corporation exemplifies vertical control through southwestern U.S. fabrication assets, while Advanced Micro Devices occupies a position representing fabless design leadership dependent on external foundry partnerships. Among diversified technology conglomerates, Samsung Electronics anchors the competitive landscape as a Korean-based integrated player with Americas market presence spanning memory and logic MPU segments.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices |
| Qualcomm Technologies |
| NVIDIA Corporation |
| Micron Technology |
| Samsung Electronics |
| Broadcom |
| Apple |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
Fab utilization rates above ninety percent at leading foundries in Taiwan and South Korea compress margin flexibility across the Americas MPU ecosystem, binding price floors to wafer-start commitments while concentrating supply power among integrated device manufacturers with captive Arizona and New Mexico capacity.
Pricing Analysis
After-sales revenue from multi-year field service and extended reliability warranties drives lifetime value for automotive-grade MPU suppliers. Three-tier pricing structure across automotive-certified, industrial-rugged, and consumer-optimized levels separates AEC-Q100 validated units from standard-temperature variants. Pricing pressure stems from direct foundry contracting displacement of distributor channels among Tier-1 automotive buyers in Michigan and Ontario. Consumer Electronics segments exhibit highest price sensitivity due to die-size efficiency competition, while Aerospace and Healthcare procurement consolidates through qualified supplier lists with premium tolerance.
Supply Chain Analysis
Port congestion at Long Beach and container availability constraints on trans-Pacific lanes elevate inbound logistics costs for Asian-sourced lithography equipment and wafer substrates. Advanced MPU production draws from Taiwan, South Korea, and the United States for leading-edge fabrication, with neon gas purification and extreme ultraviolet scanner components resting on Dutch and Japanese toolmaker concentration. Single-source vulnerability in extreme ultraviolet scanner supply creates structural risk for domestic U.S. foundry scaling. Distribution runs through direct wafer-start agreements for high-volume automotive and data-center buyers, while fragmented industrial and consumer segments channel through authorized distributors with inventory risk transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas MPU market sits at a platform-economics inflection where ARM-based ecosystem interoperability in automotive infotainment and RISC-V fragmentation in embedded control create divergent competitive moats.
For Market Incumbents: Fortify captive fabrication advantage through CHIPS Act-funded capacity additions in Arizona and New Mexico, while deepening AEC-Q100 certification portfolios to defend against fabless competitors dependent on Taiwan foundry access. Channel control through direct Tier-1 automotive contracting represents the critical lever for margin protection. For New Entrants and Emerging Players: Differentiate on heterogeneous packaging expertise for silicon carbide power electronics integration, targeting underpenetrated Brazilian automotive plants and Argentine industrial automation retrofits with edge-AI inference solutions. RISC-V implementation for deterministic automotive control systems offers the most penetrable white-space entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MPU suppliers with multi-year automotive platform wins and federal procurement qualification. Long-term viability favors integrated device manufacturers with domestic wafer fabs over pure-play fabless designers exposed to foundry allocation volatility. Watch for Bureau of Industry and Security export control expansion as inflection signal for RISC-V ecosystem acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Wafer Fab Expansion | CHIPS Act funding in Arizona and New Mexico tightens federal supply-chain security standards. |
| Heterogeneous Packaging Investment | Silicon carbide integration capability addresses electric powertrain sensor-fusion requirements. |
| Direct Foundry Contracting | Tier-1 automotive suppliers in Michigan negotiate wafer-start agreements displacing distributor channels. |
| Edge AI Inference Convergence | ARM-based MPU and tensor processing unit integration enables predictive maintenance without cloud dependency. |
| RISC-V Ecosystem Development | Open-source architecture attracts embedded automotive investment amid x86 and ARM licensing constraints. |
Research Methodology
A spread of perspectives from foundry operations executives, Tier-1 automotive procurement directors, semiconductor equipment specialists, and federal program managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, Department of Commerce CHIPS Act award disclosures, TSMC and GlobalFoundries capacity announcements, and customs trade data. Bottom-up wafer-start modeling and top-down end-use demand triangulation anchored volume estimates.
Segmentation dimensions modeled span product type, application vertical, end-user regulatory burden, and technology architecture choice across the projection horizon. CAGRs derived from foundry capacity expansion timelines, electric vehicle production ramp curves, and data-center hyperscaler capex disclosures. Automotive powertrain electrification content-per-vehicle trajectories and sub-7nm process yield maturation curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained CHIPS Act funding execution, stable neon gas supply from Ukrainian and Russian purification infrastructure, or unaltered Bureau of Industry and Security export control frameworks would require recalibration. Forecasts reflect documented assumptions regarding foundry allocation patterns and automotive platform design cycle compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio Power Amplifier Market
Electronic Components
Distribution Components Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Global Capacitor Market
Electronic Components
Amplifier Market
Electronic Components
SAW Filters Market
Electronic Components
RAID Controller Card Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Europe PCB Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Hydrogen Thyratron Market